
 Pre-Assembled Packaging Market | 2026-2036
Pre-Assembled Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Assembled Packaging Market Analytics
Market Context
Capital-intensity divergence between integrated converters and asset-light assemblers is redrawing competitive boundaries in pre-assembled packaging. Amcor leverages captive resin-to-film operations to control input costs across flexible formats. Smurfit Westrock anchors its position through vertical integration into containerboard mills and corrugating plants spanning multiple continents. Sealed Air Corporation differentiates via automated packaging systems that bundle film, equipment, and technical service into single-source contracts.
Technical Definition and Segment Structure
Pre-assembled packaging denotes finished or semi-finished containment structures delivered in ready-to-deploy configurations, typically formed from substrates meeting specified burst strength, dimensional tolerance, and stack-load criteria, eliminating downstream setup labor for end-user filling lines. Plastic trays and clamshells dominate food service and retail-ready display applications where dimensional repeatability governs conveyor compatibility and shelf presentation. Paperboard boxes sustain the fastest expansion in e-commerce subscription and direct-to-consumer channels where printability and crush resistance determine unboxing experience. Rigid packaging formats command margin concentration in healthcare and cosmetics segments requiring tamper-evidence and child-resistance certifications that flexible alternatives cannot replicate.
Regulatory Framework and Outlook
EPA guidelines on recycled content thresholds, EU REACH restrictions on certain plastic additives, and FDA food-contact substance notifications collectively reshape material selection and supplier qualification protocols for pre-assembled packaging sold into regulated end uses. California's extended producer responsibility legislation and the EU Packaging and Packaging Waste Regulation impose fee structures tied to recyclability assessments, redirecting R&D spending toward mono-material designs and fiber-based barrier coatings. Stakeholders must monitor evolving state-level packaging fee schedules and harmonized recyclability testing protocols to avoid stranded inventory in jurisdictions with divergent compliance deadlines.
Market Dynamics
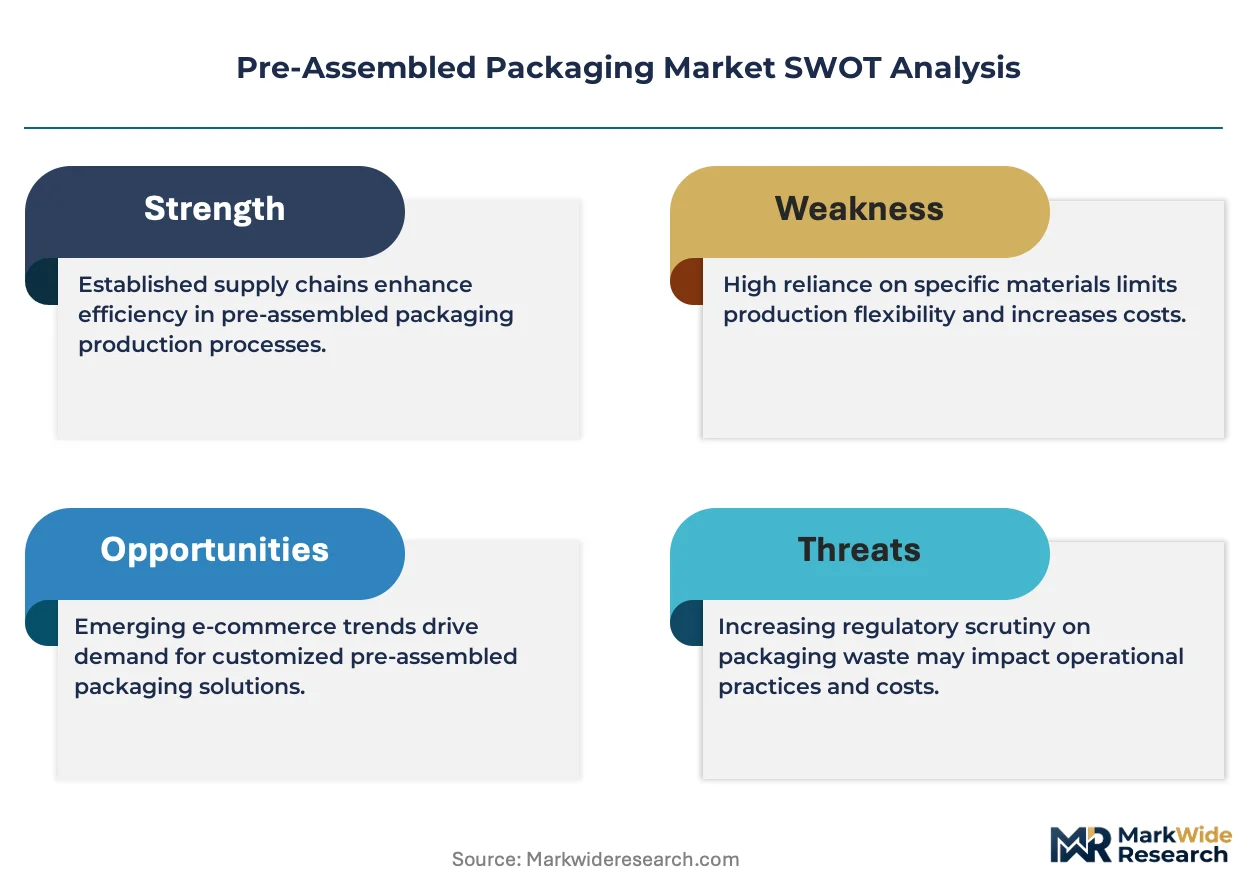
The EU Packaging and Packaging Waste Regulation is compressing design cycles for pre-assembled packaging converters, forcing rapid migration toward mono-material substrates and fiber-based barrier coatings to avoid fee penalties tied to recyclability scores.
Growth Catalysts
- Automotive Returnable Systems:German component suppliers are standardizing tray pooling programs for just-in-sequence delivery, eliminating single-use corrugated from assembly line logistics.
- REACH Restrictions on Additives:ECHA's tightening limits on certain plasticizers and flame retardants are redirecting R&D budgets toward bio-based barrier coatings that maintain food-contact compliance.
- Automated Fulfillment Infrastructure:E-commerce sortation centers in the Netherlands and Belgium are specifying dimensionally precise ready-to-use boxes that eliminate manual erecting stations.
Market Restraints
- Containerboard Input Volatility:OCC price swings in European spot markets are compressing margins for independent corrugators lacking captive pulp supply.
- Recyclability Testing Fragmentation:Divergent national protocols across EU member states are creating compliance overhead before harmonized CEP standards take effect.
- Flexible Pouch Substitution:Stand-up pouches with spouts are capturing shelf-stable food volume previously held by rigid pre-formed trays.
Strategic Opportunities
- Poland and Czech Republic Manufacturing:Greenfield corrugating capacity near German automotive clusters offers labor cost arbitrage for returnable packaging production.
- Pharmaceutical Cold Chain:Pre-qualified insulated shippers combining vacuum panels with phase-change materials address temperature excursion risks in biologics distribution.
- Extended Producer Responsibility Incentives:France's modulated eco-modulation fees reward packaging designs scoring above 70 percent on recyclability indices.
Industry Challenges
- Barrier Coating Talent Scarcity:Formulation chemists with expertise in water-based oxygen barriers command premium compensation, constraining converter R&D throughput.
- Legacy ERP Integration:Automated packaging lines from multiple OEMs require middleware development to synchronize with existing warehouse management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Assembled Packaging Market |
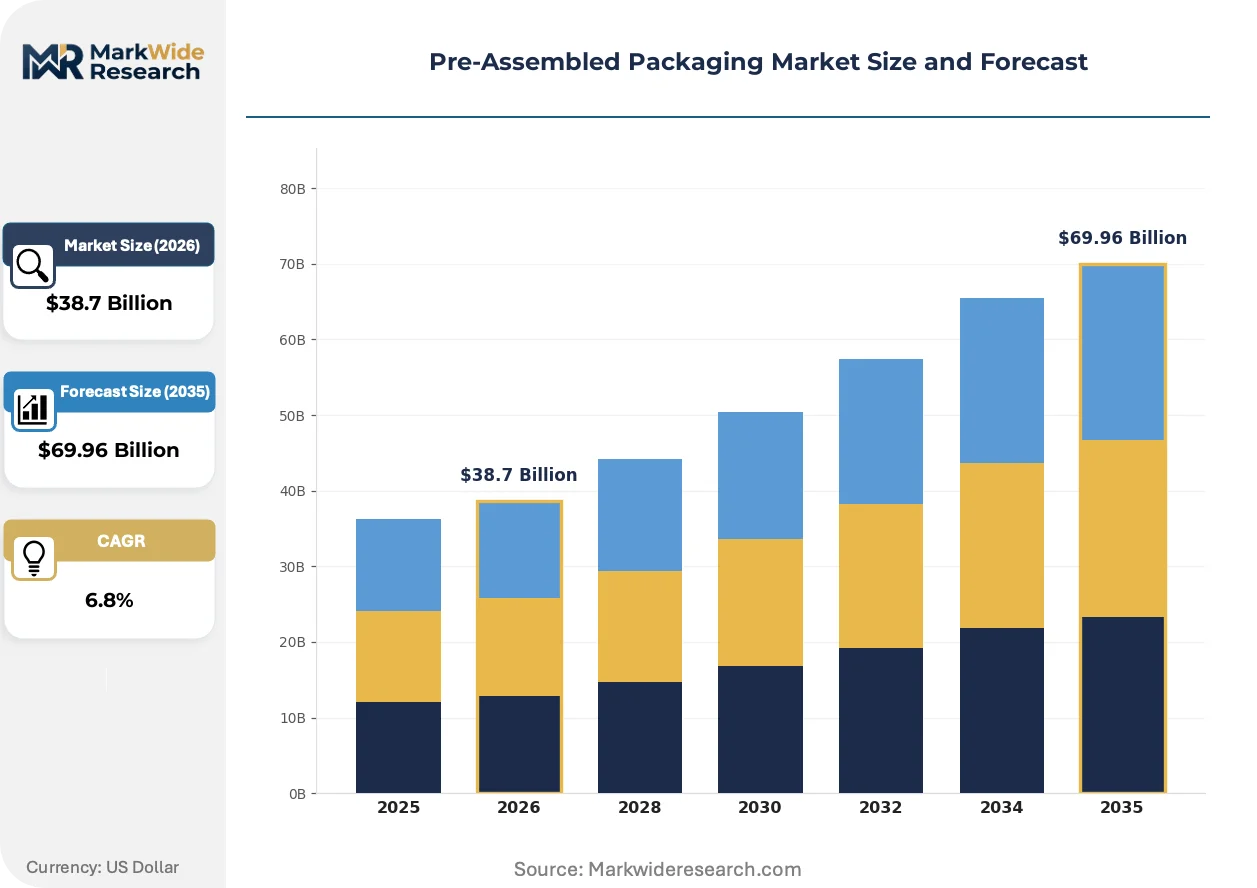
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Boxes, Clamshells, Containers Material: Plastic, Paperboard, Glass, Metal End User: Food & Beverage, Healthcare, Cosmetics, Electronics Packaging Type: Sustainable, Rigid, Flexible, Barrier |
| Companies Covered | Amcor, Ball Corporation, Smurfit Westrock, Sealed Air Corporation, Sonoco Products Company, Smurfit Kappa Group, Crown Holdings, International Paper, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Assembled Packaging Market Evolving Landscape
Pre-assembled packaging is undergoing substrate rationalization as converters consolidate material portfolios to simplify recovery streams and reduce qualification burden for multinational brand owners.
Water-based barrier coatings are decomposing the traditional multi-layer plastic laminate structure in food trays. Retail-ready protein and produce packers in Spain and Italy are piloting these mono-material formats at scale. The shift is compressing equipment amortization timelines for thermal lamination assets while opening qualification pathways with French and German retailers demanding recyclability transparency.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from molded fiber foodservice containers. Converters are reformulating with bio-wax and clay alternatives that meet FDA and EFSA migration limits. Quick-service restaurant chains in Scandinavia are absorbing modest cost premiums to secure compliant supply ahead of 2025 enforcement deadlines.
Subscription box merchants are consolidating supplier relationships toward single-source corrugated partners offering inline digital print and automated pack-out. Direct-to-consumer beauty brands in the UK are specifying unboxing-optimized formats with tear-strip reveals and interior print. The behavior concentrates procurement authority with converters possessing both structural design and graphic execution capabilities.
Pre-Assembled Packaging Market Segmentation
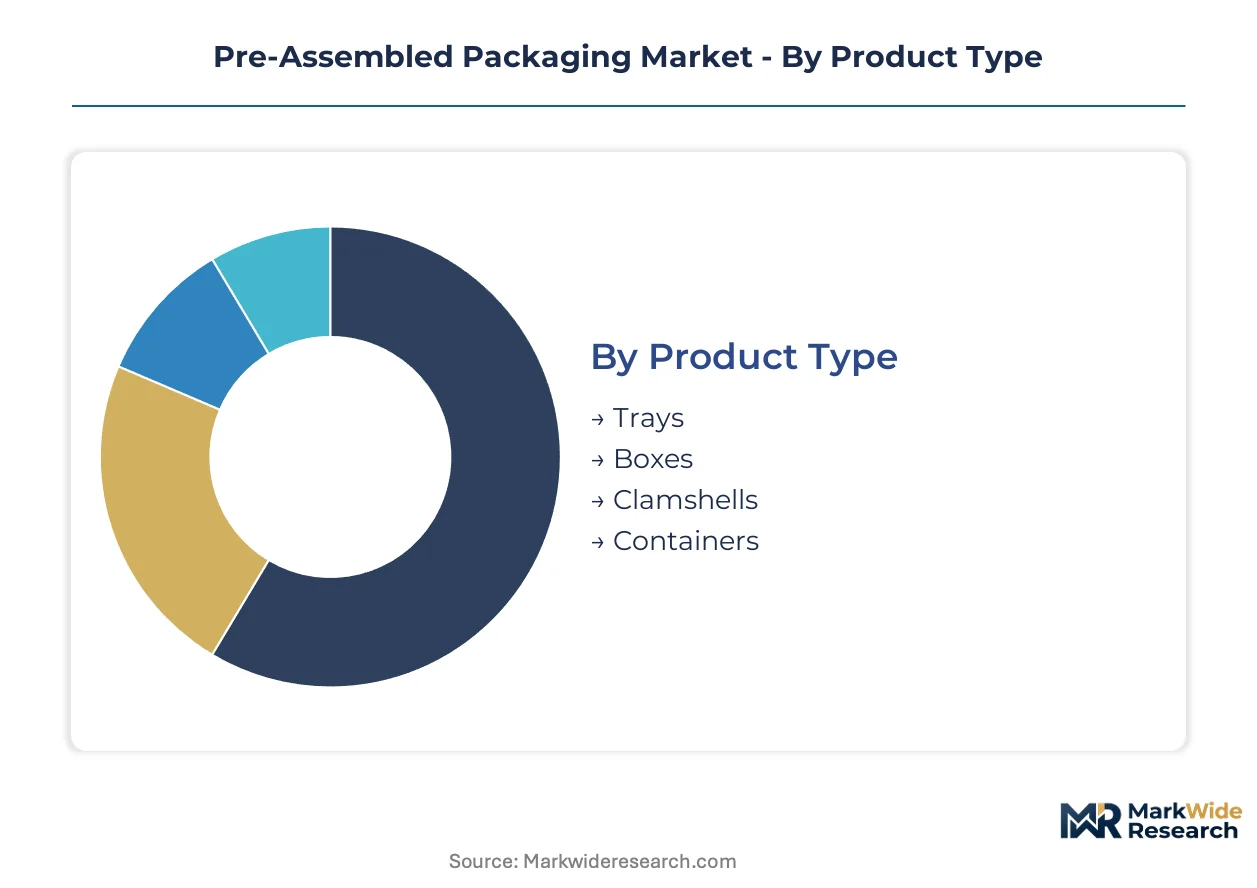
Pre-assembled packaging segmentation reflects divergent compliance burdens across substrates and end-uses. FDA food-contact notifications, EU REACH restrictions, and state-level extended producer responsibility laws each reshape procurement priorities for converters and brand owners.
Product Type:
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances and EFSA migration limits create divergent qualification timelines across structural formats.
- Trays:Standardized returnable tray systems dominate German automotive component logistics, eliminating single-use corrugated from just-in-sequence assembly lines. Pooling programs with RFID tracking reduce per-trip costs below disposable alternatives.
- Boxes:Ready-to-use corrugated formats accelerate through Netherlands and Belgium e-commerce fulfillment centers where automated sortation demands dimensional repeatability. Inline digital print capability separates winning suppliers.
- Clamshells:Retail-ready display applications favor PET and rPET clarity for produce visibility.
- Containers:Healthcare and cosmetics segments specify tamper-evident and child-resistant certifications.
Boxes handle the majority of throughput; trays are gaining share fastest through automotive standardization.
Material:
Cost tier stratification separates captive pulp integrators from resin-dependent independents.
- Plastic:ECHA's tightening limits on plasticizers and flame retardants redirect R&D toward bio-based barrier coatings. Trays and clamshells maintain food-contact compliance through mono-material rationalization.
- Paperboard:OCC price volatility in European spot markets compresses margins for non-integrated corrugators. France's modulated eco-modulation fees reward designs scoring above 70 percent on recyclability indices.
- Glass:Premium cosmetics and pharmaceutical applications demand chemical inertness.
- Metal:Aerosol and specialty food containers retain niche volume against flexible substitution.
Paperboard carries the largest volume base; plastic formats are expanding most quickly through barrier coating innovation.
End User:
Application-specific certification requirements fragment supplier qualification protocols.
- Food & Beverage:Quick-service restaurant chains in Scandinavia absorb cost premiums for PFAS-free molded fiber ahead of enforcement deadlines. Water-based barrier coatings decompose traditional multi-layer laminate structures.
- Healthcare:Pre-qualified insulated shippers combining vacuum panels with phase-change materials address temperature excursion risks in biologics distribution. FDA validation requirements extend procurement cycles.
- Cosmetics:UK direct-to-consumer beauty brands specify unboxing-optimized formats with tear-strip reveals.
- Electronics:Anti-static and moisture-barrier specifications govern semiconductor component protection.
Food & Beverage commands the widest format diversity; Healthcare posts the steepest expansion trajectory through cold chain investment.
Packaging Type:
Customer procurement patterns concentrate with converters offering integrated structural design and graphic execution.
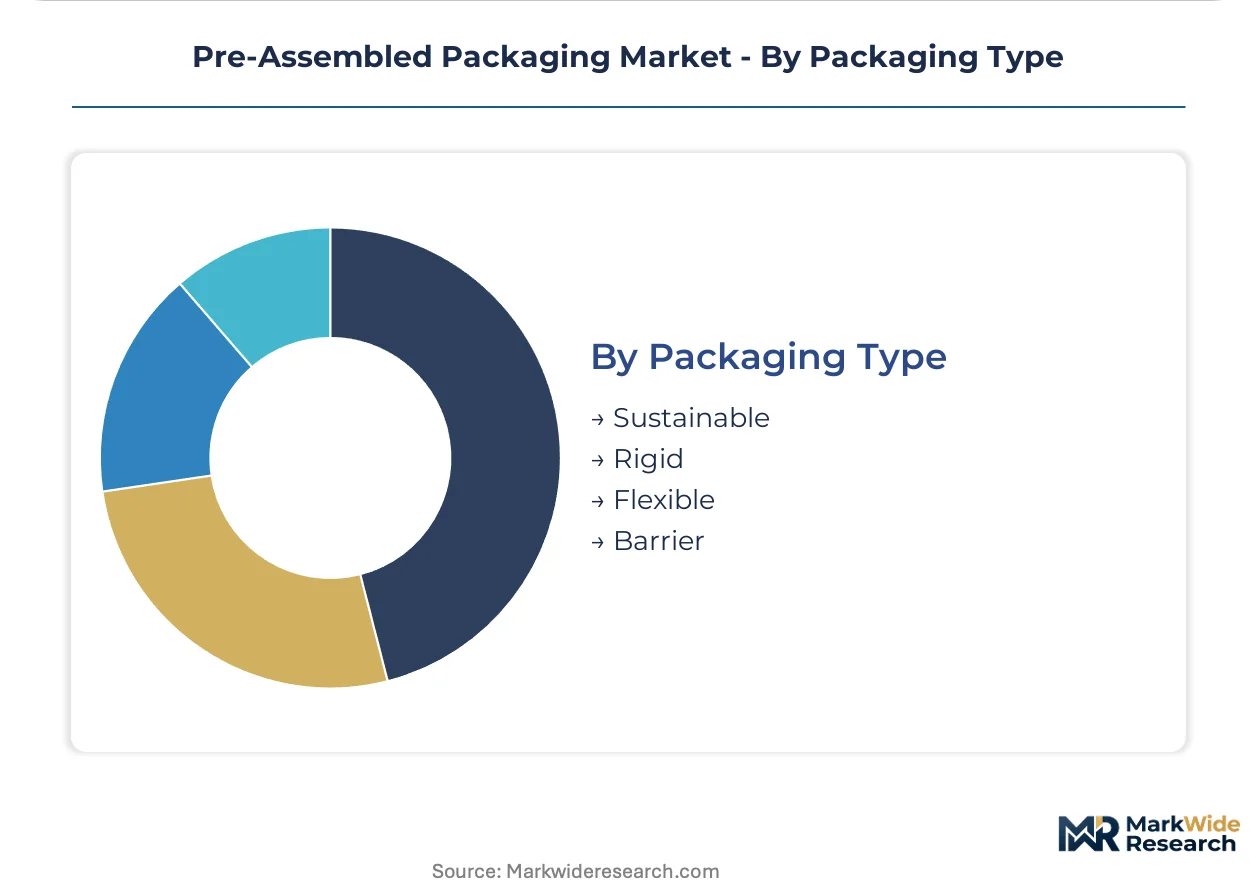
- Sustainable:California's extended producer responsibility legislation and EU Packaging and Packaging Waste Regulation impose fee structures tied to recyclability assessments. Mono-material designs qualify for reduced fees.
- Rigid:Tamper-evidence and child-resistance certifications that flexible alternatives cannot replicate protect margin concentration in pharmaceutical and cosmetics segments.
- Flexible:Stand-up pouches with spouts capture shelf-stable food volume previously held by rigid pre-formed trays.
- Barrier:Formulation chemists with water-based oxygen barrier expertise command premium compensation, constraining converter R&D throughput.
Rigid formats anchor premium pricing; Sustainable packaging climbs fastest on regulatory fee pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive component suppliers command pricing premiums for standardized returnable tray systems, while Polish independent corrugators absorb OCC volatility through leaner cost structures. This asymmetry redistributes margin capture across the European pre-assembled packaging value chain.
Germany
Automotive pooling programs with RFID-tracked trays dominate just-in-sequence logistics for component suppliers near Stuttgart and Wolfsburg. EU REACH restrictions on plastic additives accelerate converter migration toward bio-based barrier coatings. The Baden-Württemberg cluster hosts specialized formulators developing PFAS-free molded fiber alternatives for quick-service restaurant supply.
United States
Subscription box merchants concentrate procurement with corrugated partners offering inline digital print and automated pack-out capabilities. California's extended producer responsibility legislation imposes fee structures tied to recyclability assessments, redirecting R&D toward mono-material designs. The Pacific Northwest corridor attracts cold-chain specialists developing pre-qualified insulated shippers for biologics distribution.
Netherlands
E-commerce sortation centers specify dimensionally precise ready-to-use boxes that eliminate manual erecting stations. Divergent national recyclability testing protocols create compliance overhead before harmonized CEP standards take effect. The Randstad logistics hub integrates automated packaging lines from multiple OEMs requiring middleware development.
China
Dual carbon goals and GB standards enforcement reshape material selection for converters serving export-oriented electronics manufacturers. NMPA validation requirements extend procurement cycles for pharmaceutical cold-chain formats. The Yangtze River Delta concentration of semiconductor fabricators drives anti-static and moisture-barrier specifications for component protection.
France
Modulated eco-modulation fees reward packaging designs scoring above 70 percent on recyclability indices, concentrating converter investment in fiber-based barrier coatings. ANSM oversight of pharmaceutical packaging maintains stringent qualification protocols. The Île-de-France cosmetics cluster specifies unboxing-optimized formats with tear-strip reveals for direct-to-consumer beauty brands.
Pre-Assembled Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pre-assembled packaging landscape. Integrated converters with captive pulp or resin operations control input cost volatility, while asset-light assemblers compete on customization velocity and graphic execution. Three archetypes dominate: vertically integrated substrate producers, automated systems bundlers, and specialized barrier coating formulators. M&A activity concentrates among containerboard integrators seeking corrugating plant networks, while strategic partnerships proliferate between film suppliers and equipment OEMs.
Among integrated packaging conglomerates, Amcor exemplifies the resin-to-film technology anchor through captive polymer operations, Smurfit Westrock occupies the containerboard integration position with mill and corrugating assets across multiple continents, and Sealed Air Corporation represents the automated systems bundler archetype combining film, equipment, and technical service into single-source contracts.
| Leading Market Players |
|---|
| Amcor |
| Ball Corporation |
| Smurfit Westrock |
| Sealed Air Corporation |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Crown Holdings |
| International Paper |
| Berry Global |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with automotive OEMs lock in resin and containerboard supply visibility while insulating converters from OCC spot volatility in European markets. German component suppliers negotiate multi-year tray pooling agreements that fix per-trip pricing, transferring volume risk to converters in exchange for guaranteed capacity access.
Pricing Analysis
The customization-premium spread separates configured-to-order returnable tray systems from standard corrugated boxes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA food-contact tiers commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from flexible pouch substitution in shelf-stable food segments, compressing margins for rigid tray converters. Independent corrugators without captive pulp supply exhibit highest price sensitivity, while integrated conglomerates with mill assets maintain pricing power through input cost control.
Supply Chain Analysis
Germany and Poland anchor returnable packaging production for automotive logistics, with Czech Republic greenfield capacity absorbing overflow demand from Stuttgart and Wolfsburg clusters. Containerboard converters draw from Swedish and Finnish pulp mills, while plastic tray manufacturers source PET resin from Benelux petrochemical complexes. Supply chain risk centers on single-source vulnerability for water-based barrier coating formulators, where formulation chemist scarcity constrains R&D throughput. Distribution runs through just-in-sequence delivery networks linking converter plants directly to assembly line docks, eliminating intermediate warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in PFAS-free molded fiber formulation and water-based oxygen barrier chemistry represents the critical capability gap constraining converter expansion. Firms possessing these scarce technical assets capture disproportionate margin in regulated food-contact and healthcare segments.
For Market Incumbents: Consolidate barrier coating R&D capabilities through targeted acquisition of specialized formulators in the Baden-Württemberg cluster. Add captive corrugating capacity in Poland to arbitrage labor costs while maintaining proximity to German automotive demand. ECHA's tightening REACH restrictions on plastic additives threaten resin-dependent independents; backward integration into bio-based coating production defends margin position against regulatory-driven material substitution. For New Entrants and Emerging Players: Anchor in pharmaceutical cold-chain packaging, where pre-qualified insulated shipper demand outstrips qualified supplier capacity. Target UK direct-to-consumer beauty brands seeking unboxing-optimized formats with tear-strip reveals and inline digital print. Pursue co-development partnerships with subscription box merchants as the go-to-market angle, bundling structural design and automated pack-out capabilities into single-source contracts. For Investors and Strategic Acquirers: Capital is best deployed toward automated systems bundlers combining film, equipment, and technical service, given their pricing power in e-commerce fulfillment infrastructure. Long-term viability favors converters with demonstrated compliance navigation across FDA, EFSA, and EU Packaging and Packaging Waste Regulation frameworks. Watch for harmonized CEP recyclability testing protocols as the inflection signal, which will consolidate procurement authority with suppliers possessing pre-validated mono-material designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Mills | Captive pulp supply insulates margins from OCC spot volatility in European markets. |
| Barrier Coating Specialist Acquisition | PFAS-free formulation expertise commands premium pricing in quick-service restaurant supply. |
| Automated Packaging Line Deployment | Inline digital print and pack-out automation secures single-source contracts with subscription merchants. |
| Pharmaceutical Cold-Chain Qualification | FDA-validated insulated shippers address temperature excursion risks in biologics distribution. |
| Returnable Tray Pooling Program Expansion | RFID-tracked standardization eliminates single-use corrugated from German automotive assembly lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across converter procurement directors, automotive Tier 1 supplier logistics managers, quick-service restaurant chain packaging engineers, and pharmaceutical cold-chain specialists. Secondary validation drew from ECHA REACH restriction notices, EU Packaging and Packaging Waste Regulation implementation guidance, FDA food-contact substance notifications, and SEC 10-K filings from integrated packaging conglomerates. Bottom-up volume triangulation from plant-level capacity and top-down demand aggregation from end-use procurement patterns were reconciled to establish market sizing.
Across the analysis window, forecasts reflect segment-level modeling by product type, material substrate, end-use application, and geographic production cluster. CAGRs were derived from regression analysis against automotive production indices, e-commerce fulfillment center expansion pipelines, and regulatory compliance deadline schedules. Industry-specific inputs include returnable tray pooling program adoption curves and water-based barrier coating qualification timelines.
Material uncertainties — sudden OCC price spikes, accelerated REACH enforcement, or harmonized recyclability protocol delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and substitution elasticity in food-contact applications. Recalibration cycles align with material shifts in EU member state fee structures and automotive platform standardization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Europe Packaging Automation Market