
 Automatic Capping Machine Market | 2026-2036
Automatic Capping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Capping Machine Market Outlook
The EU Green Deal packaging sustainability mandates is broadening retrofit demand across European beverage and pharmaceutical filling lines. Krones AG leverages its Ingolstadt manufacturing depth to dominate high-speed rotary capping exports. SACMI Group anchors ceramic and glass packaging integration with specialized turret designs. Syntegon Technology differentiates through servo-driven cleanroom-capable systems for injectable vial applications.
An automatic capping machine is an electromechanical packaging system that applies threaded, crimped, or snap-fit closures to containers at speeds ranging from 50 to 1,200 units per minute using torque-controlled spindles or magnetic clutches. Its primary purpose is to ensure seal integrity, prevent contamination, and maintain production throughput across liquid and semi-solid product lines. Rotary capping machines capture the largest installed base in carbonated soft drink and bottled water facilities where continuous motion maximizes output. Inline capping machines represent the fastest-growing configuration among craft breweries and regional dairy processors seeking modular expansion without full line replacement. Servo driven cappers command premium positioning in pharmaceutical vial capping where precise torque validation and electronic batch recording are mandatory.
FDA cGMP regulations and the EU MDR framework enforce seal-integrity documentation and contamination-control protocols that directly shape machine specification sheets and validation protocols. ISO 9001 and ISO 15378 certification requirements from equipment buyers in Germany and Switzerland filter supplier eligibility and sustain R&D investment in traceable torque-feedback systems. Stakeholders must monitor evolving ESG disclosure rules under the EU CSRD that will soon require lifecycle carbon reporting for packaging machinery procurement decisions.
Market Dynamics
Pharmaceutical serialization mandates and EU Green Deal packaging targets are forcing beverage and pharma bottlers to replace legacy mechanical cappers with servo-driven systems capable of torque validation and electronic batch recording.
Growth Catalysts
- EU Green Deal packaging mandates:Beverage producers across Germany and France face binding recycled-content thresholds that require retrofitting existing lines with precision capping equipment to minimize material waste and seal failures.
- FDA cGMP contamination-prevention standards:Injectable drug manufacturers must document seal integrity at the vial level, driving specification of cleanroom-capable rotary systems with magnetic clutch torque control.
- Servo motor technology maturation:Declining costs for high-precision drive systems enable mid-sized craft breweries and regional dairy processors to access continuous-motion capping previously limited to multinational bottlers.
Market Restraints
- Stainless steel and servo drive input volatility:Price swings in 316L stainless steel and rare-earth magnet materials compress margins for equipment builders serving price-sensitive regional dairy markets.
- Precision component supply concentration:High-torque magnetic clutches and pharmaceutical-grade spindle assemblies concentrate among specialized suppliers in southern Germany and northern Italy.
- Pharmaceutical validation timeline friction:FDA 21 CFR Part 11 compliance documentation and IQ/OQ/PQ protocols extend sales-to-revenue cycles by 12-18 months for cleanroom capping installations.
Strategic Opportunities
- India pharmaceutical contract manufacturing expansion:CDSCO's tightening GMP enforcement and rising injectable drug exports create demand for servo-driven vial capping systems with electronic batch recording.
- EU CSRD lifecycle carbon reporting:Machinery procurement decisions will soon require documented carbon footprints, favoring European-built equipment with transparent supply chains and energy-efficient servo architectures.
- Machine vision-torque feedback convergence:Integration of real-time vision inspection with closed-loop torque control enables predictive maintenance contracts and outcome-based service models for high-volume bottlers.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven capping systems require cross-functional expertise combining mechanical alignment, PLC programming, and torque calibration that outpaces vocational training output in industrial regions.
- Legacy line integration complexity:Retrofitting servo cappers into 1990s-era filling lines demands custom mechanical interfaces and control system bridging that extends commissioning timelines and strains project engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Capping Machine Market |
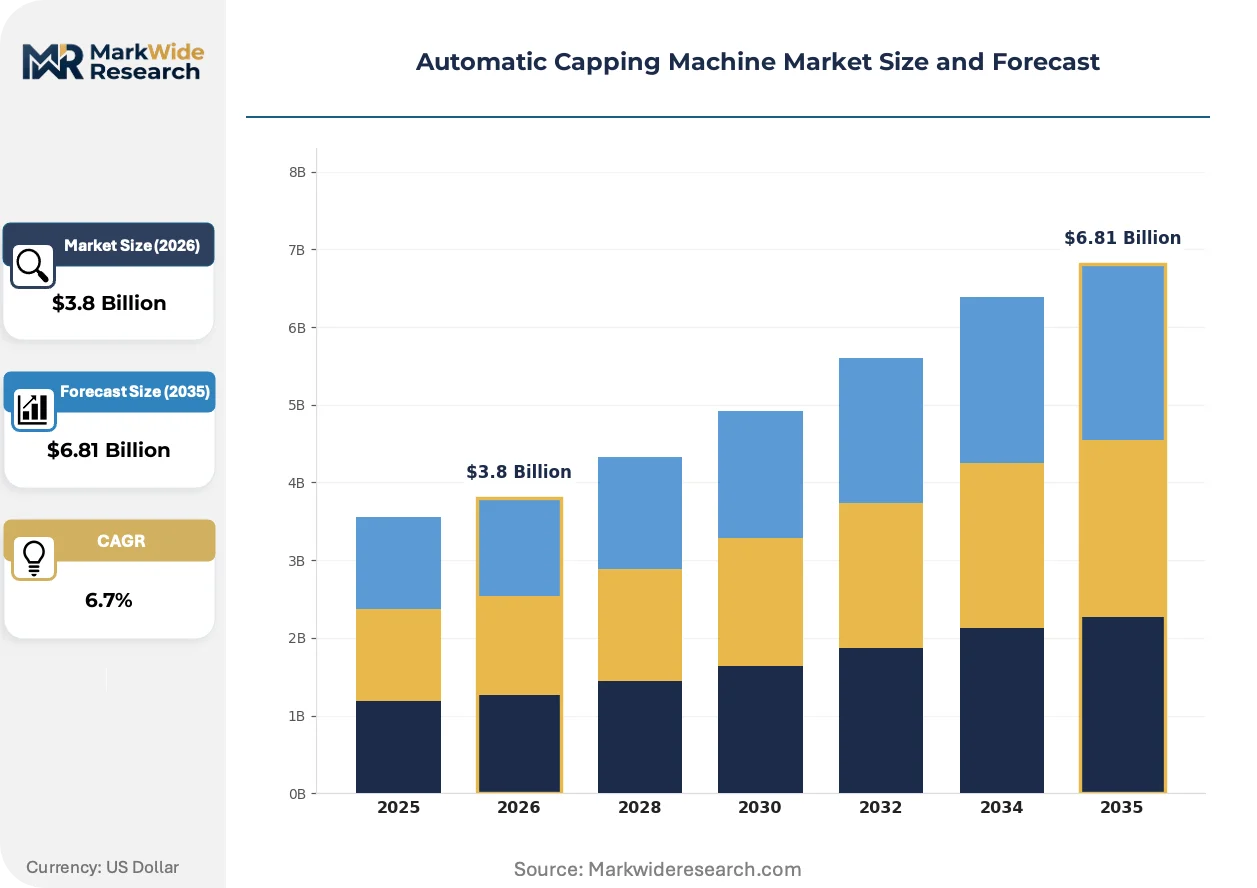
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Capping Machines, Inline Capping Machines, Servo Driven Cappers, Automatic Spindle Cappers End User: Food and Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Pneumatic, Electric, Mechanical, Hybrid Application: Bottle Capping, Jar Capping, Vial Capping, Tube Capping |
| Companies Covered | KHS GmbH, IMA Group, Krones AG, GEA Group, Serac Group, Syntegon Technology, SACMI Group, ProMach, Sidel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Capping Machine Market Strategic Shifts
Electrification of motion control and tightening pharmaceutical traceability requirements are compressing the gap between beverage and pharma capping specifications. Equipment builders now engineer platforms that span both sectors.
Servo-driven spindle technology is expanding into carbonated soft drink bottling lines previously dominated by mechanical cam-driven systems. Coca-Cola and PepsiCo bottling partners in the United States and Mexico are specifying servo architectures for their newest high-speed rotary installations. This shift compresses changeover times from hours to minutes and enables real-time torque adjustment for lightweighted PET closures.
The EU CSRD disclosure framework mandates lifecycle carbon reporting for packaging machinery procurement decisions starting with large listed enterprises. German and Swiss pharmaceutical buyers now require ISO 14001-certified equipment with documented energy consumption per thousand units capped. Equipment vendors serving these buyers are redesigning machine architectures to reduce pneumatic consumption and enable regenerative servo braking.
Regional craft breweries and small-batch dairy processors are consolidating purchasing through cooperative equipment procurement networks. These buying groups negotiate standardized servo-driven inline capping platforms with modular expansion paths, displacing the traditional model of direct OEM relationships. The cooperative model is most visible in the Benelux region and Pacific Northwest United States, where shared technical staff reduce the mechatronics expertise burden on individual producers.
Automatic Capping Machine Market Segmentation
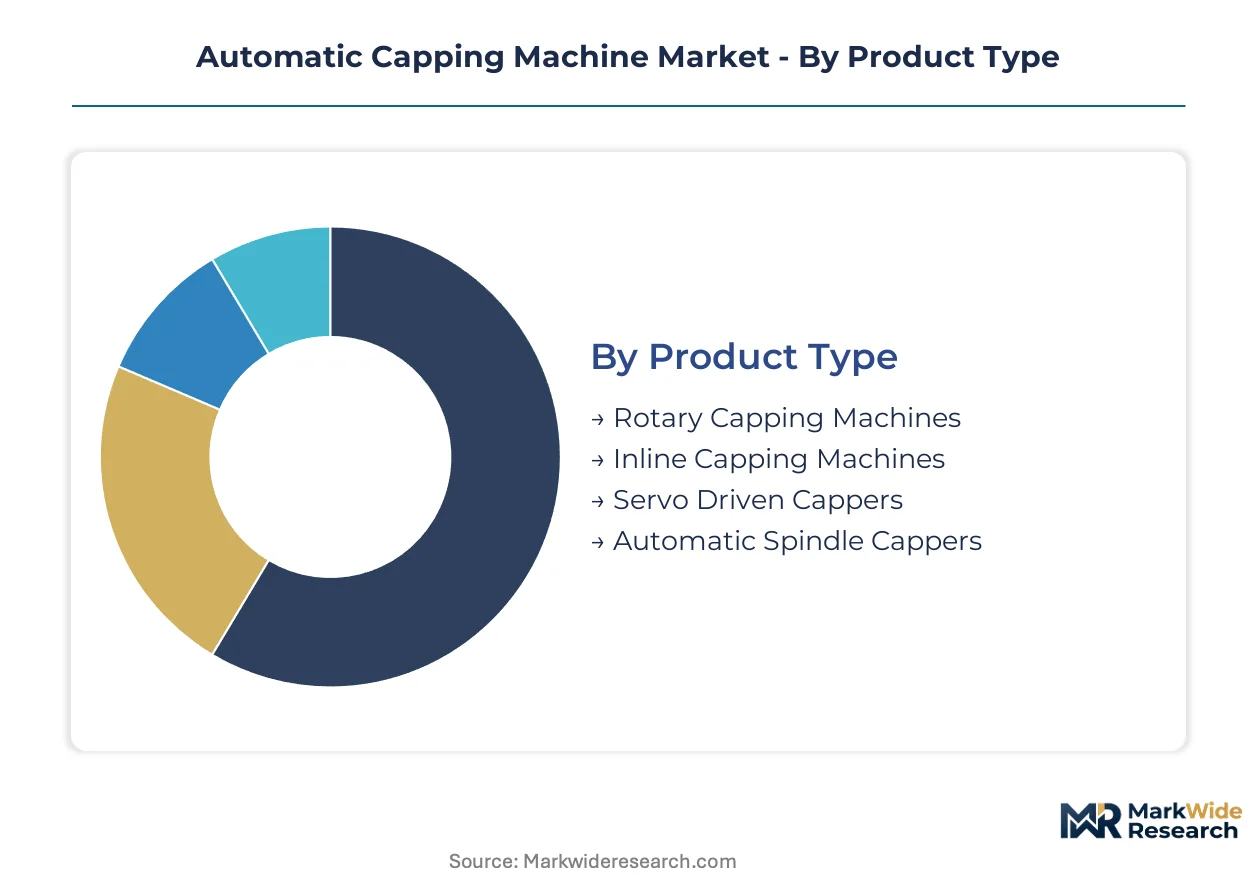
Equipment specification in the automatic capping machine market follows distinct upgrade cycles across product types, end-use sectors, and technology platforms. Segmentation reveals where retrofit demand concentrates and which configurations capture replacement spend from beverage bottlers and pharmaceutical manufacturers.
Product Type:
Retrofit cycles differ sharply between continuous-motion rotary systems and modular inline configurations, with upgrade timelines stretching from 15-year mechanical replacements to 7-year servo technology refreshes.
- Rotary Capping Machines:Continuous-motion turret designs apply closures at 600-1,200 units per minute using magnetic clutch torque control. Demand clusters at Coca-Cola and PepsiCo bottling partners in the United States and Mexico replacing 1990s-era mechanical cam systems with servo-capable platforms that enable real-time torque adjustment for lightweighted PET closures.
- Inline Capping Machines:Intermittent-motion systems with 50-300 units per minute throughput suit craft breweries and regional dairy processors seeking modular expansion without full line replacement. Cooperative procurement networks in the Benelux region and Pacific Northwest United States are consolidating purchases of standardized servo-driven inline platforms with shared technical staff.
- Servo Driven Cappers:Precision torque validation and electronic batch recording meet FDA cGMP and EU MDR requirements for injectable drug manufacturers.
- Automatic Spindle Cappers:Multi-spindle designs with mechanical or hybrid drive architectures serve mid-volume carbonated soft drink and bottled water facilities.
Volume placements concentrate in rotary capping machines; the faster expansion belongs to inline capping machines.
End User:
Regulatory intensity separates end-use segments, with pharmaceutical serialization mandates and EU Green Deal packaging targets forcing divergent specification priorities across sectors.
- Food and Beverage:Carbonated soft drink and bottled water bottlers in Germany and France drive rotary system demand under binding recycled-content thresholds. Krones AG and KHS GmbH anchor precision-engineering clusters serving this segment with high-speed turret exports.
- Pharmaceuticals:Injectable drug manufacturers require cleanroom-capable systems with documented seal integrity at the vial level. FDA 21 CFR Part 11 compliance and EU MDR framework enforcement shape machine specification sheets and extend validation timelines.
- Cosmetics:Skincare and fragrance producers favor flexible inline systems accommodating diverse closure formats and batch sizes.
- Chemicals:Agrochemical and industrial lubricant bottlers prioritize corrosion-resistant 316L stainless steel construction and explosion-proof pneumatic systems.
Food and beverage commands the largest installed base; pharmaceuticals is climbing the fastest on regulatory-driven retrofit demand.
Technology:
Energy efficiency and torque precision are displacing pneumatic dominance as EU CSRD lifecycle carbon reporting mandates reshape procurement criteria.
- Electric:Servo motor architectures with regenerative braking and documented energy consumption per thousand units capped are gaining share among German and Swiss pharmaceutical buyers requiring ISO 14001-certified equipment.
- Pneumatic:Compressed-air systems retain cost advantages in price-sensitive regional dairy markets despite stainless steel and servo drive input volatility compressing margins.
- Mechanical:Cam-driven systems face accelerated replacement as servo motor technology maturation reduces cost barriers for mid-sized processors.
- Hybrid:Combined pneumatic-electric designs bridge legacy infrastructure and precision requirements in retrofit installations.
Electric technology is gaining share fastest on ESG procurement mandates; pneumatic retains volume concentration in emerging markets.
Application:
Container geometry and closure mechanics dictate machine architecture, with vial applications demanding the tightest torque tolerances and tube capping requiring specialized handling systems.
- Vial Capping:Pharmaceutical-grade spindle assemblies with magnetic clutch torque control serve injectable drug manufacturers under FDA cGMP contamination-prevention standards. Syntegon Technology differentiates through servo-driven cleanroom-capable systems for this application.
- Bottle Capping:PET and glass bottle formats across carbonated drinks, water, and spirits drive the broadest equipment demand. SACMI Group anchors ceramic and glass packaging integration with specialized turret designs.
- Jar Capping:Wide-mouth containers for sauces, spreads, and cosmetics require adjustable spindle spacing and torque profiles.
- Tube Capping:Collapsible tube formats for pharmaceuticals and cosmetics demand specialized feeding and orientation systems.
Bottle capping holds the dominant volume position; vial capping shows the steepest expansion trajectory on pharmaceutical serialization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingolstadt anchors European precision-engineering clusters for high-speed rotary capping systems, while Mexico City and São Paulo drive Latin American retrofit demand for beverage bottling lines.
Germany
FDA cGMP contamination-prevention standards and EU Green Deal packaging mandates force pharmaceutical and beverage producers toward servo-driven torque validation systems. Krones AG and KHS GmbH dominate exports from Bavarian manufacturing corridors serving carbonated-drink and injectable-drug manufacturers.
United States
Coca-Cola and PepsiCo bottling partners specify servo architectures for lightweighted PET closure handling across high-speed rotary installations. FDA 21 CFR Part 11 compliance documentation shapes procurement criteria for pharmaceutical vial capping in New Jersey and North Carolina pharmaceutical corridors.
India
CDSCO's tightening GMP enforcement and rising injectable drug exports create demand for electronic batch recording capabilities. Contract manufacturing expansion in Maharashtra and Gujarat pulls servo-driven cleanroom-capable systems from European and Japanese equipment builders.
Mexico
Beverage bottlers retrofit 1990s-era mechanical cam systems with servo-capable platforms to serve North American export markets. Mexico City and Monterrey industrial zones concentrate cooperative procurement networks negotiating standardized inline capping configurations.
Brazil
Regional dairy processors and craft breweries in São Paulo and Minas Gerais consolidate purchasing through cooperative equipment networks. ANVISA pharmaceutical serialization mandates accelerate replacement of legacy pneumatic cappers with torque-validated servo systems.
Automatic Capping Machine Market Competitive Environment
The competitive structure tilts toward precision-engineering specialists with deep pharmaceutical and beverage sector integration. Consolidation concentrates among German and Italian equipment builders possessing captive servo-drive integration capabilities and cleanroom validation expertise. Three archetypes dominate: integrated line builders offering turnkey filling-capping integration, component specialists supplying magnetic clutch assemblies to third-party OEMs, and regional fabricators serving price-sensitive dairy markets through pneumatic system customization. M&A activity targets torque-feedback technology assets, while capacity expansion focuses on Indian and Mexican assembly facilities to shorten delivery timelines for pharmaceutical contract manufacturers.
Among German-based integrated line builders, Krones AG and KHS GmbH exemplify the precision-engineering archetype with deep Ingolstadt manufacturing heritage. Syntegon Technology occupies a position within the cleanroom-specialist tier, representing servo-driven validation capabilities for injectable vial applications. SACMI Group anchors Italian ceramic and glass packaging integration expertise, while GEA Group and IMA Group sit within diversified engineering conglomerates leveraging cross-sector technology transfer.
| Leading Market Players |
|---|
| KHS GmbH |
| IMA Group |
| Krones AG |
| GEA Group |
| Serac Group |
| Syntegon Technology |
| SACMI Group |
| ProMach |
| Sidel Group |
| Others |
Value Chain & Pricing Dynamics
Mechatronics technician concentration in southern Germany and northern Italy generates labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade servo systems and pneumatic dairy equipment. Equipment builders in Bavarian precision-engineering clusters command 40-60% labor premiums over regional fabricators in emerging markets, forcing price stratification across certification tiers.
Pricing Analysis
Outcome-based pricing tied to line uptime guarantees anchors premium tiers for pharmaceutical vial capping systems with FDA 21 CFR Part 11 validation. Three-tier pricing structure across premium, standard, and economy levels separates cleanroom-validated servo architectures from modular inline craft brewery platforms. Cost compression in economy-tier pneumatic systems is intensifying because stainless steel and rare-earth magnet input volatility squeezes regional dairy fabricator margins. Pharmaceutical contract manufacturers show least price sensitivity given mandatory torque validation requirements, while craft cooperatives in Benelux and Pacific Northwest negotiate aggressively on standardized inline platforms.
Supply Chain Analysis
Regional distribution centers in Ingolstadt, Bologna, and Chicago anchor hub-and-spoke patterns for magnetic clutch assemblies and pharmaceutical-grade spindle components. Manufacturing concentration in Germany, Italy, and Switzerland feeds precision-engineering clusters serving FDA and EU MDR compliance markets. Supply chains draw from 316L stainless steel mills in Germany and Sweden, rare-earth magnet processors in China, and specialized pneumatic valve suppliers in northern Italy. Single-source vulnerability concentrates in high-torque magnetic clutch production across three family-owned suppliers near Stuttgart. Distribution runs through OEM-direct channels for pharmaceutical validators and cooperative procurement networks for regional dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around equipment builders with captive servo-drive integration and cleanroom validation expertise. EU CSRD lifecycle carbon reporting and pharmaceutical serialization mandates are forcing weaker pneumatic specialists into exit or acquisition.
For Market Incumbents: To counter cooperative procurement networks consolidating craft brewery and dairy purchasing, Krones AG and Syntegon Technology should deepen backward integration into servo motor production and expand Indian assembly capacity for CDSCO-compliant pharmaceutical contract manufacturers. Certification investment in ISO 14001 energy documentation captures EU CSRD procurement decisions from German and Swiss buyers. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical validators and economy pneumatic dairy cappers offers entry terrain for mid-market servo-inline platforms targeting ANVISA-regulated Brazilian pharmaceutical serialization and Indian CDSCO enforcement waves. White-space concentrates in Maharashtra and Gujarat contract manufacturing corridors where European equipment delivery timelines stretch 18-24 months. Go-to-market leverage rests on localized technical service partnerships with existing dairy cooperative networks. For Investors and Strategic Acquirers: Re-rating potential sits with torque-feedback technology specialists given machine vision-torque convergence enabling predictive maintenance contracts and recurring service revenue streams. Long-term viability favors equipment builders spanning beverage and pharmaceutical specifications as electrification compresses sector boundaries. Acquisition targets should demonstrate cleanroom validation capabilities and Indian or Mexican assembly presence. Signal to watch: pharmaceutical contract manufacturers accelerating IQ/OQ/PQ timeline compression demands.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Integration | Captive motor production insulates margin pressure from rare-earth magnet volatility in Chinese supply chains. |
| Cleanroom Validation Investment | FDA 21 CFR Part 11 and EU MDR documentation capabilities unlock pharmaceutical retrofit cycles. |
| Indian Assembly Expansion | Maharashtra and Gujarat proximity shortens delivery timelines for CDSCO-enforced contract manufacturers. |
| Machine Vision-Torque Convergence | Real-time inspection integration enables predictive maintenance contracts with Coca-Cola and PepsiCo bottlers. |
| Cooperative Procurement Partnership | Benelux and Pacific Northwest craft brewery networks consolidate standardized inline platform demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automatic capping machine analysis. Primary interviews with packaging line engineers, pharmaceutical manufacturing directors, beverage plant managers, and aftermarket service heads combined with FDA 21 CFR Part 11 guidance documents, EU MDR technical files, and CDSCO GMP inspection reports. Bottom-up equipment shipment triangulation against top-down beverage and pharmaceutical capital expenditure patterns validated market sizing across rotary, inline, and servo-driven configurations.
Segmentation granularity modeled product type, end-use sector, technology platform, and application at the country level across Germany, United States, India, Mexico, and Brazil. CAGRs derived from equipment replacement cycle analysis, regulatory mandate enforcement timelines, and servo motor cost curve trajectories throughout the forecast period. Pharmaceutical serialization mandates and EU CSRD disclosure frameworks served as structural demand inputs for cleanroom-capable and energy-documented equipment categories.
Inputs from OEM shipment disclosures and regulatory filing databases were available through the study window; gaps in privately held regional fabricator production data introduce uncertainty bands in pneumatic system volume estimates. Forecasts reflect documented assumptions on retrofit cycle acceleration and servo motor adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Automatic Strapping Machines Market