
 Automated Label Inspection Machines Market | 2026-2036
Automated Label Inspection Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Label Inspection Machines Market Analytics
Modular packaging line configurations is consolidating buyer preference around integrated inspection stations rather than standalone retrofit units. Cognex Corporation leverages its vision software ecosystem to anchor premium positioning in camera-based quality assurance. Mettler-Toledo International Inc. competes through precision weighing-to-vision hybrid systems for pharmaceutical compliance. Krones AG dominates integrated inline inspection within high-speed beverage filling lines.
Automated label inspection machines employ high-resolution camera arrays, machine vision algorithms, and laser scanning modules to detect print defects, barcode degradation, and serialization errors on product labels at line speeds exceeding 600 units per minute. These systems serve primarily to enforce regulatory traceability and prevent counterfeit product infiltration across pharmaceutical, food, and consumer goods supply chains. Inline inspectors lead installed base volume due to their integration into continuous production flows, while robotic systems represent the fastest-expanding segment as flexible manufacturing demands adaptive inspection positioning. Camera-based solutions sustain the largest technology share, though RFID systems are gaining traction in pharmaceutical track-and-trace applications where electromagnetic verification complements optical validation.
The US FDA enforces strict label accuracy and serialization requirements through the Drug Supply Chain Security Act, compelling pharmaceutical manufacturers to deploy verification-capable inspection infrastructure. The EU Falsified Medicines Directive mandates standardized safety features on prescription packaging, directly stimulating vision system upgrades across European production facilities. Stakeholders must weigh the capital intensity of robotic inspection flexibility against the operational simplicity of fixed inline architectures when planning capacity investments.
Market Dynamics
Serialization mandates under the US Drug Supply Chain Security Act and the EU Falsified Medicines Directive are compelling pharmaceutical manufacturers to replace legacy laser scanners with integrated camera-based verification systems, compressing replacement cycles and reshaping vendor procurement criteria.
Growth Catalysts
- EU Falsified Medicines Directive:Mandated 2D data matrix codes on prescription packaging drive vision system upgrades across European pharmaceutical production lines.
- Pharmaceutical track-and-trace:Electromagnetic RFID verification complements optical validation in high-value drug distribution, expanding inspection modality requirements.
- German packaging equipment cluster:Concentrated automation engineering expertise accelerates technology transfer from beverage to pharmaceutical inspection applications.
Market Restraints
- High-resolution CMOS sensor supply:Concentrated fabrication capacity in East Asian foundries creates input cost volatility and lead time uncertainty for camera array production.
- Legacy laser scanner installed base:Depreciated but functional inspection infrastructure in mid-tier food packaging operations delays replacement investment decisions.
- CE marking complexity:Evolving machinery safety standards under the EU Machinery Directive extend certification timelines for new inspection system introductions.
Strategic Opportunities
- Robotic adaptive positioning:Flexible manufacturing lines in contract packaging services create demand for inspection systems with programmable spatial reconfiguration.
- India pharmaceutical export compliance:CDSCO alignment with international serialization standards drives inspection infrastructure investment in domestic formulation facilities.
- Vision-weighing hybrid architectures:Converged metrology platforms address simultaneous label verification and fill-level compliance in single-station configurations.
Industry Challenges
- Machine vision engineering talent:Shortage of specialists capable of integrating deep learning algorithms with real-time industrial control systems constrains deployment velocity.
- Legacy PLC integration:Proprietary communication protocols in established packaging lines complicate retrofit of modern inspection stations without full line shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Label Inspection Machines Market |
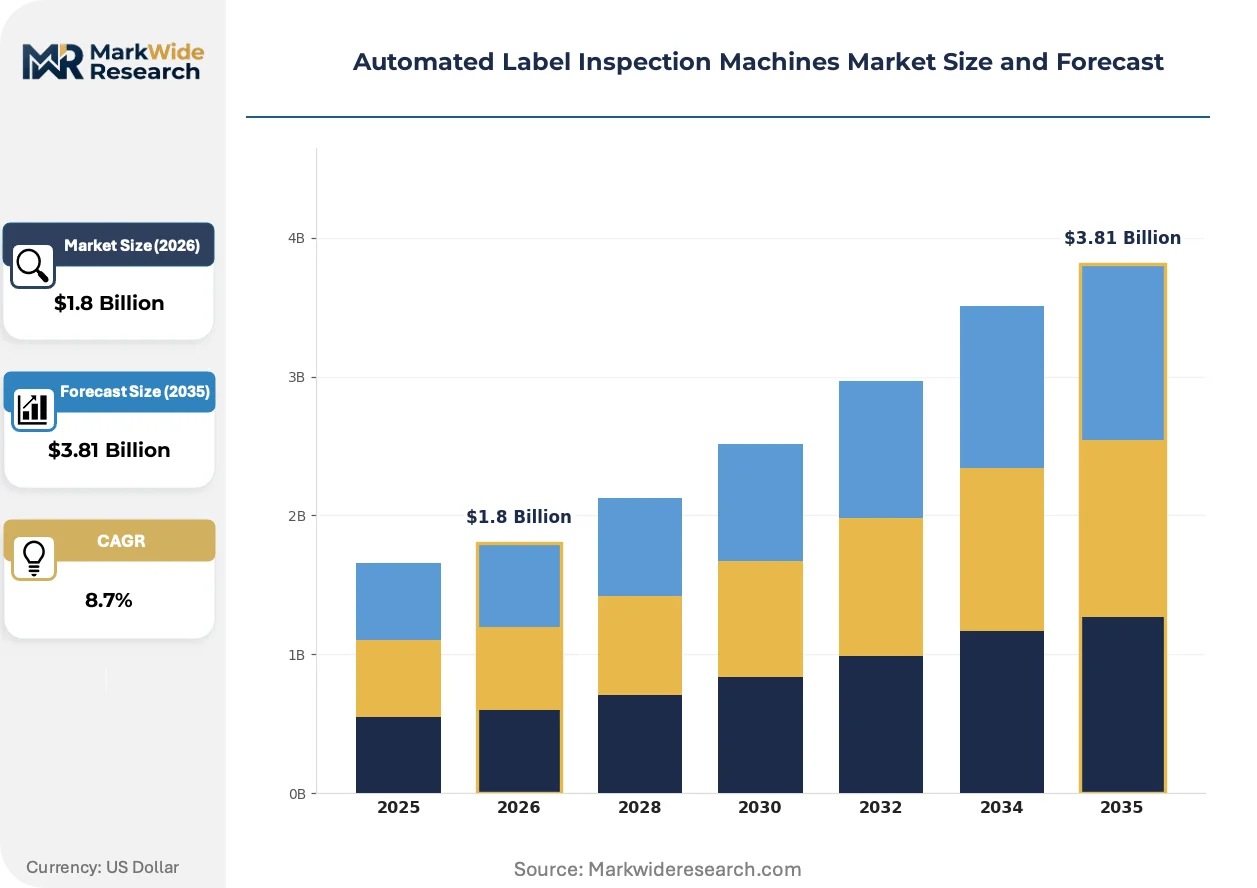
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Inspectors, Offline Inspectors, Handheld Devices, Robotic Systems Technology: Vision Systems, Laser Scanners, RFID Systems, Camera-Based Solutions End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Application: Quality Assurance, Compliance Testing, Brand Protection, Inventory Management |
| Companies Covered | Omron Corporation, Cognex Corporation, Mettler-Toledo International Inc., Ametek, Inc., Loma Systems, Sesotec GmbH, Krones AG, IMA Group, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Label Inspection Machines Market Evolving Landscape
Camera-based inspection architectures are fundamentally restructuring competitive positioning as pharmaceutical compliance requirements exceed the resolution capabilities of legacy scanning technologies. Three concurrent developments are reshaping technology investment patterns.
Deep learning-enabled defect classification is overtaking rules-based image processing in high-speed pharmaceutical lines. Convolutional neural networks trained on print defect datasets identify subtle serialization errors at 600+ units per minute. German and Swiss packaging OEMs now specify AI-vision modules as standard for new line configurations, compressing price premiums for software-anchored suppliers.
The US FDA's enforcement discretion timelines for Drug Supply Chain Security Act lot-level verification are hardening into mandatory compliance checkpoints. Pharmaceutical contract manufacturers face 2027 deadlines for interoperable track-and-trace systems. This regulatory pressure concentrates upgrade demand among mid-cap generic drug producers previously deferring capital investment.
Service unbundling is fragmenting traditional inspection system procurement. End-users now separate hardware acquisition from algorithm licensing and validation support. This behavioral shift pressures bundled-equipment vendors in North American markets, where pharmaceutical quality departments increasingly source vision software independently from automation integrators.
Automated Label Inspection Machines Market Segmentation
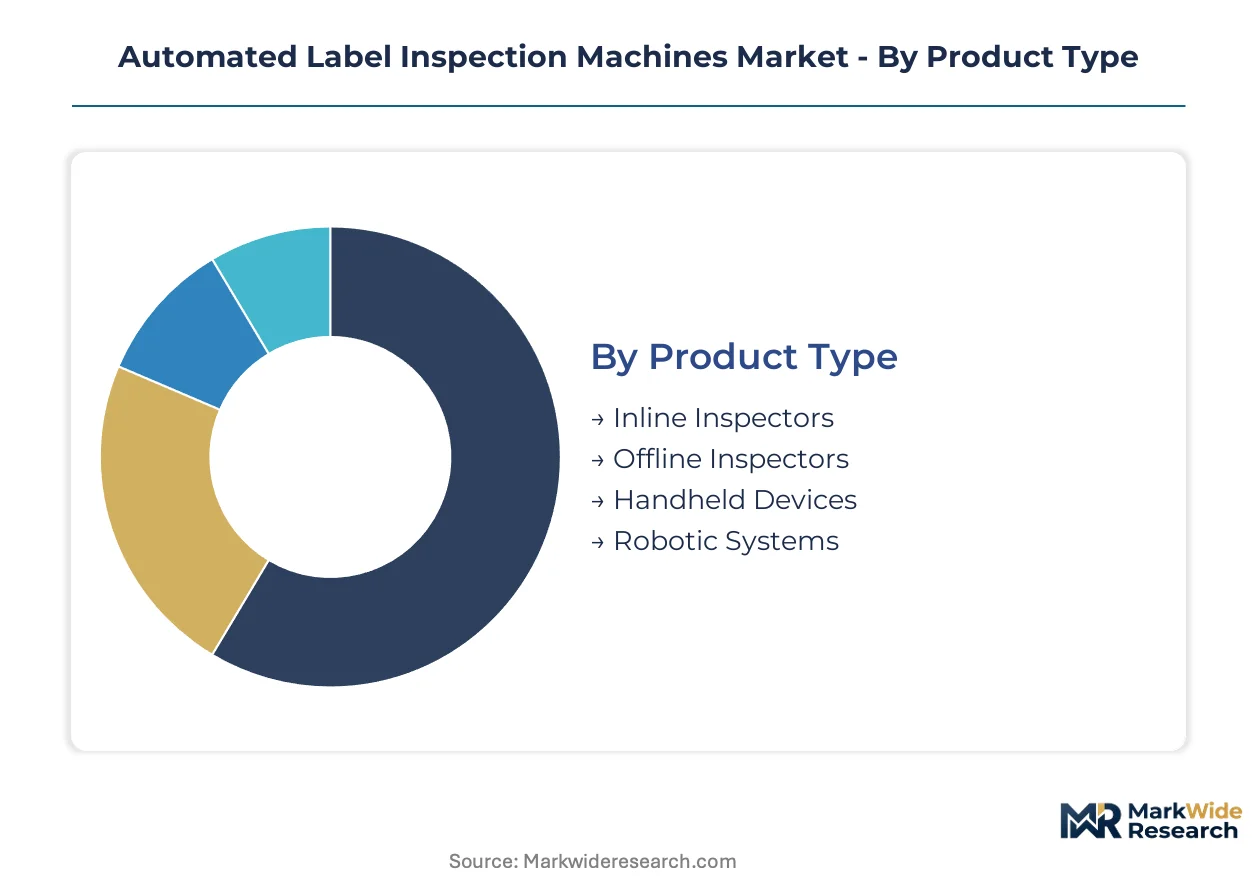
Segmentation in automated label inspection machines reflects divergent capital deployment strategies across pharmaceutical compliance mandates and flexible manufacturing requirements. Procurement patterns cluster around integrated inline architectures versus adaptive robotic configurations, with technology choices directly tied to serialization enforcement timelines and line speed specifications.
Product Type:
Supply concentration in German packaging equipment engineering has anchored inline inspection as the default specification for high-speed beverage and pharmaceutical lines, while contract manufacturers drive fragmentation toward modular alternatives.
- Inline Inspectors:Continuous-feed camera arrays and laser modules integrate directly into packaging line conveyors, processing 600+ units per minute without handling interruption. Demand concentrates in Germany at Krones AG and Syntegon Technology GmbH facilities serving EU Falsified Medicines Directive compliance deadlines. The installed base dominance here creates replacement cycle compression as serialization mandates harden.
- Robotic Systems:Programmable multi-axis positioning enables adaptive inspection geometry for contract packaging services handling variable batch formats. These systems are expanding most quickly in North American pharmaceutical manufacturing where flexible capacity commands premium pricing against fixed-line alternatives.
- Offline Inspectors:Batch-mode verification stations serve mid-tier food processors with intermittent production schedules and depreciated legacy infrastructure.
- Handheld Devices:Portable validation tools support warehouse receipt inspection and field audit applications in distribution-heavy supply chains.
Today's leader: Inline Inspectors. Tomorrow's challenger: Robotic Systems.
Technology:
Cost tier stratification separates premium vision software ecosystems from commodity laser hardware, with hybrid architectures emerging at the boundary.
- Vision Systems:High-resolution CMOS arrays paired with deep learning algorithms detect print defects and 2D data matrix degradation at pharmaceutical line speeds. Cognex Corporation anchors premium positioning through software licensing models that unbundle hardware from algorithm access. FDA enforcement discretion timelines for Drug Supply Chain Security Act compliance are compressing procurement decisions toward these architectures.
- Camera-Based Solutions:Rules-based image processing modules dominate mid-speed food and beverage applications where defect libraries are standardized and computational requirements are modest.
- Laser Scanners:Legacy one-dimensional barcode verification persists in depreciated food packaging infrastructure, though replacement cycles lag regulatory pressure.
- RFID Systems:Electromagnetic verification complements optical validation in high-value pharmaceutical distribution, with CDSCO alignment requirements in India driving incremental adoption for export compliance.
Camera-based architectures command current procurement; RFID-electromagnetic hybrids are gaining specification share in track-and-trace applications.
End User:
Application maturity varies sharply across customer types, with pharmaceutical serialization mandates creating urgency gaps versus cosmetic and electronics verticals.
- Pharmaceuticals:Stringent US FDA and EU EMA serialization requirements mandate 2D data matrix verification at unit and case levels, forcing vision system upgrades across formulation and contract manufacturing facilities. The US Drug Supply Chain Security Act lot-level verification deadlines concentrate investment among mid-cap generic producers.
- Food & Beverage:High-speed filling lines at German beverage OEMs specify integrated inspection as standard, though regulatory pressure remains below pharmaceutical thresholds.
- Cosmetics:Brand protection and anti-counterfeiting drive selective adoption, with premium positioning supporting higher equipment margins than commodity food applications.
- Electronics:Component traceability and ESD-sensitive handling create niche demand for specialized inspection geometries.
Pharmaceuticals dominate capital allocation; cosmetics represent the steepest expansion trajectory as brand protection budgets harden.
Application:
Margin structure diverges between compliance-mandated testing and discretionary quality investments, with regulatory enforcement directly determining pricing power.
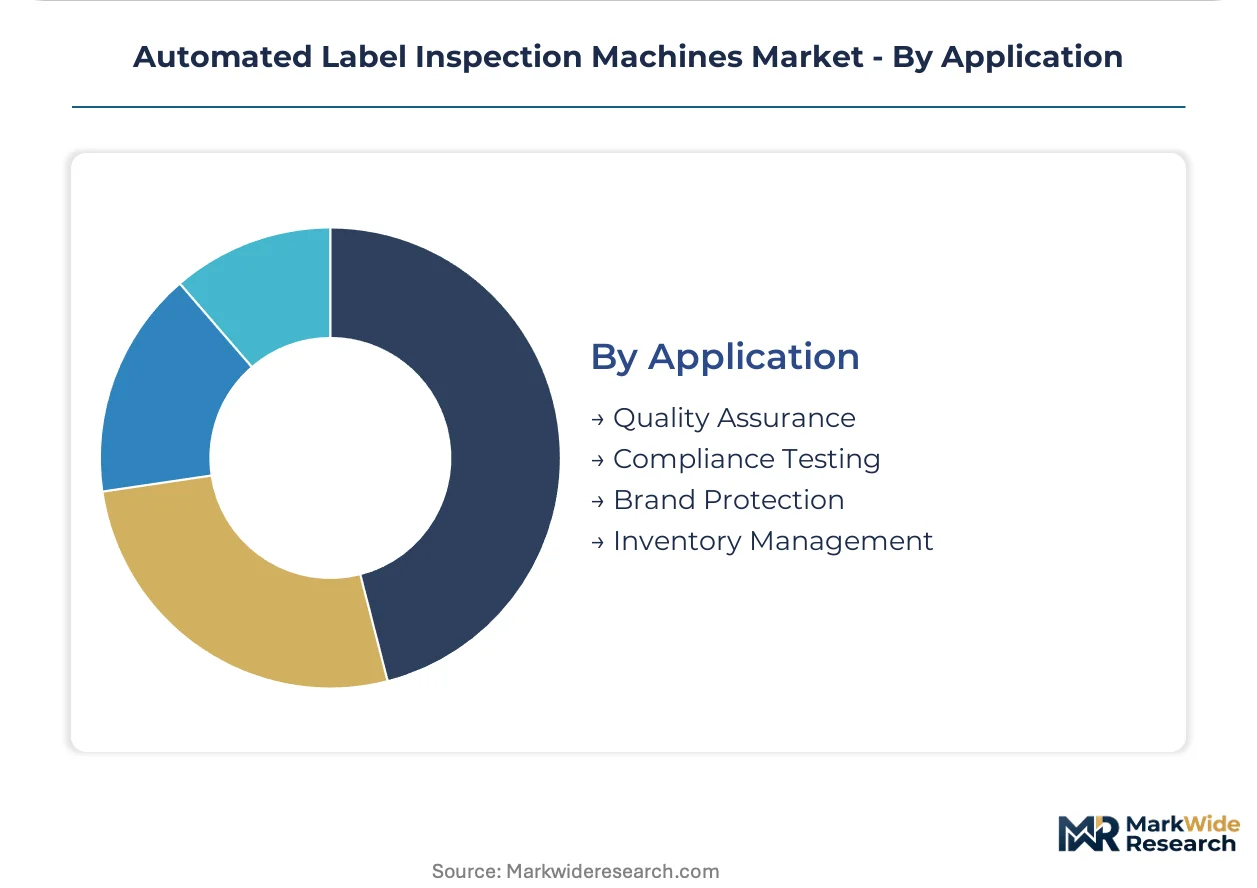
- Quality Assurance:Print defect detection and label placement verification serve baseline manufacturing requirements across all end-use verticals, with camera resolution specifications scaling to line speed requirements.
- Compliance Testing:Serialization code validation and aggregation verification are non-negotiable for pharmaceutical distribution authorization, creating inelastic demand curves and supporting premium pricing for validated software ecosystems.
- Brand Protection:Anti-counterfeiting features and authentication marking serve discretionary cosmetic and luxury goods budgets with cyclical investment patterns.
- Inventory Management:Warehouse verification and shipment validation support downstream supply chain visibility, typically through lower-cost handheld or offline configurations.
Compliance Testing captures current procurement priority; Quality Assurance maintains volume leadership across installed base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated label inspection technology first achieved commercial scale in German beverage packaging halls during the 1990s, establishing engineering protocols that migrated into pharmaceutical applications as serialization mandates emerged in the 2010s.
Germany
FDA-equivalent serialization deadlines under EU Falsified Medicines Directive compress replacement cycles for legacy laser scanners. The country's national pharmaceutical regulator enforces 2D data matrix verification standards that exceed baseline CE marking requirements. Krones AG and Syntegon Technology GmbH anchor production clusters in Bavaria and Baden-Württemberg, exporting integrated inline inspection systems to formulation facilities across the continent.
United States
Pharmaceutical contract manufacturers face hardened FDA enforcement discretion timelines for Drug Supply Chain Security Act lot-level verification. The FDA mandates interoperable track-and-trace infrastructure by 2027 for mid-cap generic drug producers. Cognex Corporation's machine vision engineering presence in Greater Boston supplies algorithm development for camera-based quality assurance platforms serving domestic packaging lines.
India
Domestic formulation facilities expand inspection capacity to meet CDSCO alignment with international serialization standards for pharmaceutical export authorization. The national pharmaceutical regulator harmonizes track-and-trace requirements with WHO prequalification protocols. Maharashtra and Gujarat host contract manufacturing clusters where vision-weighing hybrid systems address simultaneous label verification and fill-level compliance.
Switzerland
Precision instrumentation heritage supports premium positioning in pharmaceutical metrology applications. Swissmedic maintains stringent validation requirements for automated inspection systems serving high-value drug distribution. Basel and Zurich industrial corridors concentrate engineering talent for deep learning-enabled defect classification at pharmaceutical line speeds.
China
Domestic pharmaceutical manufacturers upgrade inspection infrastructure under NMPA serialization mandates for vaccine and biologics distribution. The national medical products administration enforces traceability standards aligned with international supply chain security protocols. Yangtze River Delta packaging equipment fabricators localize camera array production to reduce dependence on imported CMOS sensor supply.
Automated Label Inspection Machines Market Competitive Landscape
The competitive structure tilts toward diversified industrial automation conglomerates with vision software ecosystems. Market concentration remains moderate, with tiered positioning separating premium algorithm-anchored suppliers from hardware-centric fabricators. Three archetypes dominate: vision software licensors, precision weighing-to-vision hybrid system integrators, and integrated packaging line OEMs. Capacity expansion and strategic technology licensing constitute the primary competitive moves, as algorithm access unbundles from hardware procurement.
Among diversified automation conglomerates, Omron Corporation and Cognex Corporation exemplify contrasting strategic positions. Omron's industrial control heritage situates it within integrated line architecture supply. Cognex occupies a position representing pure-play vision software licensing. Mettler-Toledo International Inc. anchors the precision metrology tier, its weighing instrumentation lineage informing hybrid inspection platform development. These three entities collectively illustrate how technology unbundling fragments traditional bundled-equipment vendor models.
| Leading Market Players |
|---|
| Omron Corporation |
| Cognex Corporation |
| Mettler-Toledo International Inc. |
| Ametek, Inc. |
| Loma Systems |
| Sesotec GmbH |
| Krones AG |
| IMA Group |
| Syntegon Technology GmbH |
| Others |
Value Network & Pricing Analysis
Pharmaceutical serialization mandates under the US Drug Supply Chain Security Act and the EU Falsified Medicines Directive are forcing mid-cap generic producers toward camera-based vision systems, compressing procurement timelines and concentrating supplier pricing power among German and Swiss equipment engineering clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade systems from mid-speed food packaging modules and depreciated laser scanner replacements. Premium tiers command algorithm licensing fees from software-anchored suppliers like Cognex Corporation, while standard tiers compete on hardware throughput metrics. Cost compression in the economy tier intensifies as East Asian fabricators localize camera array production. Contract manufacturers in North America exhibit highest price sensitivity due to capital constraint, whereas Swiss precision drug producers show lowest sensitivity given validation requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for high-resolution CMOS sensor fabrication, creating input cost volatility for camera-based inspection arrays. German and Swiss engineering clusters supply precision metrology components and deep learning algorithm development. Raw material dependencies include semiconductor-grade silicon, optical glass substrates, and industrial-grade aluminum frames. Tariff exposure runs through East Asian sensor supply chains into European and North American assembly facilities. Distribution runs through direct OEM relationships for integrated inline systems and automation integrator channels for modular robotic configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential: engineering talent costs in German packaging clusters run substantially above comparable capability in Indian pharmaceutical manufacturing corridors, creating margin expansion for hybrid system localization.
For Market Incumbents: Anchor premium positioning through algorithm licensing unbundling from hardware procurement, mirroring Cognex Corporation's software ecosystem model. Defend against East Asian camera array localization by deepening validation support capabilities for FDA and EMA compliance pathways. Prioritize capacity addition in Maharashtra and Gujarat to capture CDSCO-aligned pharmaceutical export demand from Indian formulation facilities. For New Entrants and Emerging Players: Automation integrators represent the most accessible channel partner type for penetrating North American contract packaging services. White-space targets include vision-weighing hybrid architectures for simultaneous label verification and fill-level compliance, plus RFID-electromagnetic verification modules for high-value drug distribution. Target mid-tier food processors in depreciated legacy infrastructure segments with retrofit-focused offline inspection stations. For Investors and Strategic Acquirers: Asymmetric upside sits with precision metrology specialists possessing weighing-to-vision hybrid development capability. Long-term viability over the next decade hinges on software-anchored positioning rather than hardware fabrication scale. Acquisition target archetype: mid-cap vision software licensors with validated pharmaceutical customer bases. Signal to watch: FDA enforcement discretion timelines hardening into mandatory compliance checkpoints for lot-level verification.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Unbundling | Cognex Corporation's software ecosystem model separates recurring revenue from hardware cycles. |
| Vision-Weighing Hybrid Development | Mettler-Toledo International Inc. converges metrology platforms for pharmaceutical compliance stations. |
| East Asian Sensor Supply Localization | Yangtze River Delta fabricators reduce CMOS dependence on Taiwan and South Korean foundries. |
| Indian Pharmaceutical Export Compliance | CDSCO alignment with WHO prequalification drives inspection infrastructure in Maharashtra clusters. |
| Deep Learning Defect Classification | Swiss and German OEMs specify AI-vision modules for 600+ units per minute pharmaceutical lines. |
Research Methodology
Bottom-up pharmaceutical manufacturing modeling reconciled against top-down packaging equipment production tracking forms the analytical core of this study. Primary interviews with vision system engineering directors, pharmaceutical quality assurance managers, contract manufacturing procurement leads, and automation integrator sales heads combined with secondary validation from FDA Drug Supply Chain Security Act guidance documents, EMA Falsified Medicines Directive implementation reports, CDSCO export compliance circulars, and SEC 10-K filings from diversified industrial automation conglomerates. Triangulation between demand-side installation data and supply-side production metrics ensures cross-verified volume estimates.
Historical trendline analysis of camera array shipments and laser scanner replacement cycles informs the projection framework. Segmentation dimensions modeled include product type architecture, technology modality, end-use vertical, and application purpose across the analysis window. CAGRs derive from regression-weighted growth rate convergence between equipment production capacity expansion and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate serialization mandate enforcement timelines and CMOS sensor supply lead time fluctuations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement discretion shifts, EU Machinery Directive certification timeline changes, and East Asian semiconductor fabrication capacity allocation. Forecasts reflect documented assumptions about regulatory compliance pacing and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Pre-Assembled Packaging Market