

Robotic Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Packaging Machines Market Insights
Germany is fragmenting as Chinese and South Korean suppliers expand European assembly capacity for robotic packaging systems. ABB leverages its motion-control software stack to sustain premium positioning in high-speed pharmaceutical lines. FANUC anchors Japanese supply through its dense service network and controller standardization across food packaging plants. KUKA competes on automotive-derived articulation precision repurposed for consumer electronics tray-loading cells.
Robotic packaging machines integrate articulated mechanical arms, vision systems, and programmable logic controllers to execute pick-place, case-packing, and palletizing operations at throughputs exceeding human manual rates. Delta robots dominate lightweight primary packaging for confectionery and snack pouches where cycle speeds surpass 200 picks per minute. Vision-guided robotics leads technology adoption as pharmaceutical contract packers replace fixed-position tooling with adaptive gripper systems for variable blister formats. Collaborative robots remain the fastest-growing technology segment among small-batch personal care manufacturers retrofitting legacy filling lines without full cage enclosures.
ISO 10218-1 and ISO 10218-2 govern robot safety integration, while the EU Machinery Directive mandates CE conformity for robotic packaging cells sold across Europe. FDA 21 CFR Part 11 compliance requirements shape pharmaceutical packaging robot validation protocols in the United States. Stakeholders must monitor evolving cybersecurity standards for connected packaging lines as IEC 62443 adoption extends from automotive into food and pharmaceutical automation infrastructure.
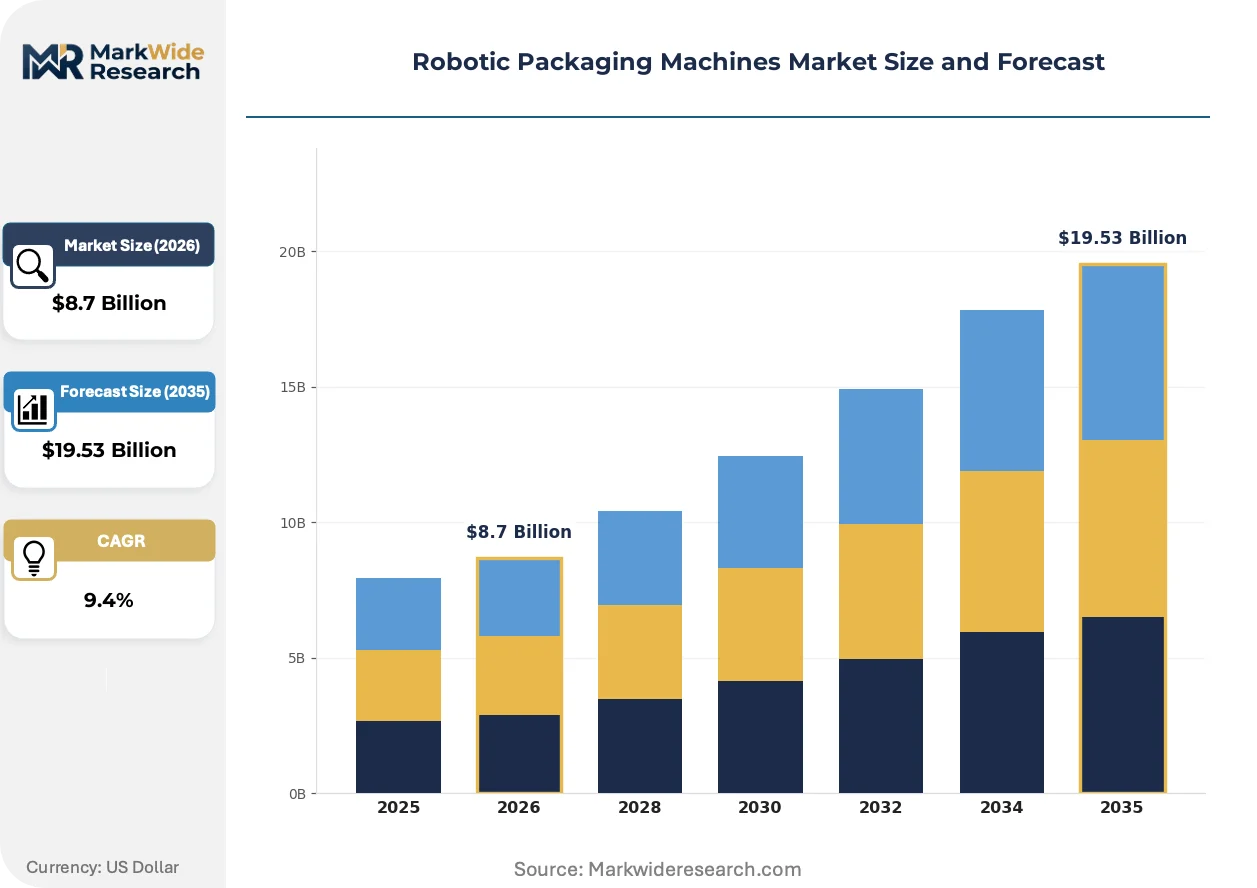
Market Dynamics
Vision-guided robotics is virtualizing fixed-position tooling across pharmaceutical and food packaging lines, compressing changeover times from hours to minutes while forcing incumbent hardware suppliers to reposition around software value.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE conformity requirements for robotic packaging cells are accelerating replacement cycles among European contract packers upgrading pre-2010 installations.
- Delta robot cycle speeds:Lightweight parallel kinematics exceeding 200 picks per minute in confectionery primary packaging are displacing pneumatic pick-place systems in high-volume snack operations.
- German automotive spillover:Precision articulation expertise developed for powertrain assembly is repurposing into consumer electronics tray-loading applications with sub-millimeter repeatability demands.
Market Restraints
- Servo motor supply concentration:Rare-earth magnet dependency on Chinese rare-earth processing creates input cost volatility for articulated arm actuators.
- ISO 10218-2 integration complexity:Safety-rated monitored stop and speed separation requirements extend deployment timelines for collaborative robot retrofits in legacy filling environments.
- Fixed automation residual value:Depreciated hard-automation assets in mature food plants delay capital release for flexible robotic replacement.
Strategic Opportunities
- Personal care small-batch flexibility:Collaborative robots without cage enclosures are penetrating mid-size cosmetics manufacturers in Italy and Spain previously excluded from automation by volume minimums.
- Pharmaceutical serialization convergence:Integration of track-and-trace hardware with adaptive gripper systems creates bundled validation pathways under FDA 21 CFR Part 11.
- South Korean supplier assembly expansion:European production footprint by Seoul-based automation vendors is circumventing tariff exposure and shortening lead times for continental pharmaceutical OEMs.
Industry Challenges
- Robot programmer scarcity:Shortage of PLC and safety-certified integrators extends commissioning timelines for multi-cell pharmaceutical deployments.
- IEC 62443 cybersecurity retrofit:Connected packaging line architecture requires segmented network redesign that conflicts with legacy flat Ethernet topologies in brownfield food plants.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Packaging Machines Market Trends and Innovations
Adaptive gripper technology combined with machine vision is collapsing the tradeoff between packaging flexibility and throughput that previously forced manufacturers into dedicated hard-automation lanes.
Digital twin environments for robotic cell commissioning are virtualizing physical prototyping requirements. Pharmaceutical packers in Switzerland and Germany are deploying Siemens and Dassault platforms to simulate blister-format changeovers before floor installation, compressing validation documentation from months to weeks. The technology is virtualizing traditional FAT/SAT protocols into software-based acceptance criteria.
EU AI Act risk classification for autonomous packaging systems is mandating conformity assessments for vision-guided quality inspection modules. High-risk categorization of pharmaceutical defect detection is forcing robot OEMs to embed logging and traceability features that exceed current ISO 10218 documentation requirements. German notified bodies are developing sector-specific guidance for adaptive robotics in GMP environments.
Contract packers are unbundling after-sales service from capital equipment procurement, preferring outcome-based uptime guarantees over traditional warranty structures. This shift pressures ABB, FANUC, and KUKA to restructure service organizations around availability metrics rather than spare parts revenue. The model is most visible in Benelux pharmaceutical contract packaging, where CDMOs prioritize OEE commitments over initial capex minimization.
Robotic Packaging Machines Market Segmentation
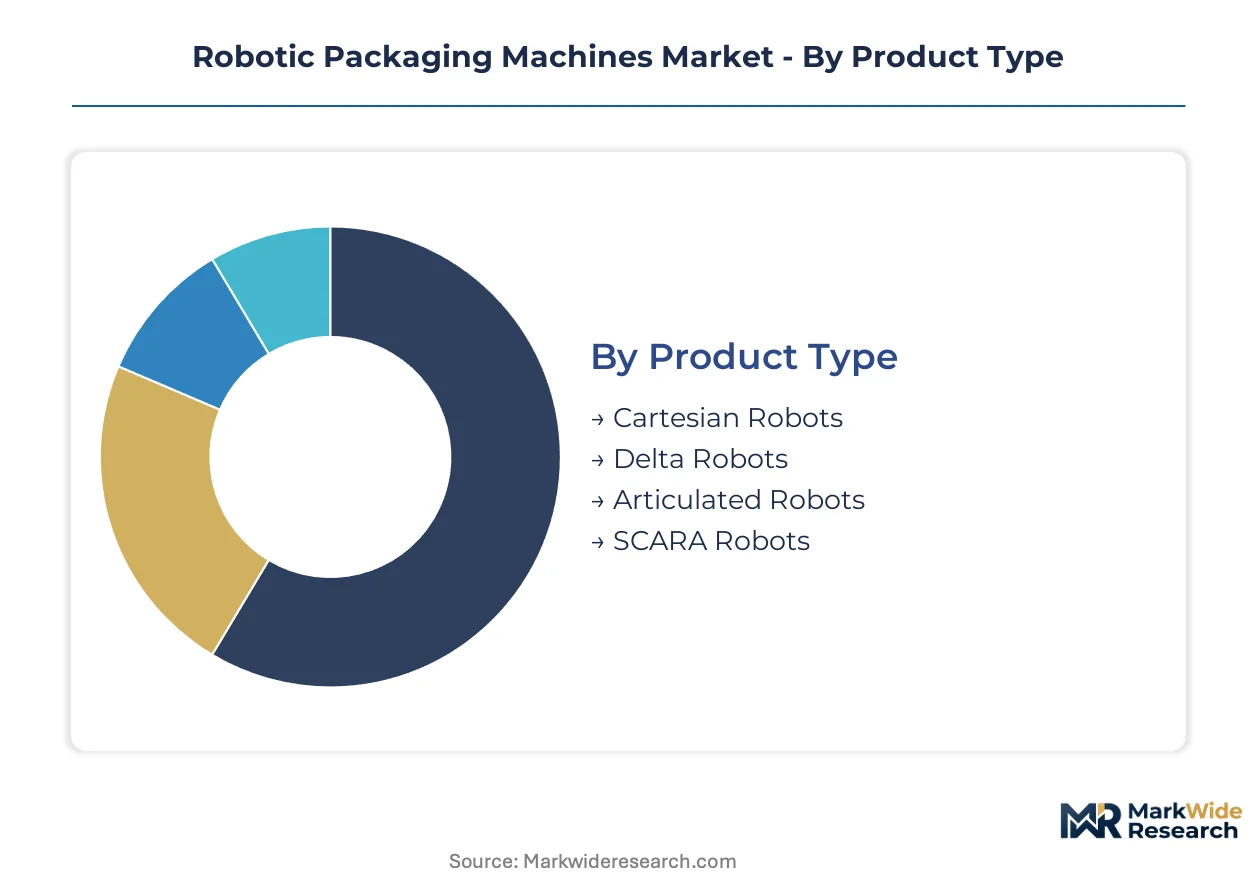
Segmentation in robotic packaging machines exposes how technical specifications, safety architectures, and end-use throughput requirements fragment procurement patterns across European automation buyers. Understanding these divides clarifies why delta robots dominate confectionery while collaborative systems penetrate cosmetics, and why pharmaceutical validation protocols create technology lock-in effects that reshape competitive positioning.
Product Type:
Mature parallel kinematics coexist with emerging collaborative architectures as manufacturers balance cycle speed against flexibility requirements in retrofit environments.
- Cartesian Robots:Three-axis linear actuators deliver sub-millimeter positioning repeatability for case-packing and palletizing operations in high-volume beverage distribution centers. German dairy cooperatives specify these systems for 24-hour continuous palletizing where gantry spans exceed ten meters and payload consistency outweighs adaptive flexibility.
- Delta Robots:Lightweight parallel manipulators achieve cycle speeds exceeding 200 picks per minute through carbon-fiber arm construction and direct-drive rotary actuators. Swiss confectionery packers deploy delta configurations for primary pouch handling where overhead mounting preserves floor space and vacuum gripper arrays manage variable snack geometries without mechanical changeover.
- Articulated Robots:Six-axis serial kinematics derived from automotive powertrain assembly deliver the reach and payload capacity for mixed-SKU case packing in third-party logistics facilities.
- SCARA Robots:Selective compliance assembly robot arms provide planar precision for tray-loading and blister insertion tasks in pharmaceutical secondary packaging with compact footprint requirements.
Delta robots handle the majority of throughput in high-speed primary packaging; articulated systems are expanding most quickly into contract logistics where SKU variability demands adaptive reach envelopes.
Technology:
Cost tiering separates vision-augmented premium systems from entry-level sensor-integrated configurations as pharmaceutical OEMs prioritize validation documentation over capital expenditure minimization.
- Vision-Guided Robotics:Machine vision integration with adaptive gripper control enables format changeovers without mechanical tooling swaps, compressing pharmaceutical line reconfiguration from hours to minutes. German contract packers specify these systems for multi-client blister packaging where batch sizes below 10,000 units previously excluded automation economics.
- Collaborative Robots:Force-limited articulated arms with safety-rated monitored stop functionality operate without protective enclosures, enabling retrofit deployment in legacy personal care filling lines with constrained floor space. Italian mid-size cosmetics manufacturers adopt these systems to automate small-batch serum assembly without cage infrastructure that would disrupt existing cleanroom layouts.
- Automated Guided Vehicles:Mobile robotic platforms integrate with packaging line palletizers for autonomous finished goods transport to warehouse staging areas.
- Sensor-Integrated Robotics:Basic proximity and force-feedback systems provide collision avoidance and quality verification in cost-sensitive food packaging applications.
Vision-guided systems command premium positioning in pharmaceutical validation environments; collaborative robots are gaining share fastest among personal care manufacturers previously excluded by volume minimums.
Application:
Customer type fragmentation separates multinational manufacturers with captive engineering resources from contract packers purchasing automation as operational expenditure rather than capital investment.
- Food & Beverage:High-throughput primary and secondary packaging operations with hygiene-rated stainless steel construction and washdown-compatible actuator sealing. Dutch dairy processors specify IP69K-rated delta robots for cheese portioning where caustic cleaning cycles demand corrosion-resistant kinematic chains.
- Pharmaceuticals:GMP-validated packaging lines with 21 CFR Part 11 documentation requirements, serialized track-and-trace integration, and isolator-compatible robot mounting. Swiss sterile fill-finish facilities deploy SCARA systems inside restricted access barrier systems for vial handling where particulate generation controls exceed standard industrial specifications.
- Consumer Electronics:Precision tray-loading and retail packaging with electrostatic discharge protection and sub-millimeter placement accuracy for fragile components.
- Personal Care:Flexible batch production with rapid format changeover for cosmetics, fragrances, and skincare products in glass and flexible primary packaging.
Food and beverage applications absorb the largest installed base; pharmaceutical deployments are climbing the fastest as serialization mandates and aseptic processing requirements accelerate replacement cycles.
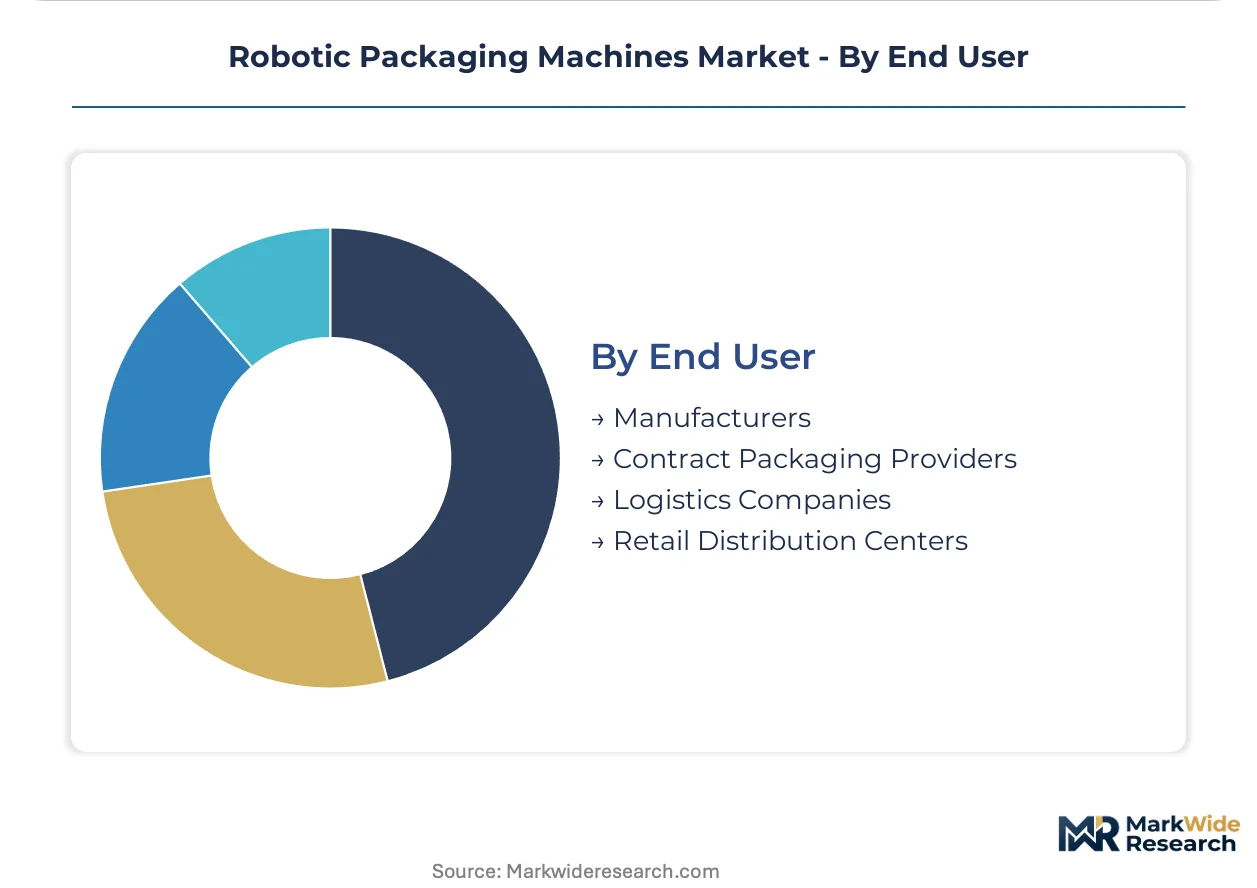
End User:
Supply concentration among German automotive-derived integrators shapes procurement patterns as contract packaging providers prioritize service network density over initial equipment cost.
- Manufacturers:Captive packaging operations with dedicated engineering staff, standardized controller platforms, and multi-site replication of validated cell configurations. German automotive suppliers extend powertrain assembly expertise into in-house electronics packaging with sub-millimeter repeatability specifications derived from precision manufacturing protocols.
- Contract Packaging Providers:Multi-client service operations with format flexibility requirements, compressed changeover windows, and outcome-based uptime contracting. Benelux pharmaceutical CDMOs specify availability guarantees over capital expenditure minimization, restructuring vendor relationships around OEE commitments rather than traditional warranty structures.
- Logistics Companies:Third-party distribution operations with mixed-SKU case handling, seasonal volume spikes, and integration with warehouse management systems for order consolidation.
- Retail Distribution Centers:E-commerce fulfillment operations with polybag packaging, variable carton sizing, and direct-to-consumer shipment preparation.
Manufacturers retain the deepest installed base with standardized controller ecosystems; contract packaging providers are expanding fastest as unbundled service models and outcome-based contracting reshape vendor selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation supply concentrates most densely in Germany, where automotive-derived precision engineering feeds directly into packaging robotics manufacturing. This concentration shapes procurement patterns across Europe and establishes technical standards that diffuse into adjacent markets.
Germany
Pharmaceutical contract packers in Baden-Württemberg and Bavaria drive demand for validated SCARA and delta configurations with 21 CFR Part 11 documentation. The EU Machinery Directive's CE conformity requirements accelerate replacement cycles among pre-2010 installations. Stuttgart's automation cluster anchors ABB and KUKA engineering centers where automotive articulation expertise repurposes into consumer electronics tray-loading cells.
Switzerland
Swiss sterile fill-finish facilities deploy isolator-compatible robotics for vial handling where particulate generation controls exceed standard industrial specifications. Swissmedic's GMP enforcement shapes validation protocols that pharmaceutical OEMs replicate globally. Basel's pharmaceutical corridor concentrates CDMOs specifying availability guarantees over capital expenditure minimization.
United States
FDA 21 CFR Part 11 compliance requirements shape pharmaceutical packaging robot validation protocols, forcing track-and-trace hardware integration with adaptive gripper systems. The FDA's serialization mandates accelerate replacement cycles in contract packaging facilities. New Jersey's pharmaceutical corridor and Boston's biotech cluster concentrate demand for vision-guided robotics with sub-millimeter placement accuracy.
China
Domestic rare-earth processing dominance creates servo motor supply leverage that influences articulated arm actuator costs globally. SAMR's machinery safety standards and GB certification requirements tighten compliance for European and Japanese OEMs operating locally. Shanghai's Yangtze River Delta automation corridor hosts expanding assembly capacity by South Korean suppliers circumventing tariff exposure.
South Korea
Seoul-based automation vendors expand European production footprints to shorten lead times for continental pharmaceutical OEMs. MFDS pharmaceutical equipment regulations align with EU standards, facilitating export market access. Busan-Ulsan's industrial automation cluster feeds precision motion control components into packaging robotics supply chains serving Southeast Asian contract manufacturers.
Robotic Packaging Machines Market Competitive Landscape
Swiss-German precision engineering specialists and Japanese controller standardization leaders split the market into technology-tiered competitive bands. The vendor base organizes around three strategic archetypes: motion-control software stack providers, dense service network operators, and automotive-derived articulation precision repurposers. Consolidation pressure intensifies as contract packers unbundle after-sales service from capital equipment procurement, forcing restructuring around availability metrics. Geographic expansion through European assembly capacity and outcome-based uptime contracting represent the dominant competitive vectors.
Within the precision-engineering tier, ABB leverages its motion-control software stack to sustain premium positioning in high-speed pharmaceutical lines. FANUC anchors Japanese supply through its dense service network and controller standardization across food packaging plants. KUKA competes on automotive-derived articulation precision repurposed for consumer electronics tray-loading cells.
| Leading Market Players |
|---|
| ABB |
| FANUC |
| KUKA |
| Yaskawa Electric |
| Omron |
| Siemens |
| Rockwell Automation |
| Syntegon |
| Gerhard Schubert |
| Others |
Pricing and Supply Chain Analysis
Rare-earth magnet dependency on Chinese rare-earth processing creates input cost volatility that compresses margins on articulated arm actuators while simultaneously forcing European OEMs to diversify servo motor sourcing across South Korean and Japanese suppliers. This single-source vulnerability widens pricing spreads between premium validated systems and economy-tier alternatives as procurement teams balance qualification costs against tariff exposure.
Pricing Analysis
EU Machinery Directive CE conformity dictates the pricing tier structure across European robotic packaging deployments. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-validated SCARA systems with full 21 CFR Part 11 documentation from food-grade delta configurations and entry-level Cartesian palletizers. Price differentiation stems from certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because South Korean suppliers are circumventing tariff exposure through European assembly expansion. Contract packaging providers in Benelux exhibit the least price sensitivity as they prioritize OEE commitments over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for servo motor procurement. Manufacturing concentrates in China, Germany, and South Korea. Rare-earth magnet processing, carbon-fiber arm construction, and direct-drive rotary actuators draw from concentrated upstream sources. Single-source vulnerability in rare-earth magnet supply creates procurement fragility. Distribution runs through authorized integrator networks with dense service footprints in Stuttgart, Basel, and Milan industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controller platform standardization is reconfiguring this market around software-ecosystem economics, where interoperability between robot OEMs and PLC vendors determines procurement decisions more than hardware specifications alone.
For Market Incumbents: Pre-empt South Korean supplier expansion by embedding motion-control software stacks deeper into pharmaceutical validation workflows. Secure backward integration into safety-rated sensor production to offset servo motor cost volatility. Defend against collaborative robot commoditization by restructuring service organizations around availability metrics rather than spare parts revenue. For New Entrants and Emerging Players: Establish a beachhead in Italian and Spanish personal care manufacturing where collaborative robot retrofits remain underpenetrated. Target mid-size cosmetics producers previously excluded from automation by volume minimums. Lead with force-limited arm deployments that circumvent cage infrastructure requirements in legacy cleanroom layouts. For Investors and Strategic Acquirers: EU AI Act risk classification for autonomous packaging systems reshapes the acquisition landscape toward vision-guided robotics with embedded logging and traceability. Long-term viability centers on software-defined flexibility rather than mechanical precision. Prioritize targets with validated pharmaceutical deployments and dense service network footprints. Monitor IEC 62443 cybersecurity adoption rates in brownfield food plants as the inflection signal for connected packaging line retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Safety-Rated Sensors | Reduces servo motor supply concentration risk for articulated arm OEMs serving pharmaceutical validation environments. |
| European Assembly Footprint Expansion | South Korean suppliers circumvent tariff exposure while shortening lead times for continental pharmaceutical OEMs. |
| Outcome-Based Uptime Contracting | Restructures vendor relationships around OEE commitments in Benelux pharmaceutical contract packaging. |
| Digital Twin Platform Deployment | Siemens and Dassault environments compress pharmaceutical validation documentation from months to weeks. |
| Collaborative Robot Retrofit Certification | ISO 10218-2 compliance enables cage-free deployment in Italian mid-size cosmetics manufacturing. |
Research Methodology
A standing panel of packaging line engineers, pharmaceutical validation specialists, aftermarket service directors, and contract packaging procurement managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against EU Machinery Directive implementation guidance, FDA 21 CFR Part 11 enforcement patterns, ISO 10218 safety standard revisions, and customs data on servo motor trade flows. Bottom-up unit economics triangulated against top-down industry spend estimates.
Scenario-bracketing framed demand projections across the analysis window. Segmentation dimensions modeled include robot kinematic architecture, technology tier, end-use application, and customer type. CAGRs were derived from installed base turnover rates and replacement cycle compression under regulatory compliance mandates. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate timelines and collaborative robot safety standard adoption curves.
Stress conditions across rare-earth supply disruption, tariff regime shifts, and cybersecurity retrofit compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.