
 Europe Packaging Automation Market | 2026-2036
Europe Packaging Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Packaging Automation Market Foresight
Recyclable mono-material films is hardening as the dominant substrate specification across European packaging lines, displacing multi-layer laminates that complicate mechanical sorting. ABB Ltd. leverages its robotics portfolio to dominate high-speed palletizing cells for food processors. Robert Bosch GmbH sustains technology leadership in precision dosing systems for pharmaceutical blister lines. Multivac Group anchors its position through deep specialization in thermoforming equipment for modified-atmosphere packaging.
Europe packaging automation encompasses integrated electromechanical systems that execute filling, sealing, labeling, and material handling operations at throughput rates exceeding 600 units per minute, governed by IEC 60204-1 safety standards and EU Machinery Directive 2006/42/EC compliance requirements. Robotic systems capture the largest installed base across pharmaceutical and food production facilities, while machine vision segments expand fastest as inline inspection mandates tighten under EU MDR and Falsified Medicines Directive traceability rules. IoT solutions concentrate margin pools in predictive maintenance contracts, though AI-driven analytics remains nascent outside tier-one consumer goods manufacturers.
CE marking under the EU Machinery Directive governs market access for all automated packaging equipment sold within the European Economic Area, while REACH compliance constrains adhesive and coating chemistries used in labeling and sealing subsystems. The EU Green Deal's packaging and packaging waste regulation revisions are forcing equipment retrofits to handle thinner-gauge recyclable substrates. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous quality-inspection algorithms before committing to multi-year capital deployment cycles.
Market Dynamics
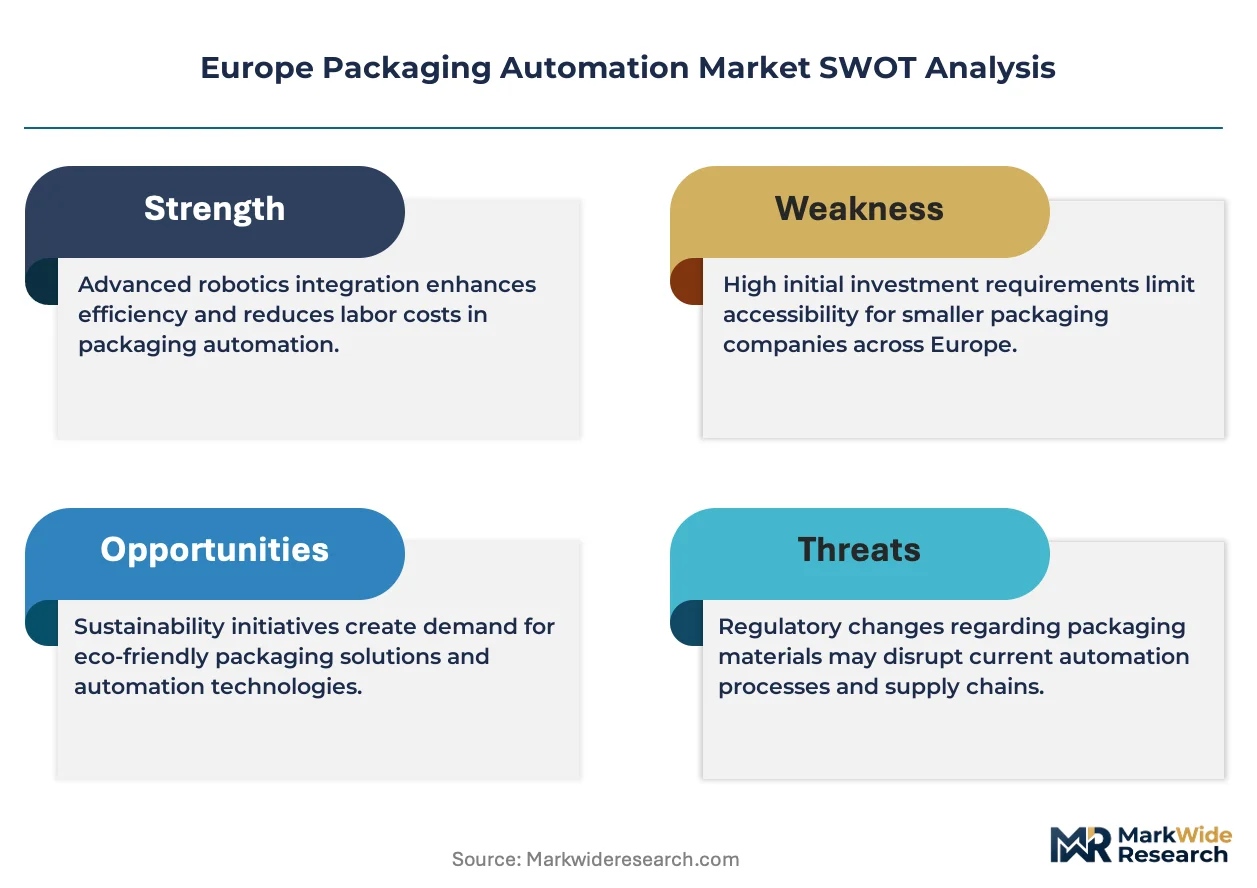
The EU Green Deal's packaging waste regulation revisions are forcing equipment retrofits across European production facilities, compressing capital deployment cycles as manufacturers race to handle thinner-gauge recyclable substrates before compliance deadlines.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization mandates across pharmaceutical packaging lines are accelerating automated track-and-trace system installations in Germany and France.
- Mono-material film specifications:Recyclable substrate requirements under the EU Green Deal are driving replacement demand for legacy multi-layer laminate handling equipment.
- Stuttgart-Munich industrial corridor:Concentrated food and pharmaceutical production clusters in southern Germany are generating sustained demand for high-throughput palletizing and thermoforming automation.
Market Restraints
- CE marking complexity:EU Machinery Directive 2006/42/EC compliance timelines and notified body bottlenecks are extending equipment validation cycles by four to eight months.
- Specialized component supply:Precision servo motors and machine vision sensors concentrate among a limited supplier base in Germany and Switzerland, creating input vulnerability.
- Thin-gauge substrate handling:Mechanical stress limitations in existing sealing and forming equipment constrain processing speeds for new recyclable film specifications below 40 microns.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated contract packaging sectors in Central Europe present first-mover advantages for integrated line automation vendors.
- AI Act risk classification:Early alignment of autonomous quality-inspection algorithms with EU AI Act requirements creates differentiation ahead of enforcement.
- Predictive maintenance contracts:IoT-enabled service models are capturing margin pools previously lost to third-party maintenance providers.
Industry Challenges
- Mechatronics engineering shortage:The gap between IEC 60204-1 safety certification requirements and available qualified automation engineers is delaying commissioning timelines.
- Legacy system integration:Retrofitting Industry 4.0 connectivity into existing packaging lines without disrupting 600+ units-per-minute throughput creates architectural complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Packaging Automation Market |
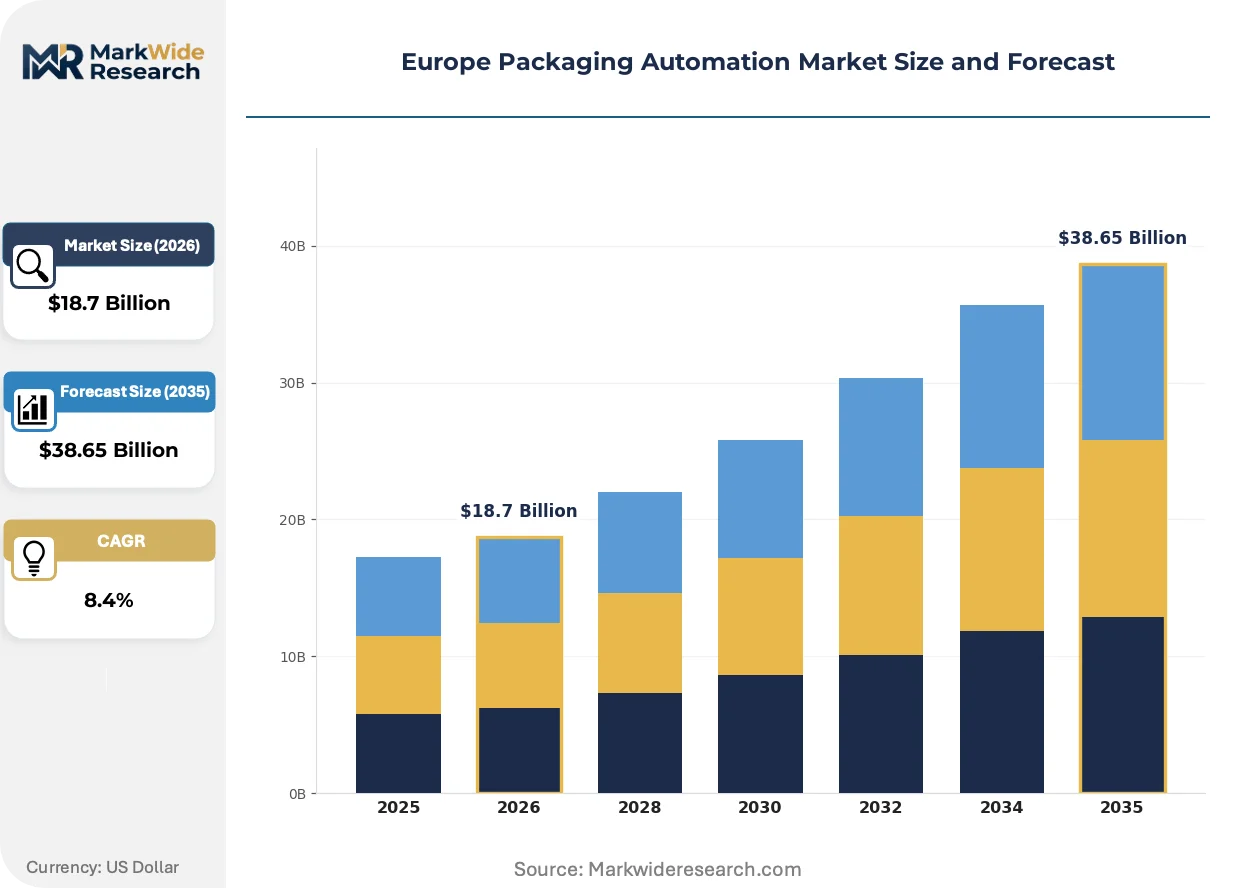
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Labeling Machines, Filling Equipment, Inspection Systems Technology: Automated Guided Vehicles, Machine Vision, IoT Solutions, AI-driven Analytics End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Application: Cartoning, Wrapping, Palletizing, Stretch Film Packaging |
| Companies Covered | DESTACO, ABB Ltd., JLS Automation, Multivac Group, Robert Bosch GmbH, Mitsubishi Electric Corporation, Swisslog Holding AG, Kollmorgen Corporation, Rockwell Automation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Packaging Automation Market Shifts & Advancements
Machine vision systems are embedding directly into packaging line control architectures, shifting quality inspection from batch sampling to 100% inline verification while compressing the feedback loop between detection and rejection mechanisms.
Collaborative robotics is integrating force-limited articulated arms into secondary packaging operations previously reserved for fixed automation, enabling mid-volume food processors in Spain and Italy to reconfigure lines for seasonal SKU rotations without mechanical changeover downtime, which is compressing the total cost of ownership justification threshold for robotic cells.
REACH compliance constraints on adhesive chemistries are forcing reformulation of hot-melt and pressure-sensitive labeling subsystems, with ECHA substance restriction proposals targeting phthalate plasticizers and certain epoxy curing agents driving equipment suppliers to validate alternative coating delivery mechanisms before 2026 regulatory deadlines, most acutely affecting pharmaceutical blister and vial labeling lines.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier consumer goods manufacturers, with Italian and French packaging cooperatives now leasing integrated filling-sealing-labeling cells bundled with remote monitoring and spare parts inclusion, concentrating vendor risk on uptime guarantees rather than hardware margins.
Europe Packaging Automation Market Segmentation
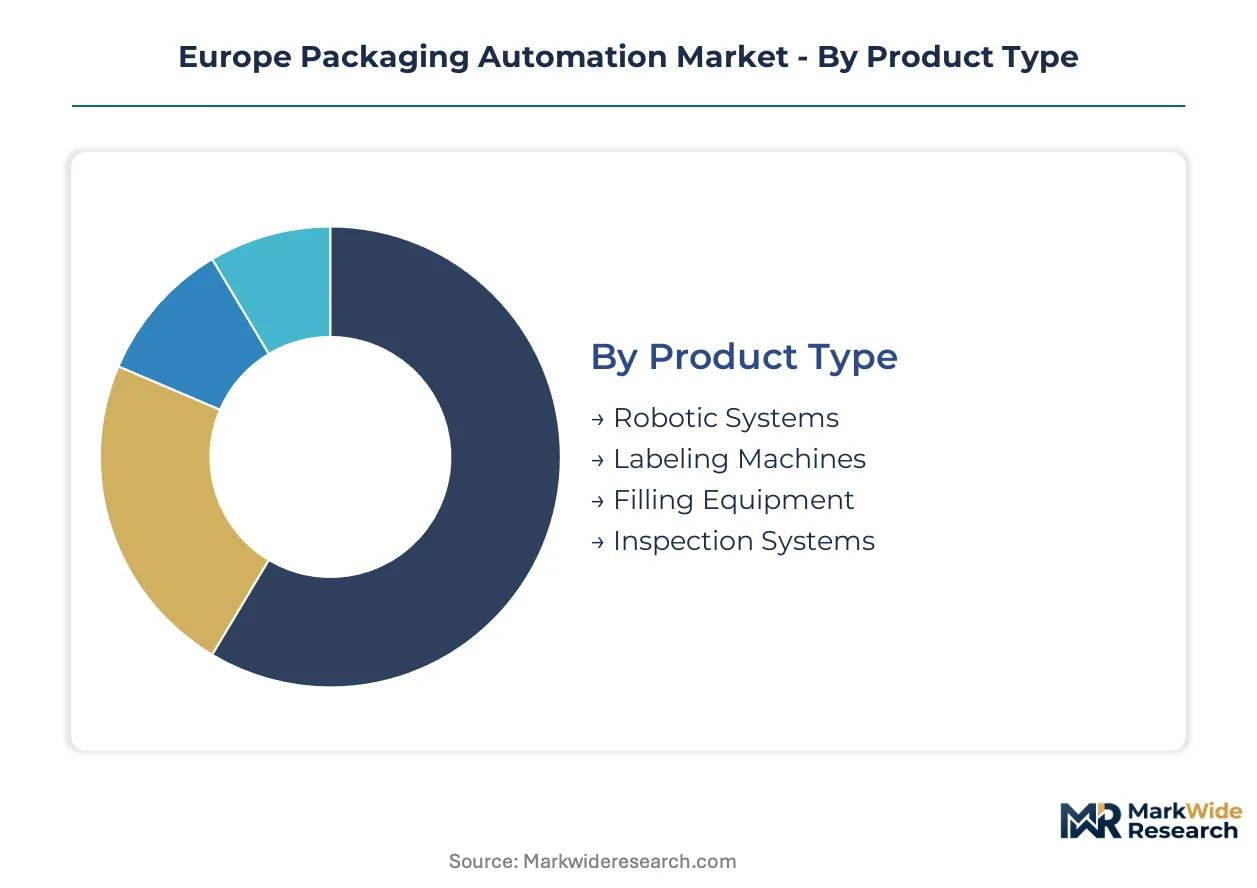
Packaging automation purchasing decisions in Europe hinge on throughput requirements, regulatory compliance burdens, and substrate compatibility. Segmentation reveals where capital deployment concentrates and which technology layers command premium pricing.
Product Type:
Capital intensity varies sharply across equipment categories, with multi-axis robotic cells demanding the highest upfront investment.
- Robotic Systems:Six-axis articulated arms and delta robots execute pick-and-place, palletizing, and case packing at speeds exceeding 150 cycles per minute. Pharmaceutical manufacturers in Germany's Stuttgart-Munich corridor deploy these for serialization-compliant handling under EU Falsified Medicines Directive mandates.
- Labeling Machines:Pressure-sensitive and shrink-sleeve applicators integrate inline printing for variable data serialization. Food processors across Spain and Italy prioritize modular units that accommodate seasonal SKU rotations without mechanical changeover.
- Filling Equipment:Volumetric and gravimetric fillers handle liquid, powder, and viscous products with precision dosing requirements.
- Inspection Systems:Checkweighers, metal detectors, and leak testers enforce quality gates before secondary packaging.
Robotic systems absorb the bulk of installed capacity; inspection systems are expanding most quickly under tightening EU MDR traceability rules.
Technology:
Integration complexity distinguishes technology tiers, with AI-driven platforms requiring specialized engineering resources scarce across European automation firms.
- Automated Guided Vehicles:Laser-guided and vision-navigated AGVs transport raw materials and finished goods within production facilities. German automotive suppliers have pioneered fleet management systems that synchronize with ERP platforms.
- Machine Vision:2D and 3D camera systems perform defect detection, OCR verification, and dimensional compliance at line speeds. Pharmaceutical blister lines under EMA serialization mandates drive adoption for 100% inline verification.
- IoT Solutions:Sensor networks enable predictive maintenance and OEE monitoring through cloud-connected PLCs.
- AI-driven Analytics:Deep learning algorithms optimize line balancing and quality prediction, currently concentrated among tier-one consumer goods manufacturers.
Machine vision claims the largest installed base; AI-driven analytics is climbing the fastest despite skills constraints.
End User:
Regulatory exposure shapes automation investment urgency, with pharmaceutical and food sectors facing the most stringent compliance deadlines.
- Food & Beverage:High-throughput lines for dairy, meat, and beverage packaging prioritize washdown-compatible stainless steel construction. Modified-atmosphere packaging for fresh proteins drives thermoforming automation demand.
- Pharmaceuticals:Blister packaging, vial filling, and serialization-track-and-trace systems dominate capital allocation. EU Falsified Medicines Directive compliance has accelerated automated line installations across France and Germany.
- Personal Care:Cosmetic and hygiene product lines emphasize flexible format changeover for diverse SKU portfolios.
- Electronics:ESD-protected handling and precision placement for consumer devices require specialized end-effectors.
Food & beverage holds the deepest installed base; pharmaceuticals is gaining share fastest on serialization mandates.
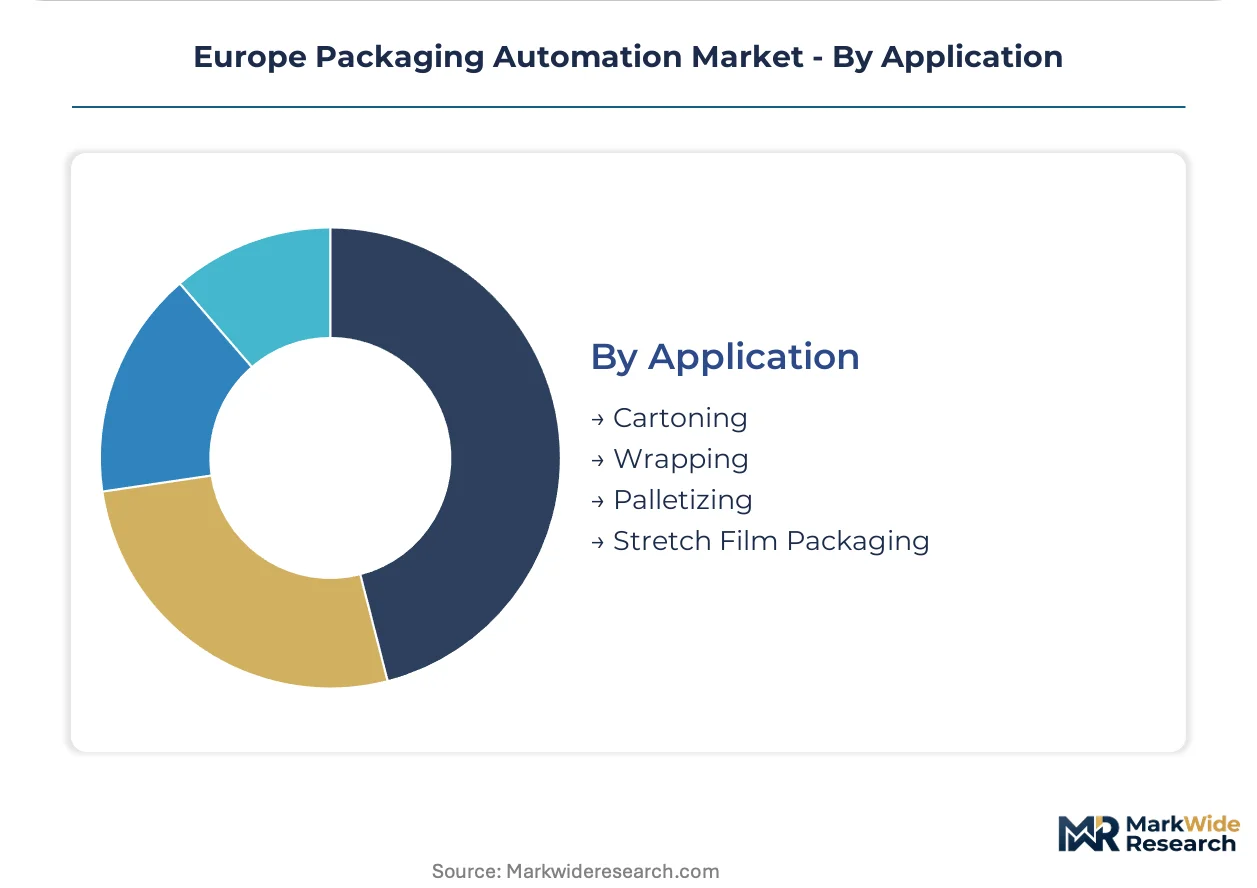
Application:
Throughput velocity and labor substitution potential determine automation priority within packaging workflows.
- Cartoning:Horizontal and vertical cartoners erect, load, and close paperboard containers. Pharmaceutical secondary packaging lines under EU MDR requirements prioritize serialization-ready cartoning with tamper-evident closure verification.
- Palletizing:Robotic and conventional palletizers stack unit loads for warehouse distribution. The Stuttgart-Munich industrial corridor sustains concentrated demand from food and beverage producers.
- Wrapping:Flow-wrapping and overwrapping systems handle individual and multi-pack configurations.
- Stretch Film Packaging:Orbital and turntable wrappers secure palletized loads for transit stability.
Palletizing absorbs the bulk of robotic deployment; cartoning is expanding most quickly on pharmaceutical serialization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrie 4.0 tax incentives and Poland's Special Economic Zones are concentrating automation investment across Central European manufacturing corridors. National regulatory frameworks and industrial clustering patterns create distinct deployment environments.
Germany
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are accelerating track-and-trace system installations across Baden-Württemberg and Bavaria. EMA compliance deadlines compress capital deployment cycles for blister packaging lines. The Stuttgart-Munich industrial corridor sustains concentrated demand for high-throughput palletizing and thermoforming equipment serving food and pharmaceutical producers.
France
Cosmetic and personal care manufacturers in Île-de-France are retrofitting lines for recyclable mono-material film specifications under EU Green Deal packaging waste revisions. ANSM pharmaceutical traceability requirements align with broader EU serialization frameworks. The Lyon-Grenoble manufacturing belt hosts specialized automation engineering firms serving pharmaceutical secondary packaging applications.
Italy
Mid-tier food cooperatives in Emilia-Romagna are adopting equipment-as-a-service models for integrated filling-sealing-labeling cells. REACH compliance constraints on adhesive chemistries are forcing reformulation of labeling subsystems before ECHA substance restriction deadlines. The Parma packaging machinery cluster anchors national production of thermoforming equipment for modified-atmosphere protein packaging.
Poland
Underpenetrated contract packaging sectors in the Łódź Special Economic Zone present first-mover advantages for integrated line automation vendors. EU cohesion fund infrastructure investments are improving logistics connectivity for automated material handling deployments. The Warsaw-Katowice manufacturing axis is attracting German and Italian automation suppliers seeking lower-cost production bases.
Switzerland
Precision servo motor and machine vision sensor suppliers in the Zurich-Basel corridor concentrate critical component supply for European packaging lines. Swissmedic pharmaceutical quality requirements exceed baseline EU MDR standards, demanding higher-grade inspection automation. The Swiss automation engineering base supports pharmaceutical packaging deployments across adjacent German and French markets.
Europe Packaging Automation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade precision equipment commanding premium positioning against food-sector volume plays. The vendor base organizes into three tiers: diversified industrial conglomerates with robotics portfolios, dedicated packaging machinery specialists with deep format expertise, and regional system integrators serving mid-tier retrofit demand. Consolidation pressure is mounting as CE marking complexity and IEC 60204-1 safety certification requirements raise barriers for smaller fabricators. Strategic moves concentrate on technology licensing partnerships and predictive maintenance service model expansion.
Within the diversified industrial tier, ABB Ltd. and Mitsubishi Electric Corporation occupy positions anchored by broad robotics and motion control portfolios that extend into packaging line integration. Robert Bosch GmbH exemplifies the dedicated machinery specialist archetype, with precision dosing and pharmaceutical handling systems representing deep format-specific expertise. Multivac Group sits within the thermoforming equipment segment as a focused technology anchor for modified-atmosphere packaging applications. These three companies collectively illustrate how competitive positioning in European packaging automation depends on matching technology breadth against application depth.
| Leading Market Players |
|---|
| DESTACO |
| ABB Ltd. |
| JLS Automation |
| Multivac Group |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Swisslog Holding AG |
| Kollmorgen Corporation |
| Rockwell Automation |
| Others |
Supply & Pricing Matrix
Captive in-house production of precision servo motors and machine vision sensors by ABB Ltd. and Robert Bosch GmbH anchors supply security and pricing power for high-throughput pharmaceutical lines, insulating tier-one vendors from component volatility while compressing margins for equipment-as-a-service entrants dependent on external sourcing.
Pricing Analysis
Volume throughput separates premium pricing from commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking complexity and IEC 60204-1 safety certification grades. Cost compression in mid-tier robotic cells is intensifying because Italian and French packaging cooperatives now demand bundled remote monitoring and spare parts inclusion. Mid-tier food processors exhibit highest price sensitivity; pharmaceutical manufacturers under EU Falsified Medicines Directive deadlines show lowest.
Supply Chain Analysis
CE marking and IEC 60204-1 safety certification gate access to the European Economic Area, filtering supplier participation. Precision servo motors and machine vision sensors concentrate in Germany and Switzerland. Raw material dependencies span specialty steel for washdown-compatible construction, optical-grade glass for vision sensors, and high-performance polymers for sealing subsystems. Single-source vulnerability runs through Swiss sensor suppliers for pharmaceutical-grade inspection systems. Distribution runs through direct OEM sales for large installations and regional system integrators for retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified mechatronics engineers capable of IEC 60204-1 safety certification represent the binding capacity constraint, propping pricing power for vendors with captive training pipelines and extending commissioning timelines for competitors.
For Market Incumbents: Anticipate consolidation pressure from CE marking complexity and notified body bottlenecks by deepening backward integration into precision motion control components and expanding predictive maintenance service contracts to capture recurring revenue streams previously lost to third-party providers. For New Entrants and Emerging Players: Capture first-mover positioning in Poland's Łódź Special Economic Zone and Czech contract packaging sectors where integrated line automation penetration remains shallow. Equipment-as-a-service leasing models with uptime guarantees offer the most penetrable go-to-market angle for capital-constrained mid-tier cooperatives. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking robotics portfolio extension. Five-to-ten-year viability favors dedicated packaging machinery specialists with deep format expertise in pharmaceutical handling or thermoforming applications. Watch ECHA substance restriction timelines for adhesive chemistries as inflection indicators for labeling subsystem replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Expansion | Captures margin pools from third-party providers through IoT-enabled uptime guarantees. |
| AI Act Compliance Investment | Creates differentiation for autonomous quality-inspection algorithms ahead of enforcement. |
| Central European Geographic Expansion | Establishes production footprint in Poland's SEZs to serve underpenetrated contract packaging. |
| Mono-material Film Handling Retrofit | Addresses EU Green Deal packaging waste regulation revisions before compliance deadlines. |
| Serialization Track-and-Trace Integration | Aligns with EU Falsified Medicines Directive mandates across German pharmaceutical corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers. Primary fieldwork validated against CE marking databases, ECHA substance restriction proposals, EU cohesion fund infrastructure disclosures, and machinery import statistics. Bottom-up equipment unit economics reconciled with top-down industrial production indices.
Reconciliation of customs import volumes, production capacity registrations, and capital expenditure disclosures shaped the analytical framework across the projection horizon. Segmentation dimensions spanned product type, technology layer, end-user industry, and application workflow. CAGRs derived from equipment replacement cycles, regulatory compliance deadlines, and substrate transition timelines. Mono-material film adoption curves and serialization mandate enforcement schedules provided industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA adhesive chemistry restrictions, EU AI Act enforcement timing, and mechatronics engineering supply expansion. Forecasts reflect assumptions about regulatory adherence, technology substitution rates, and capital availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market