
 North America Contract Packaging Market | 2026-2036
North America Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Contract Packaging Market Analytics
Flexible film substrates are shifting from multi-layer laminates toward mono-material polyethylene structures that simplify mechanical recycling streams. Pharma Tech Industries leverages automated blister packaging lines to serve generic drug manufacturers with high-volume serialization compliance. Aaron Thomas Company anchors its position through food-grade pouch filling and retort capabilities for shelf-stable protein brands. Reed Lane differentiates via kit assembly and secondary packaging for clinical trial materials.
Contract packaging encompasses outsourced primary and secondary packaging execution performed on behalf of brand owners, typically involving automated filling, sealing, labeling, and cartoning operations with throughput rates exceeding 200 units per minute for high-speed beverage lines. The practice enables consumer packaged goods companies to convert fixed packaging asset costs into variable expenses while accessing specialized equipment for seasonal demand surges. Pharmaceutical applications command premium margin pools due to cGMP validation requirements and track-and-trace infrastructure investments. Pouch formats across food and cosmetics represent the fastest-growing packaging type as brands pursue source reduction goals and e-commerce-ready durability.
FDA cGMP regulations and the Drug Supply Chain Security Act mandate unit-level traceability infrastructure that elevates capital barriers for in-house pharmaceutical packaging. EPA sustainable materials management frameworks and state-level extended producer responsibility laws in California and New York push brand owners toward recyclable mono-material structures that contract packagers must qualify on existing lines. Stakeholders should monitor how state recycling policy fragmentation affects equipment standardization decisions across multi-site co-packing networks.
Market Dynamics
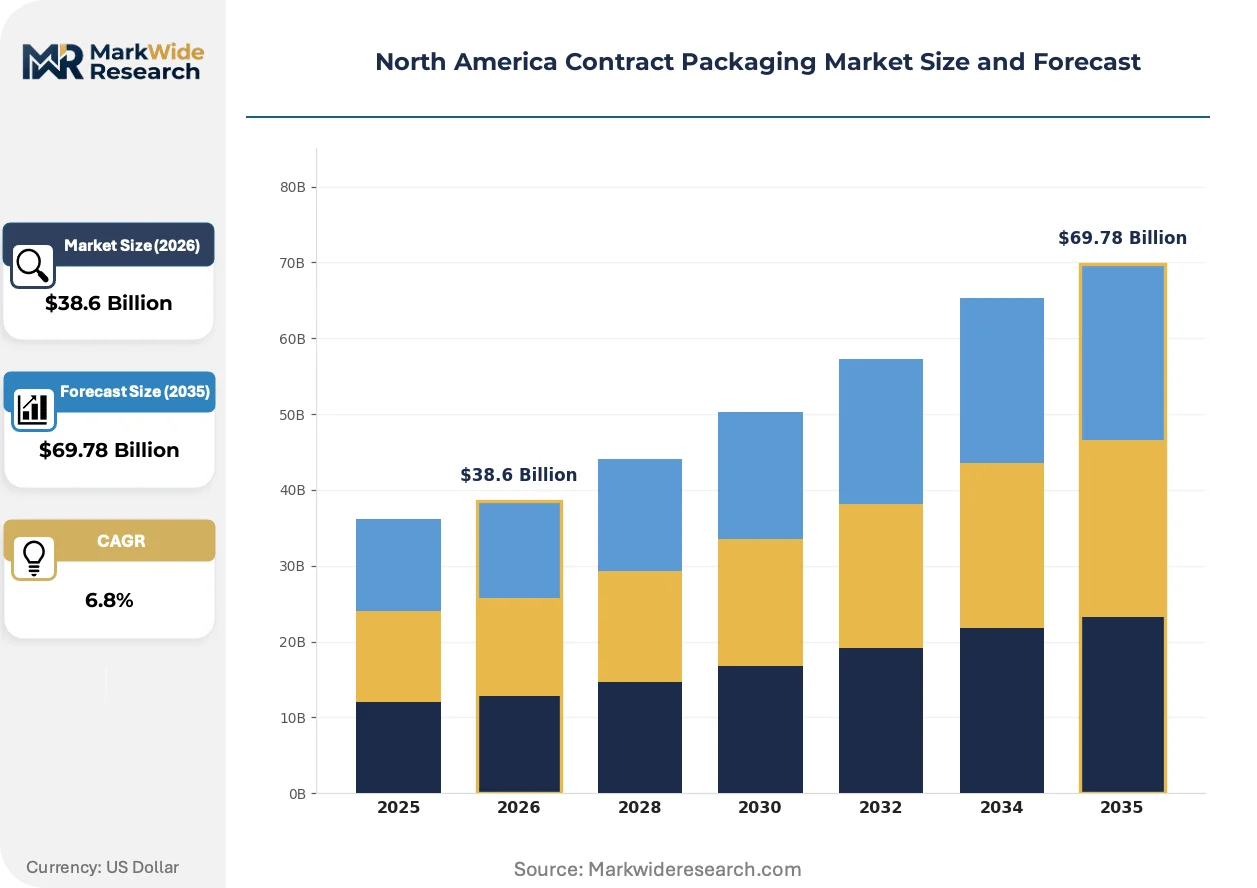
Mono-material polyethylene films are overtaking multi-layer laminates across North American contract packaging, forcing co-packers to requalify sealing parameters and line speeds for simplified recycling streams.
Growth Catalysts
- Drug Supply Chain Security Act serialization mandates:Pharmaceutical manufacturers outsource unit-level track-and-trace infrastructure to avoid capital-intensive line upgrades. FDA compliance deadlines compress in-house implementation timelines.
- Midwest industrial corridor concentration:Illinois, Ohio, and Wisconsin host dense co-packing clusters that enable just-in-time fulfillment networks for CPG brands with seasonal demand spikes.
- Retort pouch adoption for shelf-stable proteins:Food brands replace metal cans with flexible formats to reduce freight costs and retail shelf space requirements.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs fluctuate with Gulf Coast petrochemical capacity, squeezing margin predictability for fixed-price contract terms.
- Equipment standardization friction:California and New York extended producer responsibility laws impose conflicting mono-material specifications that complicate multi-site network harmonization.
- Qualified technician scarcity:Automated packaging lines require mechatronics specialists with FDA cGMP exposure, a skill set concentrated near legacy pharmaceutical manufacturing hubs.
Strategic Opportunities
- Canadian cannabis packaging specialization:Health Canada child-resistant and tamper-evident requirements create premium service tiers for licensed producers seeking export-ready compliance.
- Clinical trial kit assembly expansion:Biopharma outsourcing of patient-specific medication bundles demands cold-chain-validated secondary packaging with variable data printing.
- Direct-to-consumer e-commerce formats:Durable ship-ready pouch designs with reduced void fill replace traditional retail-focused case packing for digitally native brands.
Industry Challenges
- cGMP validation timeline compression:Pharmaceutical clients demand 12-week qualification windows that strain documentation and change-control protocols.
- Legacy MES integration complexity:New serialization equipment must handshake with 15-year-old manufacturing execution systems without disrupting batch records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Contract Packaging Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Filling, Sealing, Labeling, Cartoning Product Type: Food, Beverages, Pharmaceuticals, Cosmetics End User: Retailers, Manufacturers, Distributors, E-Commerce Packaging Type: Bottles, Pouches, Boxes, Blisters |
| Companies Covered | Pharma Tech Industries, Reed Lane, Aaron Thomas Company, Stamar Packaging, AmeriPac, Sharp Packaging Services, Unicep Packaging, Jones Healthcare Group, Multipack Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Contract Packaging Market Evolving Landscape
Digital printing and smart packaging interfaces are collapsing minimum order quantities and enabling mass customization across North American contract packaging operations.
Digital inkjet printing is overtaking flexographic methods for short-run SKU proliferation in personal care and nutraceutical segments. Brands with 500-unit test markets now demand photographic-quality labels without plate costs. This technology is compressing the economics of versioning and regionalized packaging.
EPA sustainable materials management frameworks and state-level extended producer responsibility statutes in California and New York mandate recyclable mono-material structures. Co-packers must revalidate heat-seal profiles and barrier performance without adhesive layers. Pharmaceutical and food segments face the steepest reformulation timelines.
Brand procurement teams now bundle primary packaging, secondary assembly, and fulfillment logistics under single-source agreements. Traditional tiered vendor structures with separate converters, co-packers, and 3PLs consolidate. This pattern concentrates in Midwest CPG corridors where integrated campuses reduce freight miles between operations.
North America Contract Packaging Market Segmentation
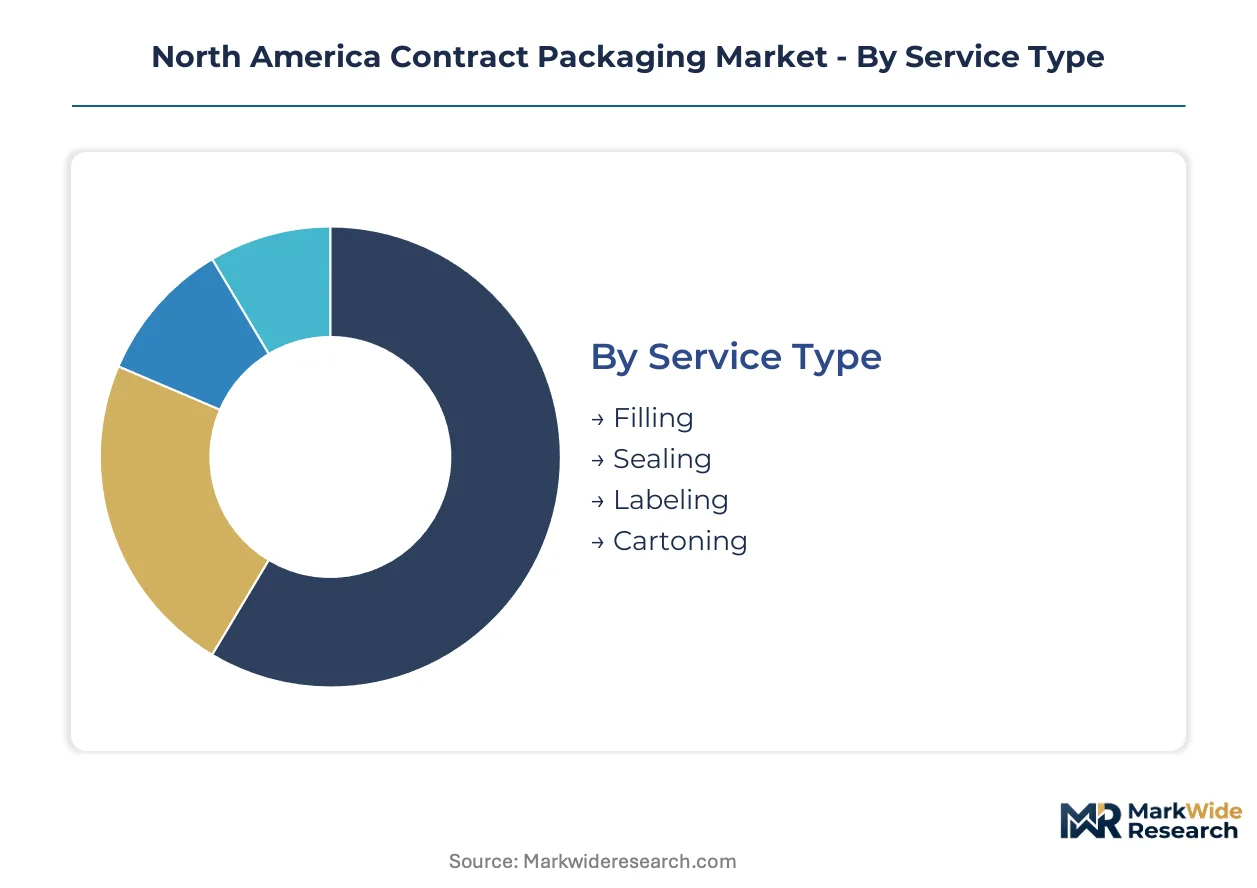
Contract packaging segmentation reveals how buyer priorities diverge across service capabilities, product categories, and fulfillment channels. Equipment specialization and regulatory compliance requirements create distinct margin tiers that reshape vendor selection criteria.
Service Type:
Capital intensity and line speed requirements drive procurement decisions across automated packaging services.
- Filling:Liquid and powder dosing systems handle throughput rates exceeding 200 units per minute for high-volume beverage contracts. Midwest co-packing clusters in Illinois and Wisconsin concentrate filling capacity for seasonal CPG demand surges.
- Sealing:Heat-seal and induction technologies must requalify parameters for mono-material polyethylene films under EPA sustainable materials management frameworks. Food-grade pouch applications command premium qualification timelines.
- Labeling:Digital inkjet methods displace flexographic printing for short-run SKU proliferation in personal care segments. Photographic-quality output eliminates plate costs for 500-unit test markets.
- Cartoning:Secondary packaging automation integrates with serialization infrastructure for pharmaceutical track-and-trace compliance. FDA cGMP validation requirements elevate technician skill barriers.
Volume sits with Filling; growth tilts toward Labeling.
Product Type:
Regulatory burden and margin structure differentiate procurement patterns across end-use verticals.
- Pharmaceuticals:cGMP validation and Drug Supply Chain Security Act serialization mandates create the highest barrier-to-entry segment. Unit-level track-and-trace infrastructure investments compress in-house implementation timelines.
- Food:Retort pouch adoption for shelf-stable proteins displaces metal can formats. Flexible substrates reduce freight costs and retail shelf space requirements for protein brands.
- Beverages:High-speed line economics favor dedicated filling campuses with seasonal surge capacity. Carbonated and non-carbonated formats require distinct carbonation and aseptic systems.
- Cosmetics:Short-run versioning and regionalized packaging demand digital printing compatibility. Mass customization capabilities attract digitally native brands with rapid test-market cycles.
Revenue concentrates in Pharmaceuticals; expansion accelerates fastest in Food.
End User:
Channel-specific fulfillment requirements reshape co-packer capability investments.
- Manufacturers:Brand owners outsource primary and secondary packaging to convert fixed asset costs into variable expenses. Just-in-time networks require Midwest corridor proximity.
- E-Commerce:Direct-to-consumer formats demand durable ship-ready pouch designs with reduced void fill. Durable packaging replaces traditional retail-focused case packing.
- Retailers:Private-label programs require rapid SKU turnaround and regionalized versioning capabilities. Digital printing compatibility enables store-brand proliferation.
- Distributors:Consolidated fulfillment operations bundle packaging with logistics under single-source agreements. Integrated campuses reduce freight miles between operations.
Contract value clusters with Manufacturers; channel mix shifts fastest toward E-Commerce.
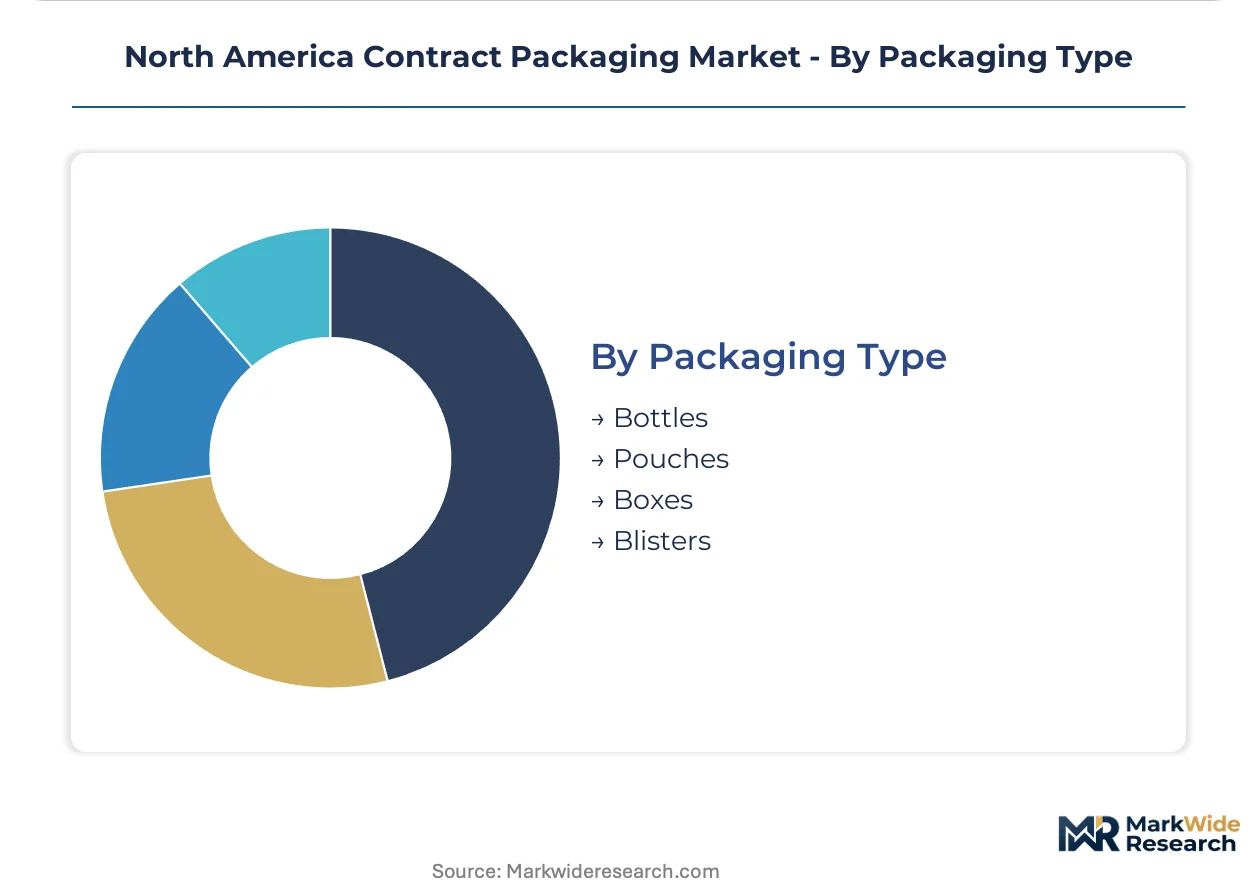
Packaging Type:
Material sustainability mandates and barrier performance requirements determine equipment requalification priorities.
- Pouches:Mono-material polyethylene structures simplify mechanical recycling streams while maintaining shelf stability. California and New York extended producer responsibility laws accelerate laminate displacement.
- Bottles:Rigid formats retain dominance in carbonated beverage and pharmaceutical liquid applications. Resin price volatility squeezes margin predictability for fixed-price contract terms.
- Blisters:Automated lines serve generic drug manufacturers with high-volume serialization compliance. Child-resistant and tamper-evident features address Health Canada requirements for export-ready cannabis packaging.
- Boxes:Secondary cartoning integrates with kit assembly for clinical trial materials. Variable data printing enables patient-specific medication bundles with cold-chain validation.
Installed base favors Bottles; sustainability tailwinds push Pouches to the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for contract packaging services concentrates in the United States Midwest industrial corridor, where co-packing clusters enable just-in-time fulfillment networks for CPG brands with seasonal demand spikes. Canada and Mexico present distinct regulatory-driven opportunities, while sub-regional specialization across all three countries shapes vendor selection criteria.
United States
Pharmaceutical serialization mandates and sustainable packaging transitions drive outsourcing intensity. FDA cGMP regulations and Drug Supply Chain Security Act compliance deadlines compress in-house implementation timelines. Illinois, Ohio, and Wisconsin host dense co-packing clusters serving food and personal care brands with automated pouch filling and retort capabilities.
Canada
Cannabis packaging specialization and export-oriented pharmaceutical compliance create premium service tiers. Health Canada child-resistant and tamper-evident requirements for licensed producers demand validated secondary packaging lines. Ontario and Quebec concentrate contract packaging capacity serving both domestic CPG brands and cross-border fulfillment operations.
Mexico
Nearshoring trends and USMCA trade integration position Mexican facilities for North American supply chain reconfiguration. COFEPRIS pharmaceutical regulations align with FDA standards to enable cross-border serialization continuity. Baja California and Nuevo León industrial corridors attract co-packing investments serving US-bound automotive and electronics aftermarket packaging.
North America Contract Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as established players retrofit lines for mono-material polyethylene films and pharmaceutical serialization infrastructure. The vendor base organizes around three strategic archetypes: large-scale integrated operators with multi-site networks, mid-tier specialists in regulated verticals, and regional pouch-focused fabricators. M&A activity and geographic expansion represent the primary competitive vectors, with buyers seeking FDA-validated facilities and sustainable packaging credentials.
Among North American specialists, Pharma Tech Industries, Aaron Thomas Company, and Reed Lane exemplify distinct capability positioning. Pharma Tech Industries anchors the pharmaceutical serialization tier with automated blister packaging infrastructure. Aaron Thomas Company occupies the food-grade flexible packaging position through pouch filling and retort specialization. Reed Lane represents the clinical trial materials segment with kit assembly and variable data printing capabilities.
| Leading Market Players |
|---|
| Pharma Tech Industries |
| Reed Lane |
| Aaron Thomas Company |
| Stamar Packaging |
| AmeriPac |
| Sharp Packaging Services |
| Unicep Packaging |
| Jones Healthcare Group |
| Multipack Solutions |
| Others |
Value Network & Pricing Analysis
Polyethylene resin feedstock costs cascade through three distinct pricing tiers as Gulf Coast petrochemical capacity fluctuations compress margins for fixed-price contract terms while rewarding volume-scaled buyers with pass-through clauses.
Pricing Analysis
Volume concentrates in high-throughput beverage filling contracts with thin per-unit margins, while pharmaceutical serialization services command premium pricing tiers due to FDA cGMP validation requirements and track-and-trace infrastructure investments. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical lines from food-grade flexible packaging and commodity secondary assembly. Cost compression in standard-tier food pouch contracts is intensifying because mono-material film requalification timelines extend without corresponding price adjustments. Generic drug manufacturers exhibit the highest price sensitivity due to tender-based procurement, while clinical trial sponsors accept premium rates for cold-chain-validated kit assembly.
Supply Chain Analysis
Domestic-content preferences embedded in California and New York extended producer responsibility statutes are reshaping sourcing patterns toward North American mono-material film suppliers and away from Asian laminate converters. Supply concentration centers on the US Midwest industrial corridor, with secondary clusters in Ontario and Baja California drawing from regional resin distribution networks. Raw material dependencies rest on Gulf Coast polyethylene production, Midwest corn-derived bioplastic feedstocks, and Canadian pulp for fiber-based formats. Single-source vulnerability runs through specialized serialization equipment suppliers serving pharmaceutical track-and-trace mandates. Distribution feeds from integrated co-packing campuses directly into CPG brand just-in-time fulfillment networks and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
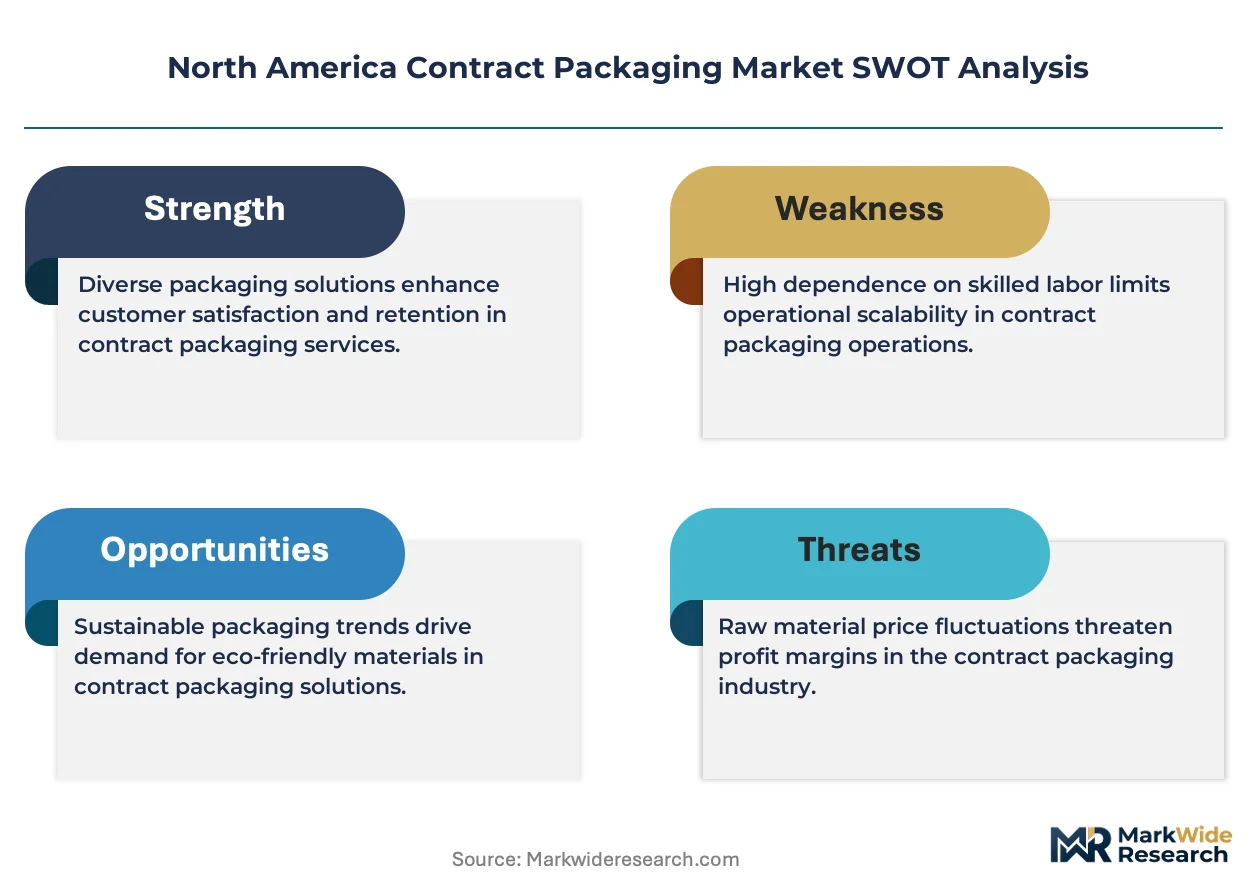
Qualified technician scarcity for FDA cGMP-validated automated lines props pricing power across pharmaceutical contract packaging, constraining capacity expansion regardless of capital availability.
For Market Incumbents: Cement market position through backward integration into mono-material film extrusion capabilities that secure supply continuity amid resin volatility. Add dedicated serialization capacity in Wisconsin and Ohio corridor locations to capture Drug Supply Chain Security Act-driven outsourcing before competitors qualify lines. Vertical integration into film supply insulates margin pressure from polyethylene price spikes. For New Entrants and Emerging Players: Canadian licensed cannabis producers represent an underserved buyer archetype seeking Health Canada-compliant child-resistant packaging with export-ready serialization. Target clinical trial kit assembly for biopharma sponsors requiring patient-specific medication bundles with variable data printing. Enter through cold-chain-validated secondary packaging partnerships with established 3PL networks serving e-commerce channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier food-grade pouch specialists in Illinois and Wisconsin with retort capabilities but underutilized serialization infrastructure. Long-term viability hinges on regulatory compliance depth rather than commodity volume scale. Watch FDA enforcement intensity around cGMP documentation timelines as the inflection signal for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Line Requalification | EPA sustainable materials management frameworks in California and New York mandate recyclable structures that force heat-seal parameter validation. |
| Serialization Infrastructure Investment | FDA Drug Supply Chain Security Act compliance deadlines compress implementation windows for pharmaceutical track-and-trace capabilities. |
| Midwest Corridor Capacity Expansion | Illinois, Ohio, and Wisconsin clusters enable just-in-time fulfillment networks for seasonal CPG demand surges. |
| Clinical Trial Kit Assembly Specialization | Biopharma outsourcing of patient-specific medication bundles demands cold-chain-validated secondary packaging with variable data printing. |
| Direct-to-Consumer Format Development | Durable ship-ready pouch designs with reduced void fill replace retail-focused case packing for digitally native brands. |
Research Methodology
Multi-period observation of pharmaceutical serialization compliance timelines, mono-material film adoption rates, and Midwest co-packing capacity utilization anchored the trend analysis, supplemented by interviews with contract packaging operations directors, FDA regulatory consultants, CPG brand procurement managers, and flexible film technical directors. Secondary validation drew from FDA cGMP guidance documents, EPA sustainable materials management frameworks, state extended producer responsibility statutes, and SEC filings of publicly traded packaging companies. Bottom-up line-level capacity estimates triangulated against top-down market value reconstruction.
Segment-weighting across service type, product category, end-user channel, and packaging format dimensions shaped the analytical framework across the analysis window. Pharmaceutical, food, beverage, and cosmetics verticals were modeled separately with distinct regulatory compliance cost structures. CAGRs were derived from installed base expansion rates, line speed improvements, and outsourcing penetration trends. Forecast inputs incorporated Drug Supply Chain Security Act implementation phases and state-level recycling policy fragmentation effects.
Revisions become necessary when FDA enforcement intensity shifts, resin price volatility exceeds historical bands, or state extended producer responsibility laws diverge further on mono-material specifications. Forecasts reflect documented assumptions about serialization equipment deployment timelines and sustainable film barrier performance qualification. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Global Packaging Robot Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Robotic Packaging Machines Market
Packaging Automation
Food Packaging Robotics Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Automated Label Inspection Machines Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Europe Packaging Automation Market