
 Australia Whey Protein Market | 2026-2036
Australia Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Whey Protein Market Outlook
The gap between premium isolate grades and commodity concentrate supply is repositioning procurement strategies across Australian food manufacturers. Fonterra Co-operative Group leverages its integrated dairy processing network to secure raw whey streams before competitors access them. Glanbia plc anchors its presence through specialized sports nutrition formulations that command shelf space in pharmacy and specialty retail channels. Bulk Nutrients competes aggressively on direct-to-consumer pricing, bypassing traditional wholesale markups through its Geelong-based fulfillment infrastructure.
Whey protein comprises the soluble protein fraction separated during cheese manufacture, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 34% to 90% depending on processing intensity. Concentrate remains the volume workhorse for baked goods and snack bar applications where cost sensitivity dominates formulation decisions. Isolate commands premium positioning among athletes and fitness enthusiasts seeking higher purity with reduced lactose content. Hydrolysate generates disproportionate margin pools despite smaller volumes, as pre-digested peptides justify therapeutic and elite sports positioning where rapid amino acid absorption carries functional value.
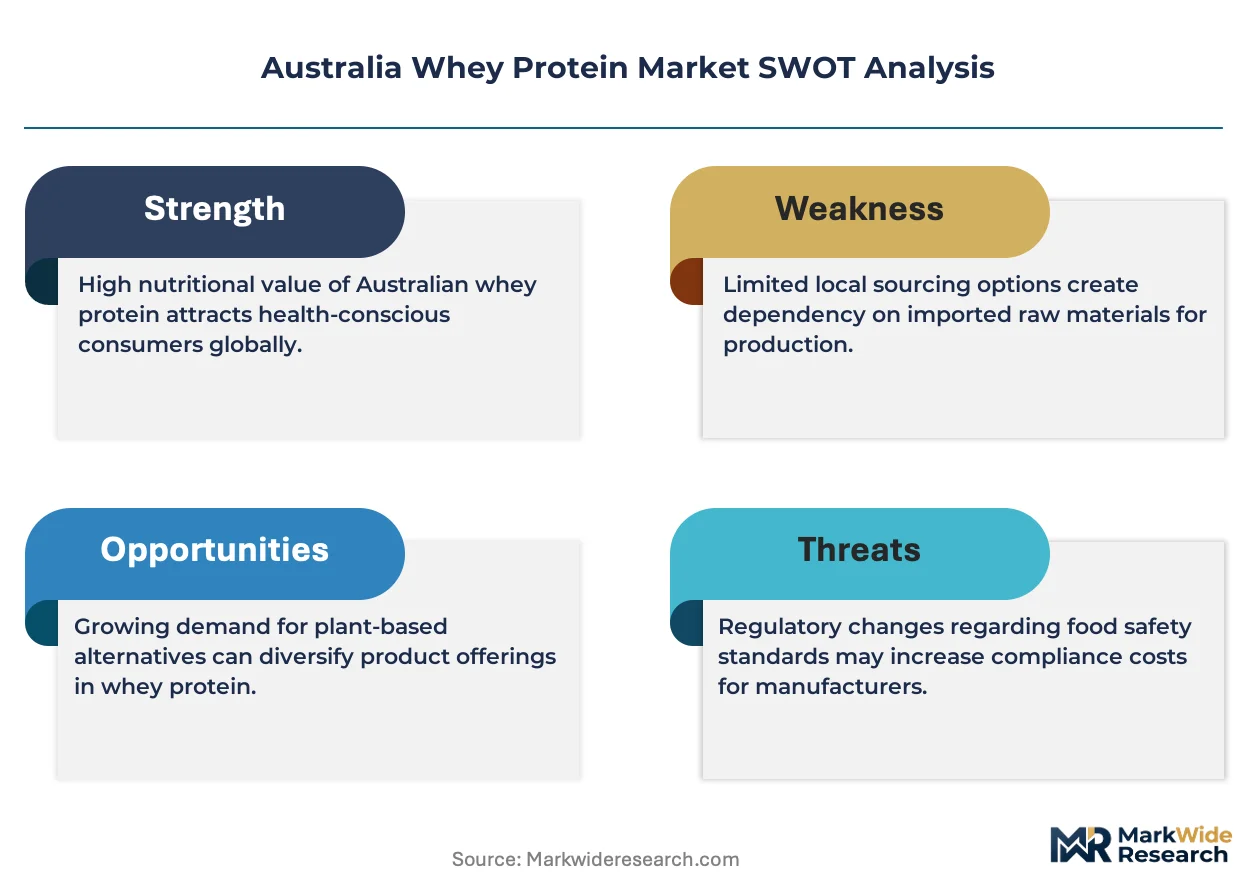
TGA oversees therapeutic claims on whey protein products marketed for muscle recovery or medical nutrition, while FSANZ governs compositional standards and labeling requirements for standard food products containing whey. FSANZ Standard 1.2.7 specifically constrains protein content declarations, forcing reformulation or label adjustment when actual protein levels fall below claimed thresholds. Stakeholders must monitor evolving TGA classification boundaries that could reclassify certain whey protein isolates as therapeutic goods rather than foods, fundamentally altering compliance costs and distribution channels.
Market Dynamics
FSANZ Standard 1.2.7 is compressing formulation margins as manufacturers absorb reformulation costs to meet tightened protein content declaration thresholds. This regulatory pressure intersects with raw whey stream scarcity, forcing procurement teams to secure supply contracts earlier in the dairy processing cycle.
Growth Catalysts
- Amateur athlete nutrition adoption:Sports nutrition consumption is expanding beyond bodybuilding into endurance sports and recreational fitness communities across New South Wales and Victoria metropolitan clusters.
- FSANZ label standard enforcement:Tighter protein content accuracy requirements are rewarding manufacturers with robust quality systems, creating competitive separation from label-shortcutting competitors.
- Metropolitan gym density concentration:Health-conscious retail penetration in Sydney and Melbourne is generating concentrated demand nodes that justify specialized distribution infrastructure investment.
Market Restraints
- Raw whey stream scarcity:Fonterra's integrated dairy processing network captures soluble protein fractions before independent manufacturers access them, concentrating upstream supply control.
- Input cost volatility:Fluid milk price fluctuations transmit directly to whey concentrate procurement budgets, compressing margin stability for cost-sensitive formulation segments.
- Therapeutic classification boundary uncertainty:TGA's evolving jurisdiction over muscle recovery claims creates compliance friction that could reclassify isolate products as therapeutic goods.
Strategic Opportunities
- Queensland and Western Australia penetration:Gym density and health retail coverage in Brisbane and Perth lag Sydney-Melbourne benchmarks, presenting whitespace for geographic expansion.
- Direct-to-consumer channel development:Bulk Nutrients' Geelong fulfillment model demonstrates bypass viability, enabling margin capture previously lost to wholesale markups.
- Medical nutrition positioning:Hydrolysate's pre-digested peptide functionality aligns with therapeutic nutrition applications where TGA oversight creates barrier-protected premium segments.
Industry Challenges
- Protein assay capability scarcity:Accurate nitrogen determination for FSANZ compliance requires specialized analytical talent that regional laboratories struggle to retain.
- Cross-jurisdictional compliance complexity:Products spanning standard food and therapeutic categories must simultaneously satisfy FSANZ compositional standards and TGA evidentiary requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Whey Protein Market |
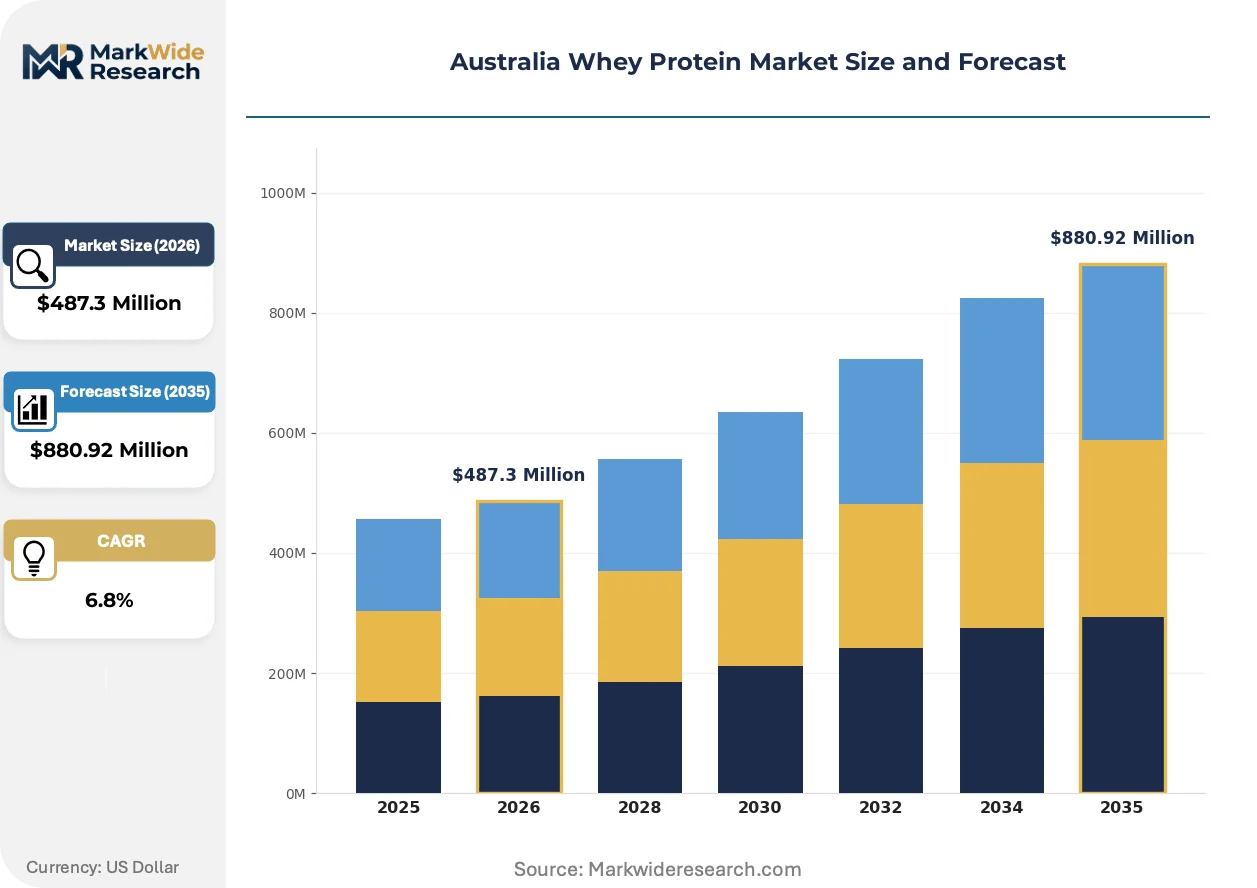
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Combinations End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Bodybuilders Packaging Type: Buckets, Sachets, Tubs, Pouches Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | Fonterra Co-operative Group, Saputo Inc, Glanbia plc, Protein Supplies Australia, Bulk Nutrients, FrieslandCampina, Kerry Group, Bioflex Nutrition, Lactalis Ingredients, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Whey Protein Market Strategic Shifts
Membrane filtration and chromatographic separation technologies are reshaping product grade availability, while regulatory precision demands and channel fragmentation are simultaneously compressing legacy manufacturing models and enabling agile entrants.
Cross-flow microfiltration and ion-exchange chromatography are automating the separation of beta-lactoglobulin and alpha-lactalbumin fractions at commercial scale. Mid-tier sports nutrition manufacturers in Victoria are adopting these systems to produce isolate grades without tolling arrangements. This equipment diffusion is automating what previously required specialized dairy processor partnerships, eroding Fonterra's historical lock on premium raw streams.
FSANZ Standard 1.2.7's protein content claim constraints are forcing reformulation cycles that previously occurred on multi-year horizons. Manufacturers must now verify nitrogen content through standardized Kjeldahl or Dumas methods before label commitment. Concentrate-dependent baked goods and snack bar segments face disproportionate adjustment burden, with several New South Wales facilities investing in in-house analytical capabilities rather than external laboratory dependency.
Pharmacy channel certification is displacing traditional sports specialty retail as the credibility gate for premium isolate positioning. TGA-adjacent therapeutic claims require evidentiary dossiers that pharmacy buyers demand but gym-focused retailers rarely enforce. This channel bifurcation is most visible in Melbourne's inner metropolitan ring, where compounding pharmacies with sports medicine affiliations are capturing athlete segment loyalty previously held by dedicated nutrition stores.
Australia Whey Protein Market Segmentation
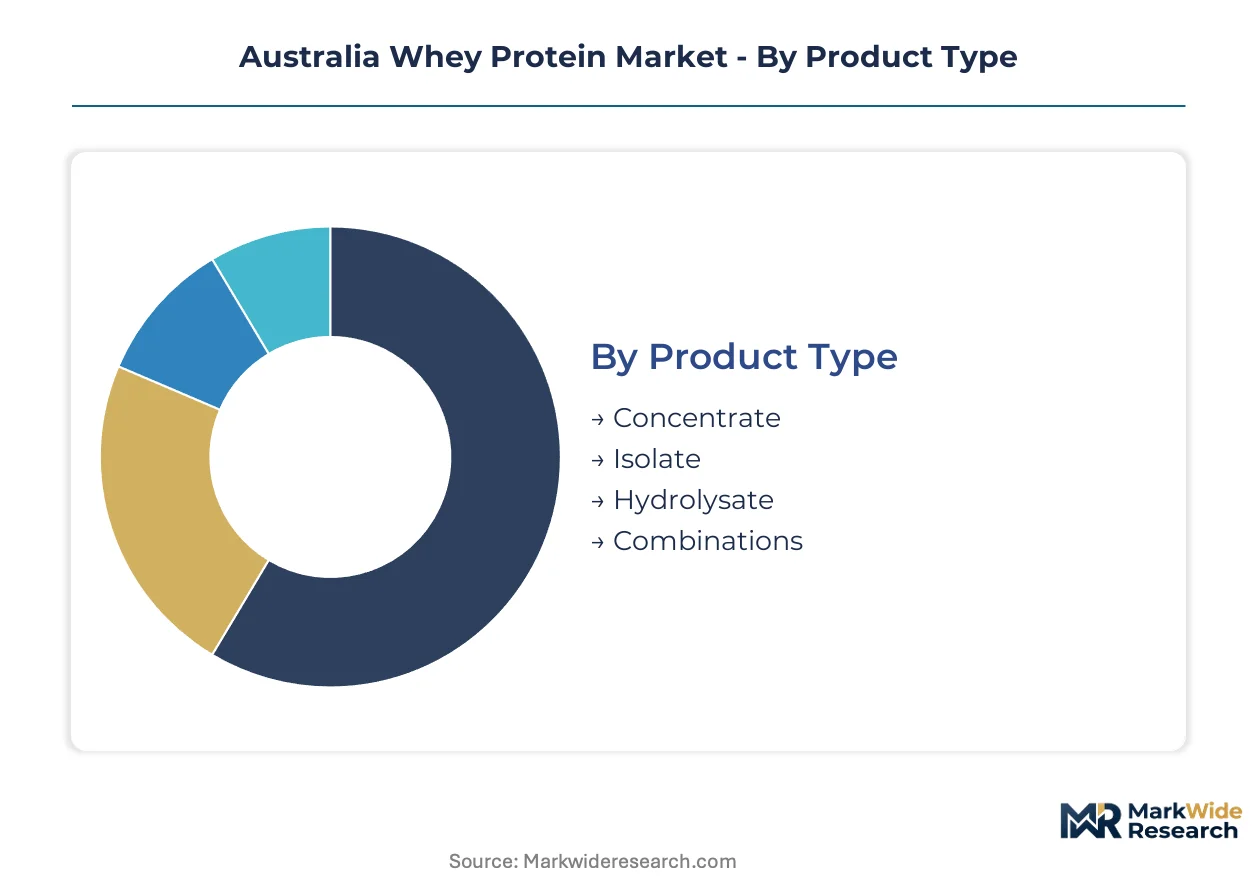
Whey protein segmentation in Australia reflects divergent compliance burdens across product grades and channel access requirements. FSANZ compositional standards and TGA therapeutic claim boundaries create tiered certification obligations that reshape competitive positioning within each segment category.
Product Type:
Concentrate carries baseline FSANZ food-standard compliance, while isolate and hydrolysate grades trigger escalating analytical verification and potential TGA jurisdiction depending on positioning claims.
- Concentrate:Protein concentrations range from 34% to 80% with retained lactose and lipid fractions. Baked goods and snack bar manufacturers in New South Wales absorb this grade for cost-sensitive formulations where nitrogen assay precision matters less than bulk procurement economics.
- Isolate:Achieves 90%+ protein concentration through ion-exchange or microfiltration processing. Pharmacy channel certification in Melbourne's inner metropolitan ring demands this grade for therapeutic-adjacent positioning where TGA evidentiary requirements create barrier-protected premium capture.
- Hydrolysate:Pre-digested peptide fractions command specialized TGA oversight when marketed for medical nutrition or elite recovery applications.
- Combinations:Blended formulations balance cost and performance for mass-market sports nutrition SKUs.
Concentrate sits at the top of the volume ranking, with Isolate climbing the fastest.
End User:
Customer archetypes stratify by performance demands, price sensitivity, and channel access patterns across metropolitan gym clusters and pharmacy networks.
- Athletes:Amateur endurance competitors and team sport participants in Sydney and Melbourne metropolitan areas drive isolate-grade adoption beyond traditional bodybuilding circles. Their nutrition decisions increasingly source through pharmacy channels demanding TGA-aligned evidentiary dossiers.
- Fitness Enthusiasts:Recreational gym members with moderate protein targets and elevated convenience expectations. This segment concentrates in Victoria's health-conscious retail corridors where direct-to-consumer fulfillment models from Geelong-based infrastructure capture repeat purchase loyalty.
- Health-Conscious Consumers:General wellness seekers integrating protein into broader dietary optimization.
- Bodybuilders:Legacy segment with established concentrate tolerance and price elasticity constraints.
Fitness Enthusiasts anchor current volume, with Athletes expanding most quickly as endurance sports nutrition adoption broadens.
Packaging Type:
Format selection intersects with distribution economics, with bulk formats favoring gym and online channels while single-serve options penetrate convenience retail.
- Buckets:Institutional-scale containers for commercial food manufacturing and high-volume athletic facilities.
- Sachets:Single-serve portability targets travel and trial occasions in airport retail and hotel fitness centers.
- Tubs:Standard household format dominating pharmacy and health store shelves across New South Wales and Victoria.
- Pouches:Flexible packaging gaining traction in online-direct subscription models where shipping weight optimization matters.
Tubs maintain volume leadership, with Pouches gaining share fastest through direct-to-consumer channel development.
Distribution Channel:
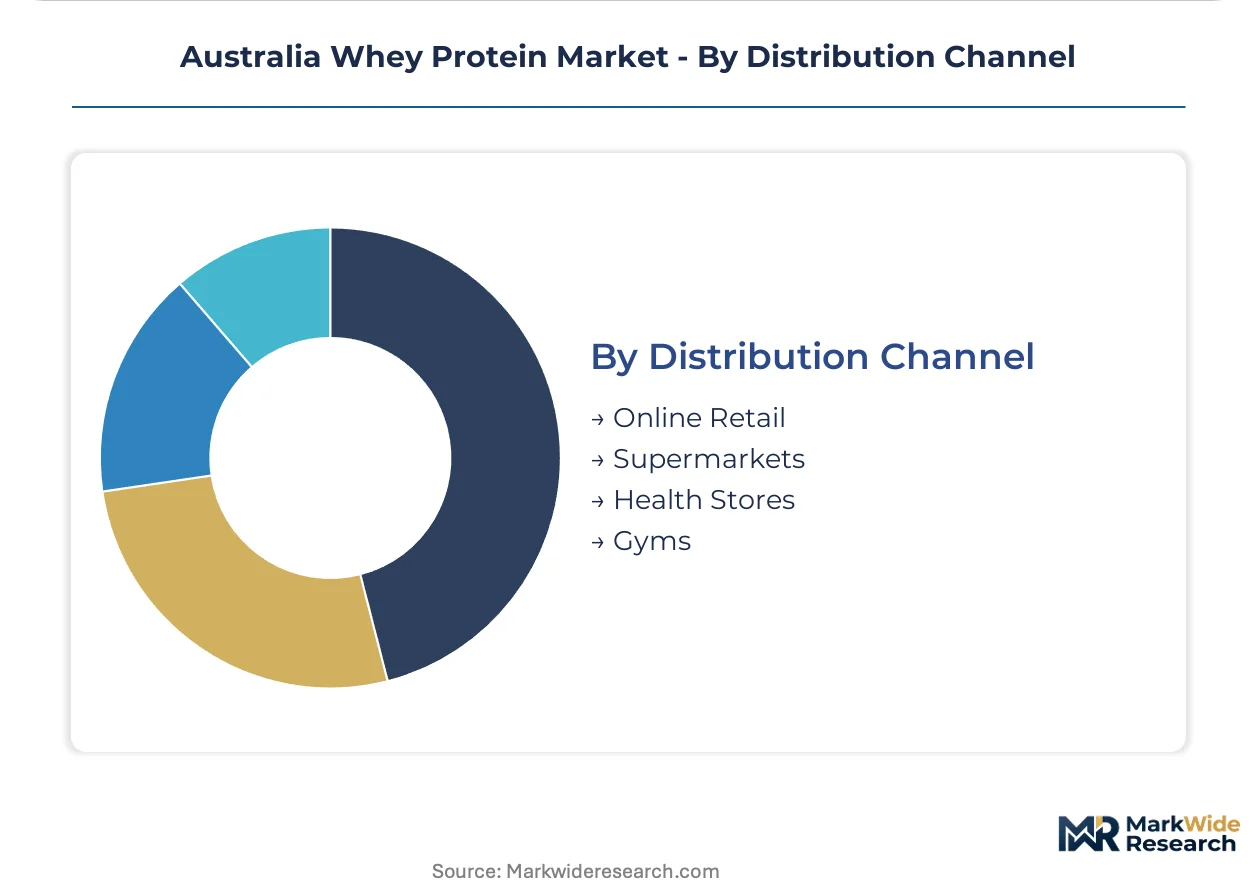
Channel selection determines regulatory exposure, with pharmacy pathways imposing TGA-adjacent requirements that supermarket and gym channels rarely enforce.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups and enable subscription mechanics. Bulk Nutrients' Geelong fulfillment infrastructure demonstrates margin capture viability that competitors are replicating.
- Supermarkets:Mass-market concentrate placement in Coles and Woolworths networks reaches health-curious households with limited sports nutrition literacy.
- Health Stores:Specialty retailers in Sydney and Melbourne metro areas curate isolate-grade portfolios for informed consumers.
- Gyms:Point-of-consumption placement captures impulse replenishment from members post-workout.
Online Retail leads volume contribution, with Health Stores showing steepest expansion trajectory as pharmacy certification displaces traditional sports specialty credibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and sports nutrition formulators cluster in Sydney and Melbourne metropolitan corridors, anchoring Australia's whey protein value chain in two dominant labor pools.
New South Wales
Sydney's metropolitan gym density and pharmacy network penetration drive isolate-grade demand among amateur endurance athletes. FSANZ Standard 1.2.7 enforcement pressures manufacturers in Parramatta industrial zones to invest in in-house nitrogen assay capabilities. The Sydney-Illawarra corridor concentrates contract manufacturing facilities serving both domestic and export formulation clients.
Victoria
Melbourne's inner metropolitan ring hosts compounding pharmacies with sports medicine affiliations that capture athlete segment loyalty through TGA-aligned therapeutic positioning. Geelong-based direct-to-consumer fulfillment infrastructure demonstrates margin capture viability bypassing wholesale markups. Regional dairy processing networks in Gippsland supply raw whey streams to Victorian isolate producers.
Queensland
Brisbane's gym density and health retail coverage lag Sydney-Melbourne benchmarks, presenting whitespace for geographic expansion. Amateur team sport participation in Southeast Queensland drives concentrate-grade consumption through supermarket channels. Sunshine Coast functional food manufacturers experiment with whey protein fortification in baked goods applications.
Western Australia
Perth's isolated metropolitan market depends on eastern supply chains with extended lead times compressing inventory turnover for retailers. Mining sector fly-in-fly-out workers generate concentrated demand for portable protein formats in airport and resource camp retail. Fremantle port infrastructure enables bulk concentrate import for local snack bar manufacturers.
Australia Whey Protein Market Competitive Environment
Top-tier vendors anchor integrated dairy processing and specialized sports nutrition formulation, while mid-tier direct-to-consumer specialists and commodity traders occupy distinct competitive strata. The market exhibits tiered concentration with three to four dominant upstream processors controlling raw whey stream access. Strategic archetypes include backward-integrated dairy cooperatives, pharmacy-channel formulation specialists, and direct-to-consumer price disruptors. Competitive moves center on procurement contract pre-positioning in dairy processing cycles and pharmacy channel certification investments.
Among integrated dairy processors, Fonterra Co-operative Group and Saputo Inc occupy positions exemplifying upstream supply control through captive whey fractionation infrastructure. Glanbia plc represents the pharmacy-channel specialist archetype, anchoring premium isolate positioning through evidentiary dossiers that satisfy TGA-adjacent requirements. Bulk Nutrients sits within the direct-to-consumer disruption tier, demonstrating margin capture viability through Geelong-based fulfillment infrastructure that bypasses traditional wholesale markups.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Saputo Inc |
| Glanbia plc |
| Protein Supplies Australia |
| Bulk Nutrients |
| FrieslandCampina |
| Kerry Group |
| Bioflex Nutrition |
| Lactalis Ingredients |
| Others |
Value Chain & Pricing Dynamics
Food technologist concentrations in Sydney and Melbourne metropolitan corridors create labor-cost differentials that widen spreads between premium isolate grades and commodity concentrate tiers. FSANZ compliance expertise scarcity in regional markets forces manufacturers to absorb higher analytical labor costs or accept reduced pricing power in pharmacy-certified segments.
Pricing Analysis
Unbundled analytical verification services command premiums separate from product procurement as FSANZ Standard 1.2.7 tightens nitrogen assay requirements. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-certified isolate from gym-channel concentrate and bulk industrial grades. Price differentiation rests on certification grade and volume scale, with TGA-adjacent therapeutic positioning justifying the steepest premiums. Pricing pressure stems from raw whey stream scarcity as Fonterra's integrated network captures soluble fractions early in dairy processing cycles. Fitness enthusiasts demonstrate highest price sensitivity through direct-to-consumer channel migration, while athletes in pharmacy channels show lowest elasticity for evidentiary-backed isolate.
Supply Chain Analysis
Dual-sourcing requirements from major sports nutrition manufacturers mandate multi-supplier qualification across New Zealand, Australian, and Irish dairy processing networks. Raw whey stream dependencies draw from fluid milk supply, ion-exchange resin inputs, and membrane filtration equipment. Supply chain risk centers on single-source vulnerability where Fonterra's Gippsland and Victorian processing infrastructure controls premium fraction access. Distribution runs through direct-to-consumer fulfillment, pharmacy wholesale, and supermarket mass-market channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through hydrolysate-grade therapeutic positioning and automation-driven assay cost reduction. Premium-tier shifts toward TGA-aligned pharmacy channels reward compliance investment with protected pricing.
For Market Incumbents: Deepen backward integration into raw whey stream procurement through pre-positioned contracts in Victorian and Gippsland dairy processing cycles. Expand in-house nitrogen assay capabilities to eliminate external laboratory dependency and compress FSANZ compliance timelines. Pharmacy channel certification investments defend against direct-to-consumer price disruptors capturing fitness enthusiast volume. For New Entrants and Emerging Players: The price-point gap between pharmacy-certified isolate and supermarket concentrate creates entry space for mid-tier direct-to-consumer specialists. Queensland and Western Australia geographic whitespace offers lowest competitive density for gym-channel penetration. Geelong-equivalent fulfillment infrastructure enables margin capture bypassing wholesale markups in Victoria's health-conscious retail corridors. For Investors and Strategic Acquirers: Dairy processors with captive whey fractionation infrastructure are the most active acquirer in this space, seeking downstream formulation capabilities. Long-term viability favors targets with pharmacy channel certification and TGA-aligned evidentiary dossiers over commodity concentrate traders. Watch FSANZ therapeutic classification boundary shifts as the inflection signal that could reclassify isolate products and alter compliance cost structures materially.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Certification | TGA-aligned evidentiary dossiers unlock premium pricing in Melbourne's compounding pharmacy networks. |
| Direct-to-Consumer Fulfillment Infrastructure | Geelong-based models demonstrate margin capture viability bypassing traditional wholesale markups. |
| In-House Analytical Capability Investment | FSANZ Standard 1.2.7 compliance eliminates external laboratory dependency and compresses reformulation cycles. |
| Raw Whey Stream Pre-Positioning | Early-cycle procurement contracts secure soluble protein fractions before competitor access in Victorian dairy networks. |
| Hydrolysate Grade Therapeutic Positioning | Pre-digested peptide functionality aligns with medical nutrition applications under TGA oversight creating barrier-protected segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports nutrition formulators, pharmacy buyers, dairy procurement managers, and FSANZ compliance officers with secondary validation. Trade data from Australian Bureau of Statistics, TGA therapeutic goods listings, FSANZ food standards registers, and dairy industry processor disclosures anchored supply-side assessment. Bottom-up SKU-level analysis and top-down sector sizing triangulated volume and value estimates.
Comparable-period anchoring linked historical whey protein consumption patterns to forward projection assumptions across the modeling period. Segmentation dimensions modeled include product grade tier, end-user archetype, distribution channel, and metropolitan versus regional geographic cluster. CAGRs derived from trend extrapolation adjusted for regulatory enforcement intensity and channel migration patterns. Forecast inputs incorporated fluid milk price transmission coefficients and gym density expansion trajectories in Brisbane and Perth.
Caveats apply where FSANZ therapeutic classification boundary shifts or raw whey stream supply disruptions could materially shift the outlook. Deviation in TGA jurisdiction expansion or Fonterra supply contract renegotiation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Bovine Collagen Peptide Market