
 Accent Tables Market | 2026-2036
Accent Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Accent Tables Market Insights
Mid-century modern specification tiers are unwinding across the accent tables category as consumers trade up from particleboard to solid-wood and veneer-construction pieces. IKEA leverages its flat-pack logistics to dominate entry-level Scandinavian-inspired lines. Bassett Furniture sustains domestic manufacturing credibility through its Bench Made program. Four Hands differentiates with artisan-sourced global designs that command premium positioning in boutique retail channels.
Accent tables are freestanding furniture pieces, typically 18 to 28 inches in height, designed for placement beside seating or against walls to support lamps, beverages, or decorative objects; primary construction employs hardwood solids, engineered wood substrates, tubular steel frames, or tempered glass tops joined through dowel, mortise-tenon, or welded fabrication methods. Console tables lead value contribution in the product type dimension, as hallway and entryway renovations command higher per-unit spending than living room refreshes. Metal and glass material combinations represent the fastest-expanding margin pool, driven by industrial and modern style preferences in urban condominium markets. Wood material segments retain volume leadership but face margin compression from volatile lumber input costs and certification compliance overhead.
The EPA administers formaldehyde standards under TSCA Title VI, directly governing composite wood emissions and reshaping supplier qualification requirements for brands selling into the United States. California Air Resources Board maintains stricter Phase 2 benchmarks that de facto set national compliance baselines, while FSC chain-of-custody certification increasingly gates access to major retail and hospitality procurement programs. Stakeholders must monitor evolving state-level chemical disclosure mandates and build supplier audit capabilities that trace material origins through multi-tier sourcing networks.
Market Dynamics
EPA's TSCA Title VI formaldehyde emission standards are forcing wholesale reformulation of composite wood substrates across the accent tables supply base, with California's CARB Phase 2 benchmarks de facto governing national compliance thresholds and reshaping supplier qualification protocols.
Growth Catalysts
- CARB Phase 2 Compliance Infrastructure:Manufacturers investing in water-based adhesive systems and FSC-certified wood sourcing are securing preferred supplier status with major retail procurement programs.
- Urban Compact Living:Residential developers in dense metropolitan markets now specify accent tables as standard furnishings in sub-600-square-foot apartment layouts.
- Metal-Glass Material Innovation:Industrial and modern aesthetic preferences in condominium renovations are expanding addressable margin pools for tubular steel and tempered glass construction methods.
Market Restraints
- Volatile Lumber Input Costs:Solid-wood and veneer-construction segments face persistent margin compression from unpredictable hardwood pricing cycles.
- Supply Concentration Risk:FSC chain-of-custody certification requirements have consolidated qualified supplier networks in Southeast Asian and South American sourcing corridors.
- Substitution by Multi-Functional Ottomans:Storage-integrated seating alternatives are capturing share in entry-level living room refresh cycles.
Strategic Opportunities
- Underpenetrated Secondary US Metropolitan Markets:Austin, Nashville, and Raleigh-Durham exhibit replacement cycle acceleration without proportional retail footprint expansion.
- Hospitality Procurement Programs:Boutique hotel renovation pipelines are creating specification pathways for artisan-sourced global designs at premium positioning tiers.
- Direct-to-Consumer Channel Development:Configurator-enabled e-commerce platforms are collapsing traditional wholesale-distributor markups for mid-century modern lines.
Industry Challenges
- Multi-Tier Supplier Audit Capability Gaps:Tracing material origins through three-plus sourcing network layers requires investment in blockchain or comparable chain-of-custody infrastructure.
- Certification Timeline Compression:EPA and state-level chemical disclosure mandate evolution is shortening product development-to-market windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Accent Tables Market |
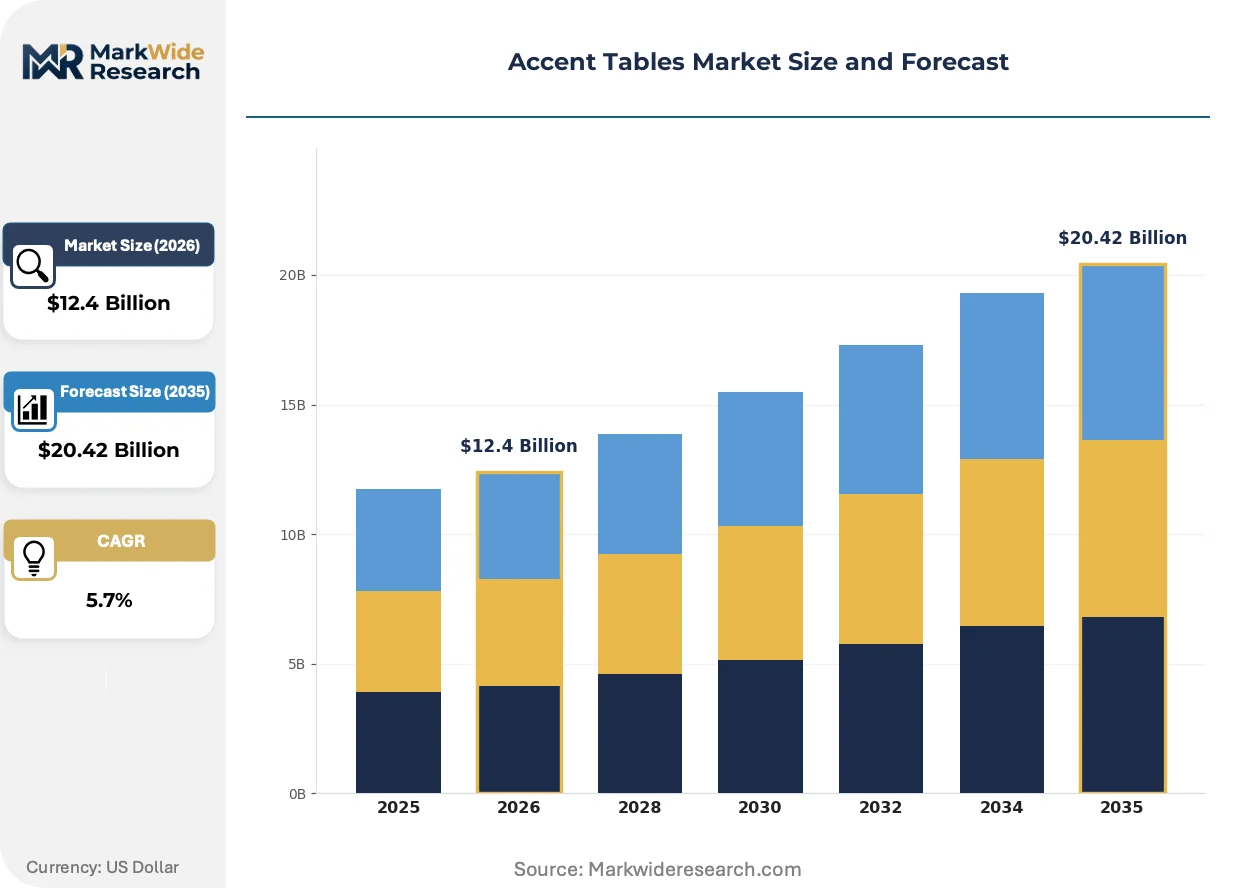
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: End Table, Coffee Table, Ottoman Table, Console Table Material: Wood, Metal, Glass, Acrylic Style: Modern, Rustic, Industrial, Coastal Usage: Living Room, Bedroom, Office, Patio |
| Companies Covered | IKEA, Bassett Furniture, Hooker Furniture, Welland Industries LLC, SEI Furniture, Acme Furniture, Ashley Furniture Industries, Wayfair, Four Hands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Accent Tables Market Trends and Innovations
Material substitution dynamics and regulatory compliance automation are restructuring competitive advantage in accent tables manufacturing, with sustainability credentialing emerging as a primary sorting mechanism for procurement decisions.
Water-based polyurethane finishing systems is supplanting solvent-based lacquers in hardwood solid and veneer-construction tiers. Boutique retail channels and hospitality specifiers are accelerating adoption timelines to meet LEED-compliant project requirements. This transition is compressing market share for conventional finishing houses unable to reformulate product lines.
EPA's formaldehyde emission standards under TSCA Title VI are mandating third-party certification for all composite wood products sold into United States distribution. Manufacturers must maintain laboratory testing partnerships and documentation systems that demonstrate ongoing compliance. Entry-level particleboard construction segments bear disproportionate compliance cost burdens relative to premium solid-wood alternatives.
Specification authority is migrating from interior designers to procurement departments within multi-unit residential developers and hospitality ownership groups. These concentrated buyers are unbundling after-sales service and demanding extended warranty terms as standard contract inclusions. This shift is most visible in Texas and Florida metropolitan markets where multi-family construction volume exceeds national averages.
Accent Tables Market Segmentation
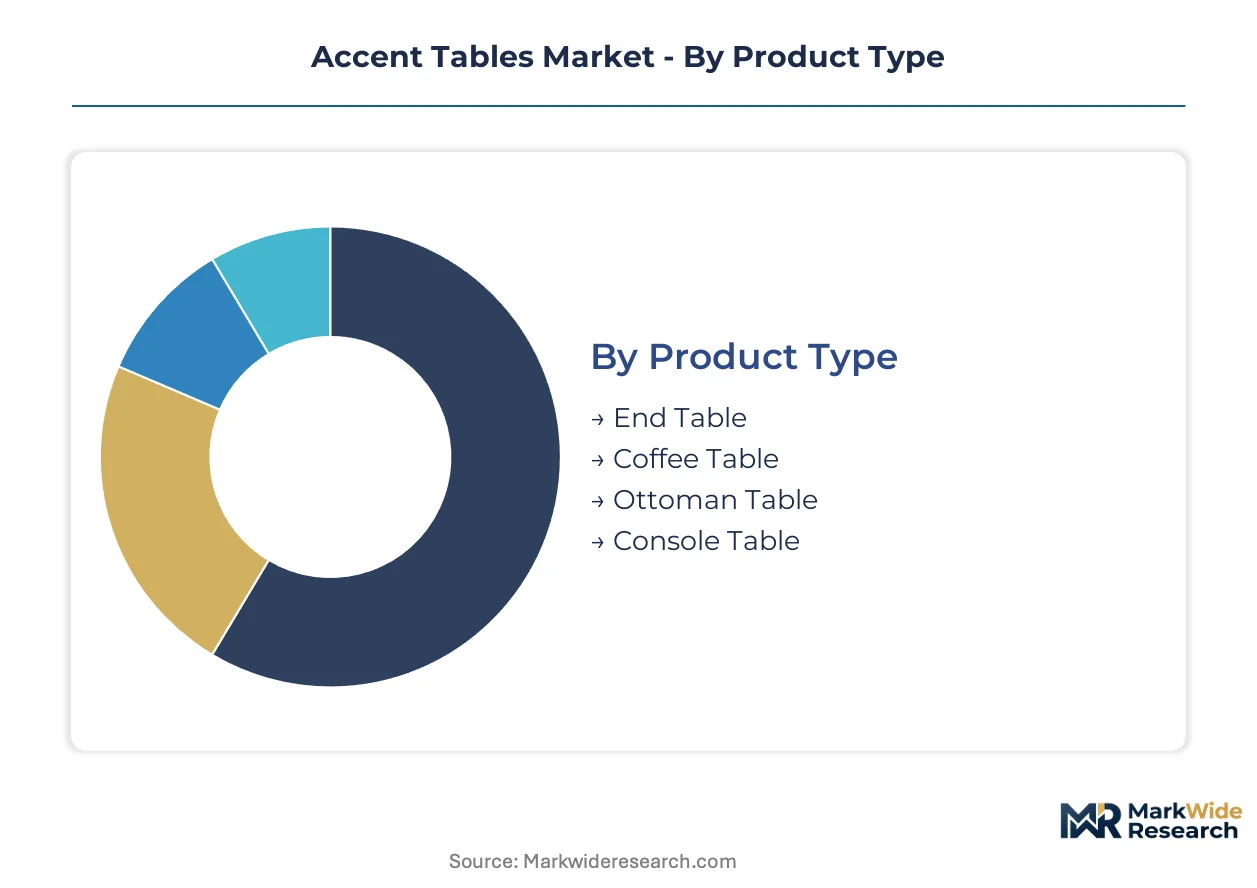
Accent tables manufacturers align product portfolios with distinct specification pathways. Regulatory compliance costs and material substitution dynamics create divergent margin profiles across construction methods and end-use applications.
Product Type:
EPA TSCA Title VI and CARB Phase 2 emission standards impose tiered compliance burdens that reshape competitive positioning across product categories.
- Console Table:Hallway and entryway renovations command elevated per-unit spending through premium material specifications and custom dimension requirements. Residential developers in Austin, Nashville, and Raleigh-Durham metropolitan markets specify these as standard furnishings in luxury multi-family lobby installations.
- End Table:Compact footprint designs dominate replacement cycles in urban sub-600-square-foot apartment layouts. California's formaldehyde emission standards under CARB Phase 2 have pushed manufacturers toward water-based adhesives and FSC-certified wood sourcing for this high-volume category.
- Coffee Table:Living room refresh cycles sustain steady demand through multi-functional storage-integrated designs.
- Ottoman Table:Storage-integrated seating alternatives capture share in entry-level living room specification tiers.
Established volume favors Console Table; emerging adoption favors End Table.
Material:
Cost tier differentiation separates premium solid-wood construction from entry-level engineered substrates facing compliance cost compression.
- Wood:Hardwood solids and veneer-construction tiers retain volume leadership but face margin pressure from volatile lumber input cycles and certification overhead. FSC chain-of-custody requirements consolidate qualified supplier networks in Southeast Asian and South American sourcing corridors.
- Metal:Tubular steel frames combined with tempered glass tops expand addressable margin pools through industrial and modern aesthetic preferences in urban condominium renovation markets.
- Glass:Tempered glass construction methods serve premium positioning tiers in boutique retail and hospitality procurement programs.
- Acrylic:Lightweight transparent substrates address coastal and contemporary style preferences with reduced shipping cost profiles.
Wood commands current volume share; Metal-Glass combinations climb the fastest.
Style:
Customer type migration from interior designers to procurement departments reshapes specification authority across aesthetic positioning tiers.
- Modern:Clean-line geometries with metal and glass material combinations dominate urban condominium markets. Water-based polyurethane finishing systems supplant solvent-based lacquers to meet LEED-compliant project requirements.
- Industrial:Exposed structural elements and mixed-material construction resonate with loft conversion and adaptive reuse residential developments.
- Rustic:Reclaimed wood sourcing and distressed finishes serve vacation rental and secondary home markets.
- Coastal:Light-toned materials and weather-resistant treatments address patio and sunroom applications in Florida and Texas metropolitan construction corridors.
Modern styling leads specification frequency; Industrial gains share fastest among renovation-driven demand.
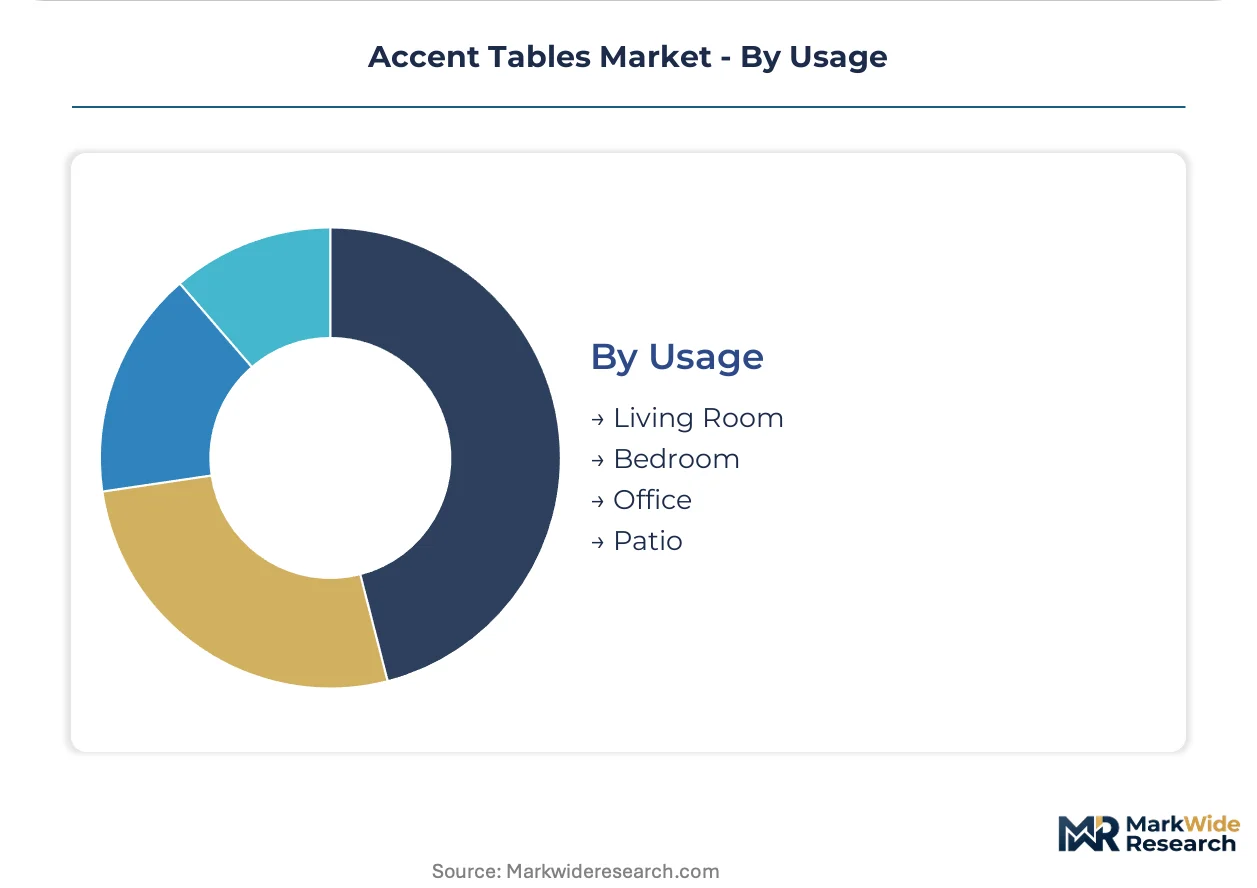
Usage:
Application context determines durability requirements, dimensional constraints, and replacement cycle timing.
- Living Room:Open-concept floor plans and multi-functional furniture preferences drive replacement cycles across metropolitan United States markets. Configurator-enabled e-commerce platforms collapse traditional wholesale-distributor markups for mid-century modern lines in this segment.
- Office:Hybrid workplace normalization sustains demand for residential office nook furnishings with compact footprint requirements.
- Bedroom:Nightstand specifications follow mattress and bedding refresh cycles with lower per-unit spending thresholds.
- Patio:Weather-resistant material treatments and powder-coated metal finishes address outdoor durability requirements.
Living Room anchors volume contribution; Office usage shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in accent tables track finished furniture outbound from Southeast Asian manufacturing clusters toward North American and European consumption centers, with regulatory compliance costs increasingly determining supplier qualification thresholds.
United States
Open-concept floor plans in metropolitan markets sustain replacement cycle velocity for console and end table categories. EPA TSCA Title VI formaldehyde emission standards govern composite wood products sold into domestic distribution, forcing reformulation of particleboard substrates. Austin, Nashville, and Raleigh-Durham metropolitan corridors exhibit accelerated renovation activity without proportional retail footprint expansion.
Germany
Industrial and modern aesthetic preferences in urban condominium renovations drive specification of tubular steel and tempered glass construction methods. ECHA REACH chemical registration requirements shape adhesive and finishing system selection across imported and domestically manufactured lines. The North Rhine-Westphalia furniture manufacturing cluster maintains finishing and assembly operations serving pan-European distribution networks.
China
Domestic consumption of accent tables rises alongside urban residential development in tier-one and tier-two cities with compact living layouts. GB standards for indoor air quality and formaldehyde emissions in wood-based panels align manufacturing practices with export market requirements. The Pearl River Delta concentration of engineered wood substrate suppliers supplies both domestic brands and export-oriented finished goods manufacturers.
Vietnam
FSC-certified hardwood sourcing corridors in Southeast Asia consolidate qualified supplier networks serving North American and European procurement programs. The country's national standards for wood product quality and labeling support compliance documentation for export shipments. Industrial zones surrounding Ho Chi Minh City host assembly and finishing operations for mid-market Scandinavian-inspired product lines.
Canada
Multi-family residential construction in Toronto and Vancouver metropolitan areas specifies accent tables as standard furnishings in compact unit layouts. Health Canada and PMRA chemical regulations govern adhesive and coating formulations in domestically manufactured and imported products. The Ontario furniture manufacturing corridor maintains upholstery and case goods production serving provincial and cross-border United States distribution.
Accent Tables Market Competitive Landscape
Concentration sits with flat-pack logistics specialists and domestic manufacturing credibility programs at opposite ends of the value spectrum, with boutique design houses occupying premium positioning tiers. The vendor base spans three strategic archetypes: mass-market flat-pack distributors, domestic manufacturing heritage brands, and artisan-sourced global design specialists. Competitive moves center on supply chain certification investments and direct-to-consumer channel development to collapse wholesale-distributor markups.
Among mass-market specialists, IKEA leverages its logistics infrastructure to dominate entry-level Scandinavian-inspired lines. Bassett Furniture sustains domestic manufacturing credibility through its Bench Made program. Four Hands occupies the premium tier with artisan-sourced global designs commanding positioning in boutique retail and hospitality procurement channels.
| Leading Market Players |
|---|
| IKEA |
| Bassett Furniture |
| Hooker Furniture |
| Welland Industries LLC |
| SEI Furniture |
| Acme Furniture |
| Ashley Furniture Industries |
| Wayfair |
| Four Hands |
| Others |
Pricing and Supply Chain Analysis
Water-based adhesive substitution for solvent-based bonding agents is redrawing supply geography toward FSC-certified hardwood corridors in Vietnam and Indonesia while compressing margins for particleboard-dependent manufacturers unable to absorb reformulation costs. This input transition simultaneously elevates procurement qualification thresholds for brands selling into California CARB Phase 2 and EPA TSCA Title VI jurisdictions, reshaping where pricing power accumulates across the value chain.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale as the primary differentiation drivers. Boutique hospitality specifiers and multi-unit residential developers exhibit the lowest price sensitivity, while entry-level living room refresh cycles face acute cost compression from storage-integrated ottoman substitutes. Pricing pressure stems from volatile hardwood input cycles and FSC chain-of-custody compliance overhead, with solid-wood and veneer-construction tiers commanding sustainable premiums against engineered substrate alternatives.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane and container availability constraints in Southeast Asian export corridors are elevating inbound logistics costs for finished goods shipments. Manufacturing concentration centers on Vietnam, Indonesia, and Malaysia for FSC-certified hardwood assembly, with engineered wood substrate dependencies drawing from Pearl River Delta suppliers. Single-source vulnerability in certified wood sourcing corridors presents structural risk, while distribution runs through wholesale-distributor networks to big-box retail and direct-to-consumer configurator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic is penetrating accent tables procurement as configurator-enabled e-commerce collapses traditional wholesale markups and hospitality ownership groups centralize specification authority through digital sourcing portals.
For Market Incumbents: Compound domestic manufacturing credibility through captive FSC-certified wood sourcing and in-house finishing capability to defend against flat-pack logistics specialists. Invest in blockchain chain-of-custody infrastructure to satisfy multi-tier supplier audit requirements from concentrated buyers. Extend warranty terms and after-sales service bundling to meet procurement department contract standards in Texas and Florida multi-family construction corridors. For New Entrants and Emerging Players: Differentiate on artisan-sourced global designs targeting boutique hotel renovation pipelines and secondary metropolitan markets lacking proportional retail footprint. Austin, Nashville, and Raleigh-Durham exhibit accelerated replacement cycles without incumbent saturation. Pursue direct-to-consumer channel development with configurator-enabled platforms to bypass wholesale-distributor markups in mid-century modern specification tiers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with certified supply chain control and direct channel assets. Long-term viability hinges on regulatory compliance automation capabilities and sustainability credentialing depth. The signal to watch is procurement department specification authority migration in multi-unit residential and hospitality segments as an inflection indicator for margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification Investment | Secures preferred supplier status with major retail and hospitality procurement programs requiring traceability documentation. |
| Direct-to-Consumer Platform Launch | Collapses wholesale-distributor markups for mid-century modern lines through configurator-enabled e-commerce interfaces. |
| Water-Based Finishing System Transition | Meets LEED-compliant project requirements from boutique retail channels and hospitality specifiers accelerating adoption timelines. |
| Secondary Metropolitan Market Expansion | Captures replacement cycle acceleration in Austin, Nashville, and Raleigh-Durham without incumbent retail saturation. |
| Hospitality Procurement Program Integration | Creates specification pathways for artisan-sourced global designs at premium positioning tiers in boutique hotel renovations. |
Research Methodology
A standing panel of residential developers, hospitality procurement directors, furniture retail category managers, and FSC certification auditors provided ongoing calibration throughout the study. Primary interviews with manufacturing operations heads and supply chain directors were cross-validated against secondary sources including EPA TSCA Title VI compliance filings, CARB Phase 2 certification databases, customs trade records, and hospitality procurement contract disclosures. Bottom-up SKU-level volume aggregation and top-down macroeconomic reconciliation ensured analytical consistency.
Outputs were validated against external benchmarks including regional construction permit data and retail point-of-sale audit information across the projection horizon. The forecast framework modeled product type, material composition, style positioning, and end-use application dimensions, with CAGRs derived from replacement cycle velocity analysis and regulatory compliance cost trajectory assessment. Hardwood input cost volatility and certification timeline compression served as industry-specific forecast inputs.
Material uncertainties — lumber price spike events, state-level chemical disclosure mandate evolution, and logistics corridor disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory stability and sourcing corridor access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Popover Pan Market