
 Spectrophotometers Market | 2026-2036
Spectrophotometers Market Size, Share, and Industry Trends Forecast 2026-2036
Spectrophotometers Market Analysis
The gap between research-grade and routine analytical spectrophotometers is expanding as pharmaceutical and environmental labs diverge in sensitivity requirements and software sophistication. Agilent Technologies leverages its chromatography-spectroscopy integration to dominate high-end pharmaceutical workflows. Thermo Fisher Scientific sustains broad catalog breadth across UV-Vis, IR, and fluorescence platforms for academic and industrial buyers. Shimadzu Corporation anchors its position in Asia-Pacific through localized service networks and compliance support for GMP-certified facilities.
A spectrophotometer measures light absorption, transmission, or reflectance across defined wavelength ranges, typically spanning 190 nm to 2500 nm depending on optical configuration and detector type; its core function is quantitative chemical analysis through Beer-Lambert law applications in quality control, research, and regulatory compliance testing. UV-Vis spectrophotometers occupy the largest installed base due to routine deployment in pharmaceutical quality control and environmental monitoring, while fluorescence spectrophotometers command premium pricing in life science research where detection sensitivity requirements exceed single-beam absorbance limits. Array technology is displacing traditional scanning monochromator architectures in high-throughput settings where speed and parallel wavelength acquisition reduce per-sample analysis time.
EPA methods under the Safe Drinking Water Act and Clean Water Act mandate specific absorbance and fluorescence detection protocols that shape instrument specification requirements for environmental testing laboratories in the United States. REACH and the EU Green Deal drive substitution analysis and contaminant detection needs that expand fluorescence and IR spectrophotometer demand across European industrial and contract testing labs. Stakeholders must monitor evolving pharmacopeial chapters from USP, EP, and JP authorities that periodically revise wavelength accuracy, stray light limits, and qualification protocols governing instrument validation in regulated pharmaceutical environments.
Market Dynamics
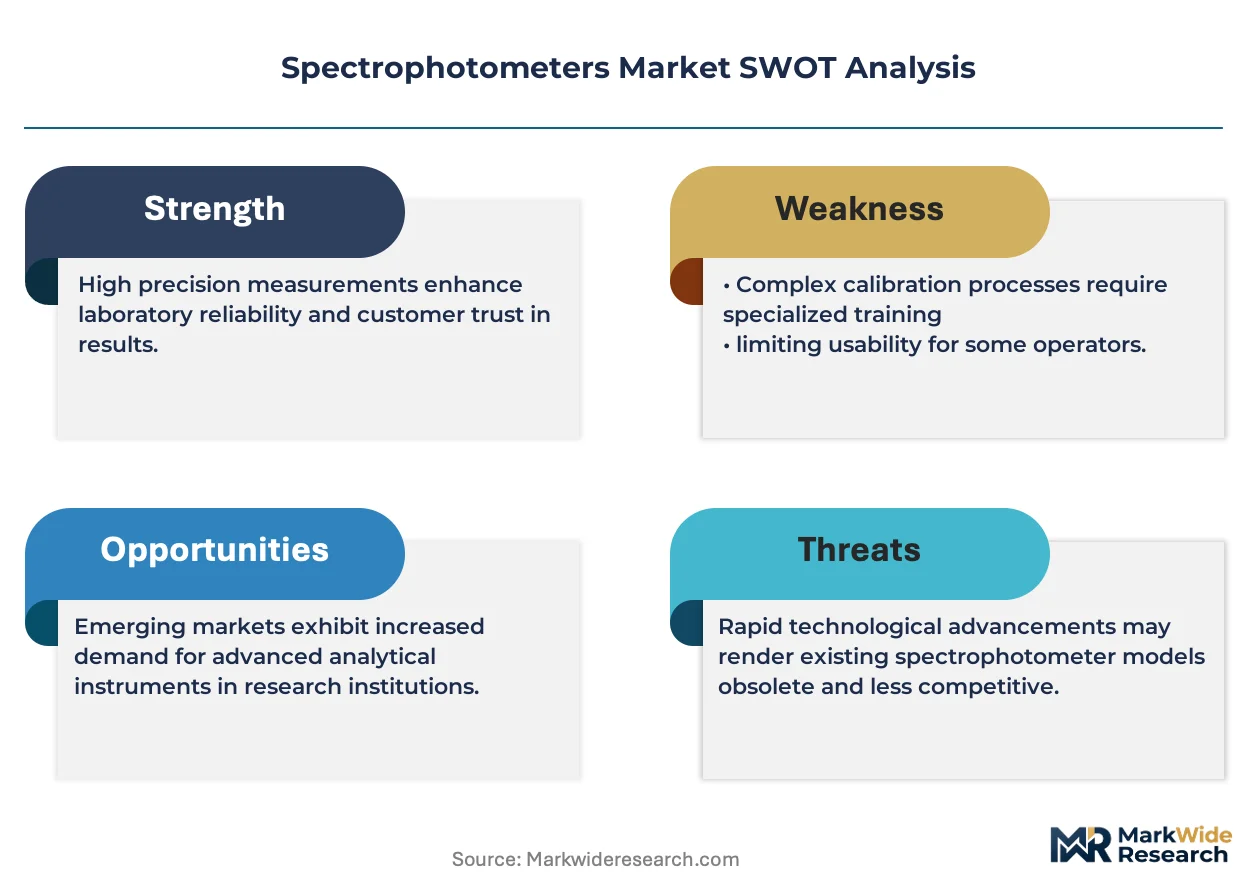
Array detector technology is compressing analysis cycles in pharmaceutical quality control labs, forcing instrument vendors to reconfigure optical architectures and software stacks around parallel wavelength acquisition rather than sequential scanning.
Growth Catalysts
- EPA monitoring mandates:The Safe Drinking Water Act and Clean Water Act prescribe specific absorbance protocols for contaminant detection, compelling environmental testing laboratories in the United States to upgrade instrument sensitivity specifications.
- Fluorescence sensitivity thresholds:Life science research applications now demand detection limits below single-beam absorbance capabilities, pulling premium instrument procurement in academic and biopharma settings.
- India and China pharmaceutical scaling:GMP-certified manufacturing clusters in Mumbai, Hyderabad, Shanghai, and Suzhou are driving replacement cycles for UV-Vis and fluorescence quality control workflows.
Market Restraints
- Optical component supply concentration:High-performance gratings, detectors, and light sources concentrate among specialized German and Japanese component suppliers, creating vulnerability to lead time volatility.
- Capital intensity of qualification protocols:USP, EP, and JP pharmacopeial validation requirements demand extensive IQ/OQ/PQ documentation, extending sales-to-revenue recognition timelines for vendors.
- Portable Raman substitution:Handheld Raman spectrometers are capturing point-of-use testing applications previously served by benchtop UV-Vis units in field environmental monitoring.
Strategic Opportunities
- Southeast Asia contract testing expansion:Singapore and Vietnam-based analytical service providers are building capacity to serve EU and US export compliance, creating instrument demand from outsourced pharmaceutical and food safety testing.
- Chromatography-spectroscopy convergence:LC-UV and LC-fluorescence integrated systems enable real-time peak identification, opening premium pricing tiers for vendors with dual-technology portfolios.
- EU Green Deal substitution analysis:REACH Article 33 extended supply chain disclosure obligations are expanding fluorescence and IR spectrophotometer deployment for contaminant fingerprinting across European industrial labs.
Industry Challenges
- Spectroscopy-software integration complexity:Pharmaceutical buyers demand seamless LIMS and ELN connectivity, forcing vendors to maintain multiple protocol adapters and validation documentation sets.
- Metrology technician scarcity:Qualified personnel for wavelength accuracy verification, stray light testing, and performance qualification are concentrated in established pharmaceutical clusters, constraining facility expansion in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectrophotometers Market |
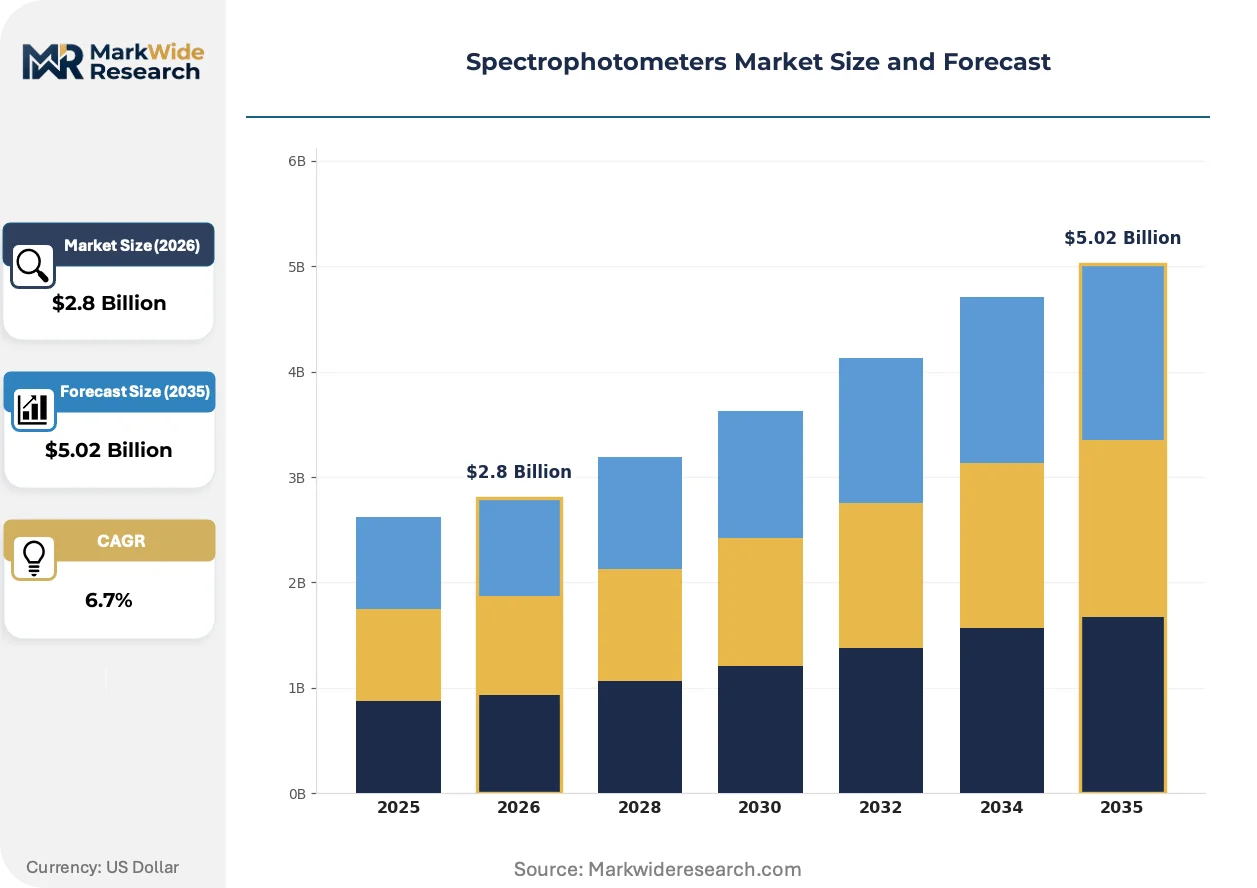
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV-Vis Spectrophotometers, IR Spectrophotometers, Fluorescence Spectrophotometers, Mass Spectrophotometers Technology: Double Beam Technology, Single Beam Technology, Array Technology, Portable Technology End User: Pharmaceuticals, Environmental Labs, Food & Beverage, Academic Institutions Application: Quality Control, Research & Development, Process Analytical, Clinical Diagnostics |
| Companies Covered | Agilent Technologies, Analytik Jena, Thermo Fisher Scientific, tec5USA, Hunter Associates Laboratory, Shimadzu Corporation, Mettler-Toledo, CRAIC Technologies, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectrophotometers Market Emerging Trajectories
Instrument architectures are bifurcating between high-throughput array systems for routine screening and research-grade platforms for trace-level quantification, with software sophistication becoming the primary differentiation vector.
Photodiode array technology is absorbing market share from traditional scanning monochromators in pharmaceutical quality control environments. High-volume generic drug manufacturers in India and China are adopting parallel wavelength acquisition to compress batch release timelines. This shift is absorbing the economic rationale for single-beam scanning architectures in applications where speed outweighs ultimate sensitivity.
REACH compliance deadlines are tightening detection threshold requirements across European environmental and food safety testing laboratories. ECHA guidance on persistent organic pollutants and microplastics characterization is mandating fluorescence and IR confirmation methods beyond basic UV-Vis screening. Contract testing organizations in Germany, France, and the Netherlands are responding by upgrading to modular platform configurations that accommodate multiple detection modalities.
Service unbundling is reshaping vendor-customer relationships in academic and industrial procurement. Research institutions in Japan and the United States are separating instrument purchase from validation, training, and maintenance contracts, pressuring traditional bundled pricing models. This pattern is most visible in National Science Foundation-funded university labs where capital equipment and operating budgets sit under distinct administrative controls.
Spectrophotometers Market Segmentation
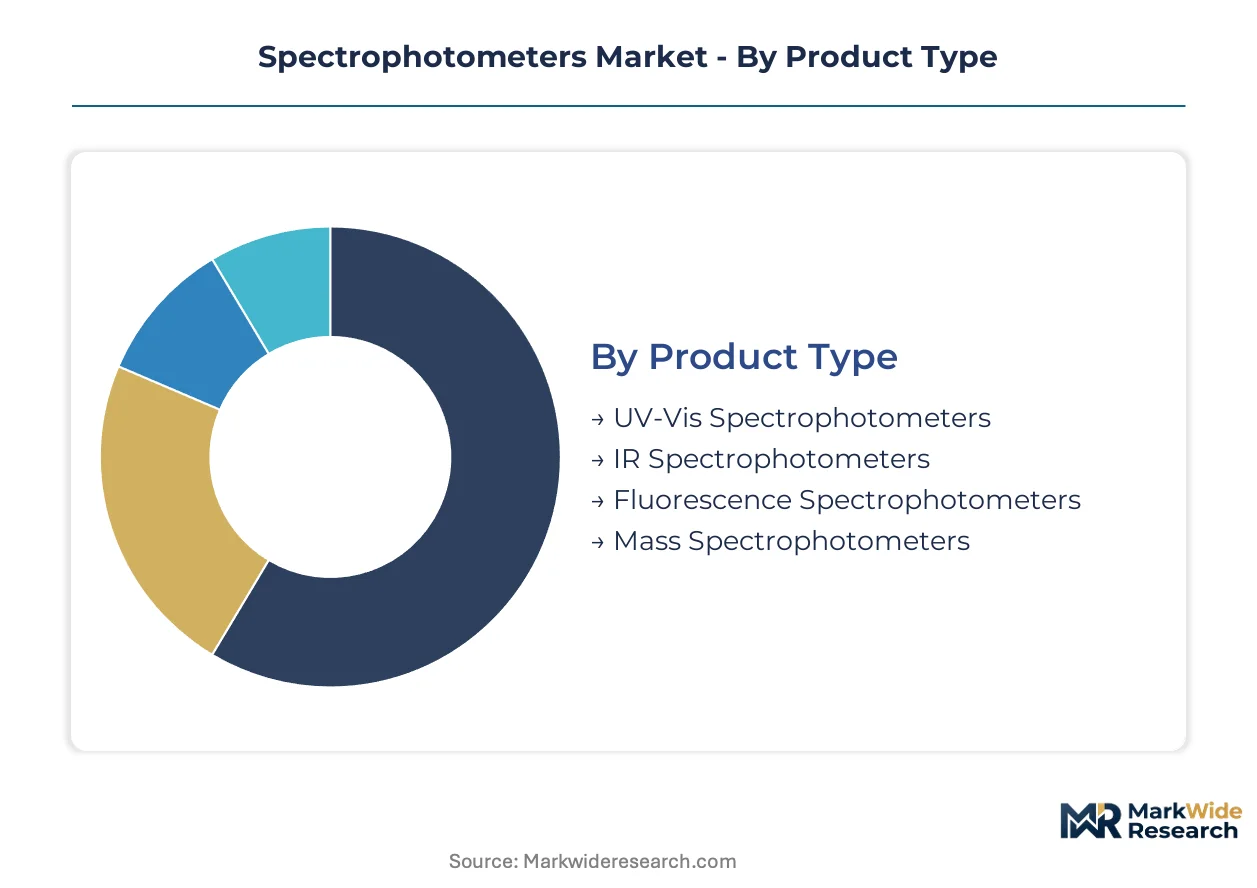
Spectrophotometer procurement patterns diverge sharply between integrated multi-technique platforms and standalone benchtop units, with pharmaceutical quality control workflows driving distinct specification requirements across optical configurations. Segmentation reveals how detection sensitivity thresholds, throughput demands, and regulatory validation burdens reshape vendor product architectures and pricing strategies.
Product Type:
Standalone UV-Vis systems dominate routine analytical workflows while fluorescence and mass spectrophotometry platforms increasingly embed into chromatography-integrated configurations for trace-level quantification.
- UV-Vis Spectrophotometers:Single-beam and double-beam architectures span 190-1100 nm with silicon photodiode or photomultiplier detection. Pharmaceutical manufacturers in India and China deploy these for dissolution testing and assay validation under USP and EP wavelength accuracy protocols. Array detector variants are displacing scanning monochromators in high-throughput generic drug release workflows.
- Fluorescence Spectrophotometers:These systems exploit Stoke's shift phenomena to achieve detection limits orders of magnitude below absorbance-based methods, utilizing xenon lamp excitation and photomultiplier emission detection. Biopharma research clusters in Germany, Japan, and the United States drive procurement for protein folding studies and impurity profiling where single-molecule sensitivity proves essential.
- IR Spectrophotometers:Fourier-transform architectures with Michelson interferometers enable molecular fingerprinting for polymer identification and contaminant screening. REACH Article 33 compliance obligations across European industrial labs sustain replacement demand for portable and benchtop FTIR units.
- Mass Spectrophotometers:These hyphenated platforms couple ionization sources with mass analyzers for molecular weight confirmation, occupying premium price tiers in pharmaceutical metabolite identification and environmental persistent organic pollutant analysis.
Volume placements concentrate in UV-Vis configurations; the steepest expansion trajectory belongs to fluorescence platforms in academic and biopharma research settings.
Technology:
Cost stratification separates research-grade double-beam systems from economy single-beam units, with portable architectures capturing point-of-use applications previously served by centralized laboratory infrastructure.
- Double Beam Technology:Simultaneous reference and sample channel measurement eliminates source fluctuation errors, delivering the photometric precision required for pharmacopeial compliance. GMP-certified facilities in Germany, the United States, and Japan specify these for instrument qualification protocols under USP Chapter 857.
- Array Technology:Photodiode array and charge-coupled device detectors enable parallel wavelength acquisition across full spectral ranges in milliseconds. Generic drug manufacturers in Hyderabad and Shanghai adopt these to compress batch release timelines where speed outweighs ultimate sensitivity.
- Single Beam Technology:Sequential reference-then-sample measurement architectures occupy economy pricing tiers for educational and preliminary screening applications.
- Portable Technology:Battery-powered units with fiber-optic probes enable field environmental monitoring and at-line pharmaceutical manufacturing testing, though detection limits trail benchtop equivalents.
Double-beam systems anchor revenue concentration in regulated pharmaceutical environments; array architectures are gaining share fastest in high-throughput quality control settings.
End User:
Customer type determines software sophistication requirements, with pharmaceutical buyers demanding LIMS integration and academic purchasers prioritizing modular upgrade paths.
- Pharmaceuticals:GMP-certified manufacturers deploy UV-Vis for dissolution and content uniformity testing, fluorescence for impurity profiling, and hyphenated LC-UV systems for stability-indicating methods. CDSCO in India and NMPA in China are tightening validation documentation requirements for imported instrumentation.
- Environmental Labs:EPA methods under the Safe Drinking Water Act mandate specific absorbance protocols for contaminant detection, compelling instrument sensitivity upgrades in United States contract testing organizations.
- Food & Beverage:Pathogen detection and adulterant screening workflows drive fluorescence and IR platform adoption for supply chain verification.
- Academic Institutions:National Science Foundation and Japan Society for the Promotion of Science funding cycles sustain replacement demand, with service unbundling trends separating capital purchases from validation contracts.
Pharmaceutical procurement generates the largest absolute instrument value; environmental lab demand is expanding most quickly under tightening EPA and ECHA detection thresholds.
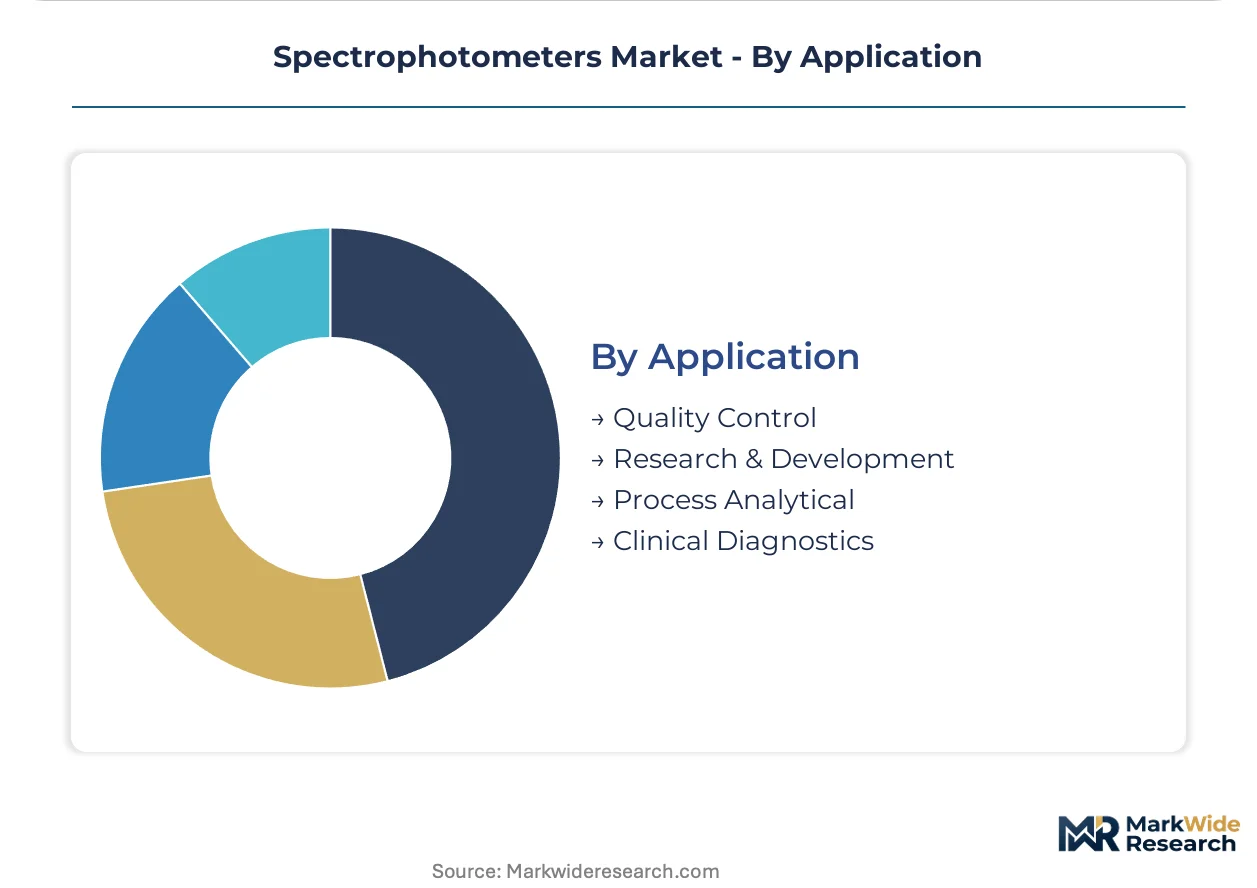
Application:
Maturity gradients separate established quality control protocols from emerging process analytical technology deployments requiring real-time spectral acquisition.
- Quality Control:Batch release testing for pharmaceuticals, environmental compliance, and food safety constitutes the largest installed base, with wavelength accuracy verification and stray light testing mandated under pharmacopeial chapters.
- Research & Development:Method development for novel therapeutic modalities and environmental contaminant characterization demands modular platforms accommodating multiple detection modalities.
- Process Analytical:At-line and in-line spectrophotometric monitoring enables real-time release testing in continuous manufacturing workflows, though validation complexity constrains adoption.
- Clinical Diagnostics:UV-Vis absorbance measurements support hemoglobin and bilirubin quantification in centralized laboratory settings.
Quality control applications dominate current placements; process analytical deployments are climbing the fastest as pharmaceutical manufacturers adopt continuous manufacturing paradigms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad and Mumbai pharmaceutical corridors are driving UV-Vis instrument procurement for GMP-certified quality control workflows, while Shanghai and Suzhou manufacturing clusters sustain fluorescence platform demand for biopharma research applications.
United States
EPA monitoring mandates under the Safe Drinking Water Act and Clean Water Act compel environmental testing laboratories in California and Texas to upgrade absorbance detection specifications. The agency's prescribed protocols for contaminant fingerprinting sustain replacement cycles in contract testing organizations. Boston and San Diego biopharma research clusters anchor fluorescence spectrophotometer procurement for protein characterization studies.
Germany
REACH Article 33 extended supply chain disclosure obligations expand fluorescence and FTIR deployment across industrial laboratories in Bavaria and North Rhine-Westphalia. ECHA guidance on persistent organic pollutant characterization mandates confirmation methods beyond basic UV-Vis screening. Frankfurt and Hamburg contract testing facilities are upgrading to modular platform configurations accommodating multiple detection modalities.
China
NMPA validation documentation requirements for imported instrumentation tighten as GMP-certified manufacturers in Shanghai and Suzhou scale UV-Vis procurement for dissolution testing workflows. The regulator's instrument qualification protocols align with USP and EP wavelength accuracy standards. Beijing-Tianjin-Hebei research institutes drive fluorescence platform demand for single-molecule sensitivity applications.
India
CDSCO tightening of validation requirements for pharmaceutical manufacturing equipment accelerates instrument replacement in Mumbai and Hyderabad generic drug production clusters. The regulator's GMP enforcement drives procurement of double-beam systems for pharmacopeial compliance. Bangalore academic institutions sustain fluorescence spectrophotometer demand through DST and DBT research funding cycles.
Japan
METI support for advanced analytical instrumentation sustains replacement demand in Kanto and Kansai pharmaceutical manufacturing zones. PMDA pharmacopeial alignment with USP and EP standards drives qualification protocol investments. Tokyo and Osaka biopharma research clusters anchor premium fluorescence platform procurement for impurity profiling applications.
Spectrophotometers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the spectrophotometer landscape, with integrated technology conglomerates holding chromatography-spectroscopy convergence advantages over standalone optical specialists. The vendor base separates into three strategic archetypes: diversified life science conglomerates with multi-technique portfolios, precision optics specialists with localized service networks, and component-integrated platform assemblers. Competitive positioning hinges on pharmacopeial validation documentation depth and LIMS connectivity protocol breadth rather than hardware specifications alone. M&A activity targets software stack capabilities and regional service infrastructure, while technology licensing agreements proliferate around array detector architectures.
Among diversified analytical instrumentation conglomerates, Agilent Technologies and Thermo Fisher Scientific occupy positions exemplifying chromatography-spectroscopy integration strategies, while Shimadzu Corporation anchors the precision optics specialist archetype through its Asia-Pacific service network density. These three entities represent distinct competitive vectors: Agilent leverages LC-UV convergence for pharmaceutical workflows, Thermo Fisher sustains catalog breadth across UV-Vis, IR, and fluorescence platforms, and Shimadzu concentrates compliance support for GMP-certified facilities. Their collective positioning illustrates how software sophistication and validation documentation depth now outweigh raw optical performance in procurement decisions.
| Leading Market Players |
|---|
| Agilent Technologies |
| Analytik Jena |
| Thermo Fisher Scientific |
| tec5USA |
| Hunter Associates Laboratory |
| Shimadzu Corporation |
| Mettler-Toledo |
| CRAIC Technologies |
| PerkinElmer |
| Others |
Supply Flow & Price Mechanics
Double-beam qualification-grade systems and economy single-beam units diverge by pharmacopeial certification depth, with that gap manifesting in both component sourcing strategies and buyer procurement budgets across GMP-certified pharmaceutical clusters in Germany, Japan, and the United States.
Pricing Analysis
Value-based pricing anchors on detection sensitivity thresholds and throughput guarantees rather than hardware specifications alone. Three-tier pricing structure across premium, standard, and economy levels separates research-grade fluorescence platforms from routine UV-Vis units and portable field instruments. Cost compression in economy single-beam architectures intensifies because Indian and Chinese generic manufacturers prioritize speed over stray light performance. Academic institutions exhibit highest price sensitivity due to unbundled service contracts, while GMP-certified pharmaceutical buyers absorb premium tiers for validation documentation depth.
Supply Chain Analysis
Dual-sourcing requirements for high-performance gratings and photomultiplier tubes compel instrument vendors to qualify secondary suppliers in Germany and Japan alongside primary Japanese component houses. Optical component dependencies rest on specialized interferometer assemblies, xenon excitation sources, and silicon photodiode arrays. Single-source vulnerability concentrates in Michelson interferometer fabrication for FTIR platforms, where qualified alternative suppliers remain limited. Distribution runs through authorized regional service networks for qualification support, with direct OEM relationships dominating high-volume pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Article 33 and EPA monitoring mandates create barrier-to-entry moats for vendors with deep pharmacopeial validation expertise.
For Market Incumbents: Deepen backward integration into photodiode array detector supply to secure throughput advantages as generic manufacturers compress batch release timelines. Fortify LIMS connectivity protocol libraries against software-native entrants targeting unbundled academic procurement. Array technology substitution threatens scanning monochromator revenue streams in routine quality control segments.
For New Entrants and Emerging Players: Contract testing organizations in Vietnam and Singapore present the most penetrable channel partner type for EU and US export compliance outsourcing. Portable Raman substitution in field environmental monitoring creates white-space for benchtop UV-Vis displacement. Target modular platform configurations accommodating multiple detection modalities as the specific go-to-market angle for European REACH-driven replacement cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with precision optics specialists possessing dense Asia-Pacific service networks given India and China pharmaceutical scaling. Long-term viability hinges on software stack differentiation as hardware commoditization accelerates across routine analytical tiers. Watch ECHA guidance expansion on persistent organic pollutant characterization as the inflection signal for fluorescence and IR platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Validation Documentation Investment | USP Chapter 857 compliance separates premium vendors in GMP-certified pharmaceutical procurement. |
| Chromatography-Spectroscopy Platform Integration | LC-UV convergence enables real-time peak identification for biopharma metabolite analysis workflows. |
| Regional Service Network Expansion | Localized qualification support captures CDSCO and NMPA-driven replacement cycles in Mumbai and Shanghai clusters. |
| Array Detector Architecture Licensing | Photodiode array technology partnerships accelerate high-throughput generic drug release adoption. |
| Software Stack Acquisition | LIMS and ELN connectivity capabilities differentiate procurement decisions beyond optical specifications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with instrument qualification engineers, pharmaceutical manufacturing directors, environmental lab managers, and academic procurement officers. ECHA substance restriction databases, EPA method protocols, USP pharmacopeial chapters, and CDSCO equipment validation guidelines provided regulatory boundary conditions. Bottom-up installation base estimates triangulated against top-down analytical instrumentation market sizing.
Granularity-level modeling deployed product type, technology architecture, end-user industry, and application workflow dimensions across the analysis window. CAGRs derived from instrument replacement cycle analysis, regulatory mandate timeline alignment, and regional pharmaceutical manufacturing capacity expansion. Detection sensitivity threshold evolution and software integration complexity served as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where ECHA persistent organic pollutant guidance expansion or EPA detection protocol revisions could materially shift the outlook for fluorescence and IR platform demand. Forecasts reflect assumptions around GMP certification enforcement consistency and academic funding cycle stability. A model refresh is warranted upon material change in REACH Article 33 supply chain disclosure obligation scope or NMPA imported instrumentation validation documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Thermogravimetric Analyzer Market