
 Asphalt Concrete Market | 2026-2036
Asphalt Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Concrete Market Outlook
Performance-based maintenance contracts are restructuring how agencies procure asphalt concrete, shifting capital expenditure into lifecycle service agreements. CRH PLC leverages its vertically integrated aggregates network to secure multi-year pavement contracts across North American jurisdictions. Vulcan Materials Company anchors its position through captive quarry access and dense logistics infrastructure in the southeastern United States. Astec Industries differentiates through equipment-technology bundling that ties plant sales to ongoing service retainers.
Asphalt concrete is a composite material comprising mineral aggregate bound with petroleum-derived bitumen, typically engineered to withstand dynamic loading cycles exceeding one million repetitions at specified temperatures. Hot mix asphalt dominates installed base volumes but faces margin compression from energy intensity, while polymer modified blends command premium positioning in airport runways and heavy-duty port facilities where rutting resistance specifications are most stringent. Warm mix formulations are gaining fastest penetration among municipal buyers seeking to satisfy federal emissions benchmarks without sacrificing structural performance.
The Federal Highway Administration mandates Superpave mix design protocols for interstate projects, while EPA National Emission Standards for Hazardous Air Pollutants constrain plant operations. State DOTs increasingly require reclaimed asphalt pavement inclusion rates that alter binder sourcing strategies. Stakeholders must monitor how Buy America domestic content thresholds and evolving MUTCD pavement marking standards reshape supplier qualification criteria.
Market Dynamics
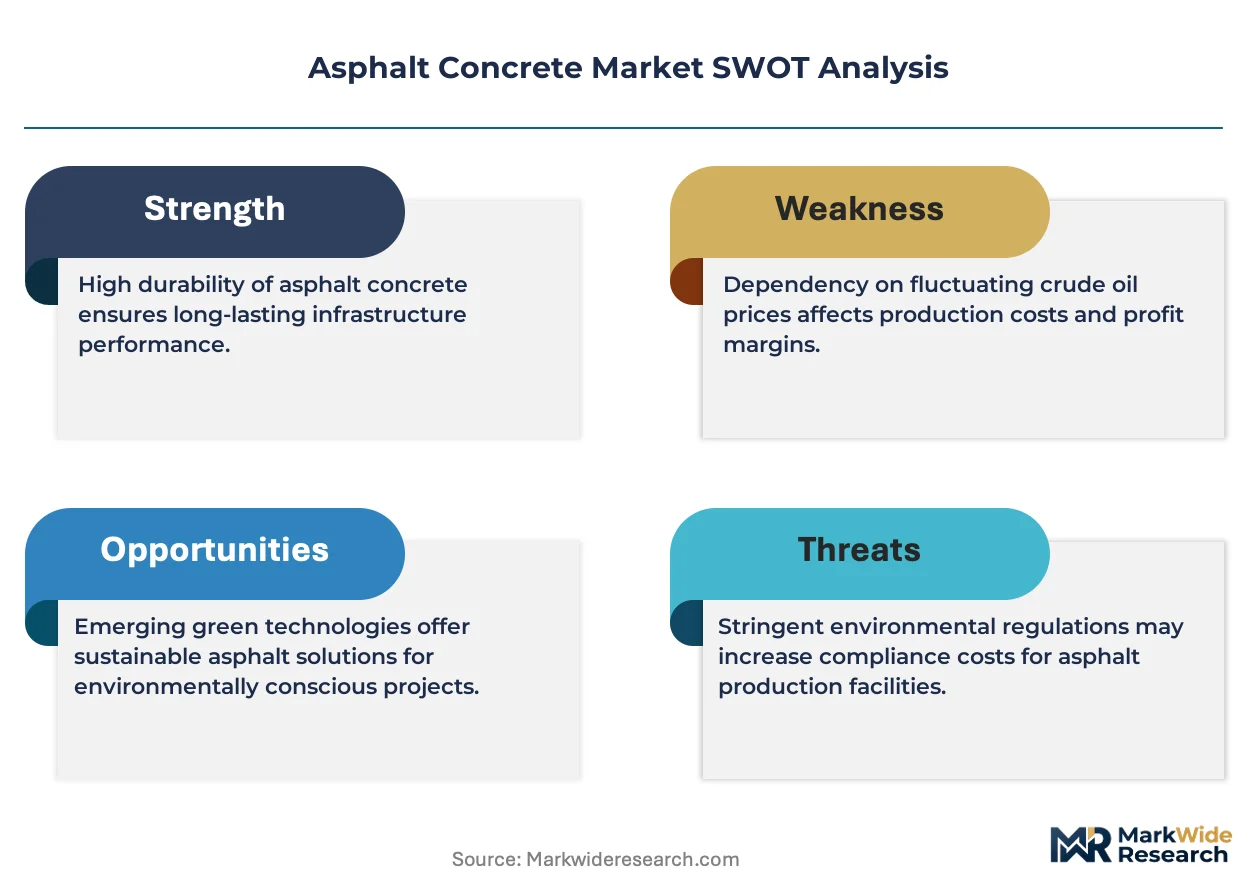
Warm mix asphalt technology is compressing energy requirements and emissions profiles while state DOTs rewrite procurement protocols around lifecycle performance rather than upfront tonnage pricing.
Growth Catalysts
- Highway Rehabilitation Mandates:The Federal Highway Administration's infrastructure spending frameworks are channeling federal matching funds into pavement reconstruction across interstate corridors.
- Warm Mix Adoption:Foaming and chemical additive processes are cutting production temperatures, satisfying EPA National Emission Standards for Hazardous Air Pollutants without structural compromise.
- China Expressway Completion:Provincial infrastructure budgets in Jiangsu, Guangdong, and Sichuan are prioritizing final network linkages in national trunk highway systems.
Market Restraints
- Bitumen Price Volatility:Crude oil feedstock fluctuations transmit directly into binder cost structures, compressing margins for fixed-price highway contracts.
- Quarry Access Concentration:Quality aggregate deposits cluster in specific geologic formations, creating captive supply zones around southeastern Appalachian and midwestern limestone belts.
- Reclaimed Asphalt Pavement Technical Limits:High RAP inclusion rates degrade binder performance in heavy-duty applications, constraining circular economy targets for airport and port pavements.
Strategic Opportunities
- India National Highway Expansion:The Bharatmala program and NHAI's expressway corridors present underpenetrated demand for polymer-modified surfaces in tropical climates.
- Performance-Based Contracting:Availability-payment and annuity-based maintenance agreements are opening multi-decade service revenue streams beyond material supply.
- Carbon Accounting Integration:Environmental Product Declarations and embodied carbon thresholds in public procurement are creating first-mover advantages for low-temperature mix suppliers.
Industry Challenges
- Mix Design Certification Bottlenecks:Superpave Level 3 and performance-graded binder testing require specialized laboratory capacity that strains regional technical resources.
- Plant Relocation Costs:Mobile asphalt plant redeployment for remote infrastructure projects demands capital-intensive logistics coordination and site preparation.
- Skilled Operator Shortages:Paver and compactor automation is outpacing training program throughput, creating field execution gaps in quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Concrete Market |
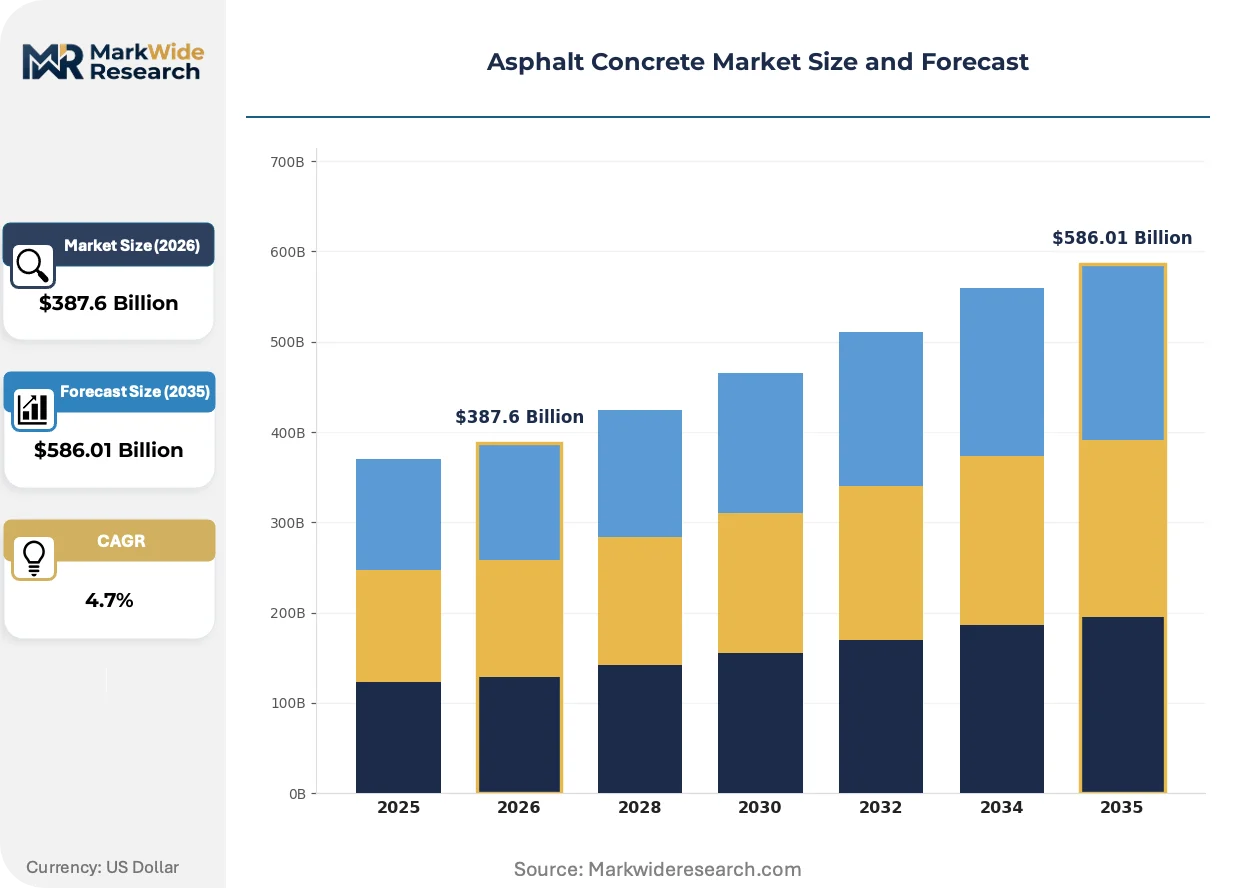
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $586.01 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Mix, Warm Mix, Cold Mix, Polymer Modified Application: Pavement, Road Construction, Airport Runways, Parking Lots End User: Government, Private Contractors, Industrial, Infrastructure Material: Aggregate, Asphalt Binder, Reclaimed Asphalt Pavement, Filler |
| Companies Covered | Astec Industries, ADM/FAYAT GROUP, CRH PLC, Blaw-Knox, Gencor Industries, Vulcan Materials Company, Ammann America, BOMAG Americas, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Concrete Market Strategic Shifts
Digital compaction monitoring and real-time density sensing are replacing manual core sampling, compressing quality assurance cycles while data-driven maintenance scheduling extends pavement service lives.
Intelligent compaction systems with integrated GPS and accelerometer feedback are electrifying quality control protocols on highway projects. State DOTs in Texas, Florida, and California are mandating continuous compaction monitoring for major contracts. The technology is electrifying competitive differentiation among contractors who can demonstrate uniform density achievement without lane closures for core extraction.
The EPA's National Emission Standards for Hazardous Air Pollutants are tightening particulate and volatile organic compound limits at batch and drum plants. Operators face retrofit investments in baghouse filtration and thermal oxidizers or plant replacement decisions. California's South Coast Air Quality Management District and Texas Commission on Environmental Quality are implementing the most stringent state-level interpretations, forcing capital deployment toward closed-system production designs.
Asset management contracts are displacing traditional design-bid-build procurement for municipal and county road networks. Engineering firms and material suppliers are bundling pavement condition assessment, predictive maintenance algorithms, and resurfacing execution into multi-year agreements. This pattern is most visible in the United Kingdom's Highway England frameworks and emerging county-level programs across Ohio and Pennsylvania.
Asphalt Concrete Market Segmentation
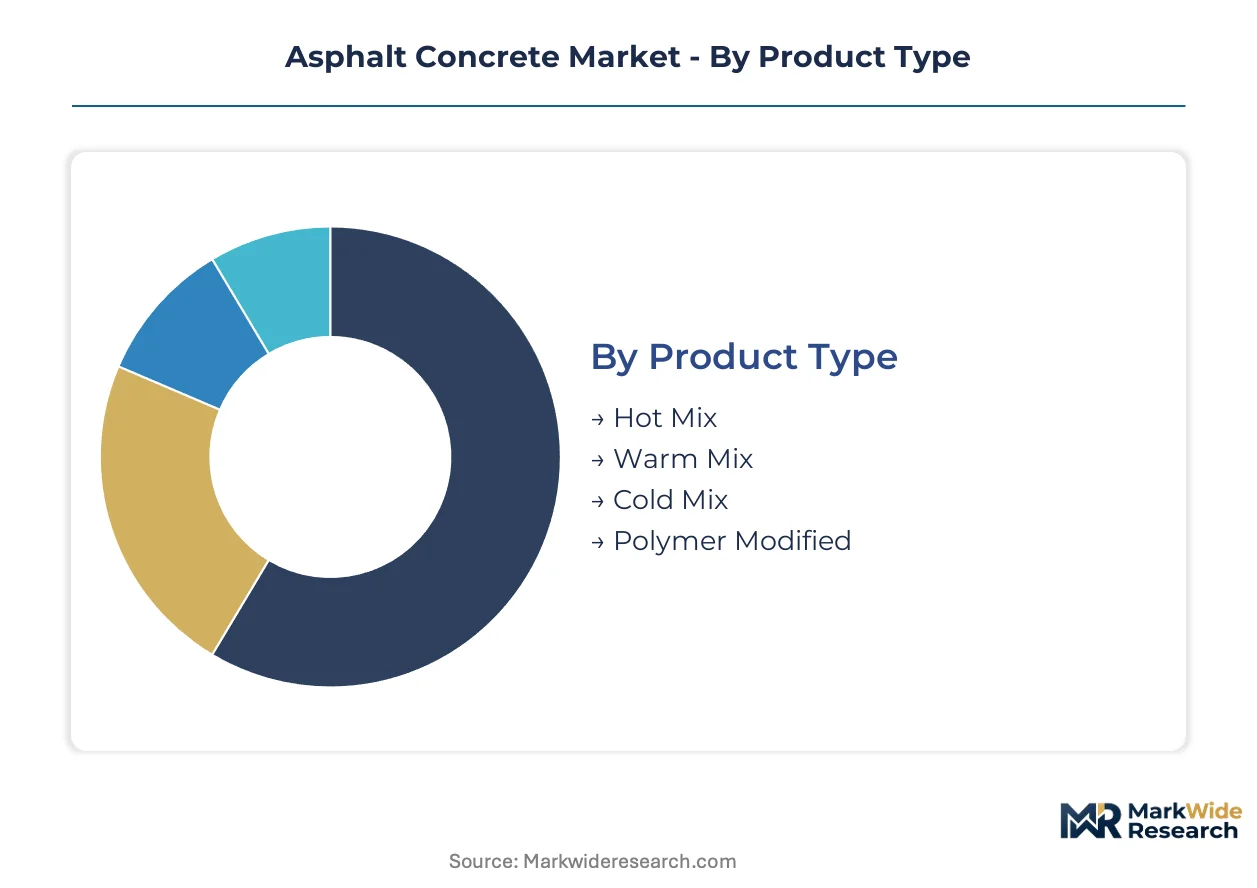
Segmentation in asphalt concrete reveals how specification requirements fragment procurement across infrastructure tiers. Mix design protocols, loading duty, and environmental compliance reshape supplier qualification and pricing architecture.
Product Type:
FHWA Superpave certification governs interstate-grade products while state DOTs apply tiered approval tiers for municipal and industrial applications.
- Hot Mix:Petroleum-derived bitumen binds mineral aggregate at elevated temperatures exceeding 150°C. Demand concentrates in federal-aid highway reconstruction across Texas, Florida, and California where structural performance specifications remain non-negotiable under FHWA mandates.
- Warm Mix:Foaming agents and chemical additives reduce production temperatures by 20-40°C while preserving binder adhesion. Municipal buyers in EPA non-attainment zones adopt this formulation fastest to satisfy National Emission Standards for Hazardous Air Pollutants without core property sacrifice.
- Cold Mix:Emulsified bitumen permits ambient-temperature placement for temporary patches and remote access roads.
- Polymer Modified:Styrene-butadiene-styrene and ethylene-vinyl-acetate elastomers enhance rutting resistance for heavy-duty loading cycles.
Leading the category by volume: Hot Mix. Growing fastest: Warm Mix.
Application:
Loading intensity and surface tolerance specifications create four distinct procurement tiers with divergent qualification burdens.
- Pavement:Highway surface courses bearing dynamic axle loads demand Superpave Level 3 mix design validation. State DOTs in Ohio and Pennsylvania are shifting procurement toward performance-based contracts that penalize premature distress.
- Road Construction:Base and binder courses absorb structural loading beneath finished surfaces. County-level agencies across the southeastern United States specify reclaimed asphalt pavement inclusion rates that alter material sourcing economics.
- Airport Runways:FAA pavement design standards mandate Marshall stability thresholds and specific gravity tolerances stricter than highway equivalents.
- Parking Lots:Light-duty commercial surfaces prioritize initial cost over extended service life in private development projects.
Pavement commands the largest installed base. Airport runways carry the steepest specification premium.
End User:
Procurement sophistication separates public agency buyers from private contractors, with distinct contract structures and technical oversight requirements.
- Government:Federal Highway Administration matching funds flow through state DOTs with Buy America domestic content verification. Highway rehabilitation programs channel material demand through design-bid-build and emerging asset management frameworks.
- Private Contractors:Commercial developers and residential subdivisions prioritize schedule compression over lifecycle optimization.
- Industrial:Port authorities and heavy manufacturing facilities specify polymer-modified surfaces for container handling and equipment movement zones.
- Infrastructure:Utility corridors and rail intermodals require specialized drainage and subgrade stabilization.
Government agencies dominate tonnage offtake. Industrial end users deliver the highest margin realization per unit.
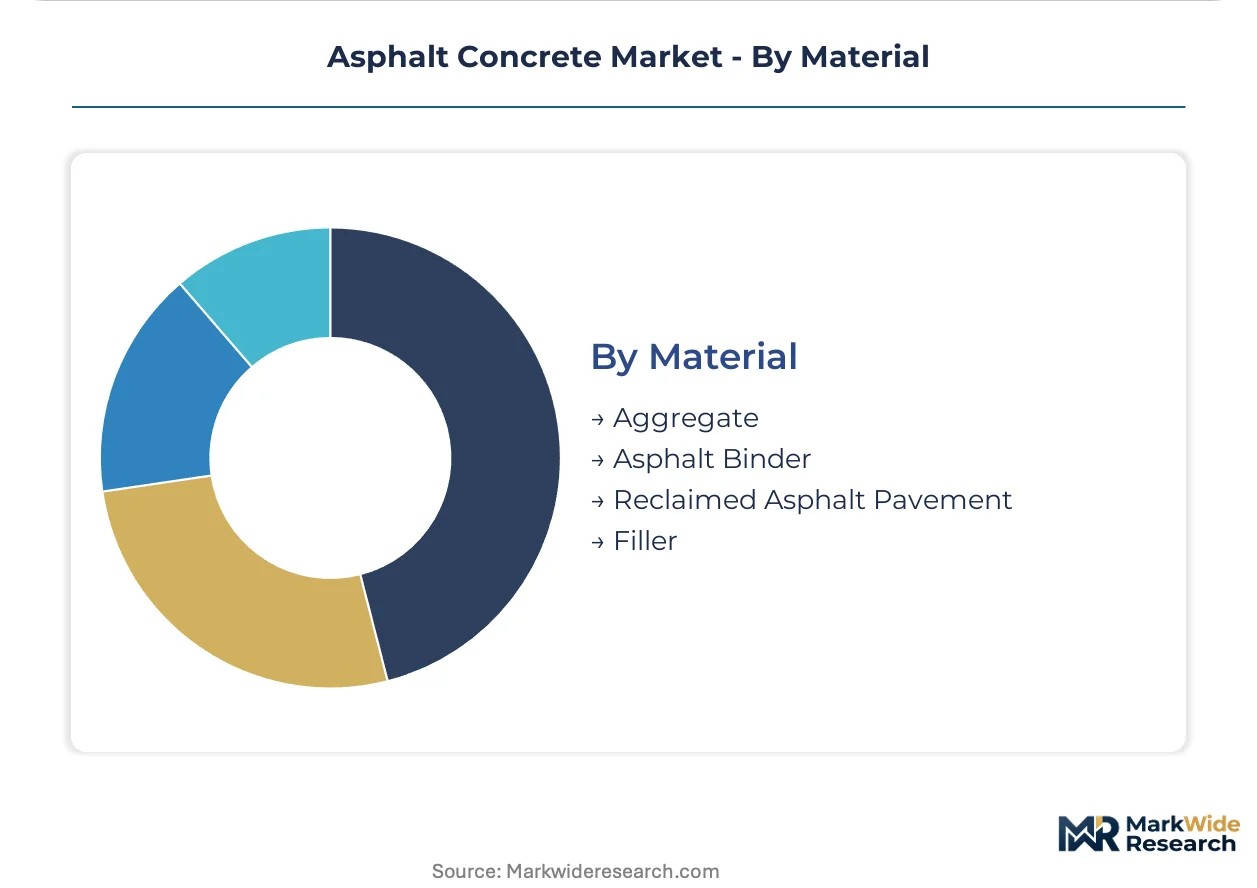
Material:
Supply geography and circular economy targets reshape sourcing strategies across the four constituent material classes.
- Aggregate:Crushed limestone and granite provide structural skeleton with specified gradation bands. Quality deposits cluster in Appalachian and midwestern formations, creating captive supply zones around Vulcan Materials and CRH PLC quarry networks.
- Asphalt Binder:Vacuum-distilled petroleum residuum constitutes 4-7% of mix mass but 30-40% of material cost. Crude price volatility transmits directly into highway contract margin compression.
- Reclaimed Asphalt Pavement:Milled surface material substitutes for virgin aggregate and binder in lower-duty applications. State DOTs in Wisconsin and Texas mandate minimum inclusion rates that strain quality control protocols.
- Filler:Hydrated lime and mineral dust modify binder rheology and moisture resistance.
Aggregate represents the dominant mass fraction. Reclaimed asphalt pavement is expanding most quickly under circular economy procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asphalt concrete production concentrates near quality aggregate deposits and major consumption corridors, creating distinct regional supply-demand configurations. China consumes the largest absolute tonnage for expressway completion, while the United States drives premium-mix specification evolution through federal procurement frameworks.
United States
Federal Highway Administration matching funds are channeling material demand toward interstate rehabilitation across Texas, Florida, and California. State DOTs in Ohio and Pennsylvania are rewriting procurement protocols around performance-based lifecycle contracts rather than upfront tonnage pricing. The southeastern Appalachian limestone belt anchors captive aggregate supply zones around major quarry networks.
China
Provincial infrastructure budgets in Jiangsu, Guangdong, and Sichuan are prioritizing final network linkages in the national trunk highway system. The Ministry of Ecology and Environment is tightening emissions benchmarks at batch and drum plants in non-attainment zones. The Yangtze River Delta corridor concentrates warm-mix technology deployment for municipal buyers seeking federal compliance without structural compromise.
India
The Bharatmala program and NHAI expressway corridors are generating underpenetrated demand for polymer-modified surfaces in tropical climates. The Bureau of Indian Standards is developing performance-graded binder specifications aligned with heavy-duty loading cycles. Western Maharashtra and Gujarat industrial corridors are attracting plant investment to serve port and logistics infrastructure expansion.
Germany
Bundesministerium für Verkehr und digitale Infrastruktur frameworks are mandating reclaimed asphalt pavement inclusion rates that alter binder sourcing strategies. The KBA influences construction equipment emissions standards that reshape plant technology selection. The Rhine-Ruhr and Bavarian construction clusters are piloting carbon-accounting integration through Environmental Product Declarations in public procurement.
Saudi Arabia
Vision 2030 giga-projects and logistics corridor development are driving specification-grade demand for airport runways and heavy-duty port facilities. The Saudi Food and Drug Authority and national environmental regulators are implementing construction materials standards that affect import qualification. The Eastern Province and Riyadh construction zones are concentrating demand for polymer-modified blends where rutting resistance specifications are most stringent.
Asphalt Concrete Market Competitive Environment
Top-tier vendors anchor integrated aggregates-to-pavement service models, while mid-scale equipment fabricators compete on technology bundling and regional plant deployment. The market structure reflects consolidation around quarry access and logistics infrastructure alongside fragmentation in specialized mixing equipment. Two strategic archetypes dominate: vertically integrated materials conglomerates controlling captive aggregate supply, and technology-forward equipment specialists bundling plant sales with service retainers. Competitive moves center on multi-year pavement contract capture and warm-mix technology licensing for emissions compliance.
Among North American-based materials suppliers, CRH PLC and Vulcan Materials Company exemplify the integrated archetype through quarry network control and dense logistics infrastructure. Astec Industries occupies a position on the equipment-technology vector, representing the bundling specialist model that ties plant sales to ongoing service agreements. These three names illustrate how supply-side concentration around aggregate access and production technology shapes competitive positioning across federal-aid and municipal procurement tiers.
| Leading Market Players |
|---|
| Astec Industries |
| ADM/FAYAT GROUP |
| CRH PLC |
| Blaw-Knox |
| Gencor Industries |
| Vulcan Materials Company |
| Ammann America |
| BOMAG Americas |
| Owens Corning |
| Others |
Value Chain & Pricing Dynamics
Skilled paver operator concentration in the southeastern United States widens pricing-tier spreads between premium performance-based contracts and commodity municipal bids, as labor-cost differentials compound with aggregate haul distances to stratify regional procurement economics.
Pricing Analysis
Margin tightening in municipal-grade hot mix reflects bitumen feedstock volatility and fixed-price highway contract exposure. Three-tier pricing structure across polymer-modified, warm-mix, and standard hot-mix levels separates airport runway specifications from county road maintenance. Price differentiation hinges on Superpave certification grade and captive quarry access. State DOTs in EPA non-attainment zones show least price sensitivity due to emissions compliance mandates, while private commercial developers drive hardest bargain on initial tonnage rates.
Supply Chain Analysis
Bitumen supply rests on Gulf Coast refinery capacity and Canadian heavy crude import channels, with quality aggregate deposits clustering in Appalachian and midwestern limestone formations. Crude oil residuum, crushed granite, and reclaimed asphalt pavement constitute the three critical input streams. Single-source vulnerability concentrates around specialized polymer modifier suppliers for SBS-modified blends. Distribution runs through rail-served terminals and truck haul networks radiating from captive quarry zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asphalt concrete market functions as a cost-of-compliance arena where EPA National Emission Standards for Hazardous Air Pollutants erect capital-intensive barriers that favor incumbents with retrofit-capable plant fleets and baghouse filtration infrastructure.
For Market Incumbents: Hedge against bitumen price volatility through backward integration into terminal storage assets or long-term binder supply agreements with Gulf Coast refiners. Secure multi-year performance-based contracts with state DOTs in Ohio and Pennsylvania to lock in lifecycle revenue streams before warm-mix technology commoditizes emissions advantages. Prioritize quarry network densification in the southeastern limestone belt to defend delivered-cost position against regional challengers. For New Entrants and Emerging Players: Digital equipment-technology bundling offers a channel route to bypass capital-intensive quarry ownership, pairing automated plant controls with predictive maintenance software subscriptions. Target municipal buyers in Texas and Florida seeking Superpave Level 3 certification without legacy plant retrofit burdens. Lead with warm-mix technology licensing as a service model rather than asset-heavy production capacity. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated materials conglomerates given federal infrastructure matching fund flows and Buy America domestic content thresholds. Long-term viability favors quarry-network owners with dense logistics infrastructure over pure-play equipment fabricators. Watch for state DOT procurement rule shifts toward availability-payment contracts as the inflection signal for service-revenue multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Storage | Captive asphalt terminal access insulates margin compression from crude price volatility in fixed-price highway contracts. |
| Warm-Mix Technology Licensing | EPA emissions compliance without structural performance sacrifice opens municipal procurement doors in non-attainment zones. |
| Performance-Based Contract Capture | Multi-year lifecycle agreements with state DOTs convert material supply into annuity-style maintenance revenue streams. |
| Quarry Network Densification | Appalachian and midwestern limestone belt consolidation creates delivered-cost moats against regional competitors. |
| Digital Compaction Monitoring Deployment | Intelligent compaction systems with GPS feedback satisfy Texas and California DOT mandates while differentiating contractor quality control. |
Study Parameters
Multi-period observation of state DOT procurement volumes, plant emissions retrofit investments, and reclaimed asphalt pavement inclusion rates anchored the trend analysis, supplemented by interviews with asphalt plant operators, state transportation procurement officers, quarry network managers, and warm-mix technology licensors. Secondary validation drew from Federal Highway Administration obligation data, EPA compliance filings, state DOT bid tabulations, and industry association production surveys. Bottom-up project pipeline tracking and top-down infrastructure spending allocation models were triangulated to reconcile volume estimates.
Segment-weighting across mix type, application duty, and end-user procurement sophistication shaped the analytical framework over the projection horizon. Modeled dimensions included hot-warm-cold-polymer product tiers, highway-airport-industrial application intensity, and government-private-infrastructure buyer categories. CAGRs were derived from elasticity-adjusted demand curves incorporating bitumen price sensitivity and federal matching fund flow assumptions. Warm-mix adoption curves and performance-based contract penetration served as industry-specific forecast inputs.
The model holds under steady federal infrastructure appropriation levels and stable crude feedstock availability; deviation in EPA enforcement intensity or state DOT procurement rule shifts would shift volume and margin trajectories. Forecasts reflect documented assumptions regarding rehabilitation program continuity and emissions technology cost curves. A small set of named triggers—bitumen price spike magnitude, Superpave specification revisions, and quarry permitting delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Facade Gasket Market
Construction and Engineering
Asia Pacific Sanitaryware Market
Construction and Engineering
US HVAC Systems Market
Construction and Engineering
Residential Furnaces Market
Construction and Engineering
Construction Engineering Services Outsourcing Market
Construction and Engineering
Mine Ventilation System Market
Construction and Engineering
Asia-Pacific Cement Market
Construction and Engineering
Drill Bit Market
Construction and Engineering
North America Steel Roofing Market
Construction and Engineering
Germany Aluminum Door and Window Market
Construction and Engineering
Pharmaceutical Material Handling Equipment Market
Construction and Engineering
Compaction Machines Market
Construction and Engineering
Air-Cooled Heat Exchangers Market
Construction and Engineering
Indonesia Infrastructure Market
Construction and Engineering
Lightweight Cellular Concrete Market
Construction and Engineering
Architecture Smart Glass Market