
 Butyl Stearate Market | 2026-2036
Butyl Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Butyl Stearate Market Outlook
China is tilting the supply map as domestic oleochemical producers expand fatty acid ester capacity to serve Asia-Pacific cosmetic and lubricant demand. KLK Oleo leverages integrated palm oil refining through Southeast Asian plantations to secure feedstock cost advantages. Emery Oleochemicals anchors its position through specialty ester chemistry expertise developed across European and North American technical centers. BASF SE competes on pharmaceutical-grade butyl stearate purity standards that exceed general industrial specifications.
Butyl stearate is a butyl ester of stearic acid, typically manufactured via esterification of stearic acid with n-butanol using acid or enzymatic catalysis, yielding a colorless to pale yellow liquid with a melting point near 19°C and flash point above 160°C. It functions primarily as a lubricant, plasticizer, emollient, and defoaming agent across cosmetic, food-contact, and industrial formulations. Cosmetic applications lead volume absorption due to widespread incorporation in moisturizers and sunscreens where sensory spreadability commands premium positioning. Industrial lubricants represent the fastest-growing application segment as metalworking fluid formulators replace mineral oil derivatives with biodegradable ester bases. The B2B sales channel dominates distribution, reflecting bulk procurement patterns by compounders and contract manufacturers who specify technical certificates of analysis.
REACH registration requirements in Europe mandate full toxicological dossiers for butyl stearate imports above one tonne annually, raising compliance costs for non-European suppliers. FDA food-contact notifications govern butyl stearate use in paper and paperboard applications under specified conditions, while China's GB standards for food additives impose additional testing protocols for import clearance. Stakeholders must monitor regulatory divergence between jurisdictions, as tightening purity thresholds in one region create competitive advantages for suppliers already certified across multiple frameworks.
Market Dynamics
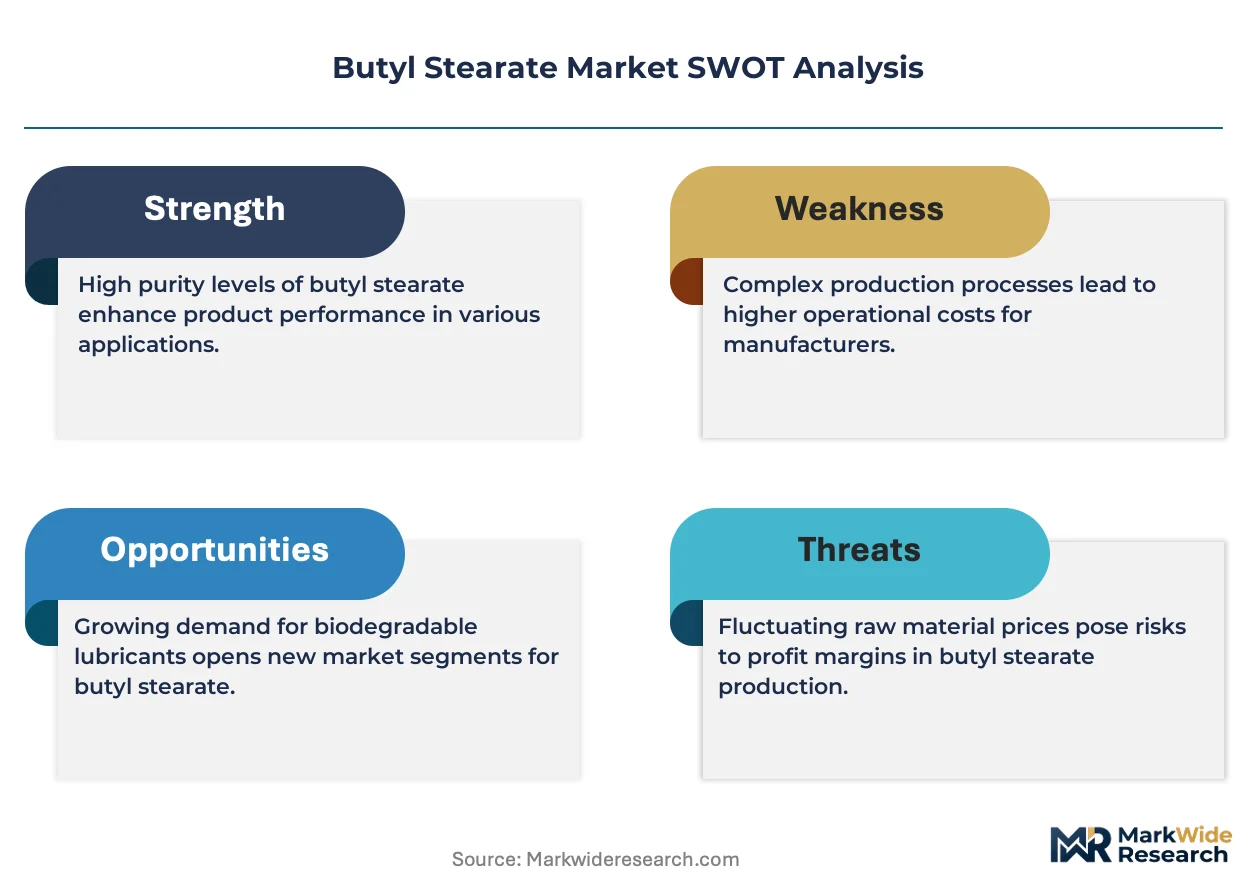
REACH compliance in Europe and FDA food-contact notifications in the United States are tightening purity specifications for butyl stearate, forcing suppliers to restructure certification investments and batch-testing protocols across multiple regulatory frameworks simultaneously.
Growth Catalysts
- Biodegradable lubricant mandates:Metalworking fluid formulators in Germany and Japan are replacing mineral oil derivatives with ester bases to meet corporate sustainability targets and industrial effluent regulations.
- GB standards alignment:China's food additive testing protocols for import clearance are accelerating domestic oleochemical capacity expansion to serve regional cosmetic and lubricant demand.
- Enzymatic catalysis:Specialty chemical producers are adopting biocatalytic esterification processes to reduce energy intensity and improve product color specifications for pharmaceutical-grade applications.
Market Restraints
- Palm oil feedstock volatility:Southeast Asian plantation output fluctuations transmit directly into stearic acid pricing, compressing margin predictability for integrated and non-integrated producers alike.
- REACH dossier costs:Full toxicological registration requirements for imports above one tonne annually raise fixed compliance burdens for non-European suppliers without existing European technical centers.
- Mineral oil substitution limits:High-performance synthetic hydrocarbons retain cost advantages in extreme-pressure lubricant segments where ester hydrolytic stability remains technically inferior.
Strategic Opportunities
- Indian pharmaceutical excipients:CDSCO's evolving purity standards for topical formulations create entry points for certified butyl stearate suppliers in an underpenetrated compounding market.
- Sunscreen emollient premiumization:SPF 50+ formulations in South Korea and Australia are specifying sensory-grade esters that command technical certificates of analysis and long-term supply agreements.
- EU Green Deal chemistry incentives:Biobased carbon content verification schemes are channeling R&D funding toward enzymatic process improvements and waste-fatty-acid feedstock integration.
Industry Challenges
- Cross-jurisdiction certification timelines:Divergent purity thresholds between FDA food-contact notifications, REACH registrations, and China's GB standards force parallel testing workflows that extend product launch cycles by 8-14 months.
- Specialty ester chemist scarcity:Formulation expertise spanning cosmetic sensory evaluation and industrial lubricant tribology concentrates in European and North American technical centers, limiting replication speed in emerging production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyl Stearate Market |
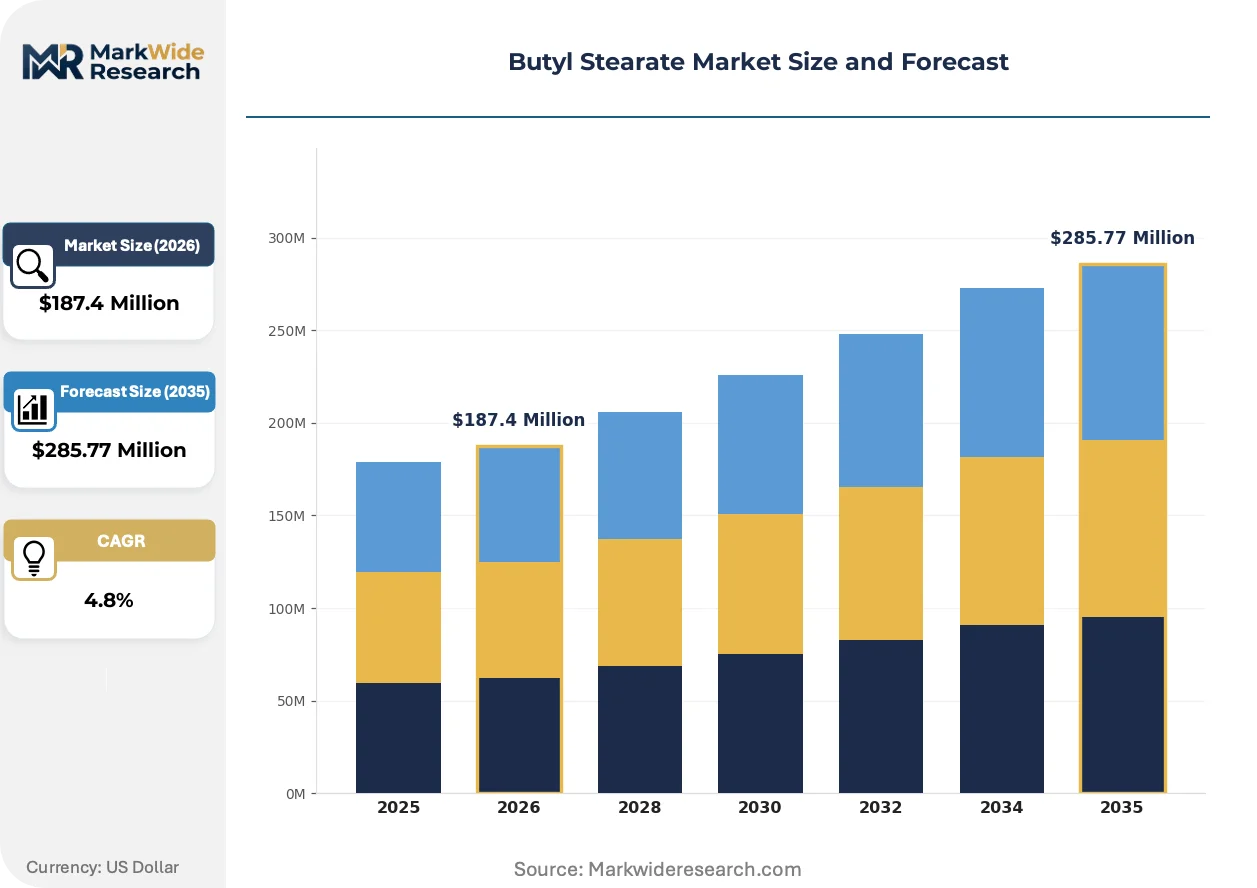
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Stearate, Butyl Oleate, Butyl Palmitate, Butyl Laurate Application: Cosmetics, Industrial Lubricants, Food Additive, Personal Care Products End User: Cosmetic Manufacturers, Food & Beverage Industry, Chemical Companies, Pharmaceutical Firms Distribution Channel: Online Sales, B2B Sales, Retail, Direct Sales |
| Companies Covered | KLK Oleo, Emery Oleochemicals, Wilmar International, BASF SE, Croda International Plc, IOI Oleochemicals, Fine Organics, Gattefossé, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyl Stearate Market Strategic Shifts
Process intensification and regulatory chemistry are restructuring how butyl stearate is manufactured, certified, and procured across cosmetic, pharmaceutical, and industrial end-uses. Three developments are compressing competitive timelines and reconfiguring supplier-buyer relationships.
Enzymatic esterification is hybridizing batch and continuous production architectures. Specialty chemical producers in the Netherlands and Singapore are retrofitting fixed-bed lipase reactors into existing acid-catalysis lines to reduce color bodies and energy consumption simultaneously. This hybridization is enabling pharmaceutical-grade output from assets previously confined to industrial specifications, compressing the capital barrier between tier grades.
REACH authorization requirements for substances of very high concern are extending disclosure obligations down the butyl stearate supply chain. Importers into the European Economic Area must now document full substance identity and safe-use guidance through downstream cosmetic and lubricant formulators. Metalworking fluid compounders with multinational manufacturing footprints are responding by consolidating supplier bases to reduce audit complexity and ensure single-point accountability for SVHC compliance.
Certificate-of-analysis specifications are displacing spot-buying in B2B procurement. Contract manufacturers in China's Yangtze River Delta and Germany's Rhine-Ruhr corridor are locking annual volumes with technical-grade suppliers who guarantee batch-to-batch consistency in acid value, saponification number, and color. This specification-driven contracting is most visible in sunscreen and pharmaceutical topical manufacturing, where formulation rework costs from off-spec emollients exceed raw material price differentials by an order of magnitude.
Butyl Stearate Market Segmentation
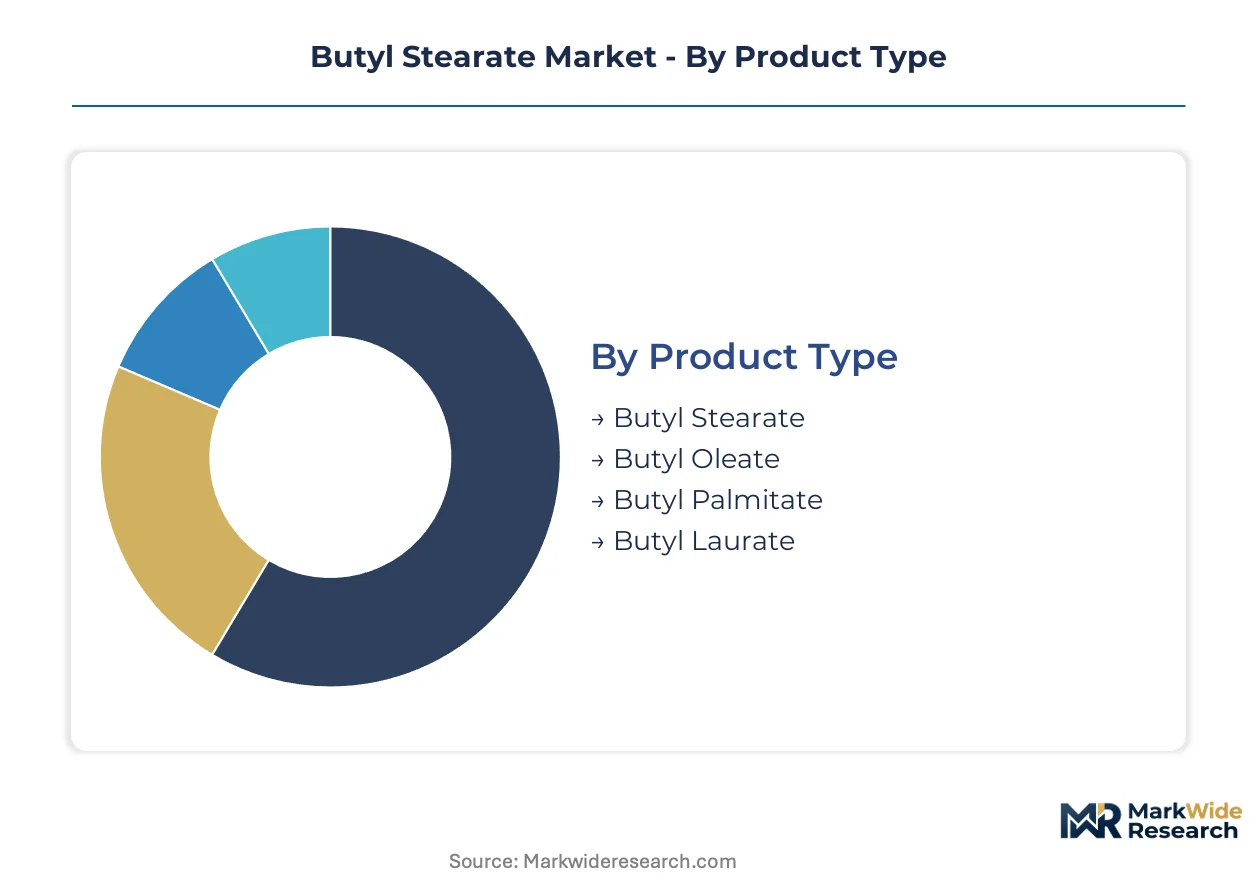
Butyl stearate procurement patterns diverge sharply across end-use specifications, with cosmetic formulators demanding pharmaceutical-grade certificates of analysis while industrial lubricant blenders prioritize bulk volume and biodegradability credentials. Understanding these segment boundaries enables suppliers to align certification investments with buyer willingness to pay for purity tier differentiation.
Product Type:
Use-case spectrum spans industrial lubricant bases demanding oxidative stability through cosmetic emollients requiring low color specifications.
- Butyl Stearate:Saturated C18 fatty acid ester manufactured via acid or enzymatic catalysis, yielding melting point near 19°C and flash point above 160°C. Metalworking fluid formulators in Germany specify this grade for biodegradable cutting fluid bases under corporate sustainability mandates. The dominant share belongs to Butyl Stearate, while Butyl Oleate is closing the gap fastest.
- Butyl Oleate:Unsaturated C18:1 ester with lower pour point and superior low-temperature fluidity compared to stearate analogs. Aviation hydraulic fluid compounders favor this variant for cold-climate operational envelopes where pour point depression commands premium positioning.
- Butyl Palmitate:C16 saturated ester with intermediate melting characteristics between laurate and stearate grades. Sunscreen manufacturers incorporate this emollient for spreadability modulation in SPF 50+ formulations.
- Butyl Laurate:C12 saturated ester with lowest molecular weight and highest volatility among the series. Fragrance solvent applications exploit its rapid evaporation profile in fine perfume diluents.
Price stratification across these four esters tracks carbon chain length and degree of saturation, with unsaturated variants commanding modest premiums for low-temperature performance.
Application:
Volume concentration tilts toward cosmetic and personal care absorption, though industrial lubricants exhibit steepest expansion trajectory.
- Cosmetics:Moisturizer and sunscreen formulators specify butyl stearate as primary emollient for sensory spreadability and skin-conditioning functionality. South Korean SPF 50+ manufacturers are locking annual volumes with technical-grade suppliers who guarantee batch-to-batch consistency in acid value and color specifications.
- Industrial Lubricants:Metalworking fluid compounders replace mineral oil derivatives with ester bases to meet industrial effluent regulations in Germany and Japan. This segment is expanding most quickly as biodegradable lubricant mandates tighten across European manufacturing jurisdictions.
- Food Additive:Paper and paperboard applications under FDA food-contact notifications require specified purity thresholds with full toxicological documentation. China's GB standards impose additional testing protocols for import clearance, accelerating domestic oleochemical capacity expansion.
- Personal Care Products:Hair conditioner and body lotion manufacturers procure butyl stearate for detangling and emollient properties distinct from cosmetic-grade specifications.
Cosmetic applications absorb the largest volume share, while industrial lubricants are gaining share fastest on regulatory tailwinds.
End User:
Procurement sophistication varies from pharmaceutical-grade certificate requirements through commodity bulk purchasing.
- Cosmetic Manufacturers:Contract manufacturers in China's Yangtze River Delta specify technical certificates of analysis with guaranteed batch consistency. Formulation rework costs from off-spec emollients exceed raw material price differentials by substantial margins.
- Food & Beverage Industry:Paper packaging converters require REACH-registered supply chains with full substance identity documentation for SVHC compliance across European Economic Area imports.
- Chemical Companies:Intermediate producers blend butyl stearate into specialty lubricant additives and plasticizer formulations for downstream industrial compounders.
- Pharmaceutical Firms:Topical formulation developers in India face evolving CDSCO purity standards creating entry points for certified excipient suppliers in an underpenetrated compounding market.
Cosmetic manufacturers command the dominant procurement volume, while pharmaceutical firms are scaling specification requirements fastest.
Distribution Channel:
Channel selection correlates with volume scale and technical service intensity required for specification compliance.
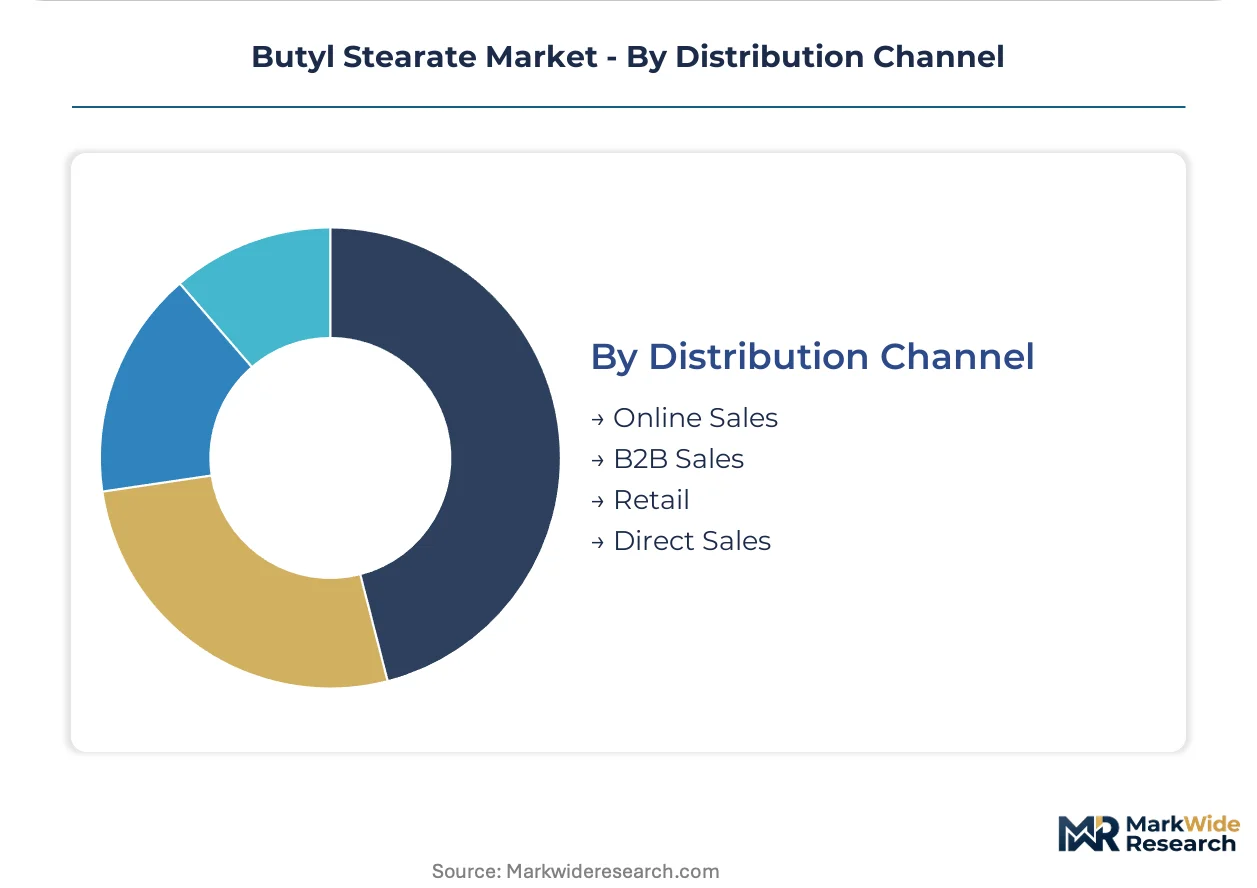
- B2B Sales:Bulk procurement patterns by compounders and contract manufacturers dominate volume flow, reflecting technical certificate requirements and annual volume commitments. Rhine-Ruhr corridor metalworking fluid blenders consolidate supplier bases to reduce audit complexity.
- Direct Sales:Pharmaceutical-grade producers bypass intermediaries to maintain chain-of-custody documentation for regulatory submissions to FDA and EMA.
- Online Sales:Small-batch cosmetic formulators and research institutions procure sample quantities through specialized chemical distribution platforms.
- Retail:Hobbyist cosmetic makers and artisan formulators access packaged quantities through specialty ingredient suppliers.
B2B sales capture the dominant channel share, while direct sales are expanding fastest among pharmaceutical-grade specification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration requirements anchor European demand for certified butyl stearate, while China's GB standards and FDA food-contact notifications shape procurement patterns across the dominant consumption geographies. Suppliers must navigate divergent purity thresholds across these three regulatory frameworks simultaneously.
China
Domestic oleochemical producers in the Yangtze River Delta are expanding fatty acid ester capacity to serve regional cosmetic formulators and export-oriented lubricant blenders. GB standards for food additives impose additional testing protocols for import clearance, accelerating substitution of imported volumes with local production. Shanghai and Jiangsu province clusters now host integrated palm oil refining through Southeast Asian feedstock arrangements.
Germany
Metalworking fluid compounders in the Rhine-Ruhr corridor are replacing mineral oil derivatives with biodegradable ester bases to meet corporate sustainability targets and industrial effluent regulations. REACH authorization requirements for substances of very high concern extend disclosure obligations through downstream formulators, consolidating supplier bases to reduce audit complexity. Bavarian specialty chemical producers retrofit fixed-bed lipase reactors to enable pharmaceutical-grade output.
United States
FDA food-contact notifications govern butyl stearate use in paper and paperboard applications under specified conditions, with full toxicological documentation required for regulatory submissions. Gulf Coast chemical producers leverage integrated oleochemical infrastructure to serve domestic lubricant blenders and pharmaceutical excipient markets. New Jersey and Pennsylvania clusters concentrate formulation expertise for cosmetic and personal care applications.
India
CDSCO's evolving purity standards for topical formulations create entry points for certified butyl stearate suppliers in an underpenetrated pharmaceutical compounding market. Maharashtra and Gujarat states host emerging contract manufacturing capacity for regional cosmetic brands seeking import substitution. Mumbai-Pune industrial corridor demand concentrates in hair conditioner and body lotion manufacturing.
South Korea
SPF 50+ sunscreen manufacturers are locking annual volumes with technical-grade suppliers who guarantee batch-to-batch consistency in acid value and color specifications. MFDS cosmetic safety assessments drive specification requirements for sensory-grade esters in premium formulations. Seoul metropolitan area formulators command premium positioning through long-term supply agreements with certified producers.
Butyl Stearate Market Competitive Environment
Integrated oleochemical majors and specialty ester chemists split the market between feedstock-cost-driven volume positions and specification-premium niches. The vendor base concentrates among palm oil processors with captive stearic acid supply and European technical centers with enzymatic catalysis expertise. Three archetypes dominate: plantation-integrated producers leveraging Southeast Asian feedstock control, European specialty houses with pharmaceutical-grade certification infrastructure, and Asian regional champions scaling domestic capacity for import substitution. Competitive moves center on backward integration into palm oil refining and enzymatic process licensing for color-sensitive applications.
Among plantation-integrated producers, KLK Oleo represents feedstock-cost leadership through Malaysian and Indonesian plantation networks. European specialty ester chemistry expertise concentrates with Emery Oleochemicals, which anchors premium positioning through technical centers in Germany and North America. BASF SE exemplifies pharmaceutical-grade purity standards that exceed general industrial specifications, occupying the certification-intensive tier where batch-to-batch consistency commands substantial premiums over commodity alternatives.
| Leading Market Players |
|---|
| KLK Oleo |
| Emery Oleochemicals |
| Wilmar International |
| BASF SE |
| Croda International Plc |
| IOI Oleochemicals |
| Fine Organics |
| Gattefossé |
| Evonik Industries |
| Others |
Value Chain & Pricing Dynamics
Palm oil feedstock volatility transmits directly into stearic acid pricing, compressing margin predictability for integrated and non-integrated producers while simultaneously forcing tiered pricing spreads between pharmaceutical-grade and industrial specifications. This commodity exposure determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of backward-integrated capacity in Southeast Asian plantation zones.
Pricing Analysis
Chinese domestic producers undercut European and North American suppliers by 15-25% on industrial-grade deliveries, while pharmaceutical-grade certificates command substantial premiums in Germany and South Korea. Price differentiation hinges on REACH registration status and enzymatic process color specifications, with cosmetic formulators least sensitive due to formulation rework cost exposure. Cost compression in industrial lubricant tiers is intensifying because mineral oil substitutes retain cost advantages in extreme-pressure segments.
Supply Chain Analysis
Extended payment terms of 90-120 days from Yangtze River Delta contract manufacturers strain working capital for non-integrated suppliers, accelerating consolidation toward plantation-backed producers. Supply concentrates in Malaysia, Indonesia, and China, with stearic acid, n-butanol, and lipase biocatalysts as critical inputs. Single-source vulnerability around Southeast Asian palm oil estates creates tariff exposure risk. Distribution runs through B2B bulk procurement channels anchored by compounders in Germany's Rhine-Ruhr corridor and China's Jiangsu province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certificate-of-analysis services and regulatory compliance documentation represent faster-expanding revenue layers than base chemical production, as formulation rework costs from off-spec batches exceed raw material price differentials by substantial margins.
For Market Incumbents: Entrench pharmaceutical-grade certification infrastructure through enzymatic process retrofits that enable color-sensitive applications previously confined to industrial specifications. Consolidate supplier audit relationships with multinational metalworking fluid compounders seeking single-point SVHC accountability. Capacity addition in Bavarian technical centers reinforces premium positioning against plantation-integrated cost leaders.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical excipient compounding market where CDSCO purity standard evolution outpaces domestic certification capacity. Target Maharashtra and Gujarat contract manufacturers seeking import substitution for topical formulation bases. A go-to-market angle anchored by REACH-registered supply documentation bypasses incumbent cost advantages through regulatory compliance speed.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty ester chemists with pharmaceutical-grade technical centers over commodity volume players. Long-term viability hinges on backward integration into palm oil refining or enzymatic licensing agreements that compress capital barriers between grade tiers. The signal to watch is GB standards alignment acceleration in China, which would validate domestic capacity expansion strategies and pressure non-integrated import models.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Retrofit | Enables pharmaceutical-grade output from industrial assets through fixed-bed lipase reactor installation. |
| Backward Integration into Palm Oil Refining | Secures captive stearic acid supply against Southeast Asian plantation output fluctuations. |
| REACH Registration Investment | Mandatory toxicological dossiers unlock European Economic Area access above one-tonne thresholds. |
| Certificate-of-Analysis Service Expansion | Locks annual volumes with sunscreen manufacturers facing formulation rework cost exposure. |
| Joint Venture with Yangtze River Delta Compounders | Reduces audit complexity for multinational metalworking fluid manufacturers with Asian footprints. |
Study Parameters
A spread of perspectives from plant managers at integrated oleochemical facilities, procurement leads at metalworking fluid compounders, technical R&D directors specializing in enzymatic catalysis, and distribution channel partners in the Yangtze River Delta converged on the working assumptions. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, European Chemicals Agency registration databases, and Chinese GB standards documentation. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by grade tier, end-use industry, and regional production hub. CAGRs were derived from growth rate convergence analysis across independent projection streams. Industry-specific forecast inputs included biodegradable lubricant mandate adoption curves in Germany and Japan, and MFDS cosmetic safety assessment timelines in South Korea.
Stress conditions across palm oil price volatility bands, REACH authorization timeline extensions, and GB standards enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and enzymatic process adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Estolides Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Glycerine Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Alcohol Ethoxylates Market