
 Asia Pacific Programmatic Advertising Market | 2026-2036
Asia Pacific Programmatic Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Programmatic Advertising Market Outlook
Capital-intensity divergence between self-serve platforms and managed-service providers is reorganizing competitive dynamics across the region. Google LLC leverages its proprietary identity graph and first-party data infrastructure to sustain pricing power in premium video inventory. InMobi Pte. Ltd. anchors its position through deep carrier integrations and SDK penetration across India's app ecosystem. Appier Inc. differentiates via AI-driven creative optimization that reduces customer acquisition costs for mid-market advertisers.
Programmatic advertising denotes the algorithmic buying and selling of digital ad impressions through real-time auction mechanisms, typically executing transactions within 100 milliseconds via bid requests routed through ad exchanges. Its primary commercial purpose is to match advertiser demand with publisher supply at individualized user-segment precision while automating budget pacing and frequency capping. Video Ads command disproportionate CPM premiums as connected TV inventory scales across the region, while Mobile Ads represent the volume backbone given smartphone-first internet access patterns. Demand-Side Platforms concentrate margin pools through SaaS fees and media markups, whereas Private Marketplaces are expanding fastest as brand-safety concerns push spend away from open exchanges.
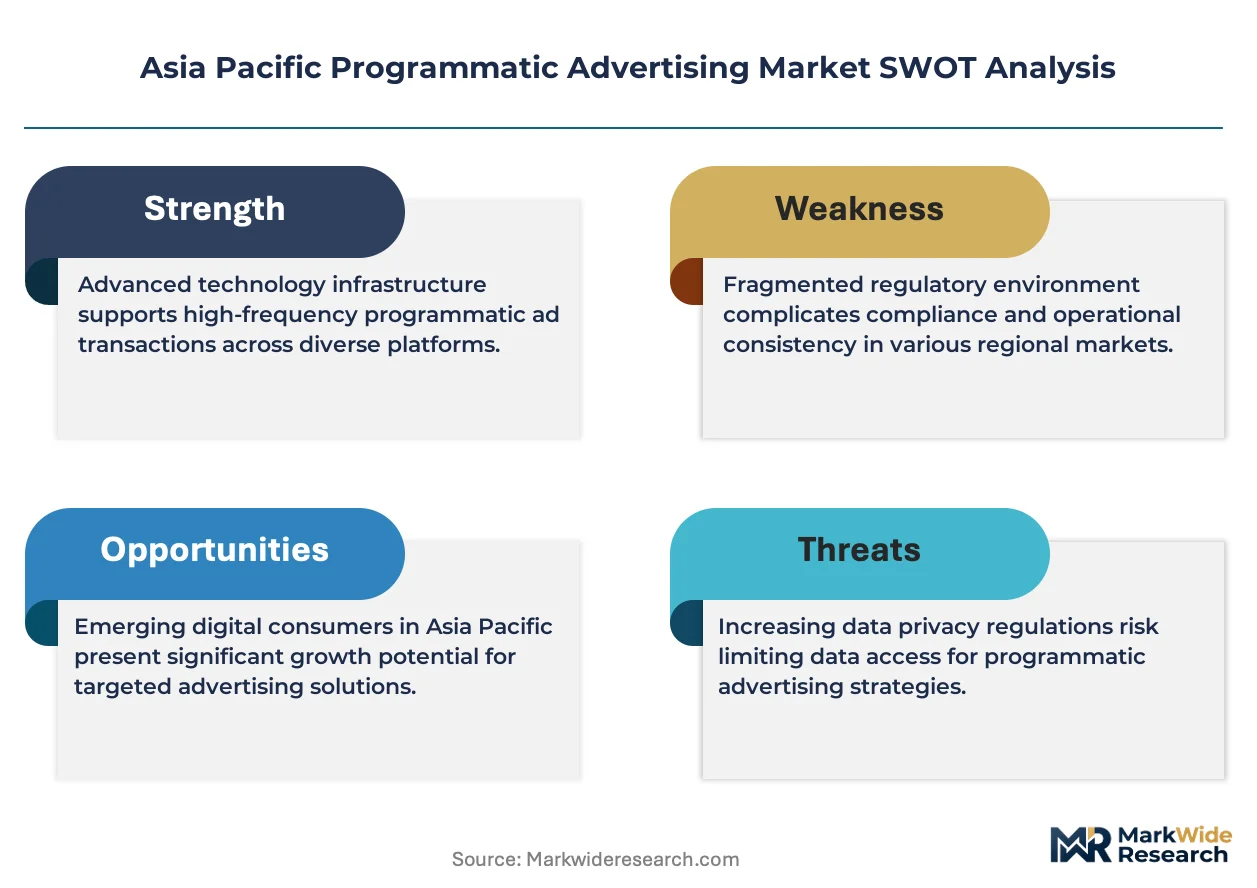
India's Digital Personal Data Protection Act imposes explicit consent requirements for cross-context behavioral tracking, directly elevating first-party data strategies and clean-room adoption. China's Personal Information Protection Law restricts outbound data transfers, forcing multinational platforms to localize ad-tech infrastructure and measurement stacks. Australia's Privacy Act reforms and the ACCC's digital platform oversight add compliance layers for audience profiling practices. Stakeholders must weigh regulatory fragmentation against the efficiency gains of unified buying platforms as data-localization mandates proliferate.
Market Dynamics
First-party data infrastructure investments are fragmenting competitive advantage across Asia Pacific, as consent-based targeting architectures replace third-party cookie dependencies and force platform-level differentiation on measurement fidelity.
Growth Catalysts
- India's Digital Personal Data Protection Act:Explicit consent mandates are accelerating clean-room adoption and authenticated audience partnerships among domestic publishers.
- Connected TV inventory expansion:Premium video supply growth across Indonesia and Vietnam is drawing brand-safety-conscious FMCG budgets from linear television.
- Mobile commerce acceleration:Smartphone-first transaction patterns in Southeast Asia are compressing attribution windows and elevating real-time optimization demand.
Market Restraints
- Data-localization infrastructure costs:China's Personal Information Protection Law forces multinational platforms to replicate ad-tech stacks within mainland boundaries.
- Identity graph fragmentation:Proprietary device graphs from carrier-integrated SDK providers create interoperability friction across demand-side platforms.
- Supply concentration in premium video:Regional broadcaster joint ventures are consolidating connected TV inventory access behind exclusive private marketplace arrangements.
Strategic Opportunities
- Indonesia's mid-market advertiser segment:AI-driven creative optimization tools are penetrating brands below multinational scale with self-serve pricing models.
- Retail media network convergence:E-commerce platform data clean rooms are merging with programmatic pipes, enabling closed-loop measurement for CPG advertisers.
- Japan's privacy-enhancing technologies:METI guidance on differential privacy and federated learning is creating compliant targeting alternatives for precision marketers.
Industry Challenges
- Cross-platform measurement standardization:Divergent viewability and attention metrics between mobile in-app and connected TV environments complicate unified reporting.
- Consent management platform integration:Legacy publisher ad servers require middleware development to interface with region-specific preference frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Programmatic Advertising Market |
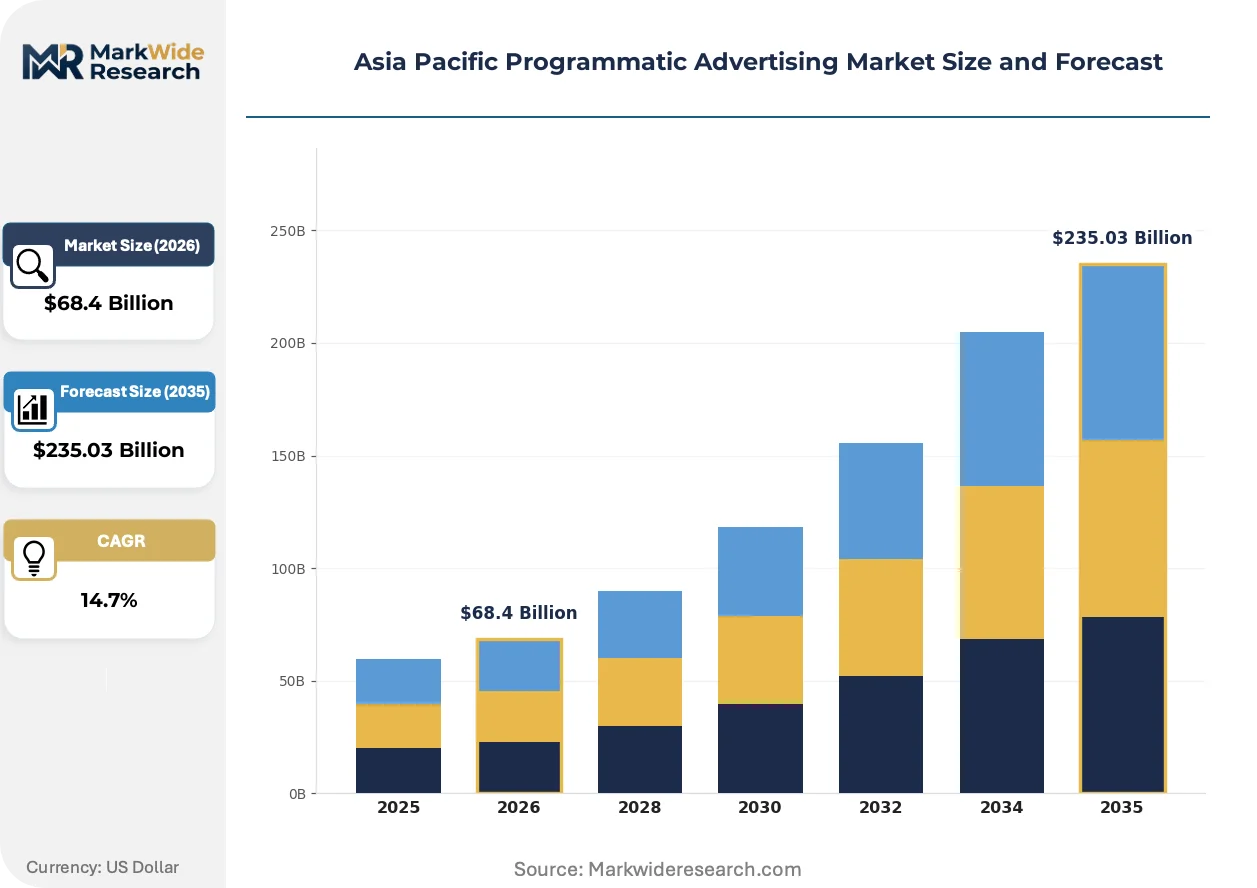
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $235.03 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Display Ads, Video Ads, Mobile Ads, Native Ads Platform: Demand-Side Platforms, Supply-Side Platforms, Ad Exchanges, Social Media Buying Type: Real-Time Bidding, Programmatic Direct, Private Marketplaces, Automated Guaranteed Industry Vertical: Retail, Travel, Entertainment, Automotive |
| Companies Covered | The Trade Desk, Inc., Adform A/S, Amazon.com LLC (Amazon Advertising), InMobi Pte. Ltd., Magnite, Inc., Appier Inc., Google LLC, Moloco, Inc., AnyMind Group Pte. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Programmatic Advertising Market Strategic Shifts
Algorithmic buying architectures are pivoting toward privacy-preserving targeting methods as regulatory consent frameworks harden and identifier deprecation accelerates across mobile operating systems.
Server-side ad insertion technology is displacing client-side SDK-based delivery in premium video environments. Major streaming platforms across Australia and South Korea are adopting SSAI to circumvent ad-blocking and improve latency. This infrastructure shift is displacing traditional ad-server mediation layers and compressing margin pools for intermediary video ad networks.
Australia's Privacy Act reforms and ACCC digital platform oversight are tightening notice-and-consent requirements for audience profiling. Advertisers must now document legitimate interest assessments for behavioral segmentation. Financial services and health-adjacent verticals are responding by shifting budget toward contextual and first-party data activation strategies.
Commerce media budgets are migrating from siloed retail platforms into unified programmatic pipes. Brand advertisers in India and Southeast Asia are demanding consolidated reporting across e-commerce and open-web inventory. This convergence is most visible among FMCG conglomerates seeking closed-loop attribution between upper-funnel video and lower-funnel transaction data.
Asia Pacific Programmatic Advertising Market Segmentation
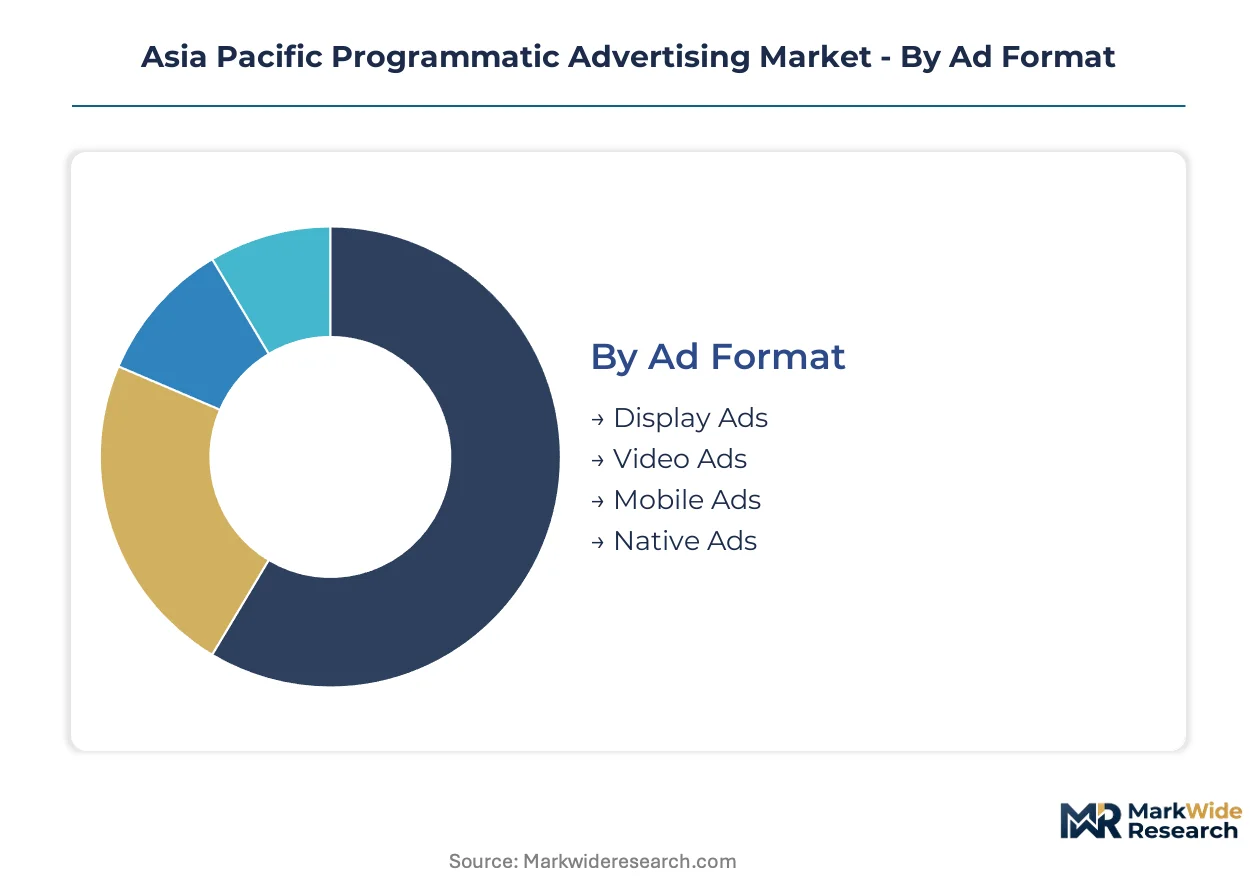
Programmatic advertising architectures fragment across multiple operational dimensions, each commanding distinct margin structures and technology requirements. Ad format selection dictates creative production workflows and measurement protocols, while platform type determines data access privileges and inventory liquidity. Buying mechanisms and industry verticals further stratify competitive positioning across the Asia Pacific ecosystem.
Ad Format:
Video and mobile formats face intensifying substitution pressure as connected TV inventory scales and in-app environments consolidate around SDK-integrated supply paths.
- Display Ads:Standard banner and rich media units executing through header bidding integrations. Retail advertisers in India concentrate spend here for mid-funnel prospecting, though viewability measurement inconsistencies constrain premium pricing.
- Video Ads:Pre-roll, mid-roll, and outstream inventory commanding CPM premiums through server-side ad insertion. FMCG brands across Indonesia and Vietnam are migrating linear television budgets into programmatic video as connected TV penetration accelerates.
- Mobile Ads:In-app and mobile web inventory leveraging device ID graphs for frequency management. Southeast Asia's smartphone-first commerce patterns sustain volume concentration here despite identifier deprecation pressures.
- Native Ads:Feed-integrated and recommendation engine placements mimicking editorial content. Publisher-direct partnerships dominate supply access, limiting pure exchange liquidity.
Mobile Ads retain volume leadership; Video Ads hold the steepest expansion curve.
Platform:
Cost tier differentiation separates enterprise-grade infrastructure from self-serve alternatives, with managed service premiums compressing as automation matures.
- Demand-Side Platforms:Advertiser-facing buying interfaces aggregating inventory access across exchanges and private marketplaces. India's mid-market brands are concentrating here for consolidated reporting and algorithmic optimization.
- Supply-Side Platforms:Publisher yield optimization layers managing header bidding configurations and floor price dynamics. Regional broadcaster joint ventures are consolidating supply-side control across Australia and South Korea.
- Ad Exchanges:Open auction environments enabling real-time impression clearing. Brand-safety concerns are pushing spend toward private marketplace alternatives, constraining open exchange growth.
- Social Media:Walled-garden programmatic pipes leveraging first-party identity graphs. China's Personal Information Protection Law reinforces the data advantages of domestic social platforms.
Demand-Side Platforms anchor advertiser spend concentration; Social Media captures the most rapid budget migration.
Buying Type:
Application context determines automation depth, with brand-sensitivity and inventory scarcity dictating manual override requirements.
- Real-Time Bidding:Open auction impression clearing within 100-millisecond windows. Latency constraints and fraud exposure limit adoption for premium brand campaigns.
- Programmatic Direct:Automated guaranteed deals preserving publisher control over inventory allocation. Australia's major publishers prefer this mechanism for upfront commitment structures.
- Private Marketplaces:Invitation-only auction environments with curated publisher participation. Japan's brand-safety-conscious advertisers are expanding commitment here to circumvent open exchange quality variance.
- Automated Guaranteed:Fixed-price, reserved inventory workflows eliminating auction dynamics. Broadcasters across Indonesia use this for connected TV scarcity management.
Real-Time Bidding sustains transaction volume leadership; Private Marketplaces demonstrate the most aggressive share gain.
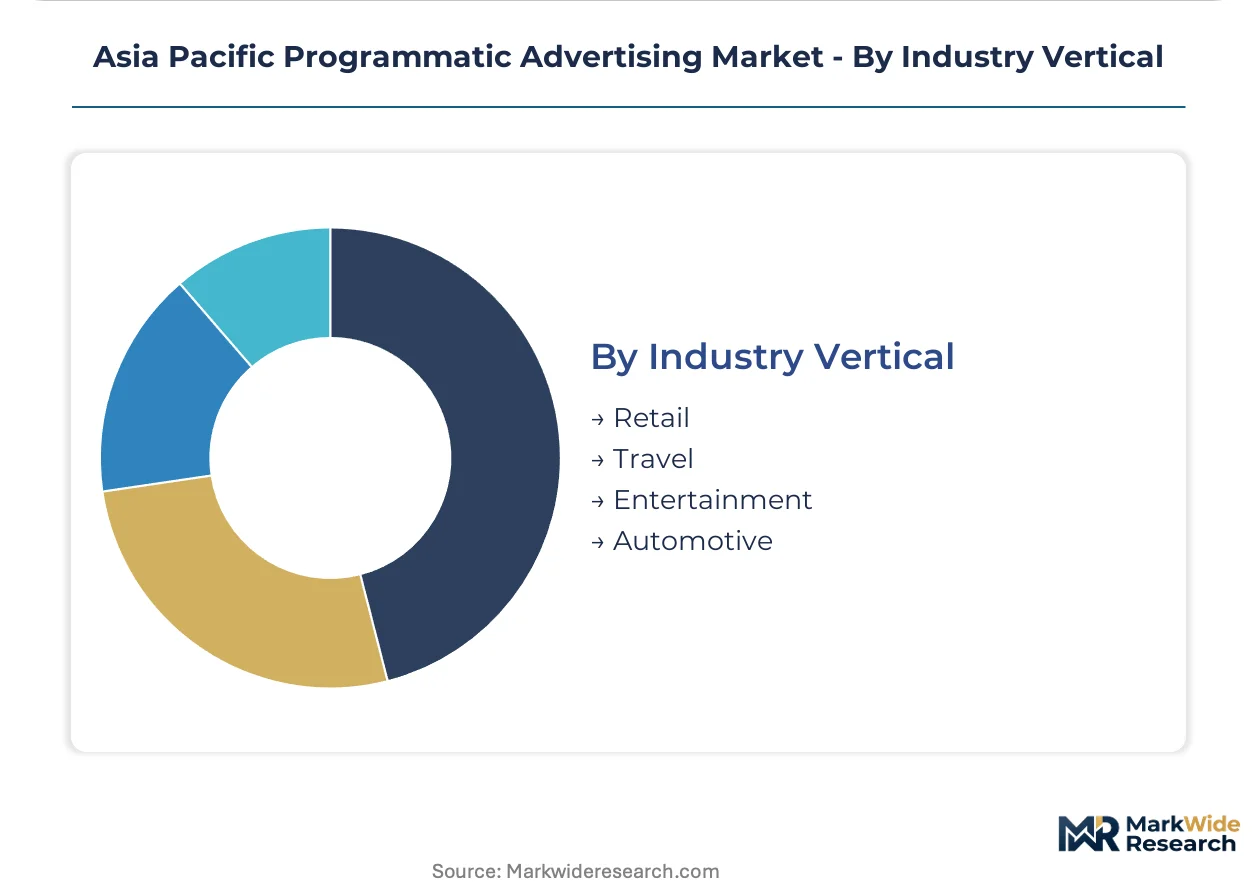
Industry Vertical:
Customer sophistication and data maturity stratify adoption patterns, with digitally native sectors advancing fastest into algorithmic optimization.
- Retail:E-commerce platforms and omnichannel brands leveraging first-party transaction data. India's retail media networks are merging clean-room infrastructure with programmatic pipes for closed-loop attribution.
- Travel:Airlines, hotels, and online booking platforms with seasonal demand volatility. Dynamic creative optimization addresses inventory perishability, though post-pandemic recovery remains uneven across Southeast Asia.
- Entertainment:Streaming services, gaming publishers, and content platforms. Australia's subscription video platforms are adopting server-side ad insertion, displacing traditional ad-server mediation.
- Automotive:OEMs and dealer networks with extended consideration cycles. Privacy regulations complicate cross-device attribution for this high-consideration vertical.
Retail commands current spend concentration; Entertainment demonstrates the most rapid technology adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Asia Pacific programmatic advertising landscape. Indonesia and Vietnam exhibit the highest price sensitivity as mid-market advertisers prioritize self-serve platforms with compressed SaaS fees. Japan and Australia command premium pricing tolerance where brand-safety certifications and measurement fidelity justify managed-service premiums.
China
Domestic e-commerce platforms are consolidating commerce media budgets behind walled-garden programmatic pipes. The Personal Information Protection Law restricts outbound data transfers, forcing multinational advertisers to localize ad-tech infrastructure within mainland boundaries. Shanghai and Beijing host the primary clusters of publisher joint ventures controlling premium video inventory access.
India
Mid-market retail brands are expanding programmatic budgets aggressively as mobile commerce penetration accelerates. The Digital Personal Data Protection Act imposes explicit consent requirements for cross-context behavioral tracking, elevating first-party data strategies and clean-room adoption. Mumbai and Bengaluru anchor the domestic publisher ecosystem developing authenticated audience partnerships.
Japan
Brand-safety-conscious advertisers are migrating spend toward private marketplace arrangements to circumvent open exchange quality variance. METI guidance on differential privacy and federated learning is creating compliant targeting alternatives for precision marketers. Tokyo and Osaka concentrate demand-side platform development serving domestic automotive and financial services verticals.
Indonesia
Smartphone-first transaction patterns are compressing attribution windows and elevating real-time optimization demand among FMCG advertisers. Regulatory frameworks remain less prescriptive than regional counterparts, enabling faster deployment of AI-driven creative optimization tools. Jakarta anchors the app ecosystem where carrier-integrated SDK providers are consolidating device graph control.
Australia
Streaming platforms are adopting server-side ad insertion technology to circumvent ad-blocking and improve latency in premium video environments. Privacy Act reforms and ACCC digital platform oversight tighten notice-and-consent requirements for audience profiling practices. Sydney and Melbourne host the primary clusters of broadcaster joint ventures consolidating connected TV inventory access.
Asia Pacific Programmatic Advertising Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific programmatic advertising ecosystem. The market structure concentrates around three distinct tiers: global platforms with proprietary identity graphs, regional specialists with deep carrier integrations, and AI-native challengers with creative optimization capabilities. Dominant competitive moves include private marketplace exclusivity arrangements with premium publishers and vertical integration into first-party data clean-room infrastructure.
Within the global platform tier, Google LLC and Amazon.com LLC occupy positions defined by proprietary data assets and commerce media convergence. Among Asia Pacific-based specialists, InMobi Pte. Ltd. and Appier Inc. exemplify the carrier-integrated and AI-driven archetypes respectively. The Trade Desk, Inc. represents the independent demand-side platform model competing on unified cross-channel buying interfaces.
| Leading Market Players |
|---|
| The Trade Desk, Inc. |
| Adform A/S |
| Amazon.com LLC (Amazon Advertising) |
| InMobi Pte. Ltd. |
| Magnite, Inc. |
| Appier Inc. |
| Google LLC |
| Moloco, Inc. |
| AnyMind Group Pte. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at server-side ad insertion infrastructure clusters in Australia and South Korea shapes both supply concentration and price floors for premium video inventory. Scale economies in carrier-integrated SDK deployments across Indonesia compress marginal delivery costs while elevating barriers for non-integrated intermediaries.
Pricing Analysis
Managed-service fees and platform SaaS subscriptions drive lifetime value capture across demand-side and supply-side platforms. Three-tier pricing structure across premium, standard, and economy levels separates brand-safety-certified private marketplace access from open exchange liquidity and self-serve automation tiers. Price differentiation rests on measurement fidelity certifications and first-party data integration depth. Pricing pressure stems from self-serve platform commoditization in Indonesia and Vietnam. Mid-market advertisers in Southeast Asia exhibit highest price sensitivity; Japan's automotive and financial services verticals tolerate managed-service premiums.
Supply Chain Analysis
Just-in-time impression clearing through real-time bidding coexists with strategic stockpiling of reserved inventory in automated guaranteed workflows. Supply concentrates in China, India, and Australia as data-localization mandates force infrastructure replication. Raw material dependencies span identity graph data, carrier SDK integrations, and clean-room measurement stacks. Single-source vulnerability sits with proprietary device graphs controlled by carrier-integrated providers. Distribution runs through demand-side platform interfaces and publisher-direct private marketplace arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Asia Pacific programmatic advertising hinge on interoperability friction between walled-garden identity systems and open-web measurement standards. The report identifies specific stakeholder imperatives across incumbent defense, entrant positioning, and investment screening.
For Market Incumbents: Compound first-party data infrastructure advantages through clean-room partnerships with domestic publishers in India and Indonesia. Carrier SDK integration depth and server-side ad insertion capacity in Australia anchor defensive moats against AI-native creative optimization challengers. Private marketplace exclusivity arrangements with regional broadcasters consolidate premium video access.
For New Entrants and Emerging Players: Differentiate on privacy-enhancing targeting methods aligned with Japan's METI differential privacy guidance and India's consent-framework requirements. Indonesia's mid-market FMCG segment offers lowest penetration friction for self-serve AI creative tools. Go-to-market through retail media network convergence enables closed-loop attribution narratives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among demand-side platforms with vertical-specific workflow integration and supply-side platforms controlling connected TV inventory access. Long-term viability favors carriers with authenticated audience scale and compliance-authenticated measurement stacks. Watch for clean-room interoperability standardization as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Room Infrastructure Partnership | Enables compliant first-party data activation under India's Digital Personal Data Protection Act. |
| Server-Side Ad Insertion Scale-Up | Circumvents ad-blocking latency in Australia's streaming platform environments. |
| Carrier SDK Integration Deepening | Consolidates device graph control across Indonesia's smartphone-first app ecosystem. |
| Private Marketplace Exclusivity Arrangement | Secures brand-safety-certified inventory access for Japan's financial services advertisers. |
| AI-Driven Creative Optimization Launch | Reduces customer acquisition costs for mid-market retailers in Southeast Asia. |
Study Parameters
Desk research of regulatory filings, ad-tech infrastructure disclosures, and publisher yield optimization documentation preceded structured interviews with demand-side platform product managers, supply-side platform yield directors, advertiser agency trading desk heads, and privacy compliance officers. Primary fieldwork across Mumbai, Jakarta, Sydney, and Tokyo validated secondary data on inventory pricing and consent-framework implementation. Bottom-up transaction volume estimates and top-down media spend allocations underwent cross-referencing triangulation.
Variance decomposition across ad format, platform type, buying mechanism, and industry vertical dimensions shaped the analytical framework. Modeled segmentation captured deployment model, organization scale, regional regulatory cluster, and integration complexity variations. CAGRs were derived from trend extrapolation anchored to disclosed infrastructure investment cycles and inventory expansion timelines. Forecast inputs incorporated connected TV penetration curves and mobile commerce acceleration patterns.
Material uncertainties — regulatory enforcement intensity, identifier deprecation timelines, and cross-border data flow restrictions — sit outside the modeled envelope. Forecasts reflect assumptions on consent-framework adoption rates and clean-room interoperability progress. Revision becomes warranted when privacy-enhancing technology deployment crosses mainstream adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
In-Flight Advertising Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Native Advertising Market