
 5G Telemedicine Platform Market | 2026-2036
5G Telemedicine Platform Market Size, Share, and Industry Trends Forecast 2026-2036
5G Telemedicine Platform Market Insights
The direct-to-hospital sales channel is tilting toward platform-as-a-service models that bundle 5G connectivity with clinical software stacks. Siemens Healthineers leverages its imaging hardware installed base to embed telemedicine modules directly into radiology workflows. Teladoc Health anchors its position through payer contracts that lock in virtual visit volumes across employer and health plan networks. Cisco Systems controls the network layer, competing on low-latency edge architectures purpose-built for remote surgical consultation.
A 5G telemedicine platform combines ultra-reliable low-latency communication (URLLC) networks with real-time video, biometric streaming, and AI-assisted diagnostic tools to deliver clinical services at distance. The architecture typically requires sub-10 millisecond latency for synchronous applications such as telesurgery or emergency stroke assessment, with network slicing isolating traffic for guaranteed quality of service. Cloud-based deployment leads in new installations because hospitals avoid capital-intensive radio infrastructure ownership, while edge computing segments capture margin pools where latency sensitivity blocks public cloud routing. Virtual consultation and remote patient monitoring within solution offerings are expanding fastest as reimbursement codes stabilize and chronic disease management programs scale.
The FDA governs software-as-a-medical-device classifications that determine which platform features require premarket clearance, while the FCC manages spectrum licensing that directly constrains where 5G healthcare networks can operate. HIPAA compliance obligations shape data architecture decisions, particularly for cloud-based deployments handling protected health information across state lines. Stakeholders must monitor how FDA guidance on AI diagnostic modules evolves relative to EU MDR requirements, as divergent approval pathways will fragment platform development roadmaps and channel investments.
Market Dynamics
Network slicing capabilities are restructuring how healthcare providers contract for connectivity, separating guaranteed service tiers from commodity bandwidth and forcing vendors to prove latency performance under clinical load conditions.
Growth Catalysts
- FCC spectrum allocation for healthcare bands:Dedicated mid-band frequencies accelerate private 5G network deployment across hospital systems without competing against consumer traffic.
- Remote patient monitoring reimbursement codes:CMS physician fee schedule expansions in the United States validate chronic disease management via connected devices.
- Edge computing architectures:Hospital IT departments deploy localized compute nodes to process AI-assisted diagnostic data without routing through public cloud infrastructure.
Market Restraints
- Radio infrastructure capital intensity:Small cell densification requirements strain rural hospital budgets where patient volumes cannot amortize deployment costs.
- FDA software-as-a-medical-device clearance timelines:AI diagnostic modules face 12-18 month premarket review cycles that delay platform feature rollouts.
- Optical fiber backhaul gaps:Last-mile fiber concentration in urban corridors leaves exurban clinics dependent on microwave links with weather vulnerability.
Strategic Opportunities
- India's tier-2 city expansion:Practo and regional providers scale remote consultation networks where specialist physician density remains critically low.
- Network-as-a-service contracting models:Telecom operators offer operational expenditure-based 5G connectivity bundles that shift infrastructure risk away from hospital capital budgets.
- EU MDR harmonization with FDA pathways:Convergent approval frameworks reduce redundant clinical validation costs for platform vendors seeking dual-market entry.
Industry Challenges
- Interoperability with legacy HL7 v2 systems:Hospital electronic health record integration requires custom middleware development that extends deployment timelines.
- Telehealth-specific malpractice coverage gaps:Insurers in multiple jurisdictions lack standardized policies for cross-border remote consultation liability.
- Biometric data residency requirements:State-level health information regulations fragment cloud architecture decisions for multi-hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Telemedicine Platform Market |
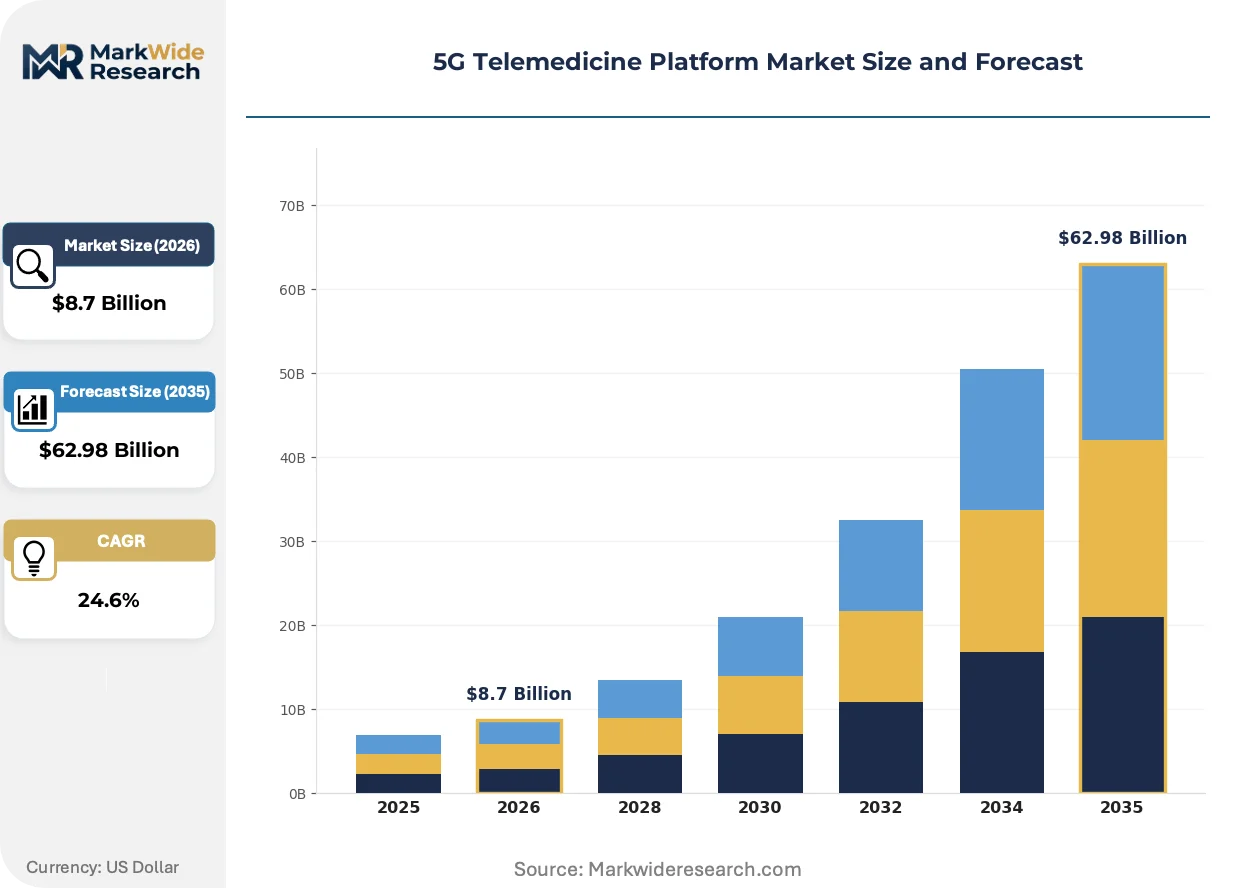
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Offering: Remote Patient Monitoring, Virtual Consultation, Medical Imaging, Electronic Health Records, AI Diagnostics Use Case: Chronic Disease Management, Emergency Response, Mental Health Support, Postoperative Care, Prenatal Monitoring End User: Physicians, Outpatient Centers, Home Healthcare Providers, Diagnostic Laboratories |
| Companies Covered | Huawei Enterprise, Siemens Healthineers, GE Healthcare, Teladoc Health, American Well, Cisco Systems, Philips, IBM, Practo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Telemedicine Platform Market Trends and Innovations
Artificial intelligence inference at the network edge is compressing diagnostic decision timelines, while regulatory frameworks race to keep pace with software-driven clinical workflows.
Ultra-reliable low-latency communication is collapsing the distance barrier for synchronous telemedicine applications. Telesurgery pilots in South Korea and Germany now operate at sub-5 millisecond latency, enabling specialist surgeons to control remote robotic instruments across metropolitan regions. Academic medical centers are collapsing referral network hierarchies by embedding 5G-enabled consultation directly into emergency department triage protocols.
The EU AI Act risk classification framework is reshaping how platform vendors architect diagnostic modules. High-risk AI systems for clinical decision support now require conformity assessments before CE marking, extending development cycles but creating quality differentiation. European hospital procurement committees are responding by mandating AI transparency documentation that exceeds current FDA guidance on algorithmic explainability.
Hospital purchasing committees are consolidating vendor relationships around integrated platform stacks rather than point solutions. Radiology departments in the United States increasingly specify combined imaging hardware, 5G connectivity, and AI workflow tools in single procurement vehicles. This bundling behavior concentrates contract value with full-stack providers and marginalizes standalone software vendors lacking network infrastructure partnerships.
5G Telemedicine Platform Market Segmentation
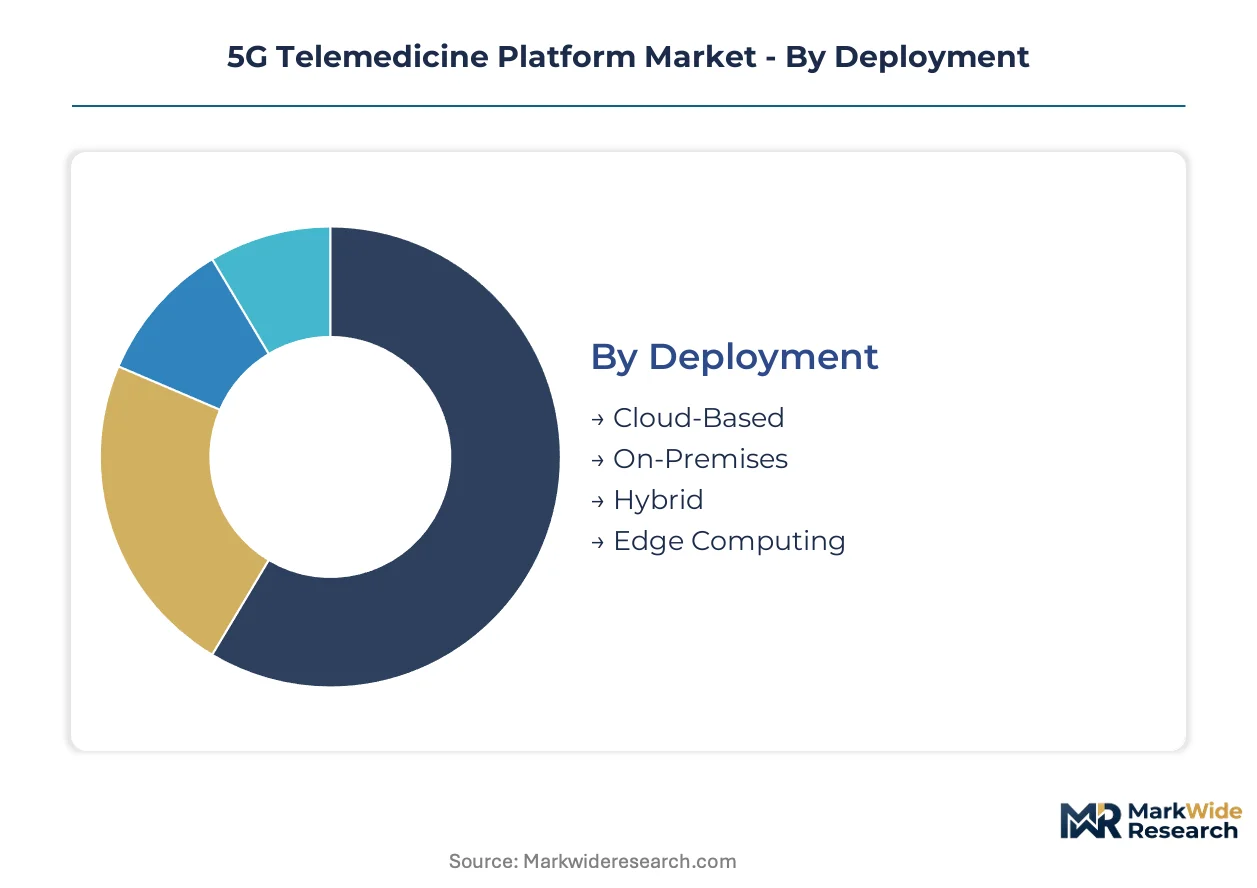
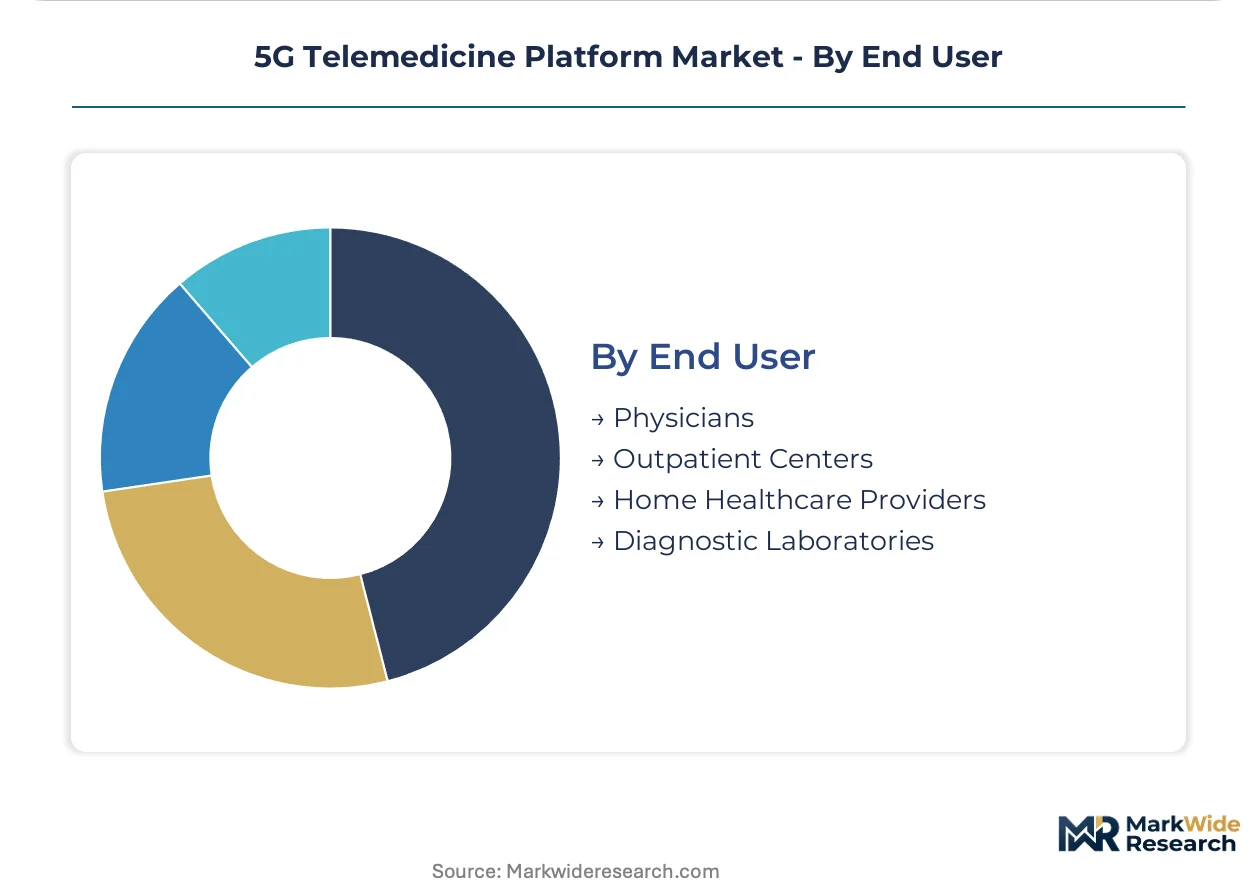
5G telemedicine platforms fragment across deployment architectures, clinical applications, and care settings. Each segmentation axis reveals distinct margin structures, regulatory exposure, and infrastructure requirements that shape vendor positioning and hospital procurement behavior.
Deployment:
Cloud-based deployments turn over fastest as hospitals prioritize operational expenditure models, while edge computing contracts extend longest due to hardware refresh cycles and localized infrastructure ownership.
- Cloud-Based:Multi-tenant architectures host clinical workloads on shared infrastructure with HIPAA-compliant data partitioning. United States hospital systems concentrate demand here as they avoid radio equipment capital outlays and shift to subscription-based network-as-a-service contracting.
- Edge Computing:Localized compute nodes process AI diagnostic inference and real-time video streams within hospital premises. Germany's academic medical centers drive adoption where sub-10 millisecond latency requirements for telesurgery and emergency stroke assessment block public cloud routing.
- On-Premises:Hospital-owned server infrastructure with dedicated 5G small cell deployments.
- Hybrid:Split architectures routing non-sensitive workloads to cloud while retaining critical data on local infrastructure.
Cloud-based deployments dominate installed base. Edge computing is where expansion concentrates.
Solution Offering:
Cost tier differentiation separates high-investment AI diagnostics from commoditized virtual consultation modules, with reimbursement stability determining which segments command premium pricing.
- Virtual Consultation:Real-time video platforms with integrated scheduling, billing, and EHR documentation workflows. India's tier-2 cities concentrate demand where Practo and regional providers scale networks to address specialist physician scarcity.
- AI Diagnostics:Machine learning modules for radiology interpretation, pathology screening, and clinical decision support. EU MDR conformity assessments and FDA software-as-a-medical-device clearance timelines constrain rollout velocity but create quality-based vendor differentiation.
- Remote Patient Monitoring:Continuous biometric streaming from connected devices for chronic disease management.
- Medical Imaging:High-resolution DICOM transmission with 5G-enabled low-latency viewing.
- Electronic Health Records:Cloud-native EHR systems with embedded telemedicine documentation tools.
Virtual consultation dominates installed base. AI diagnostics is where expansion concentrates.
Use Case:
Volume concentration clusters around chronic conditions with recurring reimbursement, while emergency applications remain supply-constrained by latency infrastructure and specialist availability.
- Chronic Disease Management:Longitudinal care programs for diabetes, hypertension, and heart failure via connected devices and scheduled virtual touchpoints. United States demand concentrates here as CMS physician fee schedule expansions validate remote monitoring with dedicated reimbursement codes.
- Emergency Response:5G-enabled stroke assessment, trauma triage, and prehospital consultation. South Korea's metropolitan regions deploy these networks where sub-5 millisecond latency enables real-time specialist intervention during ambulance transport.
- Mental Health Support:Asynchronous and synchronous behavioral health consultation platforms.
- Postoperative Care:Remote surgical site monitoring and recovery coordination.
- Prenatal Monitoring:Remote fetal surveillance and high-risk pregnancy management.
Chronic disease management dominates installed base. Emergency response is where expansion concentrates.
End User:
Customer type determines procurement complexity, with hospital networks demanding integrated stacks and home healthcare providers accepting modular point solutions.
- Physicians:Individual practitioners and group practices adopting telemedicine for panel expansion and workflow efficiency. United States payer contracts through Teladoc Health and similar platforms lock in virtual visit volumes across employer and health plan networks.
- Home Healthcare Providers:Agencies deploying remote monitoring for aging-in-place populations. India's urban corridors concentrate demand as families seek alternatives to institutional long-term care for elderly relatives.
- Outpatient Centers:Ambulatory surgical and specialty clinics extending post-procedure monitoring.
- Diagnostic Laboratories:Remote pathology review and AI-assisted specimen analysis.
Physician practices dominate installed base. Home healthcare providers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's mid-band spectrum allocation for healthcare-specific 5G networks underwrites the United States' infrastructure leadership. Germany's fiber-optic backbone density enables sub-10 millisecond latency corridors between academic medical centers. India's National Digital Health Mission creates the regulatory framework for tier-2 city telemedicine scaling.
United States
Rural hospital networks drive virtual consultation adoption as CMS reimbursement codes validate remote chronic disease management. The FCC's dedicated healthcare spectrum bands accelerate private 5G deployment without consumer traffic competition. Mayo Clinic's Rochester campus anchors emergency stroke assessment networks extending across Minnesota and neighboring states.
Germany
Academic medical centers demand edge computing architectures for telesurgery applications requiring sub-5 millisecond latency. The EU AI Act's high-risk system classification extends development cycles for diagnostic modules but creates quality-based vendor differentiation. Berlin-Brandenburg's metropolitan corridor hosts telesurgery pilots connecting Charité hospital to regional trauma centers.
India
Tier-2 cities concentrate demand for remote specialist consultation where physician density remains critically low. The National Digital Health Mission's unified health ID system enables interoperable patient records across state boundaries. Practo scales networks through Bangalore's technology cluster while addressing diabetes and hypertension management in Pune and Hyderabad.
South Korea
Metropolitan regions deploy 5G-enabled emergency response networks during ambulance transport. The Ministry of Science and ICT's 5G+ strategy funds healthcare-specific network slicing demonstrations. Seoul National University Hospital anchors real-time trauma triage protocols extending to Gyeonggi Province satellite facilities.
United Kingdom
NHS England's virtual ward programs expand remote patient monitoring for postoperative and chronic care populations. The MHRA's software-as-a-medical-device guidance shapes AI diagnostic module approval pathways. London's Guy's and St Thomas' NHS Foundation Trust embeds 5G consultation into emergency department workflows across the capital.
5G Telemedicine Platform Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in connectivity and imaging hardware. The vendor base concentrates around full-stack providers bundling network infrastructure with clinical software, marginalizing standalone application vendors. Three archetypes dominate: telecom-network hybrids, medical device incumbents embedding telemedicine modules, and pure-play virtual care platforms. Consolidation proceeds through payer contract lock-ins and radiology workflow integration rather than horizontal M&A.
Within the medical device incumbent tier, Siemens Healthineers and GE Healthcare exemplify hardware-anchored platform strategies. Teladoc Health occupies a position among pure-play virtual care specialists. Cisco Systems represents the network infrastructure archetype competing on edge architecture latency performance. These three company types illustrate how competitive positioning diverges across the connectivity-to-application stack.
| Leading Market Players |
|---|
| Huawei Enterprise |
| Siemens Healthineers |
| GE Healthcare |
| Teladoc Health |
| American Well |
| Cisco Systems |
| Philips |
| IBM |
| Practo |
| Others |
Pricing and Supply Chain Analysis
Bangalore's technology cluster anchors cloud infrastructure capacity for 5G telemedicine platforms, concentrating compute node manufacturing and compressing subscription pricing for downstream hospital networks. FCC spectrum licensing costs and edge computing hardware procurement feed directly into SaaS tier differentiation, while rural hospital budget constraints force vendors toward network-as-a-service operational expenditure models.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital network contracts from individual physician practice subscriptions, with platform bundling commanding premium positioning. Three-tier pricing stratifies across full-stack integrated deployments, modular software licenses, and connectivity-only network services. Cost compression in the connectivity-only tier intensifies as telecom operators compete on latency guarantees. Hospital purchasing committees demonstrate lowest price sensitivity for telesurgery-capable edge architectures, while home healthcare providers and tier-2 city clinics prioritize economy-tier virtual consultation modules.
Supply Chain Analysis
Extended payment terms from network equipment vendors to hospital IT departments have become standard, with supply-chain finance facilities bridging 90-180 day procurement cycles. Component manufacturing concentrates in China, South Korea, and Taiwan for 5G small cells, edge servers, and AI inference chips. Raw material dependencies include gallium nitride semiconductors, high-purity optical fiber, and specialized medical-grade sensors. Single-source vulnerability in advanced node chip fabrication threatens platform rollout timelines. Distribution runs through telecom operator direct sales forces and radiology equipment manufacturer bundled offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in 5G telemedicine hinge on interoperability consolidation, with HL7 FHIR adoption collapsing integration friction and rewarding vendors who embed across EHR workflows rather than operate as standalone modules.
For Market Incumbents: Entrench radiology workflow dominance by embedding telemedicine modules directly into imaging hardware installed bases, countering pure-play virtual care platforms that lack network infrastructure partnerships. Prioritize FDA software-as-a-medical-device clearance investment for AI diagnostic modules to create regulatory moats against faster-moving but uncertified entrants. Lock in payer contract exclusivity clauses that tie virtual visit volumes to multi-year commitments. For New Entrants and Emerging Players: Build out remote patient monitoring specialization for India's tier-2 cities, where Practo has established demand but specialist physician density gaps remain acute. Target home healthcare provider segments with modular point solutions rather than competing for hospital network integrated stack procurement. Pursue network-as-a-service partnerships with telecom operators to bypass capital-intensive radio infrastructure ownership requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-stack platform integrators over standalone application vendors, as hospital purchasing committees consolidate vendor relationships and marginalize point solutions. Long-term viability rests on edge computing architecture control and radiology workflow integration depth. Monitor FDA guidance evolution on AI diagnostic modules as the inflection signal distinguishing quality-tier vendors from commodity competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Network-as-a-Service Partnership | Shifts infrastructure capital burden from rural hospitals to telecom operators via operational expenditure contracting. |
| FDA Software-as-a-Medical-Device Submission | Accelerates AI diagnostic module clearance timelines and creates regulatory differentiation against uncertified competitors. |
| Radiology Workflow Integration | Embeds telemedicine modules into Siemens Healthineers and GE Healthcare imaging hardware for captive distribution. |
| HL7 FHIR Interoperability Certification | Reduces hospital EHR integration friction and shortens deployment timelines for multi-hospital network contracts. |
| EU MDR Conformity Assessment Pathway | Opens dual-market entry for AI diagnostic platforms and aligns development roadmaps with convergent regulatory frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC spectrum allocation records, FDA 510(k) and De Novo submission databases, CMS physician fee schedule documentation, and hospital procurement contract disclosures. Interviews with hospital CIOs, biomedical engineers, GPO contracts managers, and telemedicine platform product directors inform deployment architecture preferences and vendor selection criteria. Top-down market sizing triangulates against bottom-up hospital system adoption curves and telecom operator 5G healthcare network deployment disclosures.
Forecast inputs incorporate deployment model segmentation across cloud-based, edge computing, on-premises, and hybrid architectures; solution offering splits between virtual consultation, AI diagnostics, remote patient monitoring, and medical imaging; and use case differentiation across chronic disease management, emergency response, mental health support, and postoperative care. CAGRs derive from elasticity modeling against reimbursement code expansion trajectories and latency infrastructure buildout curves. Edge computing penetration rates and private 5G network deployment velocity shape regional growth assumptions.
Sensitivities concentrate around FCC spectrum auction timing, FDA AI diagnostic guidance revision, and CMS remote monitoring reimbursement code stability. Forecasts reflect documented assumptions regarding network equipment cost curves and hospital IT capital expenditure cycles. Macroeconomic deviation affecting hospital operating margins, regulatory divergence between FDA and EU MDR pathways, or breakthrough low-earth orbit satellite latency alternatives would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Telemedicine Service Market
Telemedicine
Remote Healthcare Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
US Telemedicine Market
Telemedicine
US Virtual Visits Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Telehealth Services Market
Telemedicine
Global Telemedicine Market
Telemedicine
US Virtual Care Market
Telemedicine
Real-Time E-Healthcare System Market