
 Asia-Pacific Synthetic Camphor Market | 2026-2036
Asia-Pacific Synthetic Camphor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Synthetic Camphor Market Insights
Aftermarket service revenue for technical grade camphor purification is narrowing as producers integrate downstream formulation capabilities. Oriental Aromatics Limited leverages its Maharashtra manufacturing base to sustain bulk powder supply contracts across western India. Nagase & Co. Ltd. anchors Japanese pharmaceutical distribution channels through specialized logistics for temperature-sensitive camphor derivatives. Saptagir Camphor Limited competes on cost structure in Andhra Pradesh's expanding specialty chemical corridor.
Asia-Pacific synthetic camphor denotes a bicyclic monoterpene ketone (C10H16O) manufactured primarily from alpha-pinene via catalytic oxidation, typically achieving purity grades between 96% and 99.5% for pharmaceutical applications. The substance functions chiefly as a counter-irritant in topical medicaments, a plasticizer in cellulose nitrate films, and a fragrance fixative in cosmetic formulations. Powder and granule product types dominate volume throughput for industrial chemical buyers, while liquid formulations capture expanding share in pharmaceutical emulsion applications where rapid dissolution properties command premium positioning. End use demand from the cosmetics segment exhibits faster structural growth than mature chemical intermediates consumption, with formulation-grade specifications driving margin migration toward solution and suspension delivery systems.
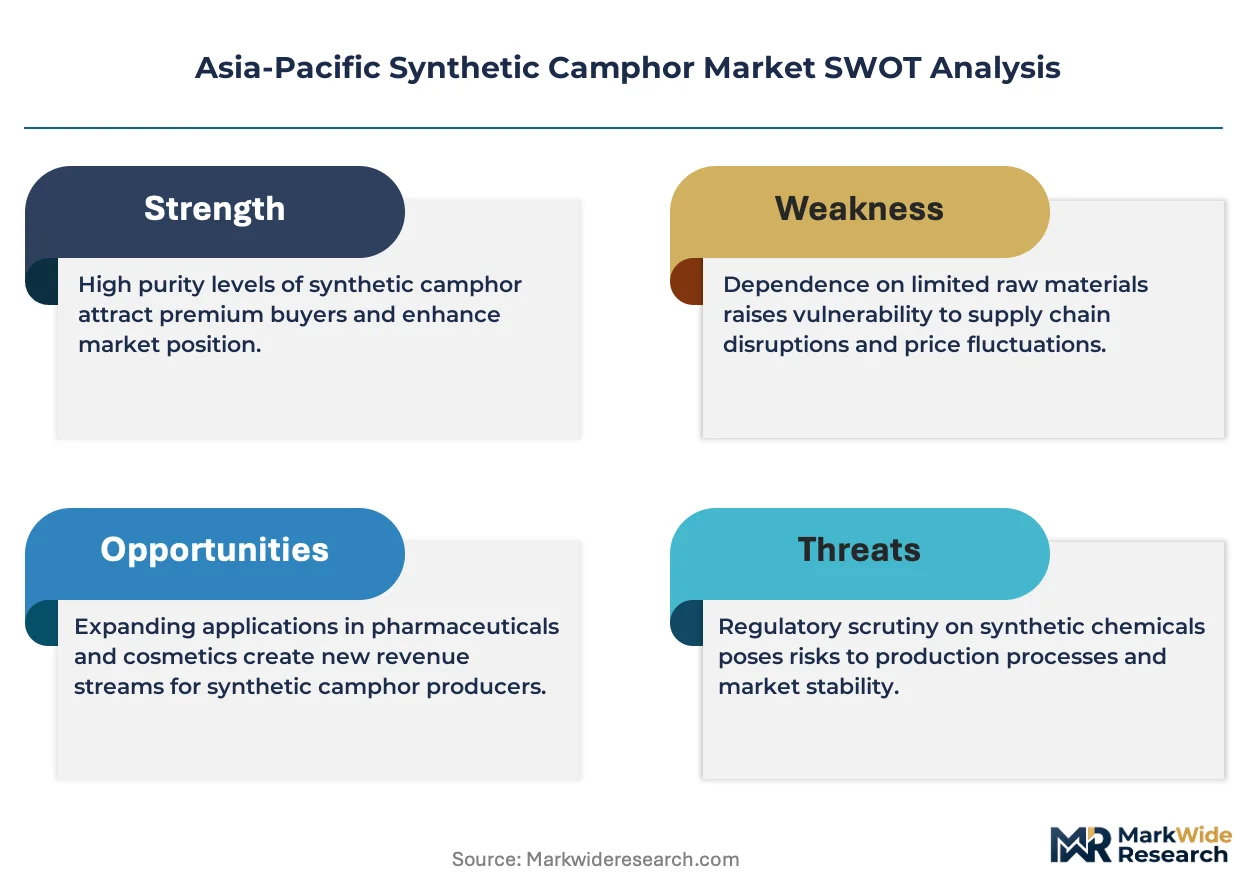
India's Central Drugs Standard Control Organisation and China's National Medical Products Administration enforce divergent purity thresholds for pharmaceutical-grade camphor, fragmenting cross-border product registration requirements. Japan's Ministry of Economy, Trade and Industry administers industrial chemical handling standards that constrain bulk import logistics for non-JIS certified suppliers. REACH-aligned regulatory convergence in South Korea through the Ministry of Food and Drug Safety is compressing compliance timelines for regional exporters. Stakeholders must monitor evolving API localization mandates and formulation-grade certification harmonization across multiple national frameworks to secure sustained market access.
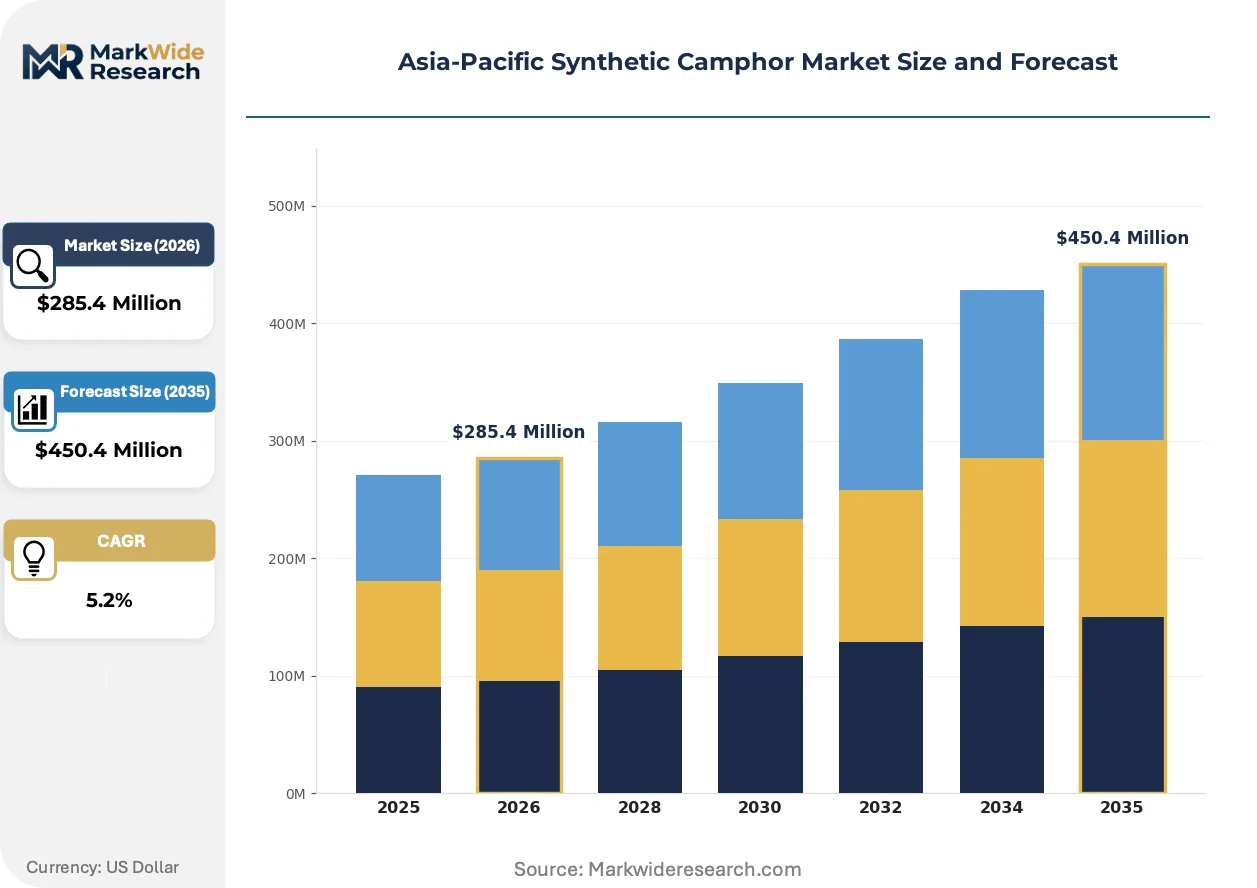
Market Dynamics
India's PLI scheme for active pharmaceutical ingredients is redrawing procurement economics across the Asia-Pacific synthetic camphor value chain, compressing import dependency and accelerating captive production investments.
Growth Catalysts
- CDSCO API Localization Mandates:India's pharmaceutical regulator enforces stricter domestic sourcing thresholds for topical analgesic formulations, redirecting procurement toward Maharashtra and Andhra Pradesh manufacturing clusters.
- Cosmetic Formulation-Grade Demand:Fragrance fixative applications in premium skincare emulsions are absorbing higher-purity camphor derivatives at faster volume growth than industrial plasticizer segments.
- Alpha-Pinene Feedstock Security:Zhejiang and Fujian province specialty chemical clusters maintain integrated turpentine-to-camphor processing infrastructure, insulating regional supply from import volatility.
Market Restraints
- Crude Turpentine Price Volatility:Input costs for alpha-pinene extraction fluctuate with gum rosin harvest cycles across southern China and Indonesian plantation regions.
- Divergent Purity Thresholds:CDSCO and NMPA enforce non-harmonized pharmaceutical-grade specifications, fragmenting cross-border product registration and extending compliance timelines.
- Cellulose Nitrate Substitution:Alternative plasticizers in film coating applications are displacing technical-grade camphor in select industrial chemical buyer segments.
Strategic Opportunities
- Vietnamese Specialty Chemical Corridor:Underdeveloped downstream formulation capabilities in northern industrial zones create white space for integrated purification-to-delivery investments.
- MFDS REACH Alignment:South Korea's regulatory convergence with EU chemical handling standards compresses certification burdens for regional exporters targeting multiple national frameworks.
- Liquid Emulsion Delivery Systems:Rapid-dissolution pharmaceutical applications command premium positioning as formulation houses pivot from powder toward solution-based topical medicaments.
Industry Challenges
- Catalytic Oxidation Process Expertise:Scarcity of skilled technicians for continuous flow reactor operations constrains capacity expansion at mid-scale producers.
- Temperature-Controlled Logistics Certification:METI-administered industrial chemical handling standards for bulk camphor derivatives require specialized cold-chain infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Synthetic Camphor Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Crystals End Use Industry: Pharmaceuticals, Cosmetics, Food, Chemicals Formulation: Emulsions, Solutions, Suspensions, Powders Packaging Type: Drums, Bags, Cartons, Bottles |
| Companies Covered | Oriental Aromatics Limited, Nagase & Co. Ltd., Saptagir Camphor Limited, Hunan Deli Essential Oil Co., Ltd., Skyrun Industrial Co. Ltd., Kanchi Karpooram Limited, Fujian Green Pine, Zhejiang Jianye Chemical Co., Ltd., Mangalam Organics Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Synthetic Camphor Market Trends and Innovations
Continuous flow catalytic oxidation is displacing batch processing across Asia-Pacific synthetic camphor manufacturing, compressing cycle times and tightening purity variance bands.
Membrane separation technology for final-stage purification is migrating from pharmaceutical-grade producers toward technical-grade suppliers as cost curves flatten. Specialty chemical clusters in Zhejiang province deploy ceramic nanofiltration modules to achieve 99.5% purity thresholds without multiple recrystallization stages. This equipment migration is enabling smaller-batch flexibility for contract formulation houses serving regional cosmetic brands.
NMPA's 2023 revision to pharmaceutical excipient registration rules now mandates stability testing documentation for imported camphor derivatives. Chinese domestic producers with in-house analytical capabilities capture accelerated approval timelines. Japanese pharmaceutical distributors respond by consolidating supplier panels to pre-qualified NMPA-registered entities.
Formulation houses are unbundling after-sales technical service from bulk powder contracts, purchasing purification and blending expertise separately from commodity supply. Western India pharmaceutical manufacturers now source technical-grade feedstock from Maharashtra producers while contracting specialty blending to dedicated formulation service providers. This service unbundling concentrates margin capture with downstream capability owners in Gujarat and Karnataka.
Asia-Pacific Synthetic Camphor Market Segmentation
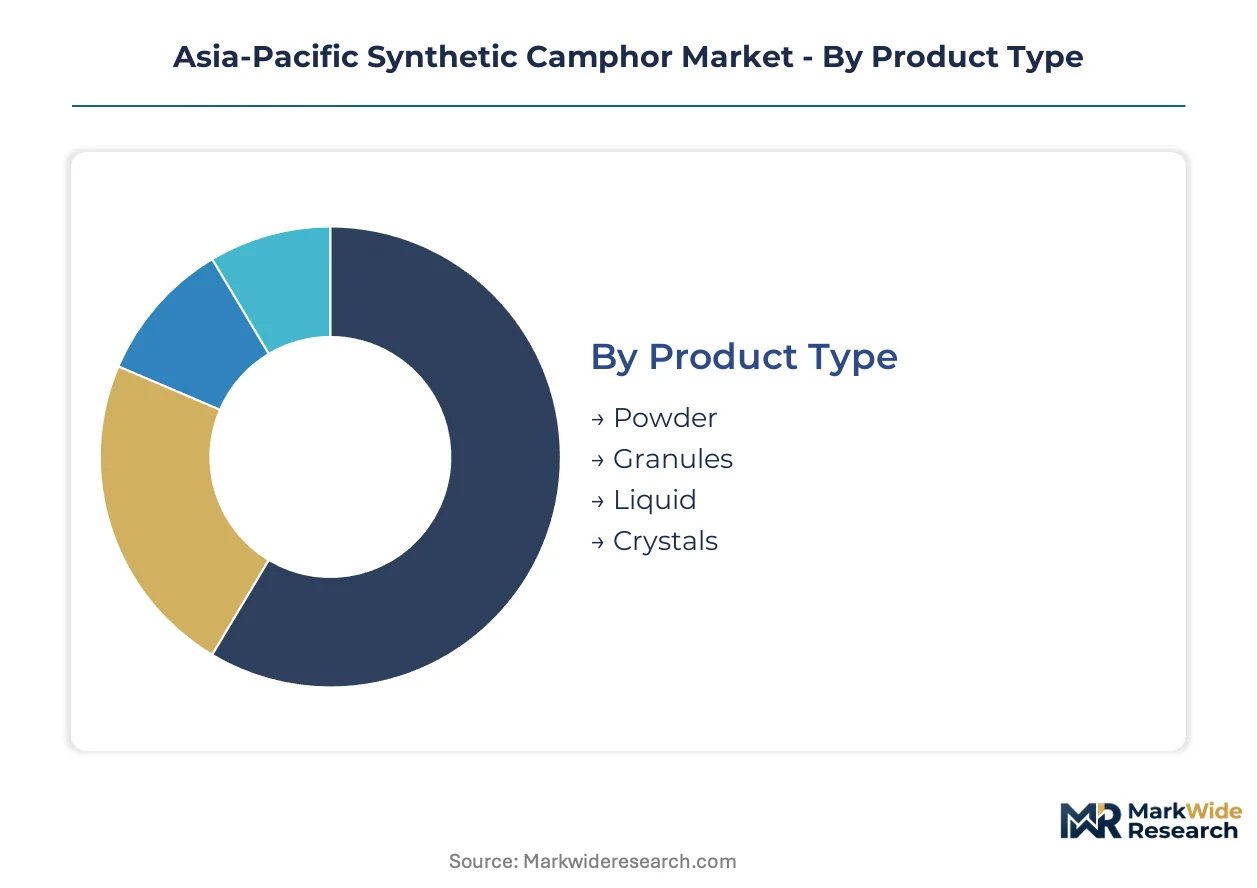
Synthetic camphor demand fragments across four distinct taxonomies in Asia-Pacific. Product type determines upstream manufacturing configuration, while end-use industry dictates purity thresholds and regulatory compliance pathways. Formulation and packaging choices increasingly unbundle as buyers separate commodity procurement from delivery-system engineering.
Product Type:
Powder and granule formats command mature volume positions, whereas liquid and crystal grades occupy emerging premium niches with steeper technical barriers.
- Powder:Fine particulate camphor achieves 96-98% purity through standard catalytic oxidation and recrystallization. Maharashtra and Zhejiang chemical clusters supply bulk powder to western Indian pharmaceutical manufacturers under CDSCO-mandated domestic sourcing thresholds. Powder contracts increasingly exclude formulation services as buyers unbundle purification from blending expertise.
- Granules:Agglomerated particles reduce dust handling hazards and improve flow characteristics for automated pharmaceutical tablet production. Andhra Pradesh's specialty chemical corridor ships granule formats to formulation houses in Gujarat and Karnataka seeking intermediate processing efficiency.
- Liquid:Dissolved or molten camphor enables rapid incorporation into topical emulsions and cosmetic serums without dissolution stages. Fujian province producers with continuous flow reactor capabilities capture premium positioning in fragrance fixative applications.
- Crystals:High-purity monoclinic structures serve analytical reference standards and specialized pharmaceutical excipient roles requiring documented polymorphism control. Japanese PMDA-registered suppliers dominate this specification tier through METI-certified handling protocols.
Powder retains volume leadership; liquid holds the steepest expansion curve.
End Use Industry:
Pharmaceutical and chemical applications anchor established consumption patterns, while cosmetics and food-grade segments command widening purity premiums.
- Pharmaceuticals:Topical analgesic formulations consume camphor as a counter-irritant at 96-99.5% purity grades. India's PLI scheme for active pharmaceutical ingredients redirects procurement toward Maharashtra and Andhra Pradesh manufacturing bases, compressing import dependency from Chinese suppliers.
- Chemicals:Cellulose nitrate plasticizer applications absorb technical-grade camphor at lower purity thresholds than pharmaceutical specifications. Alternative plasticizers in film coating applications are displacing camphor in select industrial buyer segments.
- Cosmetics:Fragrance fixative roles in premium skincare emulsions absorb higher-purity derivatives with documented stability testing. NMPA's revised excipient registration rules favor domestic Chinese producers with in-house analytical capabilities.
- Food:Flavoring agent applications in confectionery and chewing gum formulations require food-grade certification under divergent national safety frameworks. FSSAI in India and MFDS in South Korea enforce non-harmonized additive approvals, fragmenting cross-border product registration.
Chemicals retains volume leadership; cosmetics holds the steepest expansion curve.
Formulation:
Solid delivery systems dominate throughput economics, while liquid formats command formulation-grade margin premiums in pharmaceutical emulsion applications.
- Emulsions:Oil-in-water dispersions enable controlled-release topical medicaments with enhanced skin penetration. Rapid-dissolution properties in liquid emulsion delivery systems command premium positioning as formulation houses pivot from powder toward solution-based applications.
- Solutions:Homogeneous molecular dispersions in alcohol or oil carriers serve cosmetic serum and pharmaceutical tincture applications. Zhejiang specialty chemical clusters deploy ceramic nanofiltration modules to achieve solution-grade purity without multiple recrystallization stages.
- Suspensions:Heterogeneous particulate dispersions require controlled particle size distribution for dosing consistency. Suspension stability testing documentation now mandates under NMPA's revised pharmaceutical excipient registration protocols.
- Powders:Direct compression or blending feedstock for solid dosage forms remains the lowest-cost delivery pathway. Powder formulation demand concentrates in Maharashtra bulk supply contracts serving western Indian pharmaceutical manufacturers.
Powders retains volume leadership; emulsions holds the steepest expansion curve.
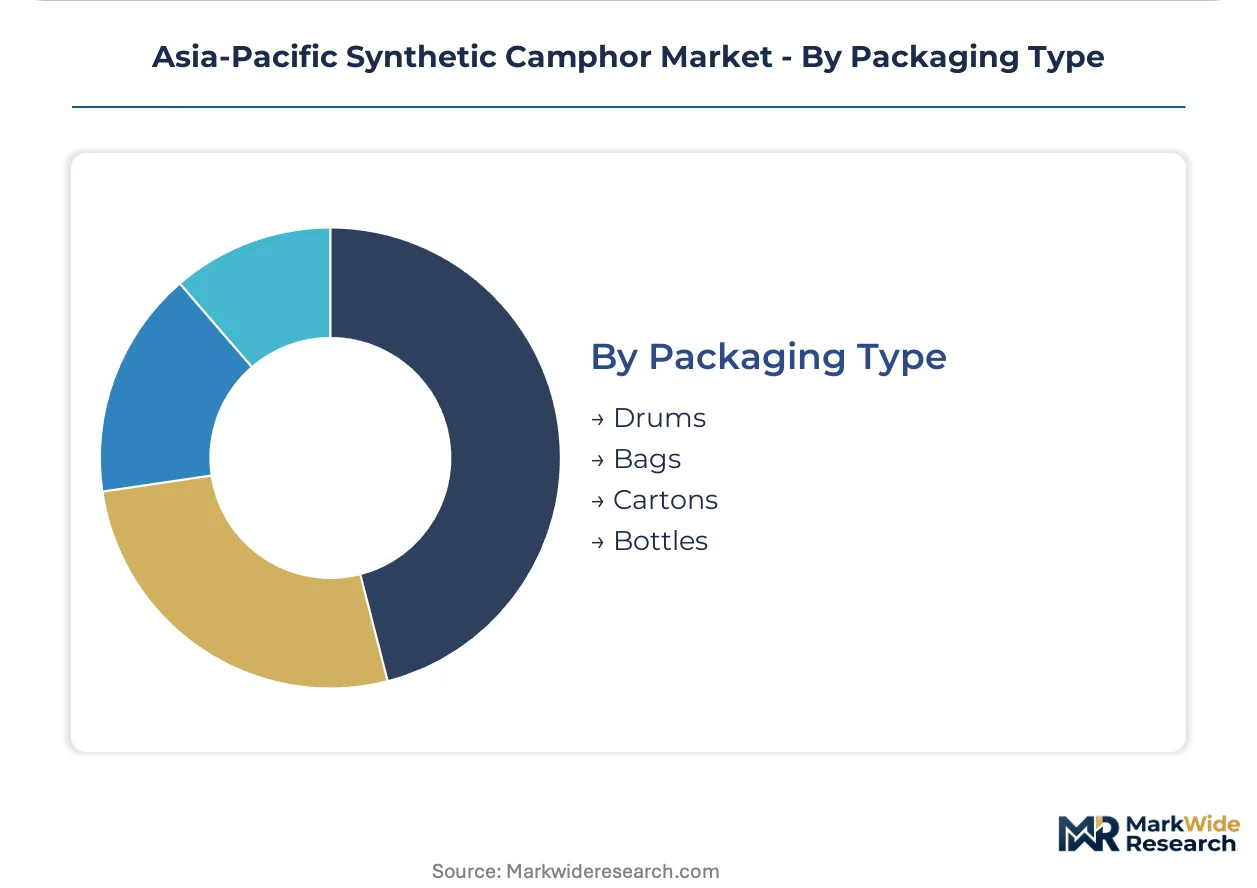
Packaging Type:
Industrial bulk formats serve chemical intermediates procurement, while unitized packaging addresses pharmaceutical and cosmetic formulation hygiene requirements.
- Drums:Steel or fiber containers handle 200-250 kg payloads for chemical intermediate buyers with integrated formulation capabilities. Drum logistics require temperature-controlled infrastructure under METI-administered industrial chemical handling standards for bulk camphor derivatives.
- Bags:Multi-layer polymer sacks with moisture barriers serve powder and granule shipments to mid-scale pharmaceutical manufacturers. Bagged product demand concentrates in Andhra Pradesh's expanding specialty chemical corridor.
- Cartons:Corrugated fiberboard with inner liners protects crystal and high-purity grades from mechanical damage and contamination. Carton packaging supports smaller-batch flexibility for contract formulation houses serving regional cosmetic brands.
- Bottles:Amber glass or fluoropolymer containers preserve liquid camphor stability against photodegradation and oxidation. Bottle formats enable precise dosing for pharmaceutical emulsion and cosmetic serum applications.
Drums retains volume leadership; bottles holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes synthetic camphor chiefly as cellulose nitrate plasticizer and chemical intermediate, while India and Japan prioritize pharmaceutical-grade specifications for topical medicament formulations, creating divergent procurement patterns across the region.
China
Zhejiang and Fujian province specialty chemical clusters supply both domestic plasticizer demand and export pharmaceutical markets. NMPA's 2023 excipient registration revision mandates stability documentation that favors domestic producers with in-house analytical capabilities. Continuous flow reactor adoption in Fujian enables premium liquid camphor output for fragrance fixative applications.
India
Maharashtra and Andhra Pradesh manufacturing bases anchor CDSCO-mandated domestic sourcing for topical analgesic formulations. The PLI scheme for active pharmaceutical ingredients compresses import dependency and accelerates captive production investments. Saptagir Camphor Limited competes on cost structure in Andhra Pradesh's expanding specialty chemical corridor.
Japan
Pharmaceutical-grade crystal specifications for analytical reference standards dominate domestic consumption. METI-administered industrial chemical handling standards constrain bulk import logistics to JIS-certified suppliers. Nagase & Co. Ltd. anchors pharmaceutical distribution channels through specialized temperature-controlled logistics infrastructure.
South Korea
Cosmetic formulation-grade demand absorbs higher-purity derivatives for premium skincare emulsions. MFDS REACH alignment compresses certification burdens for regional exporters targeting multiple national frameworks. Domestic formulators increasingly source solution-grade camphor for rapid-dissolution delivery systems.
Vietnam
Underdeveloped downstream formulation capabilities in northern industrial zones create white space for integrated purification-to-delivery investments. The country's national pharmaceutical regulator maintains additive approval frameworks that fragment cross-border product registration. Specialty chemical infrastructure remains concentrated around Hanoi and Hai Phong port logistics.
Asia-Pacific Synthetic Camphor Market Competitive Landscape
Capability concentration sits with integrated purification specialists; scale advantage sits with bulk powder suppliers serving commodity pharmaceutical feedstock contracts. The market structures around three archetypes: continuous flow reactor operators capturing liquid-grade premiums, regional distributors controlling cold-chain logistics certification, and backward-integrated turpentine processors insulating against alpha-pinene volatility. Dominant competitive moves include unbundling after-sales technical service from commodity supply and consolidating supplier panels to pre-qualified regulatory registrants.
Among India-based specialists, Oriental Aromatics Limited, Saptagir Camphor Limited, and Mangalam Organics Limited occupy positions across Maharashtra and Andhra Pradesh manufacturing clusters. Chinese producers including Fujian Green Pine and Zhejiang Jianye Chemical Co., Ltd. exemplify integrated coastal chemical infrastructure. Nagase & Co. Ltd. represents the logistics-certified distribution archetype essential for Japanese pharmaceutical channel access.
| Leading Market Players |
|---|
| Oriental Aromatics Limited |
| Nagase & Co. Ltd. |
| Saptagir Camphor Limited |
| Hunan Deli Essential Oil Co., Ltd. |
| Skyrun Industrial Co. Ltd. |
| Kanchi Karpooram Limited |
| Fujian Green Pine |
| Zhejiang Jianye Chemical Co., Ltd. |
| Mangalam Organics Limited |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Ningbo port freight corridors transmit alpha-pinene cost volatility directly into downstream price differentiation between pharmaceutical-grade and technical-grade camphor tiers. Zhejiang chemical clusters leverage this logistics concentration to extract premium positioning for liquid formulation grades while Maharashtra bulk powder suppliers compete on contract scale.
Pricing Analysis
Long-term offtake contracts dominate procurement between Maharashtra pharmaceutical manufacturers and domestic powder suppliers under CDSCO-mandated localization thresholds. Three-tier pricing structure across premium crystal grades, standard pharmaceutical powder, and economy technical grades reflects purity certification and METI cold-chain compliance. Cost compression in technical-grade segments intensifies as cellulose nitrate plasticizer substitution accelerates. Small-batch cosmetic formulators exhibit lowest price sensitivity, prioritizing NMPA-registered stability documentation over per-kilogram procurement economics.
Supply Chain Analysis
Alpha-pinene feedstock security anchors supply concentration across China's Zhejiang and Fujian provinces, India's Maharashtra and Andhra Pradesh corridors, and Indonesian plantation regions. Turpentine extraction from gum rosin harvests draws from southern Chinese forestry operations, Indian terpene processors, and Southeast Asian plantation networks. Single-source vulnerability concentrates in Fujian continuous flow reactor capacity for liquid-grade output. Distribution runs through Nagase-certified cold-chain logistics for Japanese pharmaceutical channels and standard bulk freight for Indian domestic chemical intermediate buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive returns as formulation houses unbundle purification from blending expertise, creating interoperability premiums for integrated purification-to-delivery operators.
For Market Incumbents: Entrench regulatory moats by consolidating NMPA and CDSCO pre-qualified supplier panels before emerging Vietnamese entrants achieve certification scale. Deepen backward integration into alpha-pinene processing to insulate margin structures from gum rosin harvest volatility. Prioritize continuous flow reactor capacity additions in Zhejiang over batch processing expansion.
For New Entrants and Emerging Players: Build out Vietnamese northern industrial zone infrastructure to capture white space in integrated formulation services where downstream capabilities remain underdeveloped. Target cosmetic emulsion delivery systems as the most penetrable premium tier given rapid-dissolution property demand and lower regulatory barriers than pharmaceutical-grade registration. Pursue toll manufacturing partnerships with established NMPA-registered Chinese producers to accelerate market access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors continuous flow reactor operators with ceramic nanofiltration capabilities over legacy batch processors. Long-term viability rests on regulatory certification breadth across multiple national frameworks rather than single-market dominance. Watch MFDS REACH alignment implementation as the inflection signal for South Korean export channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Pinene Processing | Maharashtra producers secure feedstock autonomy against Indonesian gum rosin price cycles. |
| Ceramic Nanofiltration Module Deployment | Zhejiang clusters achieve 99.5% purity thresholds without multiple recrystallization stages. |
| NMPA Excipient Registration Acceleration | Domestic Chinese producers capture approval timeline advantages over import-dependent competitors. |
| Temperature-Controlled Logistics Certification | METI-compliant cold-chain infrastructure unlocks Japanese pharmaceutical distribution channels. |
| Liquid Emulsion Delivery System Capacity | Fujian continuous flow operators command premium positioning in cosmetic fragrance fixative applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at alpha-pinene processing facilities, pharmaceutical procurement leads, cosmetic formulation directors, and cold-chain logistics operators; and secondary validation through customs trade records, CDSCO registration databases, NMPA excipient filings, and chemical industry association reports. Bottom-up capacity modeling across Zhejiang, Fujian, Maharashtra, and Andhra Pradesh production clusters triangulated against top-down demand estimation from pharmaceutical, cosmetic, and chemical intermediate end-use segments.
Forecast inputs incorporated grade-tier purity specifications, end-use industry growth differentials, packaging format migration patterns, and regional regulatory cluster alignment. Modeled segmentation spanned powder-granule-liquid-crystal product types, pharmaceutical-chemical-cosmetic-food end-use industries, and emulsion-solution-suspension-powder formulation pathways. CAGRs derived from supply-demand balance projections across the analysis window, with alpha-pinene feedstock cost curves and CDSCO localization mandate implementation timelines as primary sensitivity variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Vietnamese greenfield entrants or accelerated cellulose nitrate substitution by industrial chemical buyers would shift outcomes beyond modeled ranges. Cross-checking against MFDS registration pipeline data and Maharashtra state industrial production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
4-Tert-Butylcyclohexanone Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
US Humate Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Alanine Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Benzyl Cyanide Market