
 Stadium and Arena Management Solution Market | 2026-2036
Stadium and Arena Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Stadium and Arena Management Solution Market Outlook
Cloud-native deployment architectures is tilting how stadium operators procure integrated management platforms, replacing on-premise legacy stacks with API-first ecosystems. Johnson Controls leverages its building-automation heritage to anchor smart-venue infrastructure across North American arenas. Momentus competes through specialized event-logistics software that coordinates load-in schedules and union labor rules for touring productions. Tech Mahindra extends its IT services footprint into venue digitization by bundling IoT sensor networks with managed security operations.
Stadium and arena management solutions comprise integrated software platforms that orchestrate venue operations through real-time data fusion from access control turnstiles, point-of-sale terminals, and environmental control systems, typically processing sub-second transaction latency for concurrent spectator volumes exceeding 80,000. These systems serve commercial venues by unifying ticketing validation, crowd flow optimization, and revenue analytics into single-pane command interfaces. Ticketing Solutions occupies the largest technology segment due to persistent demand for dynamic pricing engines and fraud-resistant digital credentialing. Fan Engagement represents the fastest-expanding category as venues deploy augmented-reality wayfinding and personalized concession promotions to capture ancillary spend per attendee. Venue Management remains the margin pool where multi-year service contracts and SaaS renewal rates concentrate profitability for platform vendors.
FAA guidelines govern drone-based aerial surveillance deployments above outdoor stadiums, while OSHA standards shape venue staff safety protocols and emergency evacuation system certifications. The EU AI Act imposes algorithmic transparency requirements on automated crowd-density analytics and biometric entry systems deployed in European arenas. Stakeholders must monitor evolving data-localization mandates and interoperability standards that determine whether centralized cloud architectures or federated edge deployments become the compliant default for cross-border event operations.
Market Dynamics
Cloud-native deployment architectures are displacing on-premise legacy stacks across professional sports franchises, forcing vendors to rearchitect platforms for API-first interoperability while municipal fire-safety and accessibility codes mandate integrated emergency response modules.
Growth Catalysts
- NCAA Division I facility upgrades:Collegiate athletic programs in the United States are driving sustained procurement cycles for integrated venue management platforms as stadium modernization accelerates across Power Five conferences.
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated crowd-density analytics are compelling European arena operators to upgrade biometric entry systems and analytics engines.
- Edge computing convergence:Real-time processing demands for sub-second transaction latency at venues exceeding 80,000 concurrent spectators are pushing architectures toward federated edge deployments.
Market Restraints
- Union labor rule complexity:Load-in scheduling coordination for touring productions faces rigid jurisdictional constraints that increase implementation costs and extend deployment timelines.
- Data-localization fragmentation:Cross-border event operations encounter conflicting sovereignty requirements that complicate centralized cloud architectures and inflate compliance overhead.
- Legacy system entrenchment:Existing building automation investments create technical debt that slows migration to unified command interfaces and API-first ecosystems.
Strategic Opportunities
- Augmented-reality wayfinding:Fan Engagement category expansion enables personalized concession promotions that capture ancillary spend per attendee through spatial computing overlays.
- Dynamic pricing engine penetration:Ticketing Solutions segment growth supports fraud-resistant digital credentialing and real-time revenue optimization across secondary markets.
- Managed security operations bundling:IoT sensor network integration with venue digitization creates recurring revenue streams through multi-year service contracts.
Industry Challenges
- Interoperability standard delays:Fragmented protocols between access control turnstiles, point-of-sale terminals, and environmental control systems impede single-pane command interface deployment.
- Emergency response certification timelines:FAA drone-based aerial surveillance guidelines and OSHA evacuation system certifications require extended validation cycles before outdoor stadium deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stadium and Arena Management Solution Market |
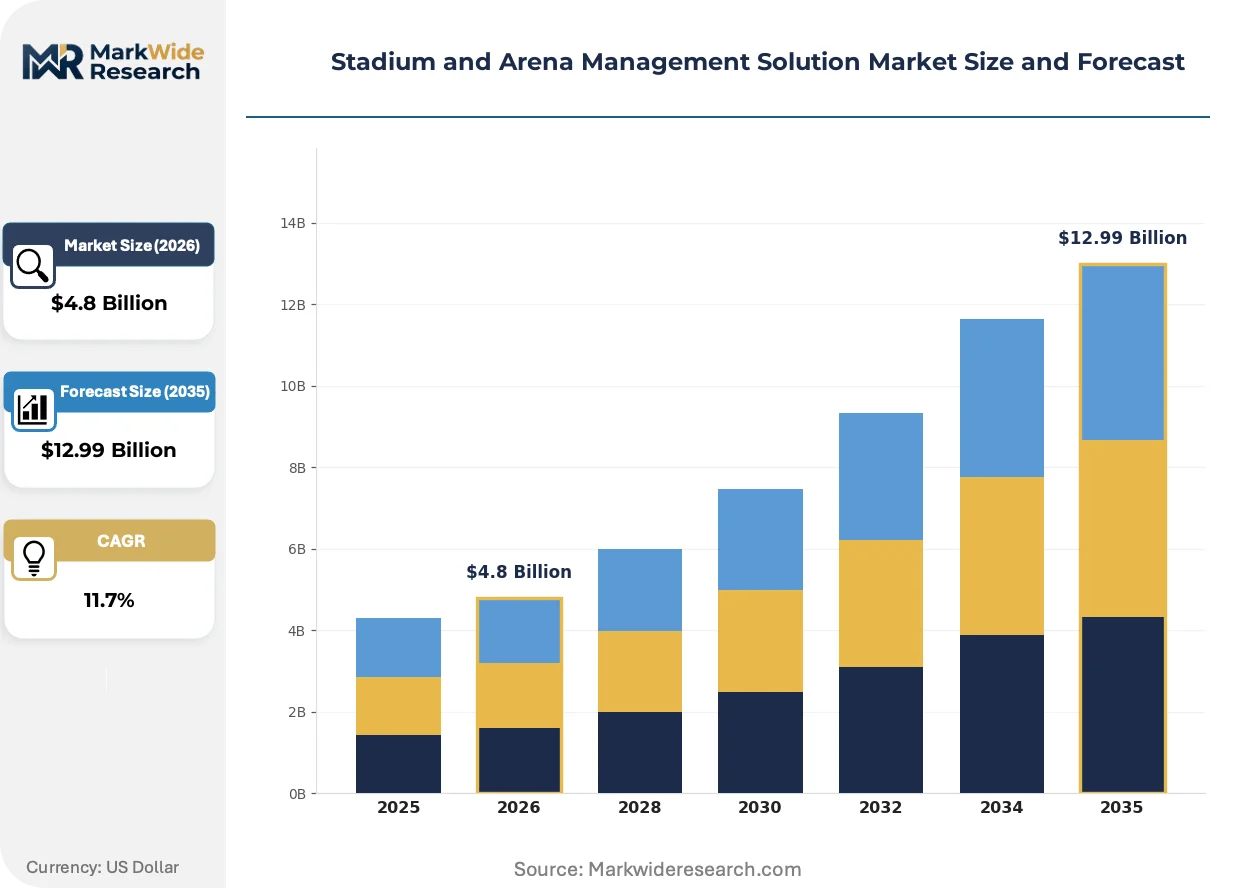
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Access Control, Ticketing Solutions, Fan Engagement, Venue Management Application: Sports Events, Concerts, Corporate Events, Exhibitions Service Type: Event Management, Security Services, Catering Services, Maintenance Services Customer Type: Stadium Owners, Event Organizers, Sponsors, Athletes |
| Companies Covered | OnePlan, SWORD Venue, Momentus, Tech Mahindra, GP Smart Stadium, VenuePro, Iventis, Johnson Controls, Virtual Venue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stadium and Arena Management Solution Market Strategic Shifts
Real-time data fusion from disparate venue subsystems is compressing operational decision cycles, while regulatory pressure on algorithmic transparency and shifting procurement preferences toward SaaS renewal models are restructuring vendor-customer relationships.
Digital twin technology is hybridizing physical venue infrastructure with virtual simulation layers, enabling predictive maintenance and scenario modeling for crowd flow optimization. Professional sports franchises and municipal arena operators are adopting these platforms at accelerated cadences to reduce operational risk. This convergence is hybridizing capital planning processes by allowing operators to test configuration changes virtually before physical deployment.
OSHA standards governing venue staff safety protocols and emergency evacuation system certifications are tightening compliance requirements for automated response triggers. Industrial consequence includes mandatory integration of environmental control systems with access control databases for synchronized lockdown procedures. North American arenas face the steepest adaptation curves as they retrofit legacy installations to meet unified certification standards.
Subscription-based platform procurement is displacing perpetual license purchases as franchise finance departments prioritize operational expenditure predictability. Venue operators are unbundling after-sales service contracts from initial software acquisition, creating discrete negotiation points for SaaS renewal rates and managed security operations. This behavioral shift concentrates most visibly among United States-based professional sports franchises with centralized procurement functions.
Stadium and Arena Management Solution Market Segmentation
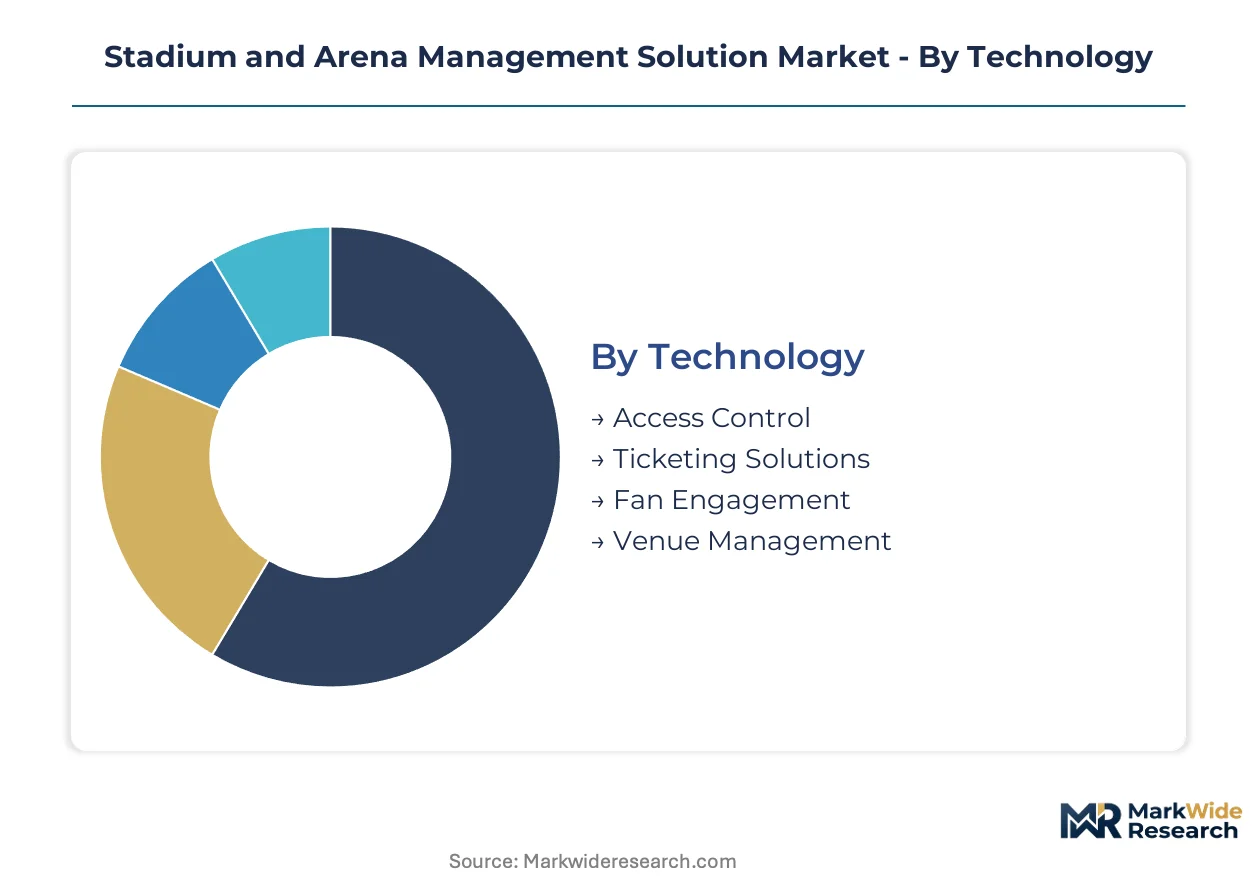
Venue operators deploy distinct technology stacks depending on whether they prioritize revenue capture, operational efficiency, or spectator experience. Procurement patterns diverge sharply between municipal arena owners and commercial event promoters, creating four discrete segmentation axes that determine vendor go-to-market strategies.
Technology:
Functional capability separates platforms by the latency requirements and integration depth they deliver across venue subsystems.
- Ticketing Solutions:Dynamic pricing engines process real-time demand signals while fraud-resistant digital credentialing reduces scalping losses. United States collegiate athletic programs sustain procurement intensity as NCAA Division I facilities modernize access infrastructure.
- Fan Engagement:Augmented-reality wayfinding and personalized concession promotions capture ancillary spend per attendee through spatial computing overlays. European arena operators accelerate deployment to comply with EU AI Act transparency mandates for algorithmic recommendation systems.
- Access Control:Biometric entry systems and turnstile validation networks enforce credential verification at sub-second latency.
- Venue Management:Unified command interfaces orchestrate environmental control, crowd flow, and emergency response from single-pane dashboards.
Ticketing Solutions holds installed capacity. Fan Engagement is rotating up the share rankings.
Application:
Event format dictates the concurrency peaks, revenue mix, and regulatory exposure that management platforms must accommodate.
- Sports Events:Professional franchises and collegiate programs require season-long platform stability with surge capacity for playoff fixtures. United States venues drive sustained investment as municipal modernization cycles and NCAA facility upgrades concentrate demand.
- Concerts:Touring productions impose load-in scheduling complexity and union labor rule coordination that specialized logistics modules address. North American arenas face the steepest adaptation curves for OSHA-compliant evacuation system certifications.
- Corporate Events:Single-day or multi-day conventions prioritize flexible seating reconfiguration and integrated AV production workflows.
- Exhibitions:Trade shows demand floor plan optimization tools combined with exhibitor lead-capture integration.
Sports Events anchors procurement volume. Concerts is climbing the fastest as touring production schedules normalize.
Service Type:
Margin concentration varies by whether vendors deliver discrete project execution or multi-year recurring service relationships.
- Event Management:Load-in coordination, union labor scheduling, and touring production logistics command premium pricing for specialized expertise. European operators face EU AI Act compliance overhead for automated crowd-density analytics.
- Security Services:Integrated access control, drone-based aerial surveillance, and emergency response module deployment require FAA certification cycles for outdoor stadiums.
- Catering Services:Concession inventory management and point-of-sale terminal integration optimize per-capita food and beverage revenue.
- Maintenance Services:Predictive maintenance modules leveraging IoT sensor networks reduce unplanned downtime for critical venue infrastructure.
Event Management holds the deepest contract backlogs. Security Services is gaining share fastest as regulatory certification requirements tighten.
Customer Type:
Procurement authority and budget cycle timing diverge between asset owners and temporary event tenants.
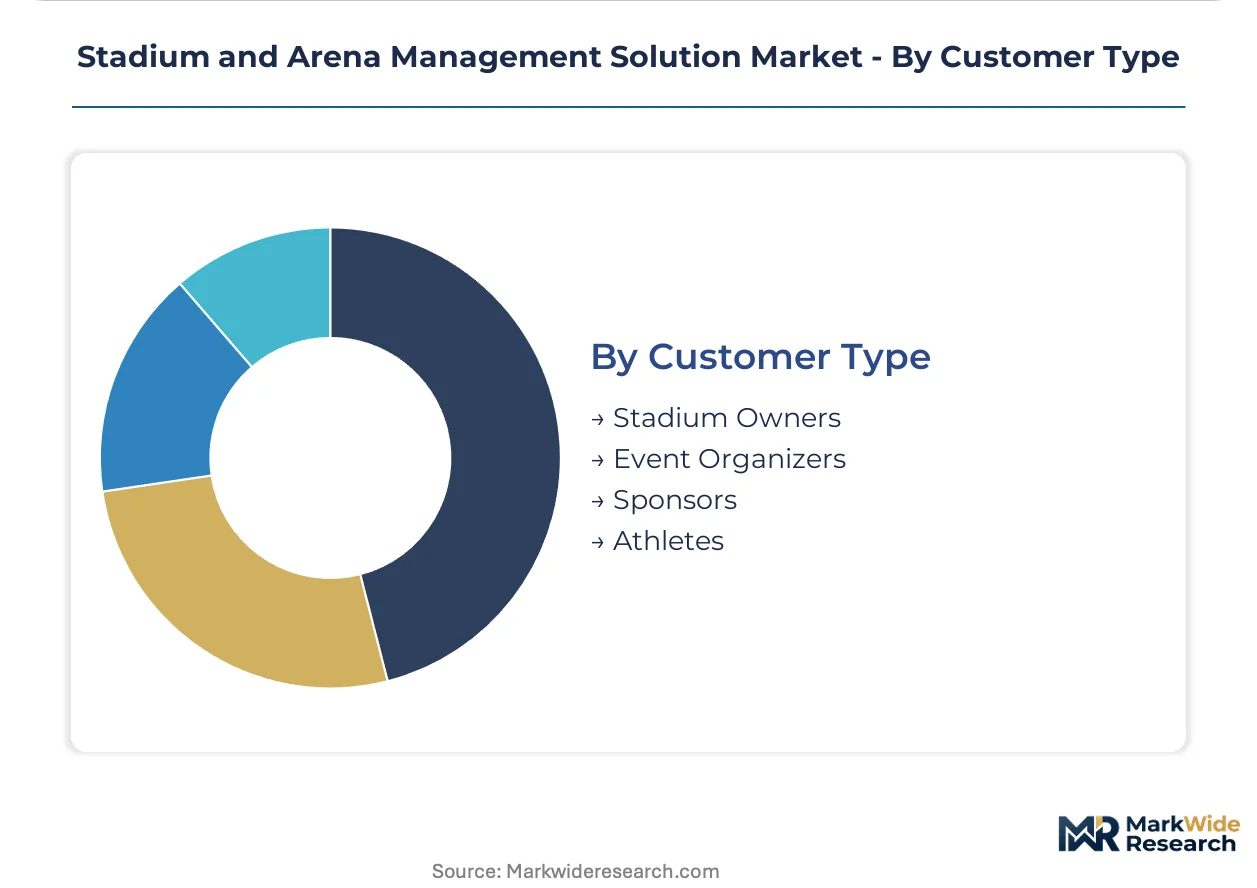
- Stadium Owners:Municipal and private venue operators prioritize multi-year SaaS renewal models and operational expenditure predictability. United States-based franchises with centralized procurement functions unbundle after-sales service from initial software acquisition.
- Event Organizers:Touring promoters and production companies demand API-first interoperability for rapid platform deployment across heterogeneous venue environments.
- Sponsors:Brand activation partners require fan engagement module access for personalized promotion delivery and attribution analytics.
- Athletes:Individual performers and sports teams utilize training facility management features and performance analytics integration.
Stadium Owners command platform selection authority. Event Organizers is rotating up the share rankings as touring volume recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export intensity in venue management software remains concentrated in North American and European vendors, while import demand accelerates across Asia-Pacific and Middle Eastern markets seeking turnkey digitization packages for new stadium construction.
United States
NCAA Division I facility upgrades and municipal arena modernization cycles sustain procurement volume across Power Five conferences and metropolitan markets. OSHA standards governing emergency evacuation system certifications tighten compliance requirements for automated response triggers. Los Angeles and Atlanta clusters anchor deployment density as legacy venues retrofit unified command interfaces.
Germany
EU AI Act algorithmic transparency mandates compel arena operators to upgrade biometric entry systems and crowd-density analytics engines. REACH compliance frameworks shape IoT sensor network specifications for environmental control integration. Munich and Frankfurt metropolitan areas concentrate vendor implementation teams serving Central European venue networks.
United Kingdom
Premier League stadium digitization programs and London venue modernization sustain platform demand across commercial and municipal asset portfolios. GDPR data-localization requirements complicate centralized cloud architectures for cross-border event operations. Greater Manchester and West Midlands clusters host specialized logistics modules addressing touring production load-in coordination.
Japan
Tokyo 2020 legacy venue repurposing and JIS standards alignment drive integrated management platform adoption across prefectural stadium networks. METI industrial digitization incentives subsidize IoT sensor network deployment for predictive maintenance modules. Kanto and Kansai metropolitan areas concentrate domestic systems integrators bundling venue digitization with managed security operations.
Australia
AFL and NRL venue consolidation programs sustain investment intensity across Melbourne and Sydney metropolitan markets. TGA-equivalent certification pathways for emergency response modules extend deployment timelines for automated evacuation systems. New South Wales and Victoria state governments anchor procurement authority for multi-year SaaS renewal models prioritizing operational expenditure predictability.
Stadium and Arena Management Solution Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: building-automation incumbents extending smart-venue infrastructure, specialized event-logistics software providers, and IT services bundlers integrating IoT networks with managed security operations. Dominant competitive moves include API-first ecosystem partnerships displacing on-premise legacy stacks and multi-year service contract unbundling that separates after-sales support from initial software acquisition.
Within the building-automation tier, Johnson Controls anchors North American smart-venue infrastructure deployment. Among specialized logistics providers, Momentus occupies a position coordinating load-in schedules and union labor rules for touring productions. Tech Mahindra represents the IT services bundling archetype, extending venue digitization through IoT sensor network integration. These three exemplify how vendor archetypes map to distinct procurement preferences across municipal arena operators and commercial event promoters.
| Leading Market Players |
|---|
| OnePlan |
| SWORD Venue |
| Momentus |
| Tech Mahindra |
| GP Smart Stadium |
| VenuePro |
| Iventis |
| Johnson Controls |
| Virtual Venue |
| Others |
Value Chain & Pricing Dynamics
Los Angeles and Atlanta clusters anchor North American smart-venue infrastructure capacity, concentrating API-first platform development and compressing deployment cost curves for municipal arena operators downstream. Cloud-native software stacks from these hubs command pricing premiums against legacy on-premise alternatives, while subscription renewal rates concentrate margin capture for vendors with established building-automation heritage.
Pricing Analysis
Stadium owners anchor pricing structure around three-tier SaaS subscription models across premium, standard, and economy deployment levels. Price differentiation rests on integration depth with environmental control systems and FAA-certified emergency response modules. Cost compression in standard-tier offerings is intensifying because collegiate athletic programs prioritize operational expenditure predictability over capital-intensive perpetual licenses. Municipal arena operators exhibit highest price sensitivity, while professional sports franchises with centralized procurement functions demonstrate lowest sensitivity due to multi-year service contract unbundling.
Supply Chain Analysis
Upstream sensor hardware and edge computing components draw from Taiwan, South Korea, and United States fabrication facilities. IoT sensor networks, biometric entry terminals, and point-of-sale integration modules constitute critical input dependencies. Single-source vulnerability in semiconductor supply for real-time transaction processing creates exposure to logistics chokepoints at East Asian ports. Distribution runs through systems integrators bundling venue digitization with managed security operations, with Johnson Controls and Tech Mahindra archetypes dominating North American and European deployment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates substantial switching costs for venue operators facing OSHA evacuation certification mandates and EU AI Act compliance overhead.
For Market Incumbents: Pre-empt API-first ecosystem fragmentation by acquiring specialized event-logistics software providers before they consolidate touring production relationships. Momentus-type competitors threaten margin pools in load-in coordination modules. Certification investment in FAA drone-based aerial surveillance and EU AI Act algorithmic transparency represents the priority lever to deepen municipal contract backlogs and extend renewal lock-in periods. For New Entrants and Emerging Players: Asia-Pacific new stadium construction corridors present underpenetrated white-space for turnkey digitization packages bundling IoT sensor networks with managed security operations. Middle Eastern markets seeking unified command interfaces for greenfield venues offer comparable entry points. Channel partnership with domestic systems integrators in Japan and Australia provides the most penetrable go-to-market angle, leveraging METI industrial digitization incentives and state government procurement authority respectively. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because SaaS renewal models and multi-year service contracts concentrate profitability in venue management platforms. Acquisition targets should emphasize vendors with established OSHA-compliant emergency response modules and federated edge deployment capabilities. The signal to watch is NCAA Division I facility upgrade cycle velocity, as Power Five conference procurement decisions indicate platform standardization momentum across collegiate athletic programs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first ecosystem partnerships displace on-premise legacy stacks across professional sports franchises. |
| Acquisition of Specialist Firm | Event-logistics software providers deepen touring production relationships and union labor rule expertise. |
| Geographic Expansion | Asia-Pacific and Middle Eastern new stadium construction channels demand turnkey digitization packages. |
| Strategic Partnership | Systems integrators in Japan and Australia bundle venue digitization with managed security operations. |
| Product Launch | Augmented-reality wayfinding modules capture ancillary spend per attendee through spatial computing overlays. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with venue operations directors, IT procurement officers, municipal arena managers, and touring production logistics coordinators; and secondary validation through SEC filings of building-automation vendors, FAA certification databases, EU AI Act regulatory disclosures, and NCAA facility upgrade announcements. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against SaaS renewal rate benchmarks anchored market sizing.
Forecast inputs considered deployment model, venue capacity tier, integration complexity with legacy environmental control systems, and regional regulatory framework clusters across the analysis window. CAGRs derived from segmented growth rate reconciliation between ticketing solutions, fan engagement modules, and venue management platforms. Edge computing convergence timelines and EU AI Act compliance investment cycles served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive platform integration moves by IT services bundlers would shift outcomes beyond modeled ranges. Cross-checking against NCAA Division I capital expenditure disclosures and municipal arena modernization bond issuances is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market