
 Fantasy Sports Market | 2026-2036
Fantasy Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Fantasy Sports Market Analysis
Real-time data streaming and machine-driven lineup optimization is rewriting how fantasy sports platforms deliver player experiences. DraftKings leverages proprietary scoring algorithms to sustain engagement across daily fantasy formats. FanDuel anchors its position through geographic dominance in state-regulated US markets. Yahoo Fantasy Sports differentiates via hybrid platform architecture spanning web and mobile ecosystems.
Fantasy sports constitutes a digital gaming category where participants assemble virtual rosters of real-world athletes, with point accumulation tied to live statistical performance across professional leagues. Platforms process millions of concurrent data feeds from official league sources to calculate scores within sub-second latency windows, serving both entertainment and wagering-adjacent commercial purposes. Mobile app deployment captures the fastest-growing participation channel as smartphone penetration deepens. Daily fantasy formats command premium revenue pools due to accelerated contest cycles and repeated entry fees. Season-long leagues retain mature, high-retention user bases with lower customer acquisition costs.
The US market navigates a patchwork of state gambling commissions and the Unlawful Internet Gambling Enforcement Act, with individual states determining whether fantasy contests constitute games of skill or chance. India's TRAI and state-level gaming authorities impose divergent restrictions on real-money features, forcing platform operators to modularize product architectures by jurisdiction. Stakeholders must monitor regulatory classification shifts in key states and countries, as reclassification decisions directly determine addressable market boundaries and permissible revenue models.
Market Dynamics
Real-time data streaming infrastructure and machine-driven lineup optimization are compressing contest cycle times from hours to minutes, forcing platforms to rebuild latency architecture around sub-second scoring calculations.
Growth Catalysts
- India's PLI scheme for digital gaming infrastructure:Production-linked incentives for server farms and data centers reduce platform operating costs in the fastest-expanding user geography.
- Mobile-first engagement protocols:Smartphone penetration among the 25-34 demographic accelerates participation rates through frictionless app onboarding and push-notification contest entry.
- State-regulated wagering frameworks:Individual US state gambling commissions clarifying fantasy sports as games of skill open addressable markets previously classified under chance-based prohibitions.
Market Restraints
- Input cost volatility in cloud compute:AWS, Azure, and Google Cloud pricing fluctuations directly compress platform margins on high-frequency daily fantasy formats.
- Regulatory fragmentation across Indian states:Telangana, Andhra Pradesh, and Karnataka impose divergent real-money gaming restrictions, forcing product modularization by jurisdiction.
- Substitution threat from sports betting legalization:State-by-state expansion of fixed-odds wagering draws overlapping user bases away from fantasy roster construction.
Strategic Opportunities
- Brazil's emerging regulatory clarity:ANVISA and federal gaming authority consultations signal forthcoming licensing frameworks for skill-based digital contests.
- Convergence of AI lineup optimizers with blockchain verification:Transparent scoring algorithms and immutable contest records address integrity concerns in high-stakes entry pools.
- Adjacent real-money gaming verticals:Rummy, poker, and casual skill-game modules extend platform lifetime value beyond seasonal sports calendars.
Industry Challenges
- Machine learning engineer scarcity:Sub-second latency scoring systems require specialized talent pools concentrated in Bangalore, San Francisco, and London.
- Multi-jurisdiction compliance architecture:Simultaneous adherence to US state gambling commissions, India's TRAI, and EU GDPR creates engineering complexity.
- Legacy payment rail integration:UPI in India, ACH in the US, and PIX in Brazil demand localized treasury operations for contest entry and payout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fantasy Sports Market |
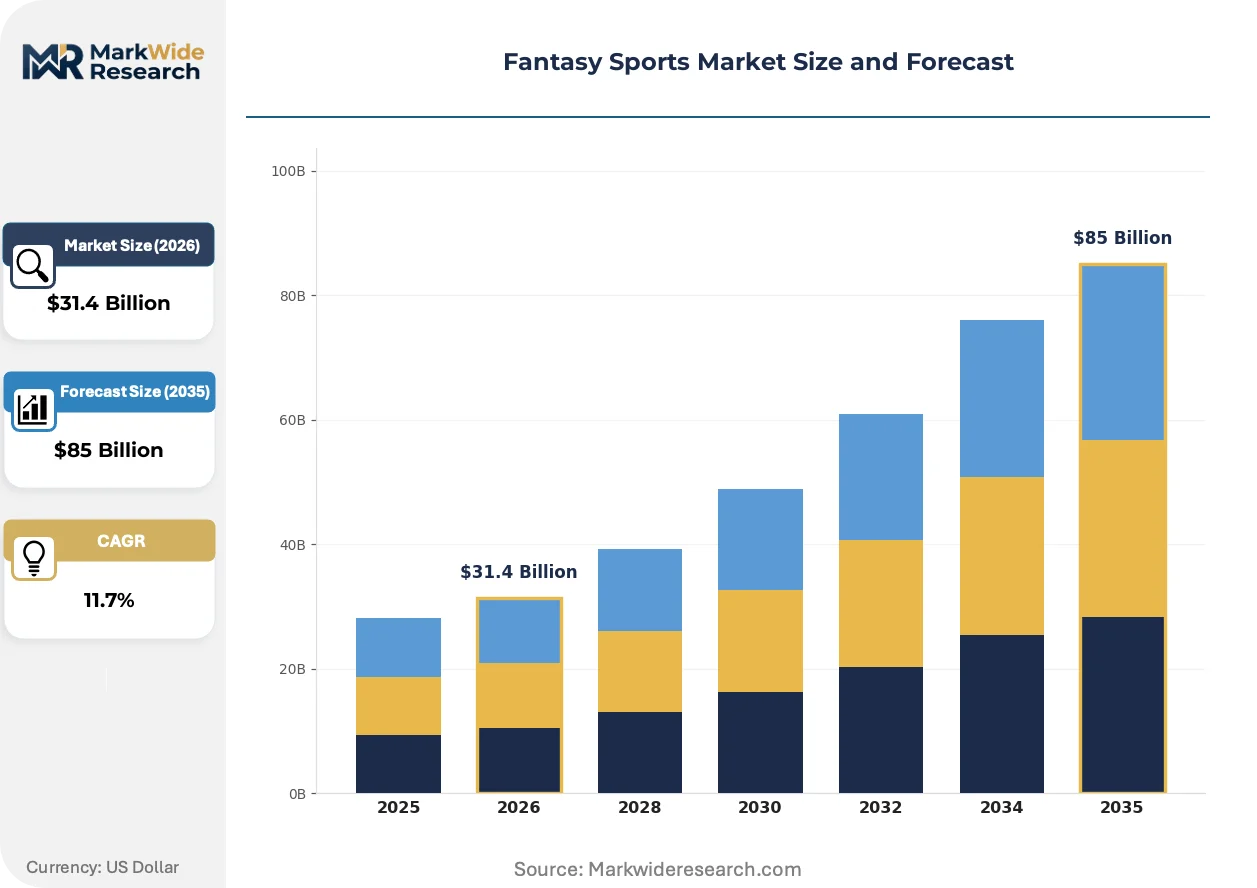
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $85 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Web-Based, Mobile App, Social Media, Hybrid Game Type: Daily Fantasy, Season-Long, Best Ball, Auction Participation Model: Paid, Free, Freemium, Subscription Age Group: 18-24, 25-34, 35-44, 45+ |
| Companies Covered | DraftKings, FanDuel, Yahoo Fantasy Sports, ESPN Fantasy Sports, CBS Sports Fantasy, Dream Sports, FantasyPros, Sleeper, PrizePicks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fantasy Sports Market Emerging Trajectories
Algorithmic contest generation and predictive player-performance modeling are compressing the gap between passive viewership and active participation, reshaping how platforms monetize sports media consumption.
Generative AI tools for automated lineup suggestions and injury-risk alerts are rendering obsolete manual research workflows that previously consumed 60-90 minutes per contest entry. Casual participants in the 25-34 age bracket adopt these tools at 3x the rate of season-long league veterans. The compression of pre-contest preparation time expands addressable user bases beyond dedicated sports analysts.
The US Unlawful Internet Gambling Enforcement Act and state-level gambling commission rulings create a patchwork where fantasy sports classification shifts quarterly. Platforms operating across multiple states must maintain modular compliance architectures that can toggle real-money features by ZIP code. Daily fantasy operators respond by concentrating lobbying resources in states with pending skill-game legislation.
Social contest formats and friend-league structures displace anonymous large-field tournaments as the primary acquisition channel. WhatsApp and Telegram group integrations in India and Brazil replace traditional email invites, shortening viral loop cycles from days to hours. This behavioral shift concentrates highest lifetime value users in closed social graphs rather than open marketplace formats.
Fantasy Sports Market Segmentation
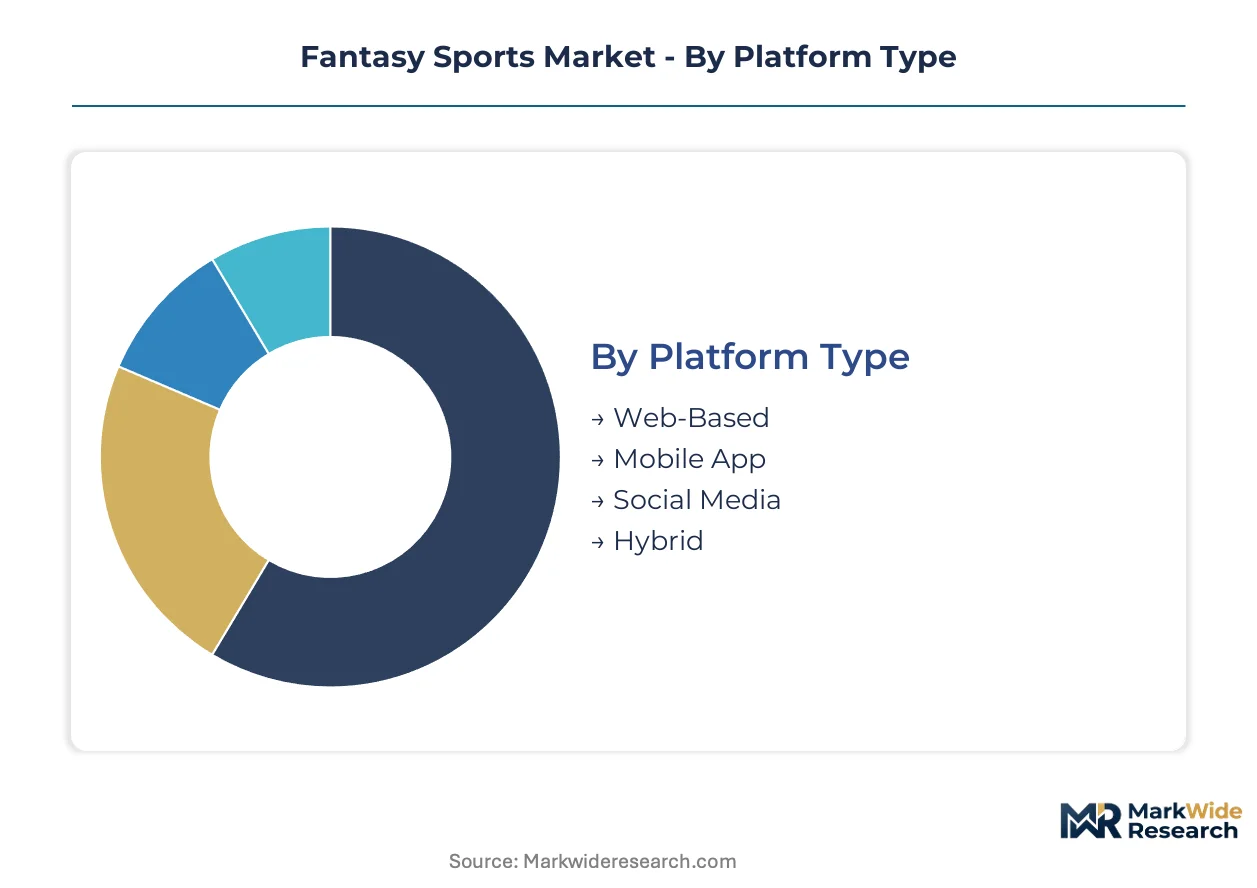
Fantasy sports platforms engineer distinct user experiences across platform architectures, contest formats, and monetization models. Segmentation reveals how operators balance engagement depth against acquisition cost in a market where mobile penetration and regulatory fragmentation reshape addressable audiences.
Platform Type:
Mature web infrastructure coexists with emerging mobile-native architectures as smartphone penetration redefines participation channels.
- Web-Based:Browser-accessible interfaces deliver complex roster management tools and multi-screen analytics suites. Legacy season-long leagues retain concentrated usage among 35-44 demographic cohorts in the US and India, though migration pressure from mobile alternatives intensifies.
- Mobile App:Native iOS and Android deployments capture push-notification contest entry and geofenced compliance toggling. India and Brazil exhibit steepest expansion trajectory as UPI and PIX integration reduces payment friction for daily fantasy participation.
- Social Media:Embedded contest layers within messaging platforms compress viral acquisition cycles. WhatsApp group integrations in India and Telegram channels in Brazil displace traditional email invites for friend-league formation.
- Hybrid:Synchronized web-mobile architectures preserve state across device switches. Cross-platform parity requirements strain engineering resources at mid-tier operators lacking dedicated platform teams.
Mobile App handles the majority of throughput; Social Media is the fastest mover on share.
Game Type:
Contest cycle duration and roster construction mechanics segment users by time commitment tolerance and analytical sophistication.
- Daily Fantasy:Compressed contest windows from hours to minutes demand sub-second scoring latency and real-time injury monitoring. Premium revenue concentration in the US market attracts cloud compute investment for high-frequency entry processing.
- Season-Long:Extended calendar engagement spans 16-22 week league cycles with waiver wire transactions and trade negotiations. Mature user bases in the US and India generate lower customer acquisition costs but slower monetization velocity.
- Best Ball:Automated lineup optimization eliminates weekly management burden. Emerging format adoption accelerates among 25-34 age bracket seeking reduced time investment without sacrificing competitive depth.
- Auction:Salary-cap alternative using dynamic bid mechanics for roster construction. Niche concentration among analytical veterans in season-long league ecosystems.
Daily Fantasy commands dominant revenue contribution; Best Ball is gaining share fastest.
Participation Model:
Monetization architecture stratifies across entry-fee dependence, advertising support, and recurring subscription streams.
- Paid:Direct entry-fee contests with prize pool distributions. Regulatory classification as skill-game versus gambling determines addressable market boundaries in the US and Indian state jurisdictions.
- Free:Ad-supported participation with sponsored contest formats. Entry-level funnel for converting casual participants toward paid tier migration.
- Freemium:Tiered feature access with premium analytics and lineup optimizers behind paywalls. Fastest-expanding model as platforms seek recurring revenue without full paywall exclusion.
- Subscription:Flat-fee unlimited contest entry eliminating per-transaction friction. Concentrated adoption among high-volume daily fantasy participants in the US market.
Freemium architectures handle expanding user acquisition; Subscription models are climbing the fastest on revenue per user metrics.
Age Group:
Generational cohorts exhibit divergent platform preferences, contest format adoption, and monetization responsiveness.
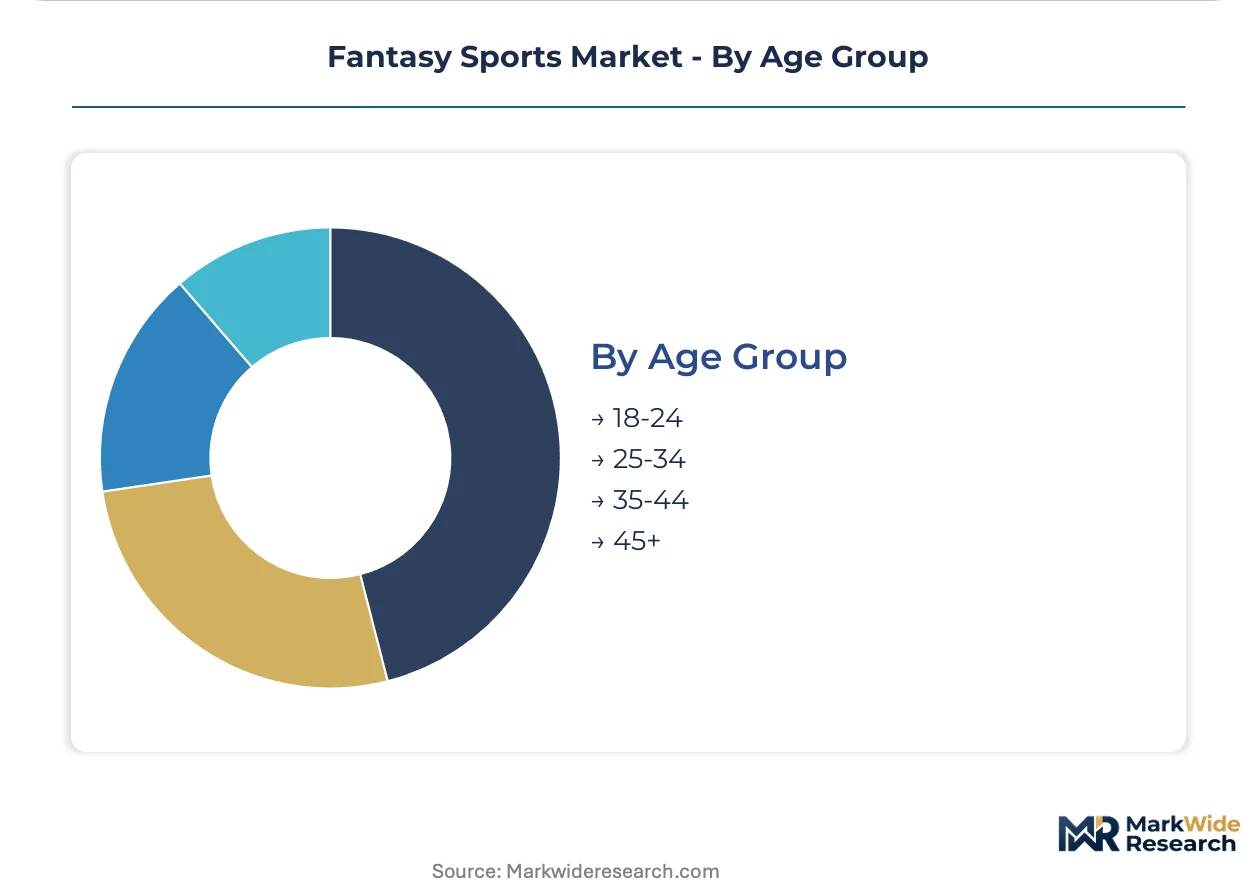
- 18-24:Mobile-native entry with social contest sharing and influencer-driven acquisition. Price-sensitive participation concentrated in free-to-play and low-stakes daily fantasy formats.
- 25-34:Core revenue demographic exhibiting 3x adoption rate of AI-powered lineup tools versus older cohorts. India and US markets show highest per-user engagement minutes.
- 35-44:Season-long league veterans with established social graphs and lower churn propensity. Web-platform preference persists despite mobile migration pressure.
- 45+:Conservative contest selection with preference for season-long stability over daily volatility. Underpenetrated segment representing expansion opportunity for simplified mobile interfaces.
25-34 cohort drives monetization throughput; 45+ segment is expanding most quickly as platform onboarding simplification improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports fantasy sports platform architecture and real-money gaming expertise to Brazil and Southeast Asian markets seeking regulatory templates. The United States channels daily fantasy technology licensing to Canadian and Mexican operators navigating similar compliance frameworks.
United States
State gambling commissions in New Jersey, Pennsylvania, and Michigan classify fantasy contests as skill games, opening premium revenue pools. The Unlawful Internet Gambling Enforcement Act creates federal guardrails while individual states determine permissible contest formats. Boston and New York City clusters concentrate machine learning engineering talent for sub-second scoring latency systems.
India
TRAI guidelines and state-level gaming authority consultations shape platform operating permissions across Maharashtra, Karnataka, and Telangana. The PLI scheme for digital gaming infrastructure subsidizes server farm investments by Dream Sports and competitors. Bangalore anchors product development teams while Mumbai hosts payment rail integration specialists for UPI transaction processing.
Brazil
ANVISA consultations and federal gaming authority deliberations signal forthcoming licensing frameworks for skill-based digital contests. PIX instant payment integration reduces entry-fee friction for daily fantasy participation. São Paulo clusters emerging platform operators seeking regulatory clarity before nationwide rollout.
Canada
Provincial lottery corporations and provincial gaming authorities determine fantasy sports classification, with Ontario and British Columbia leading permissive frameworks. ACH payment rail integration supports cross-border contest participation with US platforms. Toronto concentrates compliance architecture engineering for multi-jurisdiction operators.
United Kingdom
Gambling Commission oversight requires skill-game certification for real-money contest formats, creating compliance entry barriers. GDPR mandates shape data retention policies for player performance analytics. London clusters fantasy sports technology vendors serving European operator licensing requirements.
Fantasy Sports Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct strategic tiers. Daily fantasy specialists with proprietary scoring algorithms occupy the premium revenue segment. Legacy media platforms leverage broadcast rights integration for cross-promotional contest acquisition. Emerging mobile-native operators exploit social graph virality in underpenetrated geographies. Dominant competitive moves include state-by-state lobbying resource concentration and adjacent real-money gaming vertical expansion into poker and rummy modules.
Within the daily fantasy specialist tier, DraftKings and FanDuel exemplify algorithmic contest generation and geographic dominance in state-regulated US markets respectively. Yahoo Fantasy Sports occupies a position spanning hybrid platform architecture across web and mobile ecosystems. These three operators represent divergent strategic archetypes: proprietary technology licensing, regulatory-first market entry sequencing, and cross-platform user experience synchronization.
| Leading Market Players |
|---|
| DraftKings |
| FanDuel |
| Yahoo Fantasy Sports |
| ESPN Fantasy Sports |
| CBS Sports Fantasy |
| Dream Sports |
| FantasyPros |
| Sleeper |
| PrizePicks |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific data center freight corridors connecting Mumbai to Singapore and São Paulo to Miami shape platform operating economics, compressing margins for daily fantasy operators while enabling tiered service pricing based on latency performance. Cloud compute concentration in these corridors forces platforms to absorb bandwidth costs or pass them downstream through subscription tiering.
Pricing Analysis
Latency-generation pricing gaps separate sub-second scoring platforms from legacy batch-processing alternatives and emerging blockchain-verified contest formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by real-time data feed quality and AI lineup tool access. Pricing pressure stems from AWS and Azure compute cost volatility in high-frequency daily fantasy processing. Casual participants in the 18-24 bracket exhibit highest price sensitivity, while high-volume daily fantasy users in the 25-34 cohort accept premium subscription rates for reduced latency.
Supply Chain Analysis
Tariff exposure between US and Chinese semiconductor equipment constrains server farm expansion timelines for fantasy sports infrastructure. Supply concentrates in Taiwan for advanced chip fabrication, India for software engineering talent, and Ireland for EU data residency compliance. Raw material dependencies span cobalt for server cooling systems, rare earth elements for magnetic storage, and optical fiber for transoceanic latency optimization. Single-source vulnerability in Taiwan semiconductor foundries threatens sub-second scoring architecture deployment. Distribution runs through hyperscaler marketplaces and direct enterprise licensing to platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fantasy sports sits in early-cycle expansion as mobile-first penetration among 25-34 demographics in India and Brazil outpaces legacy market saturation patterns. Regulatory clarity in skill-game classification accelerates addressable market boundary expansion faster than historical gaming verticals.
For Market Incumbents: Entrench proprietary scoring algorithm moats through exclusive data partnerships with official league sources. Consolidate lobbying resources in pending state legislation jurisdictions to preempt sports betting substitution threats. Deepen vertical integration into real-money gaming adjacencies like rummy and poker modules to extend platform lifetime value beyond seasonal sports calendars.
For New Entrants and Emerging Players: Brazil's regulatory consultation phase offers white-space entry before federal licensing frameworks crystallize. Target social contest formats via WhatsApp and Telegram integrations to compress viral acquisition cycles below incumbent email-based benchmarks. Pursue freemium monetization architectures to capture price-sensitive 18-24 participants without full paywall exclusion.
For Investors and Strategic Acquirers: Mobile-native operators with PIX and UPI payment rail integration anchor the preferred acquisition archetype for emerging market exposure. Long-term viability hinges on regulatory classification durability across Indian state jurisdictions and US gambling commission rulings. Monitor TRAI guideline revisions and state-level real-money gaming restrictions as early inflection signals for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Lineup Optimizer Development | Sub-second latency tools capture 25-34 demographic engagement minutes from legacy research workflows. |
| Blockchain Scoring Verification | Immutable contest records address integrity concerns in high-stakes entry pools across daily fantasy formats. |
| Adjacent Gaming Vertical Expansion | Rummy and poker modules extend platform lifetime value beyond seasonal sports calendars in Indian markets. |
| Social Platform Integration | WhatsApp and Telegram embedding compresses viral acquisition cycles from days to hours in Brazil and India. |
| Regulatory Compliance Architecture | Modular ZIP-code toggling enables simultaneous operation across divergent US state gambling commission rulings. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of platform operator disclosures, league partnership announcements, and gambling commission docket filings. Primary interviews engaged product development executives at daily fantasy operators, regulatory affairs leads navigating multi-jurisdiction compliance, payment rail integration specialists, and cloud infrastructure procurement managers. Secondary validation drew from TRAI consultation papers, state gaming authority rulings, SEC filings by listed operators, and hyperscaler capex disclosures. Bottom-up user segmentation models triangulated against top-down market sizing from official league viewership data.
Forecast inputs span platform type adoption curves, contest format participation rates, and monetization model conversion funnels across the projection horizon. Segmentation dimensions modeled include platform architecture, game type cycle duration, participation model tiering, and age cohort engagement patterns. CAGRs derived from historical participation velocity in comparable digital gaming verticals adjusted for regulatory inflection timing. Industry-specific inputs incorporate smartphone penetration trajectories, payment rail adoption curves, and state-by-state regulatory classification shifts.
Practitioners should monitor cloud compute pricing volatility, Indian state gaming authority reclassifications, and US sports betting legalization expansion for early signals of forecast revision. Assumptions reflect current regulatory frameworks and technology adoption curves without anticipating disruptive platform innovations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Analytics
India Fantasy Sports Market
Sports Analytics
North America Fantasy Sports Market
Sports Analytics
Sports Analytics Solutions Market
Sports Analytics
Europe Sports Analytics Market
Sports Analytics
Asia-Pacific Sports Analytics Market
Sports Analytics
Player Tracking System Market
Sports Analytics
Middle East and Africa Sports Analytics Market
Sports Analytics
Global Player Tracking Market
Sports Analytics
Daily Fantasy Sports Market
Sports Analytics
Sports Analytics Market
Sports Analytics
Youth Sports Software Market