
 Creatine Supplements Market | 2026-2036
Creatine Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Creatine Supplements Market Analytics
E-commerce platforms is rewriting how creatine reaches end consumers, bypassing traditional brick-and-mortar intermediaries that once controlled shelf placement and pricing. Glanbia PLC leverages its vertically integrated dairy-to-supplement supply chain to secure raw material cost advantages. NutraBio anchors its market position through third-party tested, fully disclosed formulations that appeal to ingredient-conscious buyers. MuscleTech competes through aggressive sports marketing partnerships with collegiate athletic programs.
Creatine supplements are nitrogenous organic compounds, primarily creatine monohydrate, synthesized from sarcosine and cyanamide through a two-step chemical reaction yielding 99.9% purity crystalline powder for adenosine triphosphate regeneration in skeletal muscle. Powder formulations dominate volume shipments due to lower per-serving cost and flexible dosing, though capsules capture higher margins among traveling professionals and military personnel seeking portability. Athletes and bodybuilders represent the core demand pool, while casual users represent the fastest-expanding segment as gym membership penetration broadens beyond competitive sports into general wellness routines.
FDA Current Good Manufacturing Practice regulations and NSF Certified for Sport standards govern product quality, with non-compliant batches facing import detention at U.S. ports of entry. EFSA novel food assessments and FSSAI licensing requirements create parallel compliance obligations for European and Indian market access respectively. Stakeholders must monitor evolving banned-substance lists from WADA and national anti-doping agencies, as cross-contamination liabilities can trigger irreversible brand damage and distribution suspensions.
Market Dynamics
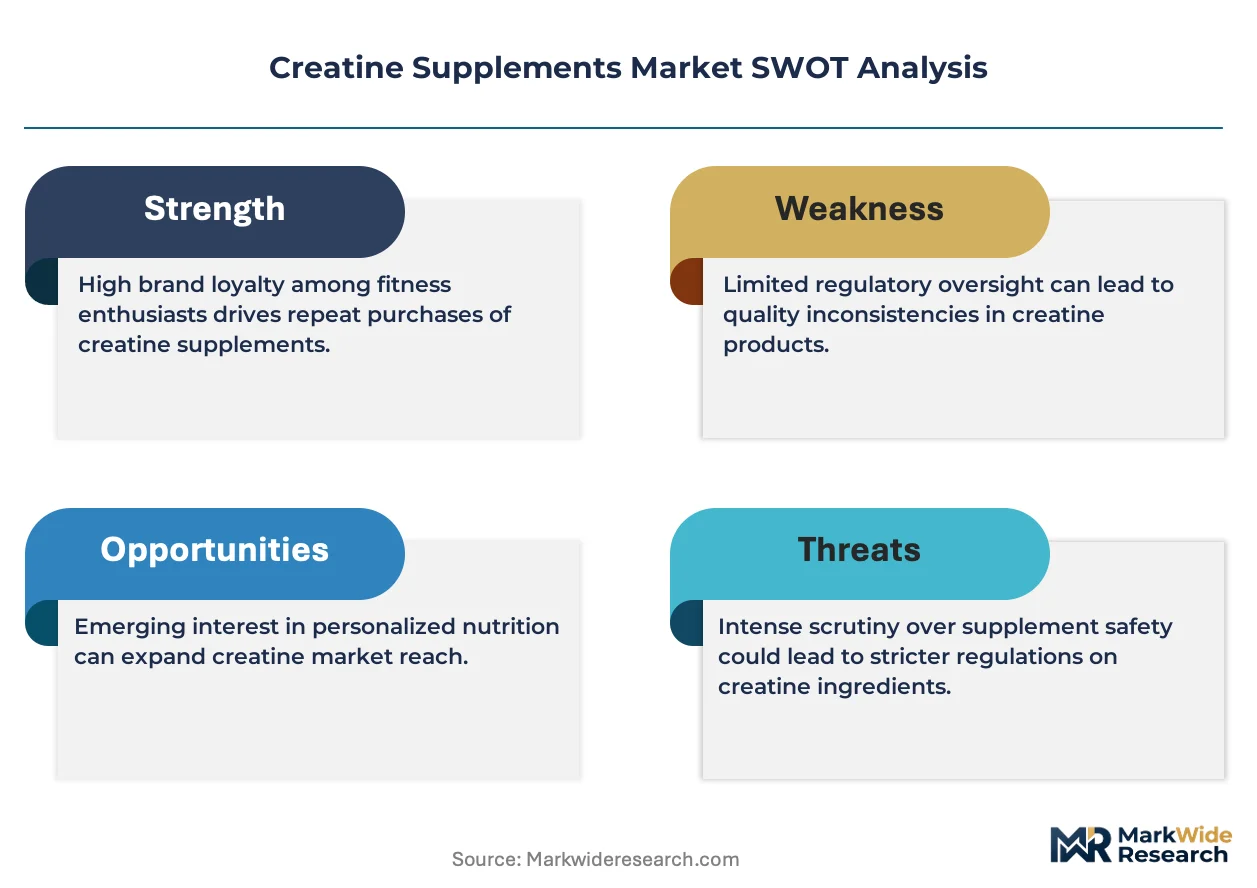
Certification requirements from FDA and NSF International are compressing margins for uncertified suppliers while concentrating procurement among pharmaceutical-grade compounders in Germany and the United States. This regulatory tightening is reshaping competitive positioning toward vertically integrated producers with captive laboratory testing infrastructure.
Growth Catalysts
- NSF Certified for Sport procurement mandates:Collegiate athletic programs and Olympic training centers now require third-party verified batches, eliminating spot-market sourcing and locking in multi-year supply agreements with certified compounders.
- Germany:Bundesliga club nutrition programs and Olympic training centers source pharmaceutical-grade creatine monohydrate directly from domestic manufacturers, creating a high-barrier reference market for purity standards.
- Micronization technology:Advanced particle-size reduction processes improve dissolution rates and bioavailability, commanding premium positioning in performance-focused segments.
Market Restraints
- Raw material concentration:Sarcosine and cyanamide feedstock production clusters in Chinese chemical manufacturing zones, exposing supply chains to import detention risks and tariff volatility.
- FDA Current Good Manufacturing Practice compliance costs:Small-batch importers face capital-intensive facility upgrades or exit from the U.S. market entirely.
- Plant-based protein alternatives:Pea and rice protein formulations with added ergogenic compounds capture wellness-oriented consumers outside competitive athletics.
Strategic Opportunities
- India:FSSAI licensing requirements are stabilizing, enabling compliant entrants to capture gym membership growth in tier-2 and tier-3 cities before domestic compounders scale.
- Military and tactical nutrition:Portable capsule formats address Department of Defense procurement for field-deployed personnel, a segment with price-inelastic demand and long contract cycles.
- E-commerce direct-to-consumer channels:Subscription models bypass brick-and-margin retail intermediaries, capturing recurring revenue and consumer data for formulation refinement.
Industry Challenges
- Analytical chemistry talent scarcity:HPLC and mass spectrometry expertise for banned-substance screening commands premium wages, constraining quality control scaling for mid-tier manufacturers.
- WADA cross-contamination liability:Single-batch failures trigger distribution suspensions and irreversible brand damage, requiring redundant testing protocols that extend production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatine Supplements Market |
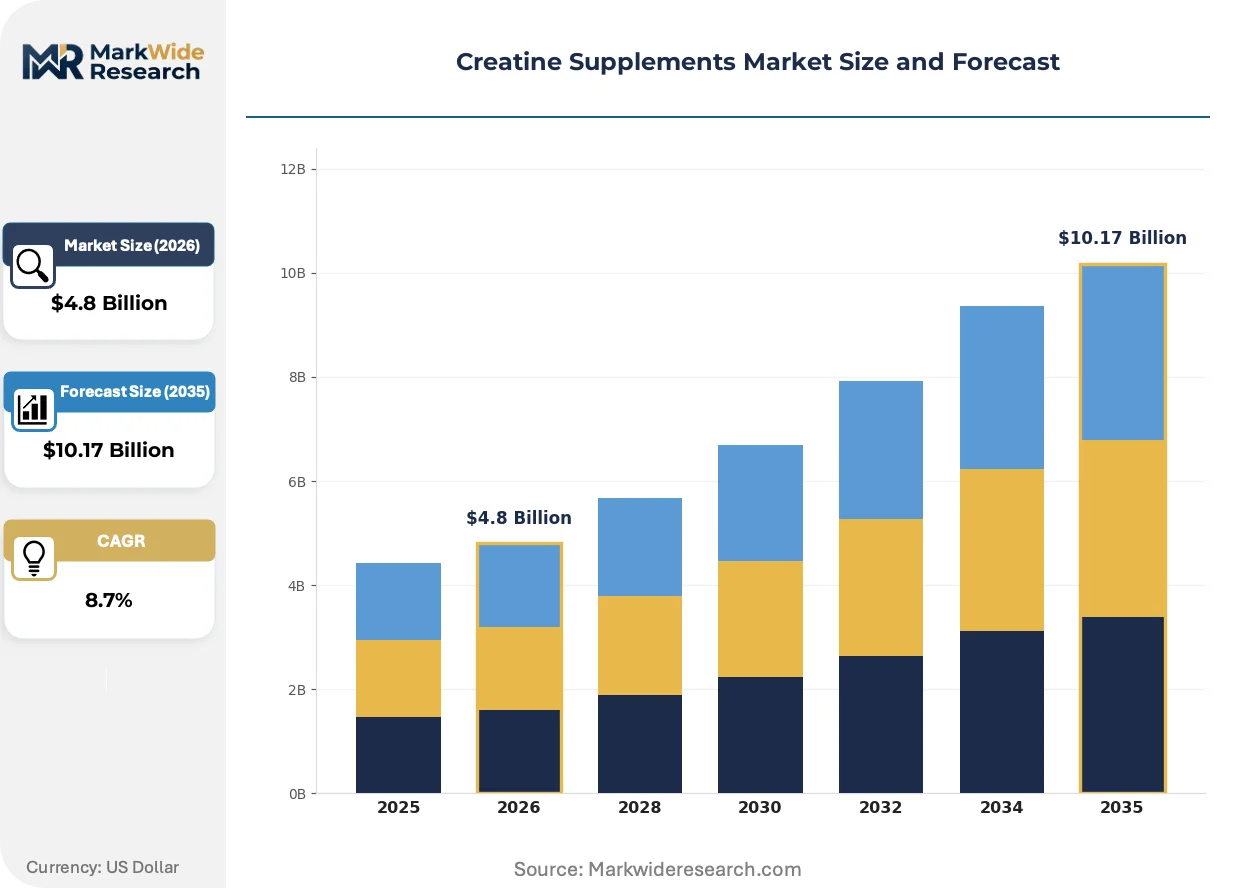
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creatine Monohydrate, Creatine HCL, Kre-Alkalyn, Buffered Creatine Form: Powder, Capsules, Chewables, Liquids End User: Athletes, Bodybuilders, Fitness Enthusiasts, Casual Users Distribution Channel: Online Retail, Specialty Stores, Gyms, Pharmacies |
| Companies Covered | Glanbia PLC, GNC Holdings, NutraBio, Weider Global Nutrition, Ajinomoto Co Inc, Allmax Nutrition, MuscleTech, Thorne, Nutrex Research, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatine Supplements Market Evolving Landscape
Formulation science and verification protocols are diverging sharply between performance-grade and wellness-grade positioning, with technology investments clustering around purity demonstration rather than novel delivery mechanisms.
Micronized creatine monohydrate with sub-200-micron particle distribution is collapsing the absorption-rate advantage previously held by liquid and esterified alternatives. Elite track-and-field programs and powerlifting federations have adopted these specifications as procurement baselines, forcing legacy manufacturers to retool milling equipment or surrender premium positioning. The technology is collapsing R&D investment into particle engineering rather than molecular modification.
EFSA novel food assessments are tightening evidentiary requirements for non-monohydrate creatine salts and derivatives, extending approval timelines for European market entry. Manufacturers with existing monohydrate dossiers gain defensive moats as newer formats face toxicology study mandates. Sports nutrition brands with pan-European distribution are consolidating formulations around approved monohydrate SKUs to avoid market fragmentation.
Ingredient-conscious buyers now demand fully disclosed Certificates of Analysis with batch-specific heavy metal and microbial testing, displacing proprietary blend marketing. This specification compression favors vertically integrated compounders with in-house laboratory infrastructure over contract manufacturers reliant on external testing. The shift is most visible in United States direct-to-consumer channels where subscription services compete on transparency metrics.
Creatine Supplements Market Segmentation
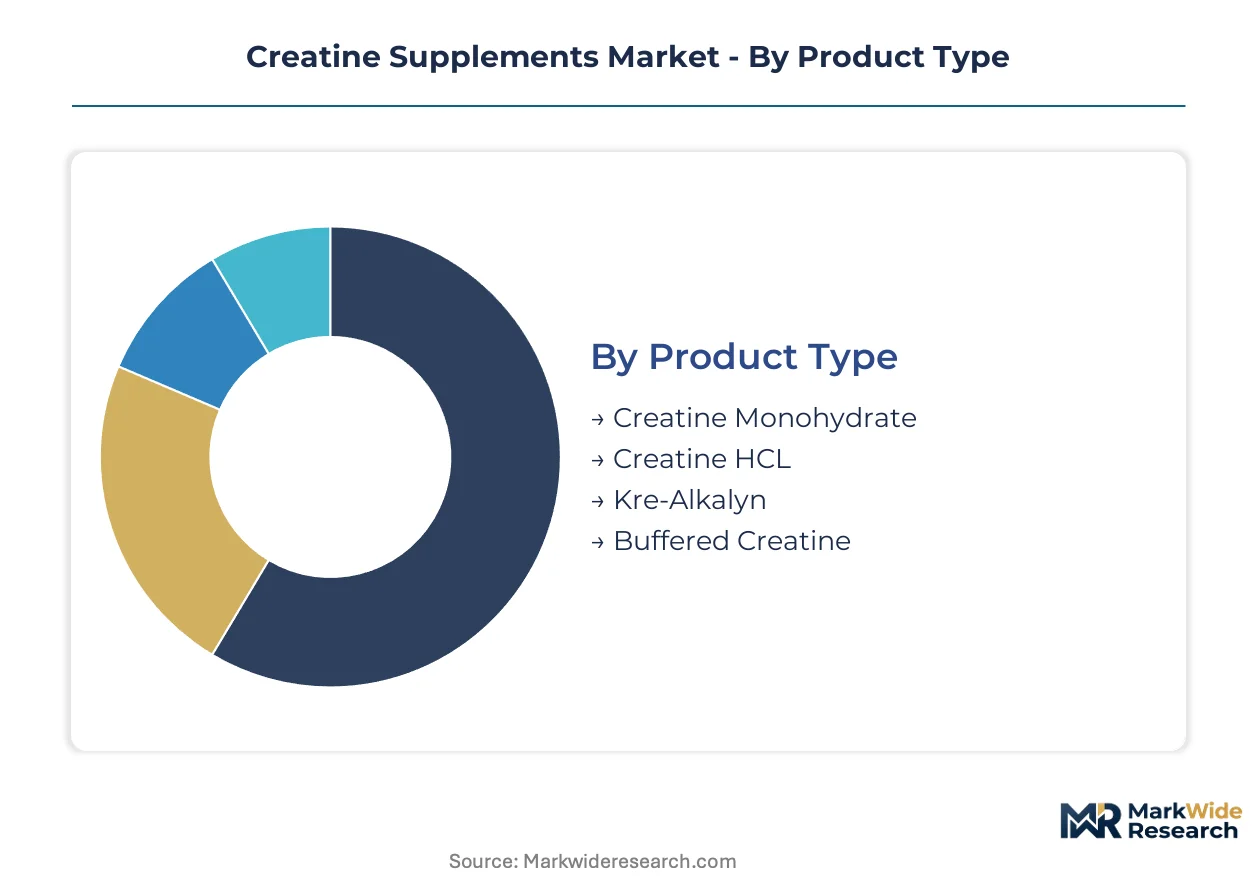
Creatine market segmentation reveals divergent margin profiles and inventory velocities across formulation types and buyer categories. Pharmaceutical-grade compounders optimize production runs around certification cycles, while direct-to-consumer channels compress replenishment intervals through subscription mechanics.
Product Type:
Cycle times vary from continuous bulk production for established formats to batch-limited runs for patented derivatives awaiting regulatory dossier completion.
- Creatine Monohydrate:99.9% purity crystalline powder synthesized from sarcosine and cyanamide serves as the ATP regeneration standard for skeletal muscle. German Olympic training centers and Bundesliga club nutrition programs source pharmaceutical-grade batches directly from domestic compounders, locking in multi-year supply agreements under NSF Certified for Sport mandates.
- Creatine HCL:Hydrochloride salt form achieves higher aqueous solubility at lower doses, appealing to athletes with gastrointestinal sensitivity to monohydrate loading protocols. EFSA novel food assessments have stalled European market entry for non-monohydrate salts, concentrating demand in North American specialty retail channels where FDA enforcement focuses on GMP compliance rather than novel substance barriers.
- Kre-Alkalyn:pH-buffered formulation marketed for reduced conversion to creatinine in acidic environments.
- Buffered Creatine:Alkaline-modified compound targeting stomach-acid resistance claims.
Creatine monohydrate anchors the volume base while creatine HCL gains share at the steepest rate.
Form:
Cost tiers separate commodity powder from convenience-positioned delivery systems with 3-4x per-serving premiums.
- Powder:Loose crystalline format dominates bulk procurement for institutional buyers and price-sensitive consumers. Lower per-serving economics and flexible dosing protocols sustain volume leadership across gym membership expansion in tier-2 Indian cities and European training facilities.
- Capsules:Pre-measured gelatin or vegetable cellulose shells command portability premiums among traveling professionals and military personnel. Department of Defense tactical nutrition contracts specify capsule formats for field-deployed units, creating price-inelastic demand pools with 12-24 month procurement cycles.
- Chewables:Flavored compressed tablets targeting entry-level users averse to mixing protocols.
- Liquids:Ready-to-drink suspensions with stability challenges limiting shelf life and distribution radius.
Powder formulations carry the volume base while capsules expand most quickly in contracted institutional channels.
End User:
Application intensity separates competitive-performance dosing protocols from wellness-oriented maintenance regimens.
- Athletes:Collegiate, Olympic, and professional competitors operating under WADA-monitored anti-doping frameworks. NSF Certified for Sport procurement mandates have eliminated spot-market sourcing, forcing athletic programs into verified supply chains with batch-specific Certificates of Analysis.
- Bodybuilders:Resistance-training specialists pursuing hypertrophy through systematic loading and maintenance phases. This segment drove early micronization adoption and now specifies sub-200-micron particle distribution as a procurement baseline, pressuring legacy manufacturers toward milling equipment retooling.
- Fitness Enthusiasts:Regular gym attendees without competitive aspirations or structured periodization.
- Casual Users:General wellness consumers incorporating creatine into broad supplement stacks.
Bodybuilders anchor the volume base while casual users climb the fastest as gym membership penetration broadens beyond competitive sports.
Distribution Channel:
Customer type fragmentation separates data-rich subscription operators from margin-compressed wholesale intermediaries.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators bypass brick-and-mortar intermediaries. Subscription models capture recurring revenue streams and granular consumption data for formulation refinement, with transparency metrics displacing proprietary blend marketing in United States channels.
- Specialty Stores:Dedicated sports nutrition retailers with educated staff and sampling programs. These outlets concentrate in German metropolitan clusters and North American fitness corridors, serving as certification gatekeepers through visible NSF and Informed Sport shelf labeling.
- Gyms:On-site pro shops and vending integration at point-of-exercise.
- Pharmacies:Licensed drug retailers with healthcare professional endorsement leverage.
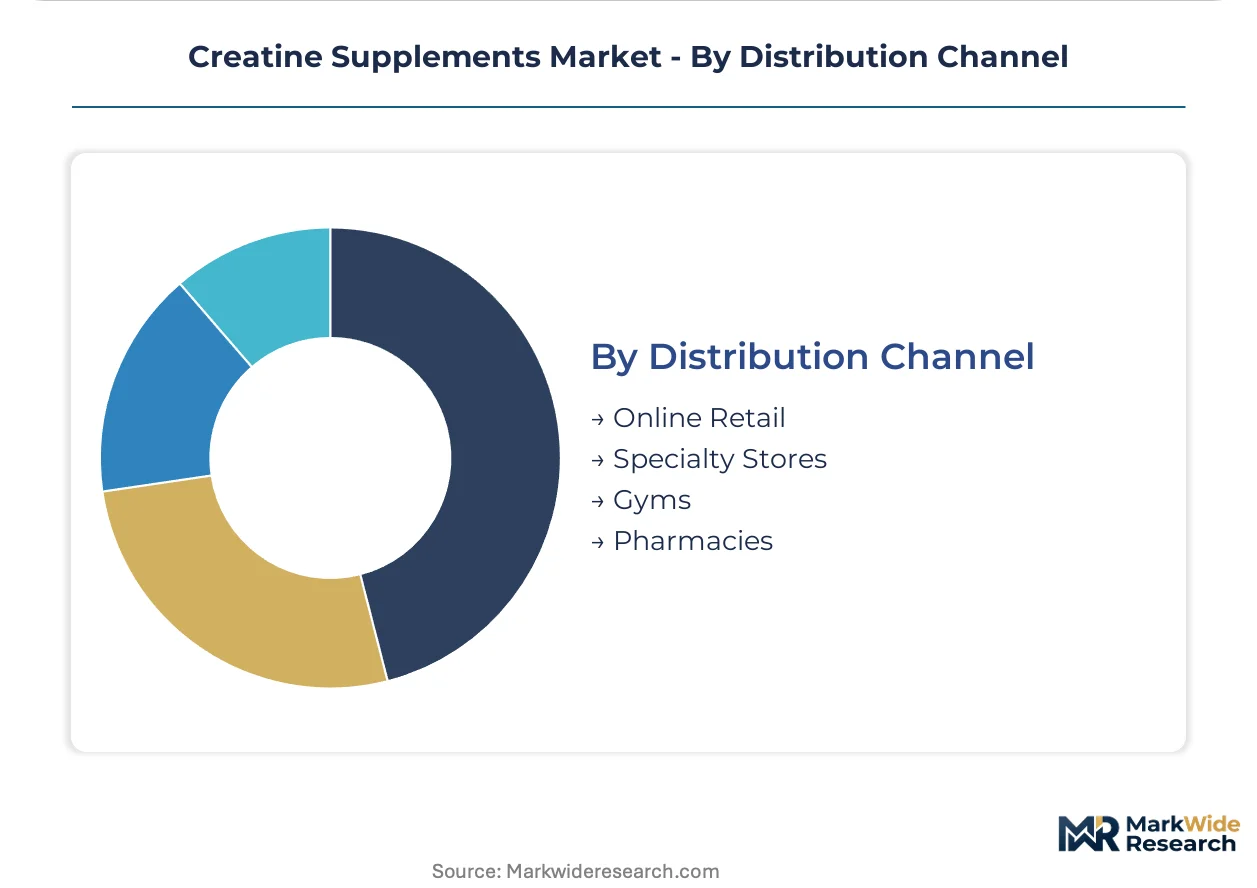
Online retail anchors the volume base while gyms gain share fastest through impulse purchase integration and trainer recommendation networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany sits at a premium to spot-market sourcing in China, reflecting the gap between pharmaceutical-grade certification and uncertified feedstock procurement. This asymmetry concentrates high-margin supply agreements with Olympic training centers and Bundesliga clubs in German manufacturing clusters. Regulatory divergence between FDA enforcement in the United States and EFSA novel food barriers in Europe fragments market access strategies across Atlantic markets.
United States
NSF Certified for Sport mandates from collegiate athletic programs and Olympic training centers have eliminated spot-market sourcing for competitive athletes. FDA Current Good Manufacturing Practice regulations govern facility compliance, with non-certified batches facing import detention at ports of entry. California and Texas host the densest concentrations of direct-to-consumer subscription operators competing on transparency metrics.
Germany
Bundesliga club nutrition programs and Olympic training centers source pharmaceutical-grade creatine monohydrate directly from domestic compounders, locking in multi-year supply agreements. EFSA novel food assessments create barriers for non-monohydrate salts while reinforcing existing monohydrate dossiers. The Rhine-Ruhr industrial corridor anchors pharmaceutical-grade production infrastructure with captive laboratory testing capabilities.
India
Gym membership expansion in tier-2 and tier-3 cities drives powder formulation demand among fitness enthusiasts and casual users entering the category. FSSAI licensing requirements are stabilizing, enabling compliant entrants to establish market positions before domestic compounders achieve scale. Maharashtra and Karnataka concentrate e-commerce fulfillment infrastructure serving direct-to-consumer channels.
China
Sarcosine and cyanamide feedstock production clusters in eastern chemical manufacturing zones expose supply chains to tariff volatility and import detention risks at destination markets. The national pharmaceutical regulator enforces export documentation standards for raw material shipments. Zhejiang and Jiangsu provinces host the primary synthesis facilities serving international compounders.
Japan
METI standards for health food manufacturing create compliance thresholds for imported finished goods, favoring domestic formulation and packaging operations. Aging demographics expand wellness-oriented demand beyond competitive athletics into general consumer segments. The Kanto region around Tokyo concentrates specialty retail channels with visible certification labeling requirements.
Creatine Supplements Market Competitive Landscape
Vertically integrated dairy-to-supplement operators and transparency-positioned direct-to-consumer specialists split the market between cost-advantaged raw material control and certification-premium positioning. The vendor base concentrates around compounders with captive laboratory infrastructure and brands with subscription-based recurring revenue models. Three archetypes dominate: pharmaceutical-grade manufacturers with Olympic procurement contracts, vertically integrated nutrition conglomerates with backward raw material control, and transparency-focused digital-native brands with batch-disclosure marketing. Competitive moves cluster around milling equipment retooling for micronization specifications and multi-year supply agreement lock-ins with certified athletic programs.
Within the vertically integrated tier, Glanbia PLC leverages dairy-to-supplement supply chain control to secure raw material cost positions. NutraBio occupies a position exemplifying the transparency-focused archetype through third-party tested, fully disclosed formulations that appeal to ingredient-conscious buyers in United States direct-to-consumer channels. MuscleTech represents sports marketing-driven positioning with partnerships anchoring visibility in collegiate athletic procurement networks. These three companies illustrate the strategic divergence between cost control, certification transparency, and marketing investment as competitive vectors.
| Leading Market Players |
|---|
| Glanbia PLC |
| GNC Holdings |
| NutraBio |
| Weider Global Nutrition |
| Ajinomoto Co Inc |
| Allmax Nutrition |
| MuscleTech |
| Thorne |
| Nutrex Research, Inc. |
| Others |
Value Network & Pricing Analysis
Rhine-Ruhr freight corridors connect German pharmaceutical-grade compounders to Olympic training centers and Bundesliga clubs, with logistics cost advantages reinforcing procurement concentration among certified suppliers while spot-market Chinese feedstock faces tariff-adjusted price penalties at destination ports.
Pricing Analysis
Configured-to-order pricing for NSF Certified for Sport batches commands substantial premiums over standard uncertified powder, with certification grade and volume scale as the primary differentiation drivers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels is compressing as FDA import detention risks eliminate the lowest tier from US channels. Pricing pressure stems from micronization equipment capital requirements pressuring mid-tier manufacturers. Casual users in Indian tier-2 cities exhibit highest price sensitivity; military tactical nutrition contracts show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from German compounders to domestic sarcosine suppliers stabilize upstream cash flows against Chinese feedstock volatility. Manufacturing concentrates in Germany, China, and the United States. Sarcosine, cyanamide, and gelatin capsule shells constitute critical input dependencies. Single-source vulnerability runs through Zhejiang and Jiangsu chemical zones. Distribution runs through direct-to-consumer subscription platforms and institutional procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micronization technology adoption represents a high-growth disruption as sub-200-micron specifications collapse absorption-rate advantages of liquid alternatives, with NSF certification mandates accelerating procurement consolidation.
For Market Incumbents: Harden quality control infrastructure through captive HPLC and mass spectrometry laboratory investment to neutralize WADA cross-contamination liability threats. Lock in multi-year supply agreements with collegiate athletic programs before domestic compounders in India achieve certification scale. Certification transparency serves as the defensive moat against transparency-focused digital-native entrants. For New Entrants and Emerging Players: Build out FSSAI-compliant production capacity in Maharashtra and Karnataka to capture gym membership expansion in Indian tier-2 and tier-3 cities before incumbent domestic compounders scale. Military and tactical nutrition capsule contracts offer the most penetrable institutional channel with price-inelastic demand and 12-24 month procurement cycles. Subscription-based direct-to-consumer transparency marketing provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Pharmaceutical-grade manufacturers with existing NSF Certified for Sport dossiers and Olympic procurement relationships represent the priority acquisition archetype for long-term viability across the 5-10 year window. The signal to watch is FDA enforcement intensity at ports of entry, which would accelerate margin compression for uncertified importers and concentrate value in vertically integrated certified compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Micronization Equipment Retooling | Sub-200-micron particle distribution meets elite track-and-field procurement baselines. |
| NSF Certified for Sport Dossier Completion | Third-party verification unlocks collegiate athletic program multi-year supply agreements. |
| Backward Integration into Sarcosine Synthesis | In-house production of feedstock insulates against Chinese import detention risks. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture and consumption data refinement displace brick-and-mortar intermediaries. |
| Military Nutrition Contract Pursuit | Department of Defense procurement specifications create price-inelastic demand pools. |
Research Methodology
The analysis maps creatine monohydrate, creatine HCL, Kre-Alkalyn, and buffered creatine segments, each validated through sports nutrition formulators, pharmaceutical compounders, collegiate athletic procurement officers, and e-commerce subscription operators. Primary interviews with these stakeholders combined with secondary validation against FDA warning letters, NSF Certified for Sport product listings, EFSA novel food assessment registers, and FSSAI licensing databases. Bottom-up volume triangulation against top-down value estimation anchored the market sizing.
Assumption sets held regulatory enforcement intensity and certification timeline constants while varying gym membership penetration rates and micronization adoption curves across the projection horizon. Segmentation dimensions modeled include product type, formulation form, end-user intensity, and distribution channel structure. CAGRs derived from historical volume trajectories and elasticity-adjusted price evolution. Industry-specific forecast inputs incorporated WADA banned-substance list updates and military nutrition contract award cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native transparency-focused brands or state-backed Chinese compounders would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Middle East Sports Drinks Market
Sports Nutrition
North America Sports Drink Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Sports Hydration Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
Global Sexual Enhancement Supplements Market
Sports Nutrition
Protein Supplements Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
Pre-Workout Supplements Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Active Nutrition Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Sports Nutrition Ingredients Market
Sports Nutrition
Middle East and Africa Sports Nutrition Market