
 Smart Planting Agriculture Market | 2026-2036
Smart Planting Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Planting Agriculture Market Insights
ISO 12100 machinery safety certification is rotating competitive access in precision planting equipment, forcing smaller OEMs toward costly redesign cycles. Deere & Company leverages its captive telematics infrastructure to lock in fleet renewal schedules across North American corn belts. AGCO Corporation anchors its position through Fendt's integrated seeding-tool control architecture. Trimble Inc. competes as an open-ecosystem alternative, selling correction services and display hardware across mixed-fleet operations.
Smart planting agriculture encompasses sensor-guided seed placement, real-time soil condition mapping, and automated depth-pressure control to optimize germination uniformity and plant population. Systems typically integrate GNSS correction to sub-inch accuracy with hydraulic downforce modulation ranging from 50 to 400 pounds per row unit, serving the core commercial purpose of reducing seed waste while maximizing yield per acre. Precision farming tools currently dominate hardware revenue as retrofit demand outpaces new equipment sales, while AI analytics represents the fastest-expanding margin pool as subscription models displace perpetual software licenses. IoT solutions remain the most mature technology layer, though autonomous equipment is displacing operator-dependent systems in high-acreage operations.
The EPA regulates precision agriculture equipment emissions under Tier 4 Final standards, while the EU Green Deal's carbon-border adjustments are reshaping import compliance for planting machinery sold into European markets. FDA oversight of gene-edited seeds intersects with smart planting when seed treatment data must trace through digital farm management platforms. Stakeholders must monitor whether soil-data ownership frameworks crystallize ahead of platform consolidation, as that sequence will determine who captures recurring revenue from planting prescription algorithms.
Market Dynamics
Variable-rate planting technology is compressing equipment replacement cycles as Brazil's Cerrado soybean belt retrofits existing fleets with sensor-guided seed placement systems, forcing capital allocation toward precision hardware over conventional machinery.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Sustainability compliance mandates for input-intensive planting systems are accelerating adoption of soil-mapping and seed-treatment traceability tools across European row-crop operations.
- Large-scale row-crop operations:Precision seeding adoption concentrates among commercial farms exceeding 5,000 hectares, where sub-inch GNSS accuracy delivers measurable yield-per-acre improvements.
- Telematics infrastructure lock-in:Captive fleet data platforms are creating renewal dependencies that shorten replacement intervals for planting equipment in North American corn belts.
Market Restraints
- Hydraulic component supply concentration:Downforce modulation systems rely on specialized valve suppliers concentrated in German industrial clusters, exposing OEMs to extended lead times.
- ISO 12100 machinery safety certification:Rotating compliance requirements force smaller equipment manufacturers into costly redesign cycles that delay product launches.
- Operator-dependent system substitution:Autonomous planting platforms threaten residual value of conventional tractor-seeder combinations in high-acreage operations.
Strategic Opportunities
- AI analytics subscription models:Recurring revenue from planting prescription algorithms represents the fastest-expanding margin pool as perpetual software licenses lose favor.
- India's precision agriculture penetration:Variable-rate technology remains underdeployed in Punjab and Haryana wheat-rice systems, creating retrofit demand among cooperative farming structures.
- Soil-data ownership frameworks:Platform consolidation timing will determine which stakeholders capture long-term value from agronomic data monetization.
Industry Challenges
- Mechatronics technician scarcity:Integration of hydraulic downforce modulation with GNSS correction requires specialized field service capabilities that outpace vocational training pipelines.
- Mixed-fleet interoperability:Open-ecosystem display hardware must reconcile proprietary telematics protocols from established equipment manufacturers, complicating retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Planting Agriculture Market |
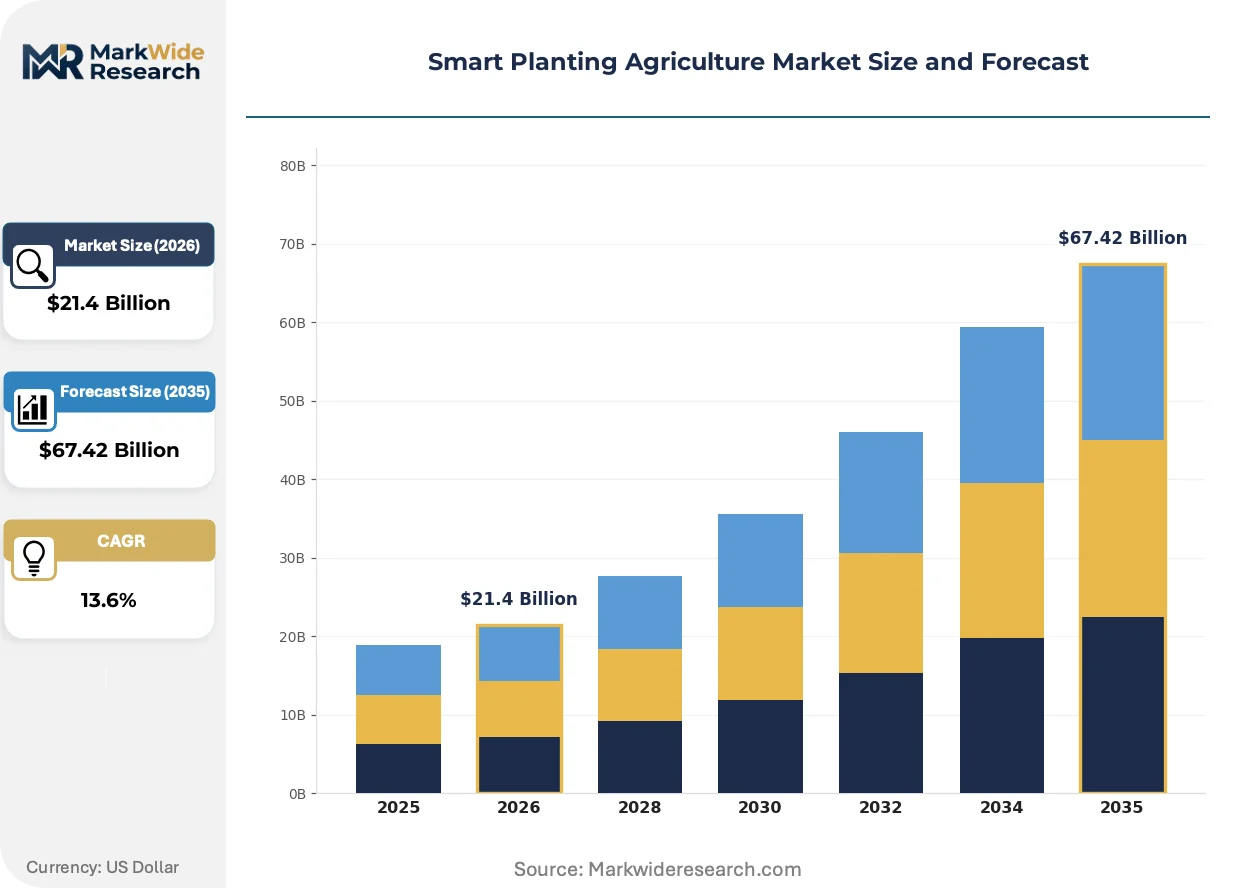
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $67.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Technology, Precision Farming Tools, Soil Sensors, Drones Application: Crop Monitoring, Irrigation Management, Yield Optimization, Pest Control End User: Farmers, Agricultural Cooperatives, Research Institutions, Agro-Companies Technology: IoT Solutions, AI Analytics, Software Platforms, Autonomous Equipment |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial, Topcon, John Deere & Company, Kubota, CLAAS Group, Farmers Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Planting Agriculture Market Trends and Innovations
Autonomous planting systems are actively reshaping competitive positioning in high-acreage agriculture, compressing the viable window for operator-dependent equipment and redistributing value toward sensor-software integration layers.
Electro-hydraulic seed metering is displacing mechanical drive systems in precision planting units. Commercial corn and soybean operations in the US Midwest are adopting these systems at replacement-cycle velocity. This displacement is compressing aftermarket parts revenue for conventional meter components while expanding margin capture for integrated control architecture providers.
The EU AI Act's risk-classification framework for agricultural automation is imposing conformity assessment burdens on autonomous planting equipment sold into European markets. Machinery OEMs must document algorithmic decision transparency for seeding-rate adjustments. High-horsepower tractor manufacturers serving German and French markets face the steepest compliance timeline compression.
Subscription-based agronomic advisory is displacing bundled equipment-and-service packages in North American distribution channels. Dealership networks are unbundling precision farming support from hardware transactions, replacing upfront margin with recurring data-analytics contracts. This shift concentrates most visibly in Iowa and Illinois corn operations where farm management platform penetration exceeds regional averages.
Smart Planting Agriculture Market Segmentation
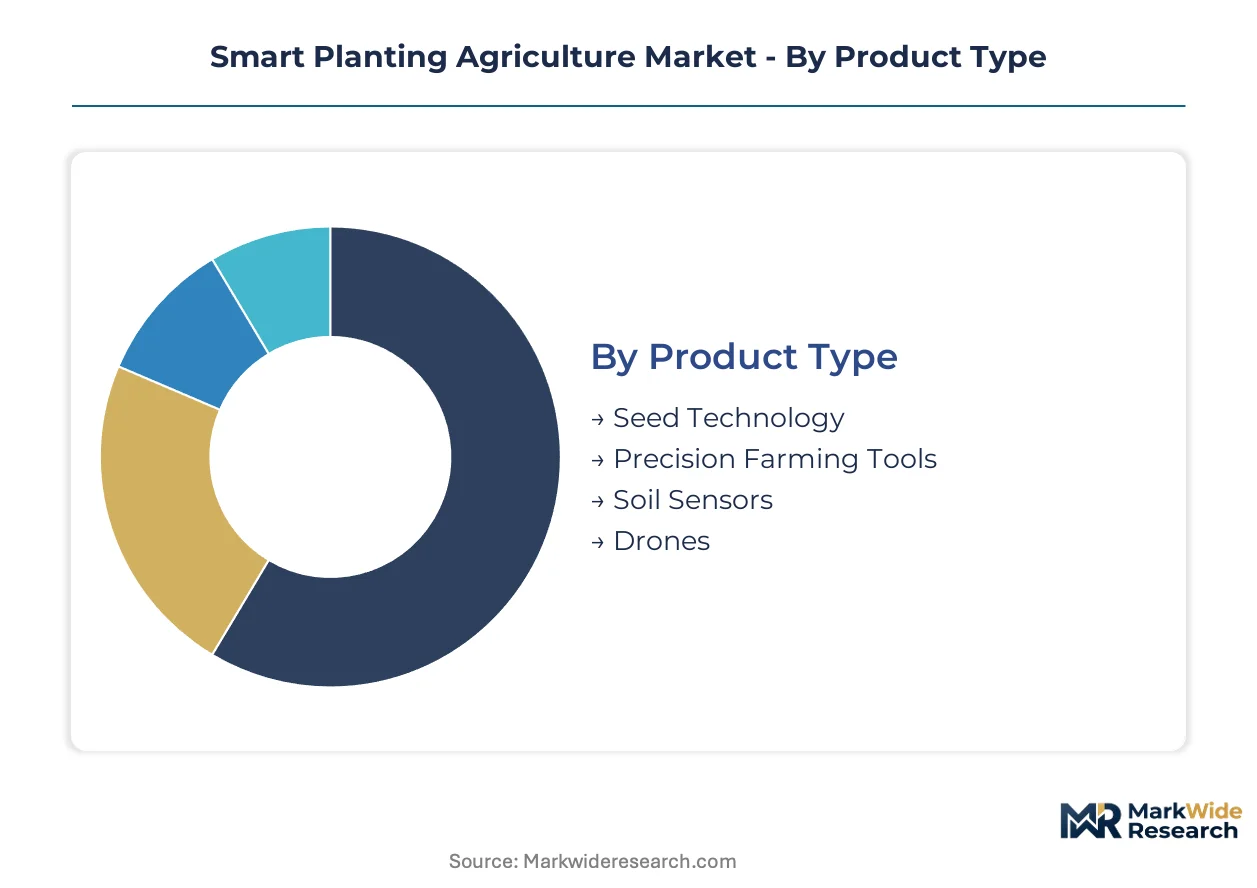
Smart planting agriculture vendors compete across four distinct category boundaries where technology maturity, customer procurement patterns, and margin capture mechanisms diverge sharply. Each segmentation axis reveals different pathways for pricing power and recurring revenue.
Product Type:
Margin pools concentrate in precision farming tools and seed technology, where hardware-software integration creates renewal dependencies and proprietary data lock-in.
- Precision Farming Tools:Variable-rate seeding units with sub-inch GNSS accuracy and hydraulic downforce modulation dominate retrofit demand in Brazil's Cerrado and the US Midwest. Equipment replacement cycles compress as telematics platforms create fleet renewal lock-in.
- Seed Technology:Gene-edited seed portfolios requiring digital treatment traceability through farm management platforms intersect with FDA oversight and EU sustainability compliance mandates. Traceability infrastructure investments concentrate margin capture among integrated providers.
- Soil Sensors:Real-time moisture and nutrient mapping devices anchor prescription algorithm inputs for AI analytics subscriptions.
- Drones:Aerial seeding and field scouting units serve high-acreage operations seeking to reduce operator labor exposure.
The dominant share belongs to Precision Farming Tools, while Seed Technology is closing the gap fastest through traceability-linked recurring revenue models.
Application:
Volume concentration tracks commercial farm size thresholds where sensor infrastructure costs amortize across sufficient acreage.
- Crop Monitoring:Continuous plant population assessment and early-season stand evaluation drive adoption among operations exceeding 5,000 hectares. Sub-inch GNSS accuracy justifies capital allocation through measurable yield-per-acre improvements.
- Yield Optimization:Planting prescription algorithms integrating soil maps, weather data, and seed genetics represent the fastest-expanding margin pool as subscription models displace perpetual software licenses.
- Irrigation Management:Soil-moisture-triggered seed placement adjustments concentrate in water-stressed regions with variable rainfall patterns.
- Pest Control:Seed treatment data traceability requirements under EU Green Deal compliance reshape input-intensive planting system economics.
Crop Monitoring commands the largest installed base, though Yield Optimization is expanding most quickly through recurring analytics contracts.
End User:
Customer procurement sophistication determines pricing architecture complexity and service bundling intensity.
- Farmers:Individual commercial operations in Iowa and Illinois corn belts drive precision farming tool penetration through dealership networks unbundling hardware from data-analytics support.
- Agricultural Cooperatives:Punjab and Haryana wheat-rice cooperative structures in India create retrofit demand for variable-rate technology currently underdeployed in South Asian smallholder aggregation models.
- Agro-Companies:Large-scale row-crop enterprises with captive agronomy teams purchase integrated control architectures directly from OEMs.
- Research Institutions:Field trial infrastructure requirements sustain demand for open-ecosystem display hardware compatible with mixed-fleet research protocols.
Farmers retain the dominant procurement volume, while Agricultural Cooperatives are gaining share fastest through cooperative financing structures.
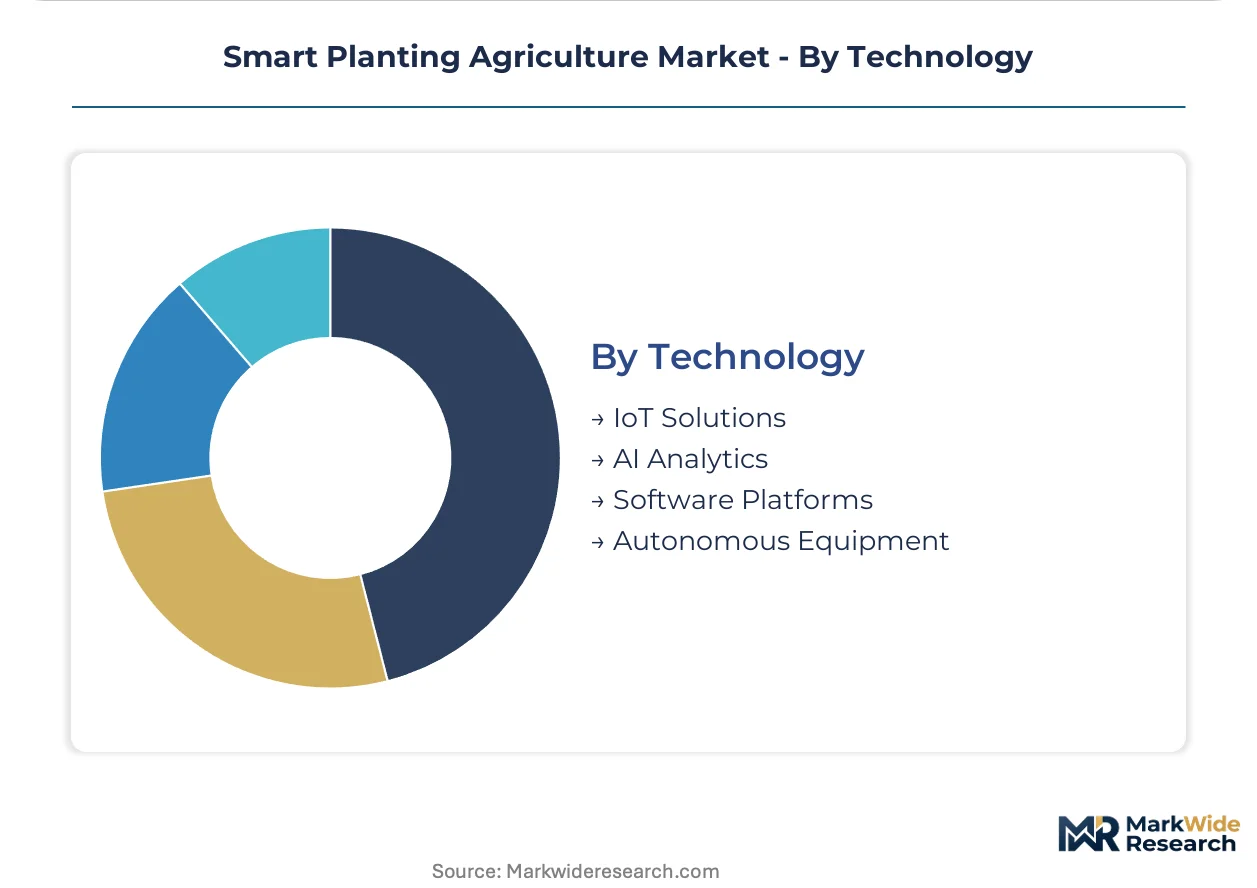
Technology:
Maturity gradients separate established connectivity layers from emerging autonomous platforms threatening residual value in operator-dependent systems.
- IoT Solutions:The most mature technology layer encompassing sensor networks and telematics infrastructure. Captive fleet data platforms create renewal dependencies that shorten replacement intervals.
- Autonomous Equipment:Actively compressing the viable window for conventional tractor-seeder combinations in high-acreage operations. EU AI Act conformity assessment burdens impose algorithmic decision transparency documentation requirements on OEMs serving German and French markets.
- AI Analytics:Planting prescription algorithms monetized through subscription models displace perpetual software licenses in North American distribution channels.
- Software Platforms:Farm management systems integrating seed treatment traceability with regulatory compliance reporting.
IoT Solutions holds the dominant installed base, while Autonomous Equipment is climbing the fastest as labor constraints intensify in high-acreage agriculture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale commercial operations exceeding 5,000 hectares drive procurement concentration in the United States, Brazil, Germany, India, and Australia, where sensor infrastructure costs amortize across sufficient acreage to justify precision hardware investments.
United States
Iowa and Illinois corn belts anchor retrofit demand for variable-rate seeding units through dealership networks unbundling hardware from data-analytics support. EPA Tier 4 Final emissions standards regulate precision agriculture equipment sold into domestic markets. Chicago-based distribution channels concentrate subscription-based agronomic advisory penetration.
Brazil
The Cerrado soybean belt retrofits existing fleets with sensor-guided seed placement systems, compressing equipment replacement cycles toward precision hardware. ANVISA oversight intersects with seed treatment data traceability requirements for export compliance. São Paulo state hosts the densest concentration of mixed-fleet telematics integration services.
Germany
High-horsepower tractor manufacturers serving German row-crop operations face compressed EU AI Act conformity assessment timelines for autonomous planting equipment. The EU Green Deal's Farm to Fork strategy mandates sustainability compliance documentation for input-intensive planting systems. Baden-Württemberg industrial clusters supply specialized hydraulic valve components for downforce modulation systems.
India
Punjab and Haryana wheat-rice cooperative structures generate retrofit demand for variable-rate technology currently underdeployed in South Asian smallholder aggregation models. BIS certification requirements shape import compliance for precision planting machinery. Karnataka's precision agriculture pilot zones test AI-driven prescription algorithms for monsoon-adjusted seed placement.
Australia
Water-stressed broadacre operations in New South Wales and Queensland adopt soil-moisture-triggered seed placement adjustments to optimize germination under variable rainfall patterns. TGA-equivalent agricultural chemical regulations intersect with seed treatment traceability mandates. Melbourne-based research institutions sustain demand for open-ecosystem display hardware compatible with mixed-fleet field trial protocols.
Smart Planting Agriculture Market Competitive Landscape
Player mix skews toward integrated equipment manufacturers with captive telematics infrastructure, creating tiered access barriers around fleet data platforms and hydraulic control architectures. The vendor base separates into three strategic archetypes: full-line OEMs with proprietary seeding-tool integration, open-ecosystem correction service providers, and specialized sensor-software bundlers. Dominant competitive moves include strategic partnerships for mixed-fleet interoperability and backward integration into hydraulic component supply.
Within the integrated OEM tier, Deere & Company and AGCO Corporation exemplify archetypes built around captive fleet data platforms and seeding-tool control architectures. Trimble Inc. occupies a distinct position as an open-ecosystem alternative, selling correction services and display hardware across mixed-fleet operations without proprietary equipment lock-in.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial |
| Topcon |
| John Deere & Company |
| Kubota |
| CLAAS Group |
| Farmers Edge |
| Others |
Pricing and Supply Chain Analysis
ISO 12100 machinery safety certification gates both supplier qualification and price differentiation simultaneously, forcing smaller OEMs into costly redesign cycles that compress margins while tiering market access between certified and non-certified equipment providers.
Pricing Analysis
Cost-plus contracts with steel and hydraulic component indexation dominate precision planting equipment procurement, particularly for large-scale row-crop operations in Brazil and the US Midwest. Three-tier pricing structure across premium, standard, and economy levels separates integrated control architectures from retrofit sensor kits and basic mechanical units. Price differentiation hinges on telematics integration depth and ISO 12100 certification status. Pricing pressure stems from electro-hydraulic seed metering adoption displacing mechanical aftermarket revenue. Cooperative farming structures in India exhibit highest price sensitivity, while North American agro-companies with captive agronomy teams show lowest sensitivity due to yield-per-acre optimization priorities.
Supply Chain Analysis
Baden-Württemberg industrial clusters in Germany function as a chokepoint for specialized hydraulic valve components essential to downforce modulation systems, exposing OEMs to extended lead times when demand surges. Manufacturing concentration spans Germany, the United States, and Brazil for final assembly, with China and Japan supplying GNSS correction modules and sensor arrays. Raw material dependencies center on high-grade steel for frame structures, rare earth elements for precision motors, and semiconductor components for control systems. Single-source vulnerability concentrates in German hydraulic component supply. Distribution runs through dealership networks in North America, direct OEM relationships for large agro-companies, and cooperative financing structures in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are compressing as telematics platforms create fleet renewal dependencies, positioning the market for cyclical recovery driven by Brazil's Cerrado retrofit wave and North American corn belt modernization.
For Market Incumbents: Compound captive telematics infrastructure advantages by deepening backward integration into hydraulic component supply and accelerating EU AI Act conformity documentation for autonomous platforms. Threats from open-ecosystem correction service providers like Trimble intensify margin pressure in display hardware segments. Priority levers include Fendt-style integrated seeding-tool control architecture investments and channel control through unbundled subscription advisory services. For New Entrants and Emerging Players: AI analytics subscription gaps in India's cooperative farming structures offer white-space entry points where variable-rate technology remains underdeployed. Punjab and Haryana wheat-rice systems represent the most penetrable geography due to financing-friendly cooperative models. Go-to-market angles should emphasize open-ecosystem interoperability with mixed-fleet operations and monsoon-adjusted prescription algorithm localization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI analytics sub-segments as software margins displace hardware-heavy equipment finance. Long-term viability over the coming decade favors platform consolidators capturing soil-data ownership frameworks ahead of algorithm monetization crystallization. Acquisition targets include specialized sensor-software bundlers with traceability-linked recurring revenue models. Signal to watch: EU carbon-border adjustment enforcement timelines reshaping import compliance economics for planting machinery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | Reduces exposure to Baden-Württemberg supply chokepoints and compresses lead times for downforce modulation systems. |
| EU AI Act Conformity Investment | Accelerates market access for autonomous planting equipment in German and French high-horsepower tractor segments. |
| Subscription Advisory Unbundling | Replaces upfront hardware margin with recurring data-analytics contracts in Iowa and Illinois dealership networks. |
| Open-Ecosystem Interoperability Partnership | Captures mixed-fleet retrofit demand from operations resisting proprietary telematics lock-in across Brazil's Cerrado. |
| Soil-Data Platform Consolidation | Positions stakeholders to capture algorithm monetization value as ownership frameworks crystallize in North American markets. |
Research Methodology
The analysis maps precision farming tools, seed technology, soil sensors, and autonomous equipment sub-sectors, each validated through equipment OEM procurement directors, agricultural cooperative managers, precision agriculture dealership owners, and farm management platform engineers. Primary interview insights triangulate against secondary sources including EPA Tier 4 Final filings, EU Green Deal strategy documents, ANVISA export compliance records, BIS certification databases, and SEC equipment manufacturer disclosures. Bottom-up sensor deployment counts and top-down agricultural machinery production data reconcile through cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation across product type, application, end user, and technology maturity tiers, with additional dimensioning by fleet size threshold and regulatory compliance cluster. CAGRs derive from equipment replacement cycle compression rates and subscription revenue conversion trajectories. Industry-specific forecast inputs include GNSS correction service adoption curves and hydraulic component lead time normalization assumptions.
Forecasts assume regulatory continuity in EPA emissions enforcement, EU AI Act implementation, and ANVISA traceability mandates; material policy shifts would require re-modeling. Specific risk factors encompass mechatronics technician scarcity constraining field service capacity, semiconductor supply volatility affecting control system availability, and EU carbon-border adjustment timeline acceleration. Practitioners should keep alternative scenarios live as soil-data ownership framework negotiations and platform consolidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Fertigation Monitoring Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
India Microirrigation System Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Harvest Market