
 Europe Seafood Market | 2026-2036
Europe Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Seafood Market Foresight
Premium ASC and MSC certification tiers is redrawing procurement standards across European seafood value chains. Austevoll Seafood ASA leverages its integrated trawler-to-retail operations to secure consistent whitefish supply. Royal Greenland AS anchors its competitive position through dominant cold-water shrimp fisheries in the North Atlantic. Mowi ASA leads Atlantic salmon farming with scale advantages in Norwegian fjord operations.
Europe seafood encompasses finfish, shellfish, and other marine organisms harvested from wild fisheries or aquaculture systems, typically processed to retain protein content above 15 percent and controlled for histamine levels below 200 mg/kg for human consumption. The category serves protein supply for retail consumers and prepared-meal manufacturers requiring standardized portion weights and traceable origin documentation. Fish products occupy the largest volume share within the product type dimension, while online retail channels represent the fastest-expanding distribution pathway as cold-chain logistics improve across the region. Foodservice end users generate concentrated margin pools through contracted volume agreements with hotel and restaurant chains.
EMA food safety guidelines, EU IUU fishing regulations, and national veterinary controls under Regulation 853/2004 shape product standards and market access for seafood operators across member states and EEA partners. These frameworks mandate catch documentation, hygiene certification, and allergen labeling that filter non-compliant suppliers from European distribution networks. Stakeholders must monitor evolving traceability requirements and carbon footprint disclosure rules that will determine supplier eligibility in coming procurement cycles.
Market Dynamics
The EU IUU fishing regulations and Marine Strategy Framework Directive are compressing supplier eligibility while foodservice operators demand traceable origin documentation for premium menu positioning.
Growth Catalysts
- ASC and MSC certification tiers:Retail procurement standards now mandate third-party sustainability verification, filtering non-compliant suppliers from European distribution networks.
- Hotel and restaurant chain expansion:Foodservice operators across Spain, Norway, and Scotland are contracting volume agreements for standardized portion weights with documented cold-chain integrity.
- Recirculating aquaculture systems:Land-based salmon farming technology is reducing fjord dependency while maintaining protein content above 15 percent.
Market Restraints
- Input cost volatility:Fishmeal and fish oil prices fluctuate with Peruvian anchovy harvest cycles, compressing aquaculture feed margins.
- Supply concentration risk:North Atlantic cold-water shrimp fisheries dominate raw material sourcing for processed seafood manufacturers.
- Regulatory friction:EMA food safety guidelines and national veterinary controls under Regulation 853/2004 extend certification timelines for new market entrants.
Strategic Opportunities
- Eastern European retail penetration:Poland and Romania show underdeveloped cold-chain infrastructure for frozen seafood distribution.
- Carbon footprint disclosure mandates:EU Green Deal reporting requirements create first-mover advantage for operators with verified emissions data.
- Direct-to-consumer platforms:Subscription seafood box services bypass traditional wholesale channels in urban Scandinavian markets.
Industry Challenges
- Histamine control expertise:Processing facilities face skill gaps in rapid testing protocols for scombroid species.
- Certification timeline compression:Dual ASC and MSC audits require 18-month compliance windows that strain working capital.
- Legacy traceability integration:Small-scale fishermen lack capital to retrofit vessels with mandatory catch documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Seafood Market |
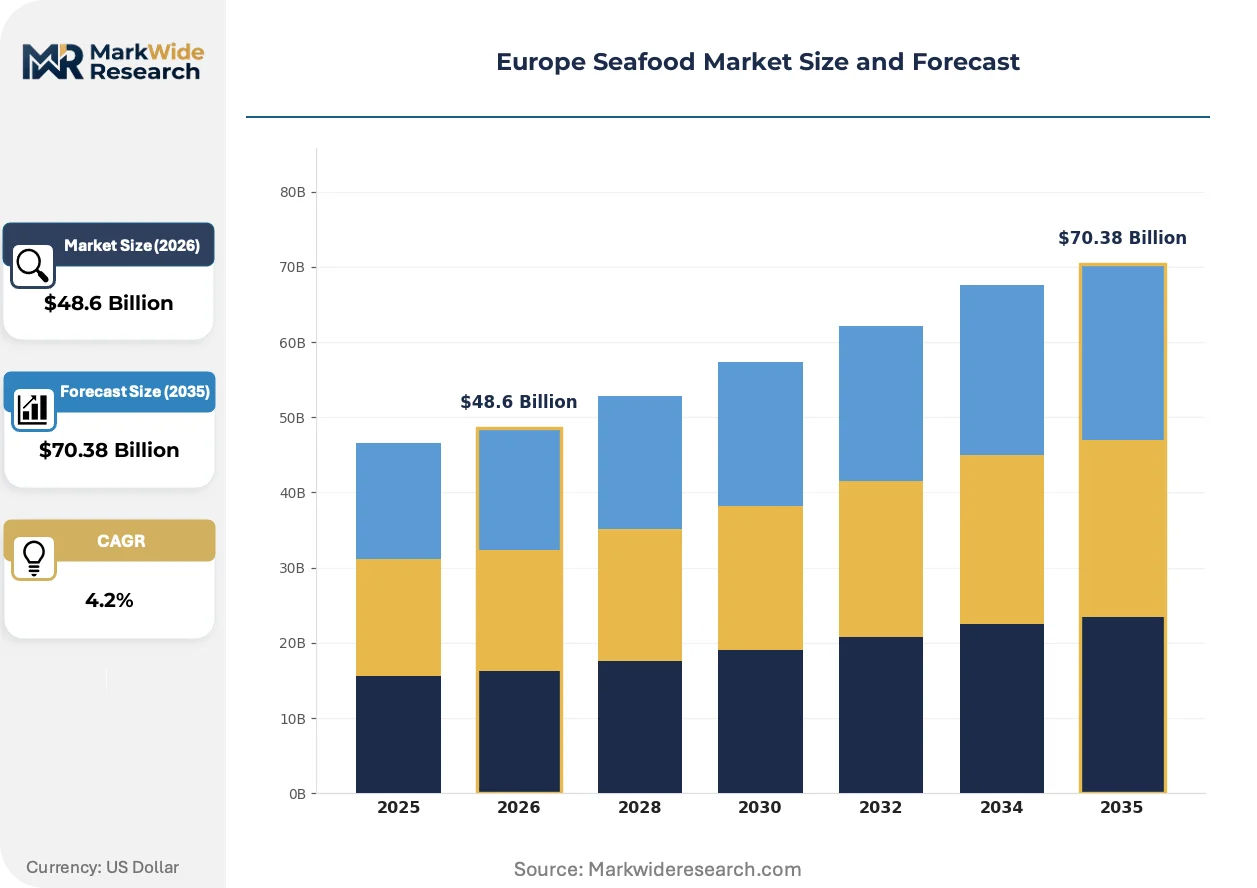
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $70.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shellfish, Cephalopods, Crustaceans Distribution Channel: Supermarkets, Online Retail, Fish Markets, Foodservice End User: Restaurants, Households, Hotels, Catering Services Sales Channel: Direct Sales, Distributors, Wholesalers, Exporters |
| Companies Covered | Austevoll Seafood ASA, Royal Greenland AS, Mowi ASA, Nueva Pescanova SA, Nomad Foods Ltd, Leroy Seafood Group, Grieg Seafood ASA, Young's Seafood Ltd, SalMar ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Seafood Market Shifts & Advancements
Digital traceability platforms and automated processing systems are compressing traditional supply chain intermediaries while regulatory disclosure requirements reshape competitive positioning.
Blockchain-based catch documentation is fragmenting the seafood provenance market. Norwegian fjord operators and Scottish salmon farmers are adopting distributed ledger systems to verify chain-of-custody. This technology is fragmenting trust mechanisms away from paper-based certificates toward immutable transaction records that retailers can query in real time.
EU Green Deal carbon border adjustment mechanisms are tightening emissions disclosure for imported seafood. Processors must now document fuel consumption across trawler operations and refrigeration transport. Spanish whitefish importers and Dutch shellfish distributors face the steepest compliance curves as they reconfigure supplier qualification criteria.
Certification-driven preference shifts are restructuring procurement hierarchies. Foodservice buyers now rank ASC and MSC credentials above price in contract negotiations. This behavioral change concentrates volume with vertically integrated operators who control both farming and primary processing, particularly visible in Norwegian Atlantic salmon supply chains.
Europe Seafood Market Segmentation
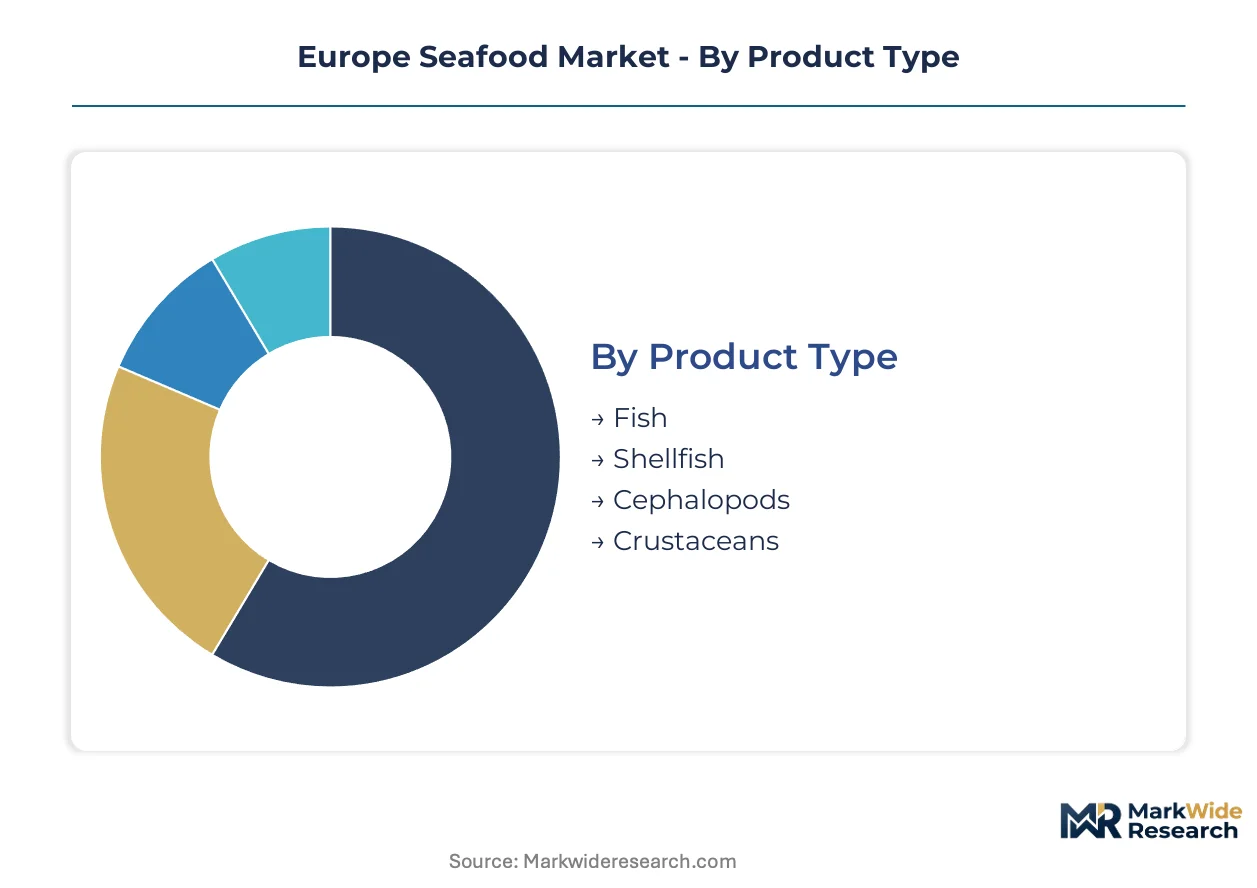
European seafood procurement patterns diverge sharply across product categories and channel configurations. Certification requirements and cold-chain capabilities filter supplier eligibility differently through each segment pathway.
Product Type:
Substitution pressure from plant-based proteins and cultivated seafood alternatives targets finfish and shellfish most aggressively, forcing differentiation through provenance documentation.
- Fish:Atlantic salmon, cod, and haddock dominate volume with protein content standardized above 15 percent. Norwegian fjord operations and Scottish sea loch farms supply contracted volumes to Spanish and German retail chains under ASC certification protocols.
- Shellfish:Mussels and oysters from Dutch Wadden Sea operations and Irish Atlantic coastlines carry live-handling requirements that constrain distribution radius. Cold-water shrimp from North Atlantic fisheries anchor premium positioning in foodservice channels.
- Cephalopods:Spanish and Portuguese coastal fleets supply octopus and squid with rapid-freeze protocols to control enzymatic degradation.
- Crustaceans:Langoustines and brown crab from Scottish and Norwegian waters serve high-margin restaurant segments.
Fish retains volume leadership; Shellfish holds the steepest expansion curve through premium restaurant placement.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain infrastructure from low-touch traditional outlets.
- Supermarkets:Centralized procurement teams at Carrefour, Tesco, and REWE mandate MSC and ASC certification for shelf placement. Standardized portion weights and vacuum-sealed packaging dominate private-label offerings.
- Online Retail:Subscription box operators in Copenhagen, Stockholm, and Amsterdam bypass wholesale markups with direct-to-consumer logistics. Cold-chain integrity verification through IoT temperature logging supports premium pricing.
- Fish Markets:Traditional auction halls in Bergen, Boulogne-sur-Mer, and Peterhead retain price-discovery functions for fresh-catch distribution to smaller processors.
- Foodservice:Contracted volume agreements with Accor, Marriott, and Iberostar chains specify traceable origin documentation for menu storytelling.
Supermarkets retain volume leadership; Online Retail is gaining share fastest through urban Scandinavian penetration.
End User:
Application-specific requirements separate institutional buyers with technical specifications from consumer segments prioritizing convenience.
- Restaurants:Michelin-starred establishments in Paris, London, and San Sebastian specify day-boat catch documentation and chef-to-fisher direct relationships.
- Households:Retail consumers in Poland and Romania show emerging demand for frozen value-added products as cold-chain infrastructure develops.
- Hotels:Buffet operations require consistent portion sizing and extended holding stability under warming lamps.
- Catering Services:Event operators across Germany and France prioritize pre-portioned, individually quick-frozen products for labor efficiency.
Restaurants retain volume leadership; Households show the steepest expansion trajectory through Eastern European retail development.
Sales Channel:
Customer-type concentration determines margin capture, with integrated operators bypassing intermediary layers.
- Direct Sales:Large-scale aquaculture operators like Mowi ASA and Austevoll Seafood ASA ship containerized volumes directly to retail central distribution centers.
- Distributors:Pan-European specialists such as Lyons Seafoods and Seafood Connection aggregate fragmented supply for mid-size retail and foodservice accounts.
- Wholesalers:Regional operators in Mediterranean ports consolidate mixed-species shipments for smaller processors lacking direct import licenses.
- Exporters:Norwegian and Scottish salmon processors dominate extra-EU shipments with documentation compliant with destination market veterinary controls.
Distributors retain volume leadership; Direct Sales climbs fastest as vertical integration deepens among major producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlantic salmon farming concentrates in Norwegian fjords and Scottish sea lochs, while North Atlantic shrimp fisheries anchor processing capacity in Greenland and Iceland. Spain, France, and Germany absorb the majority of finished seafood distribution through their retail and foodservice networks. National veterinary controls and EU IUU fishing regulations filter supplier eligibility differently across member states.
Norway
Norwegian fjord operations supply contracted Atlantic salmon volumes to German and Spanish retail chains under ASC certification protocols. The Norwegian Food Safety Authority enforces strict veterinary controls on aquaculture sites, aligning with EU Regulation 853/2004 for export market access. Bergen anchors cold-water species processing, with automated filleting plants serving pan-European distribution networks.
Spain
Spanish foodservice operators expand premium seafood menu offerings, driving demand for traceable origin documentation from Galician and Basque coastal fleets. The Ministry of Agriculture, Fisheries and Food implements EU Common Fisheries Policy reforms through national quota allocation systems. Vigo concentrates cephalopod processing, with rapid-freeze protocols controlling enzymatic degradation for octopus and squid exports.
Scotland
Scottish salmon farmers leverage sea loch sites to supply certified aquaculture products for UK and European retail procurement. Marine Scotland enforces Marine Strategy Framework Directive requirements through habitat protection zones and sustainable sourcing mandates. Peterhead retains price-discovery functions at its traditional auction hall, linking fresh-catch distribution to smaller processors across the North Sea basin.
Germany
German retail chains REWE and Edeka mandate MSC and ASC certification for private-label seafood shelf placement, filtering non-compliant suppliers. The Federal Office of Consumer Protection and Food Safety coordinates national veterinary controls with EMA food safety guidelines. Bremerhaven processes imported whitefish volumes, with cold-chain logistics hubs distributing standardized portion weights across Central European markets.
France
French foodservice buyers rank sustainability credentials above price in contract negotiations, concentrating volume with vertically integrated operators. The Directorate General for Food enforces EU IUU fishing regulations through catch documentation verification at Boulogne-sur-Mer. Paris and San Sebastian anchor premium restaurant demand, where Michelin-starred establishments specify day-boat catch documentation for menu storytelling.
Europe Seafood Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European seafood value chain. Vertically integrated aquaculture operators control farming and primary processing stages, while specialized distributors aggregate fragmented wild-catch supply. The market structure tiers into scale-driven salmon farmers, regionally focused whitefish processors, and pan-European distribution specialists. Dominant competitive moves include backward integration into feed production and geographic expansion through direct-to-retail channel development.
Among Nordic integrated operators, Austevoll Seafood ASA, Mowi ASA, and Royal Greenland AS occupy positions reflecting distinct supply chain archetypes. Austevoll Seafood ASA exemplifies trawler-to-retail integration with consistent whitefish supply control. Mowi ASA represents scale advantages in Norwegian fjord salmon farming with documented cold-chain integrity. Royal Greenland AS anchors competitive positioning through dominant North Atlantic cold-water shrimp fisheries access.
| Leading Market Players |
|---|
| Austevoll Seafood ASA |
| Royal Greenland AS |
| Mowi ASA |
| Nueva Pescanova SA |
| Nomad Foods Ltd |
| Leroy Seafood Group |
| Grieg Seafood ASA |
| Young's Seafood Ltd |
| SalMar ASA |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Norwegian salmon farmers and German retail central procurement teams lock in volume commitments and provide 12-18 month price visibility, insulating ASC-certified producers from spot market volatility in fishmeal and fish oil inputs. These arrangements concentrate margin protection with vertically integrated operators while compressing price discovery for smaller wild-catch suppliers dependent on auction hall sales.
Pricing Analysis
EU Regulation 853/2004 dictates the pricing tier structure across European seafood value chains by mandating veterinary certification costs that stratify market access. Three-tier pricing separates ASC-certified premium salmon from standard farmed product and unverified wild-catch economy tiers, with differentiation driven by certification grade and cold-chain integrity documentation. Price erosion runs through the economy tier as Eastern European retail buyers demand traceability without premium positioning. Foodservice chains show least price sensitivity, while Polish and Romanian household segments remain most responsive to promotional discounting.
Supply Chain Analysis
Bergen-to-Bremerhaven cold-chain corridors constitute the primary logistics chokepoint for Norwegian salmon entering Central European distribution networks. Supply concentrates in Norway, Scotland, and Iceland for Atlantic salmon and North Atlantic shrimp, with raw material dependencies on Peruvian anchovy harvests for fishmeal and South American soy derivatives for aquaculture feed. Single-source vulnerability persists in automated filleting equipment supply, where Dutch and Danish manufacturers dominate. Distribution runs through centralized retail procurement hubs rather than traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and distribution channels creates niche entry points as foodservice buyers disaggregate volume contracts in favor of specialized provenance sourcing. ASC and MSC compliance costs filter supplier pools unevenly, opening gaps for targeted positioning.
For Market Incumbents: Compound scale advantages in Norwegian fjord operations by securing captive fishmeal supply through backward integration into Peruvian reduction fisheries. Invest in blockchain catch documentation to defend against emerging land-based salmon competitors with superior carbon footprint credentials. Prioritize direct-to-retail channel control in German and Spanish markets where centralized procurement teams are consolidating supplier lists. For New Entrants and Emerging Players: Differentiate on recirculating aquaculture system technology to bypass fjord licensing constraints and serve urban Scandinavian subscription box channels with hyper-local provenance narratives. Target Polish and Romanian retail development where cold-chain infrastructure gaps delay incumbent penetration. Pursue chef-to-fisher direct relationships in San Sebastian and Paris restaurant clusters as the most penetrable premium segment. For Investors and Strategic Acquirers: Mid-scale whitefish processors with established MSC certification and underutilized processing capacity represent the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on feed cost hedging capabilities and regulatory compliance infrastructure rather than volume scale alone. Watch for EU Green Deal carbon border adjustment implementation as the inflection signal that revalues low-emissions supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| ASC Certification Investment | Secures shelf placement at Carrefour, Tesco, and REWE centralized procurement teams. |
| Blockchain Traceability Deployment | Enables real-time provenance queries by foodservice buyers demanding documented chain-of-custody. |
| Recirculating Aquaculture System Scale-Up | Reduces fjord dependency while maintaining protein content standards above EU thresholds. |
| Eastern European Cold-Chain Partnership | Captures emerging household demand in Poland and Romania as retail infrastructure develops. |
| Carbon Footprint Verification Program | Positions operators for EU Green Deal reporting requirements and procurement eligibility filters. |
Research Methodology
Desk research of customs trade data, EFSA food safety bulletins, and EU Common Fisheries Policy implementation reports preceded structured interviews with aquaculture operations managers, retail category buyers, foodservice procurement directors, and cold-chain logistics coordinators. Primary fieldwork captured contract structure patterns and certification timeline pressures, validated against secondary sources including Norwegian Food Safety Authority inspection records and Marine Stewardship Council audit disclosures. Bottom-up volume modeling triangulated with top-down expenditure analysis across member state consumption patterns.
Variance decomposition across product type, distribution channel, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention effects and technology adoption curves. Modeled inputs incorporated fishmeal price volatility indices, ASC certification penetration rates, and cold-chain infrastructure investment flows by member state.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt feed input cost shocks would require recalibration. Forecasts reflect documented assumptions regarding certification adoption timelines and foodservice contract renewal patterns. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and land-based salmon technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Rainbow Trout Market
Seafood
US Crustacean Market
Seafood
Canned Sardines Market
Seafood
Europe Dried Scallop Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Milkfish Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Europe Lobster Market
Seafood
Fish Protein Market
Seafood
Tuna Fish Market
Seafood
Octopus Market
Seafood
Alaskan Salmon Market
Seafood
European Frozen Seafood Market
Seafood
Canned Salmon Market
Seafood
Sea Biscuits Market
Seafood
Fish Processing Market