
 Employee Wellness Software Market | 2026-2036
Employee Wellness Software Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Wellness Software Market Foresight
Subscription-based wellness platforms is pivoting vendor revenue models from perpetual licenses to recurring engagement metrics. Personify Health leverages employer health plan integrations to sustain multi-year contracts. Headspace for Work anchors its position through meditation content libraries that differentiate against activity-only competitors. VantageFit specializes in gamified fitness challenges that occupy the mid-market segment between premium platforms and basic tracking tools.
Employee wellness software comprises digital systems that collect biometric, behavioral, and self-reported health data to deliver personalized interventions, typically integrating with wearable sensors and HR information systems via API architectures. Its primary commercial purpose is reducing employer medical costs and absenteeism through predictive risk stratification and targeted coaching workflows. Wellness platforms dominate current deployments due to their modular architecture allowing corporations to add mental health support or nutrition coaching without replacing core infrastructure. Cloud-based delivery is expanding fastest as small businesses abandon on-premise servers for SaaS models with lower upfront commitment.
HIPAA governs protected health information handling across US employer programs, while OSHA workplace safety standards increasingly reference psychosocial hazard assessments that wellness software must document. The US FDA regulates software-as-medical-device claims when platforms diagnose or treat conditions, creating compliance barriers for vendors expanding into clinical functionality. Stakeholders should monitor how state-level insurance mandates for mental health parity reshape required feature sets before committing to platform architectures.
Market Dynamics
Employer-sponsored healthcare cost containment is compressing procurement cycles and forcing wellness platforms to prove ROI through biometric outcome tracking rather than engagement metrics alone.
Growth Catalysts
- HIPAA-compliant data architectures:US employers demand audit-ready privacy frameworks that unlock insurance premium discounts for validated wellness participation.
- Wearable sensor convergence:Continuous glucose monitors and sleep trackers feed real-time risk scores into coaching algorithms.
- Psychosocial hazard documentation:OSHA's expanded workplace mental health standards mandate software-based stress assessment protocols.
Market Restraints
- FDA software-as-medical-device classification:Diagnostic or treatment claims trigger 510(k) clearance requirements that stall product roadmaps.
- Cloud infrastructure concentration:AWS and Azure dominance in healthcare data hosting creates single-point vulnerability for mid-market vendors.
- Behavioral economics limitations:Sustained user engagement beyond 90 days requires costly human coaching augmentation.
Strategic Opportunities
- State mental health parity mandates:California and New York insurance regulations are expanding required platform feature sets.
- Chronic condition management modules:Diabetes and hypertension prevention programs attract separate reimbursement codes.
- API-first ecosystem integration:HRIS and benefits administration connectivity is opening channel partnerships with Workday and SAP.
Industry Challenges
- Clinical validation timelines:Peer-reviewed outcome studies require 18-24 month publication cycles that lag sales cycles.
- Interoperability fragmentation:HL7 FHIR implementation varies across health systems, forcing redundant integration engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Wellness Software Market |
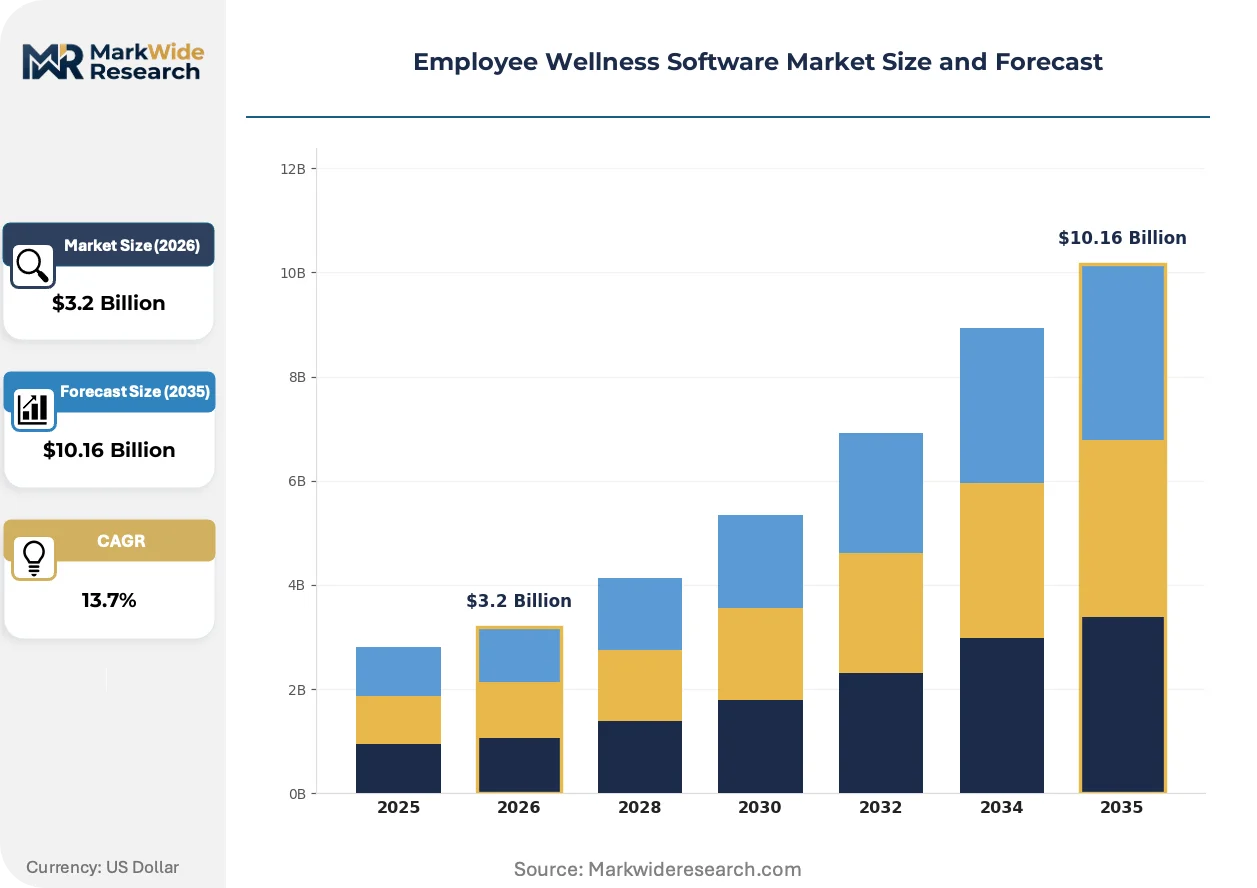
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $10.16 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Wellness Platforms, Health Assessment Tools End User: Corporations, Small Businesses, Educational Institutions, Non-Profits Deployment: On-Premise, Cloud-Based, Hybrid Solutions, SaaS Feature: Goal Setting, Activity Tracking, Nutrition Coaching, Mental Health Support |
| Companies Covered | Wellable, Wellness360, Personify Health, YuMuuv, CoreHealth Technologies, VantageFit, Headspace for Work, WebMD Health Services, Forma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Wellness Software Market Shifts & Advancements
Generative AI is compressing content production costs while biometric authentication is hardening data security protocols. Platform differentiation is migrating from feature breadth to outcome guarantees.
Large language models are expanding into personalized coaching scripts that adapt to individual stress biomarkers in real time. Self-insured employers with over 5,000 covered lives are piloting these systems fastest. The technology is expanding into predictive absence risk scoring that triggers preemptive interventions.
The FDA's evolving digital health oversight is tightening substantiation requirements for anxiety and depression management claims. Vendors must now compile real-world evidence portfolios before marketing clinical outcomes. Mental health modules face the steepest compliance burden as enforcement actions concentrate on cognitive behavioral therapy analogues.
Buyer committees now require outcome-based pricing tied to medical cost reduction rather than per-employee-per-month fees. Benefits consultants are restructuring their compensation around verified ROI demonstrations. This shift is most visible in the Fortune 500 segment where CFO involvement in wellness procurement has doubled.
Employee Wellness Software Market Segmentation
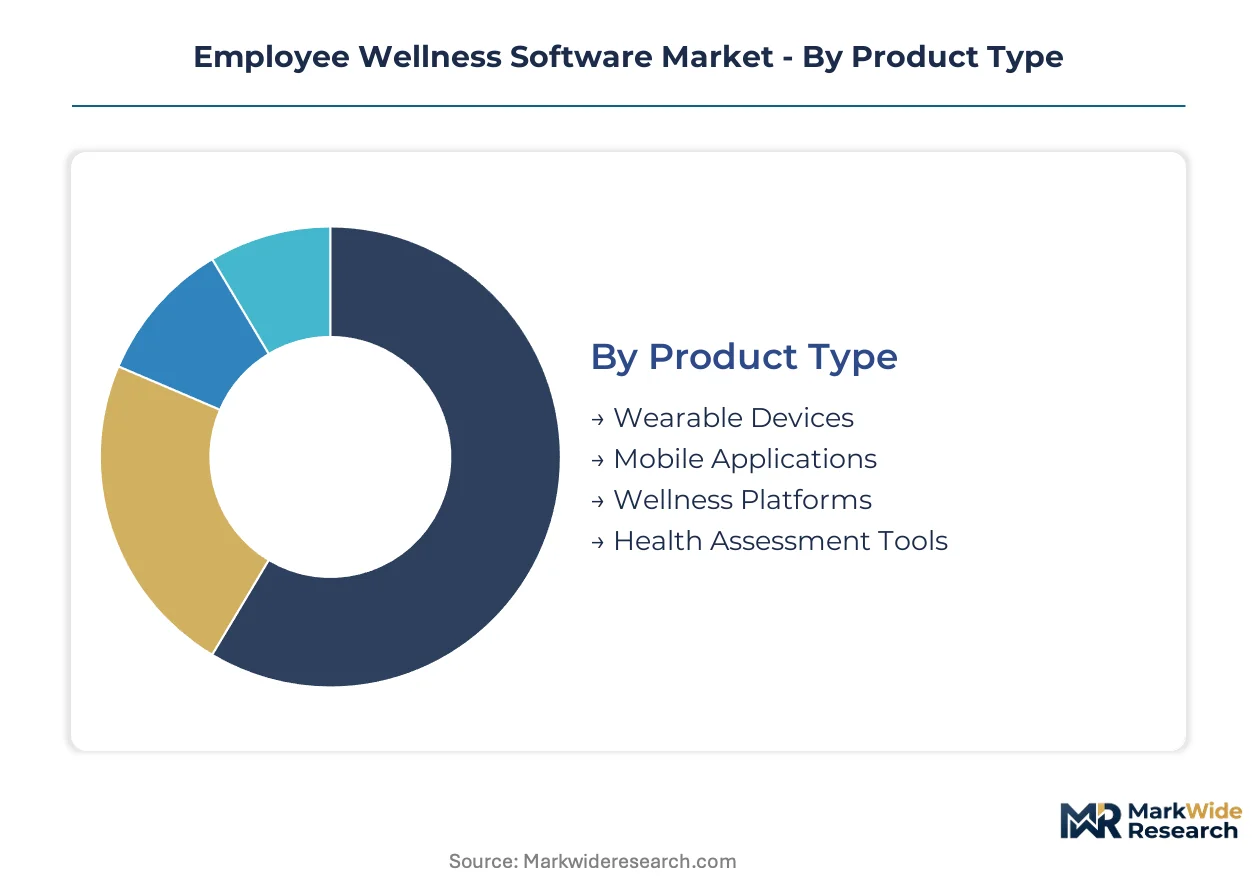
Segmentation in employee wellness software determines procurement priorities and integration complexity. Buyers evaluate platforms across product architecture, organizational scale, deployment flexibility, and intervention modality. Each dimension carries distinct compliance obligations and ROI measurement protocols.
Product Type:
Procurement committees weight total cost of ownership against biometric data granularity when selecting product categories.
- Wellness Platforms:Modular systems integrate HRIS data streams with coaching workflows through API architectures. Large corporations with distributed workforces in the United States dominate demand as HIPAA-compliant data lakes unlock insurance premium discounts.
- Mobile Applications:Smartphone-native interfaces deliver push-notification interventions and micro-learning modules. Small businesses across California and Texas prefer these for lower upfront commitment and minimal IT overhead.
- Wearable Devices:Continuous biometric sensors from Fitbit, Apple, and Garmin feed real-time risk scores into employer dashboards.
- Health Assessment Tools:Self-reported questionnaires and biometric screening schedulers satisfy OSHA documentation requirements.
Wellness platforms lead on scale; mobile applications lead on momentum.
End User:
Organization size dictates feature requirements and contract duration expectations.
- Corporations:Enterprises with 5,000+ covered lives demand predictive analytics and dedicated account management. Self-insured employers in New York and Illinois pilot generative AI coaching scripts fastest.
- Small Businesses:Firms under 500 employees prioritize per-employee-per-month pricing and rapid deployment. Cloud-based SaaS models displace on-premise alternatives across Florida and Ohio.
- Educational Institutions:Universities and K-12 districts require FERPA-aligned privacy frameworks alongside student mental health modules.
- Non-Profits:Mission-driven organizations seek grant-funded wellness subsidies and volunteer coordinator tools.
Corporations capture the largest contract values; small businesses expand the addressable market most rapidly.
Deployment:
IT infrastructure maturity and data sovereignty concerns drive architecture selection.
- Cloud-Based:AWS and Azure-hosted instances eliminate server maintenance burdens. Mid-market vendors concentrate here to avoid capital expenditure barriers for buyers.
- SaaS:Subscription models with automatic feature updates dominate new procurement cycles. Benefits administrators favor these for simplified renewal workflows.
- Hybrid Solutions:Mixed architectures keep sensitive biometric data on-premise while routing analytics to cloud processors.
- On-Premise:Legacy server installations persist in defense contractors and financial institutions with strict data localization mandates.
Cloud-based deployments claim the steepest expansion trajectory; on-premise retains defensive positions in regulated sectors.
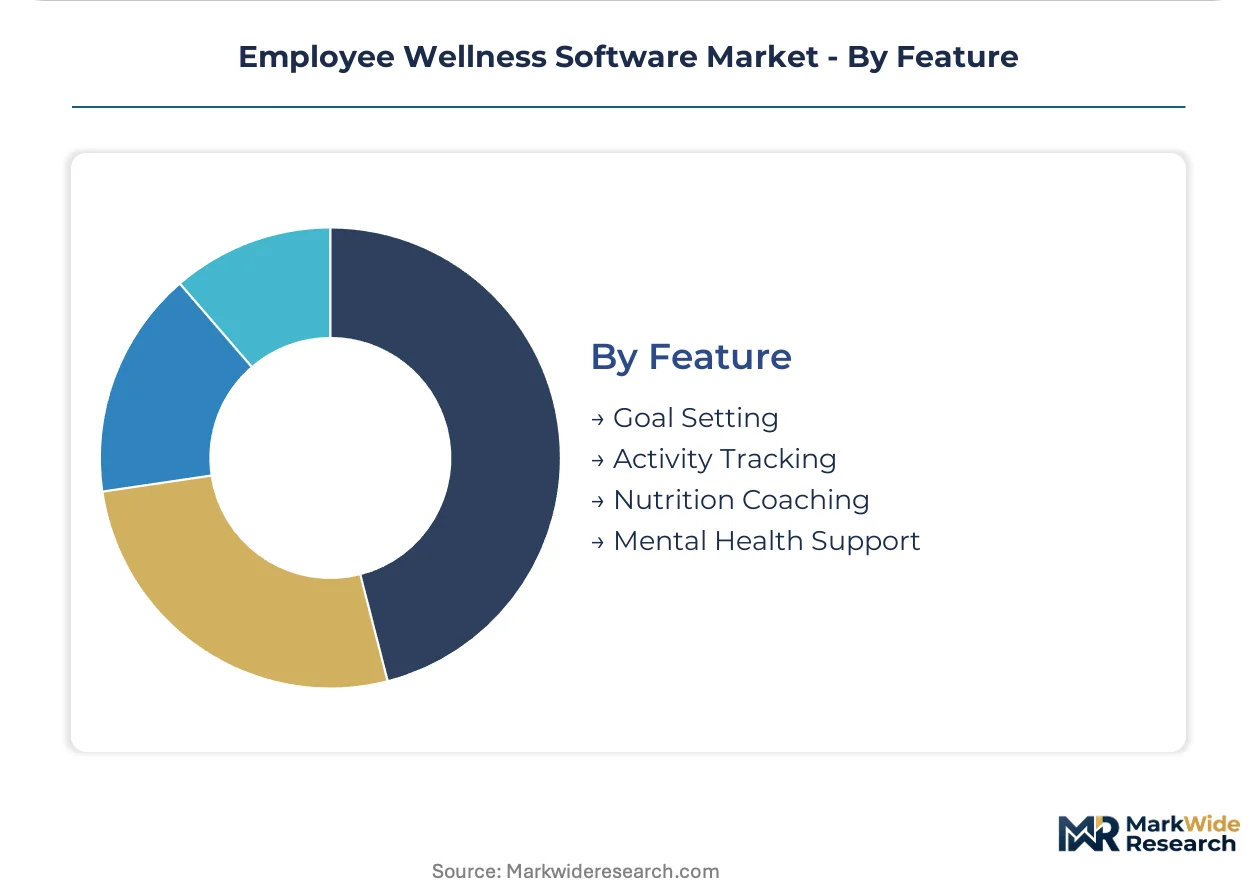
Feature:
Module selection reflects employer liability priorities and workforce demographic composition.
- Mental Health Support:Cognitive behavioral therapy analogues and stress biomarker tracking face FDA software-as-medical-device scrutiny. California and New York insurance mandates are expanding required feature sets fastest.
- Activity Tracking:Step counting, workout logging, and gamified fitness challenges occupy the mid-market segment. OSHA's psychosocial hazard documentation requirements are embedding these tools into safety protocols.
- Nutrition Coaching:Meal logging and dietary intervention modules attract separate reimbursement codes for diabetes prevention programs.
- Goal Setting:Personalized milestone frameworks with manager visibility drive engagement metrics for HR reporting.
Activity tracking leads on employer penetration; mental health support climbs the fastest as parity mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor headquarters decisions as HIPAA compliance costs in the United States push mid-market developers toward Canadian and European jurisdictions with lighter data governance burdens. Ireland and Estonia now host regional engineering centers for platforms serving American employers.
United States
Self-insured employers with over 5,000 covered lives drive platform sophistication demands across Illinois and New York. HIPAA audit frameworks and state-level mental health parity mandates in California expand required feature sets annually. The Boston-Cambridge corridor concentrates predictive analytics vendors developing generative AI coaching scripts for Fortune 500 contracts.
Canada
Provincial health system integrations create procurement pathways for wellness modules targeting public sector unions in Ontario and British Columbia. PIPEDA privacy standards attract American vendors seeking data-residency alternatives to HIPAA complexity. Toronto's fintech corridor incubates API-first startups connecting HRIS systems to wearable data streams.
Germany
Works council consultation requirements under the Betriebsrätegesetz slow enterprise software deployments but strengthen long-term contract stability. GDPR compliance investments exceed North American baselines, filtering out undercapitalized competitors. Munich and Frankfurt financial services clusters pilot biometric authentication protocols for banking sector wellness programs.
United Kingdom
NHS employer mandates and private sector insurance incentives converge around mental health module procurement in London and Southeast England. The Information Commissioner's Office enforces stricter health data processing standards than American state regulators. Manchester's digital health cluster hosts mid-market vendors specializing in cloud-based SaaS delivery for small businesses.
India
IT services exporters in Bangalore and Hyderabad deploy wellness platforms for American and European client workforces, creating demand for HIPAA-aligned engineering capabilities. The Digital Personal Data Protection Act 2023 establishes baseline privacy frameworks that attract multinational vendor subsidiaries. Mumbai's financial services sector pilots wearable integration programs for banking employees.
Employee Wellness Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated wellness platforms commanding premium pricing against point-solution vendors. The vendor base concentrates around three tiers: enterprise-grade systems with dedicated account management, mid-market SaaS offerings with modular feature expansion, and mobile-native applications targeting small business budgets. Dominant competitive moves include API ecosystem partnerships with HRIS incumbents and outcome-based pricing restructures tied to medical cost reduction guarantees.
Within the enterprise platform tier, Personify Health and Headspace for Work exemplify divergent specialization strategies—health plan integration versus content library depth—while VantageFit occupies the mid-market gamification segment between premium suites and basic tracking tools. These three vendors represent distinct archetypes: the benefits-administrator-aligned incumbent, the wellness-content pure-play, and the engagement-metrics specialist. Their positioning reflects broader market segmentation between medical cost containment buyers and employee experience optimizers.
| Leading Market Players |
|---|
| Wellable |
| Wellness360 |
| Personify Health |
| YuMuuv |
| CoreHealth Technologies |
| VantageFit |
| Headspace for Work |
| WebMD Health Services |
| Forma |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up wellness specialists anchor supply discipline through multi-year platform consolidations, compressing vendor margins while enforcing outcome-based pricing guarantees that tether SaaS fees to measurable medical cost reductions.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for mid-market SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by covered-life count and integration complexity. Price differentiation hinges on HIPAA audit readiness and dedicated account management depth. Cost compression in the small-business tier is intensifying because mobile-native entrants undercut legacy per-employee-per-month baselines. Fortune 500 self-insured employers show least price sensitivity; sub-500-employee firms negotiate hardest on upfront commitment.
Supply Chain Analysis
API-first distribution channels handle hyperscale buyer demand through direct HRIS integrations. Engineering talent concentrates in Ireland, Estonia, and India as regulatory arbitrage displaces US-based development. Platform architectures draw from AWS and Azure cloud instances, wearable sensor data streams, and third-party coaching content libraries. Single-source vulnerability in cloud hosting creates concentration risk for mid-market vendors without multi-provider redundancy. Distribution runs through benefits consultants and HR technology marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employer-sponsored healthcare cost containment positions this market as a stable compounder, with biometric outcome validation driving sustained procurement cycles regardless of macroeconomic volatility.
For Market Incumbents: Lock in long-term contracts through health plan integration partnerships that embed platforms into benefits administration workflows. Deepen HIPAA-compliant data lake investments to sustain insurance premium discount eligibility. Counter emerging generative AI coaching entrants by accelerating clinical validation timelines for predictive risk stratification modules. For New Entrants and Emerging Players: Begin with white-label API services for mid-market HRIS vendors lacking native wellness capabilities. Target state-level mental health parity mandate compliance as the most penetrable regulatory wedge. Pursue channel partnerships with benefits administrators serving California and New York employers facing expanded feature requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market SaaS vendors with modular architecture but limited outcome-guarantee track records. Five-to-ten-year viability favors platforms with demonstrated medical cost reduction documentation. Monitor FDA software-as-medical-device enforcement actions as the critical inflection signal for clinical functionality expansion risk.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Partnership | Workday and SAP integrations unlock Fortune 500 procurement pathways. |
| Outcome-Based Pricing Restructure | CFO-validated ROI demonstrations displace engagement-metric contracts. |
| Clinical Validation Investment | Peer-reviewed studies satisfy FDA substantiation for mental health modules. |
| Generative AI Coaching Deployment | Real-time biomarker adaptation differentiates against static content libraries. |
| Geographic Engineering Expansion | Ireland and Estonia hubs reduce HIPAA compliance cost burdens. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged benefits consultants, HR technology procurement officers, wellness platform product managers, and self-insured employer benefits directors. Secondary validation drew from SEC filings of publicly traded wellness vendors, HIPAA audit documentation, FDA digital health guidance releases, and state insurance mandate regulatory databases. Bottom-up deployment estimates and top-down employer spending analysis were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to documented platform adoption cycles and reimbursement code expansion timelines. Segmentation dimensions modeled include deployment architecture, organization size tier, intervention modality, and regional regulatory cluster. CAGRs were derived from fitted growth curves against verified installation counts. Forecast inputs incorporated wearable sensor penetration rates and mental health parity mandate implementation schedules.
Several conditions sit outside the modeled scope, including potential FDA reclassification of wellness platforms as medical devices and abrupt shifts in employer-sponsored healthcare policy. Forecasts reflect assumptions about sustained ROI demonstration requirements and cloud infrastructure cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Drone Mapping Software Market
Software & Services
Office Productivity Software Market
Software & Services
Global Order Management Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Global Nosql Software Market
Software & Services
Streaming Server Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Winery Management Software Market
Software & Services
Preschool Education Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Managed Information Services Market
Software & Services
Global Catalog Management Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Janitorial Software Market