
 Gym Management Software Market | 2026-2036
Gym Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Management Software Market Outlook
Developer talent scarcity in fitness-tech is rotating venture attention toward platforms that automate routine coding through low-code configuration. Mindbody sustains market presence through extensive third-party marketplace integrations. Zen Planner dominates the CrossFit and boutique studio niche with specialized workflow tools. Virtuagym competes aggressively on mobile-first design for European operators.
Gym management software encompasses member onboarding, scheduling, billing, and retention analytics delivered through web and mobile interfaces, typically requiring REST API connectivity and SOC 2 Type II certification for payment data handling. Its primary commercial purpose is reducing administrative labor while increasing member lifetime value through automated engagement triggers. Cloud-based deployment leads the market as operators abandon server maintenance burdens, though hybrid architectures persist among large chains with legacy ERP dependencies. Subscription-based pricing anchors revenue predictability for vendors, while enterprise solutions capture disproportionate margin pools from multi-location operators requiring custom branding and centralized reporting.
FCC guidelines on telecommunications infrastructure affect mobile app reliability requirements for gym software vendors serving US customers. GDPR compliance shapes data residency decisions for European deployments, particularly around biometric check-in and health data processing. ISO 27001 certification is becoming a procurement gate for health club chains evaluating vendor security posture. Stakeholders must weigh the trade-off between vertical feature depth and horizontal integration breadth when selecting platforms.
Market Dynamics
Cloud-native architecture migration is compressing vendor switching costs while API standardization is fragmenting data moats across the gym management software landscape.
Growth Catalysts
- Wearable device integration:Bluetooth Low Energy and Apple HealthKit protocols are creating real-time biometric data streams that studios monetize through personalized coaching tiers.
- GDPR Article 9 health data processing frameworks:European operators are investing in compliant check-in systems that unlock premium membership pricing through verified attendance analytics.
- Boutique studio proliferation:Specialized fitness concepts in urban United States clusters are demanding modular software stacks that scale from single locations to twenty-plus unit regional chains.
Market Restraints
- Payment processor concentration:Stripe and Square dominance in United States gym software integrations creates single-point-of-failure risk for billing continuity during API outages.
- SOC 2 Type II audit timelines:The six-to-nine month certification cycle delays vendor entry into enterprise health club procurement pipelines.
- Legacy ERP dependencies:Large United States franchise chains with on-premise Oracle or SAP installations face middleware costs that cloud-native competitors avoid.
Strategic Opportunities
- India fitness market penetration:Sub-$10 monthly software pricing tiers align with emerging gym operator margins in tier-two Indian cities where digital payment adoption is accelerating.
- CE marking for biometric hardware:European Union medical device classification pathways for heart-rate monitoring check-in kiosks create first-mover certification advantages.
- AI-driven churn prediction:Machine learning models trained on attendance pattern data are enabling automated re-engagement campaigns that reduce member acquisition cost burdens.
Industry Challenges
- Full-stack developer scarcity:Fitness-technology vendors compete for talent against fintech and health-tech sectors offering equity packages that bootstrapped gym software startups cannot match.
- Multi-platform integration complexity:Operators demand seamless connections between scheduling, access control, and nutrition tracking apps, requiring vendor engineering resources that strain mid-tier providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Management Software Market |
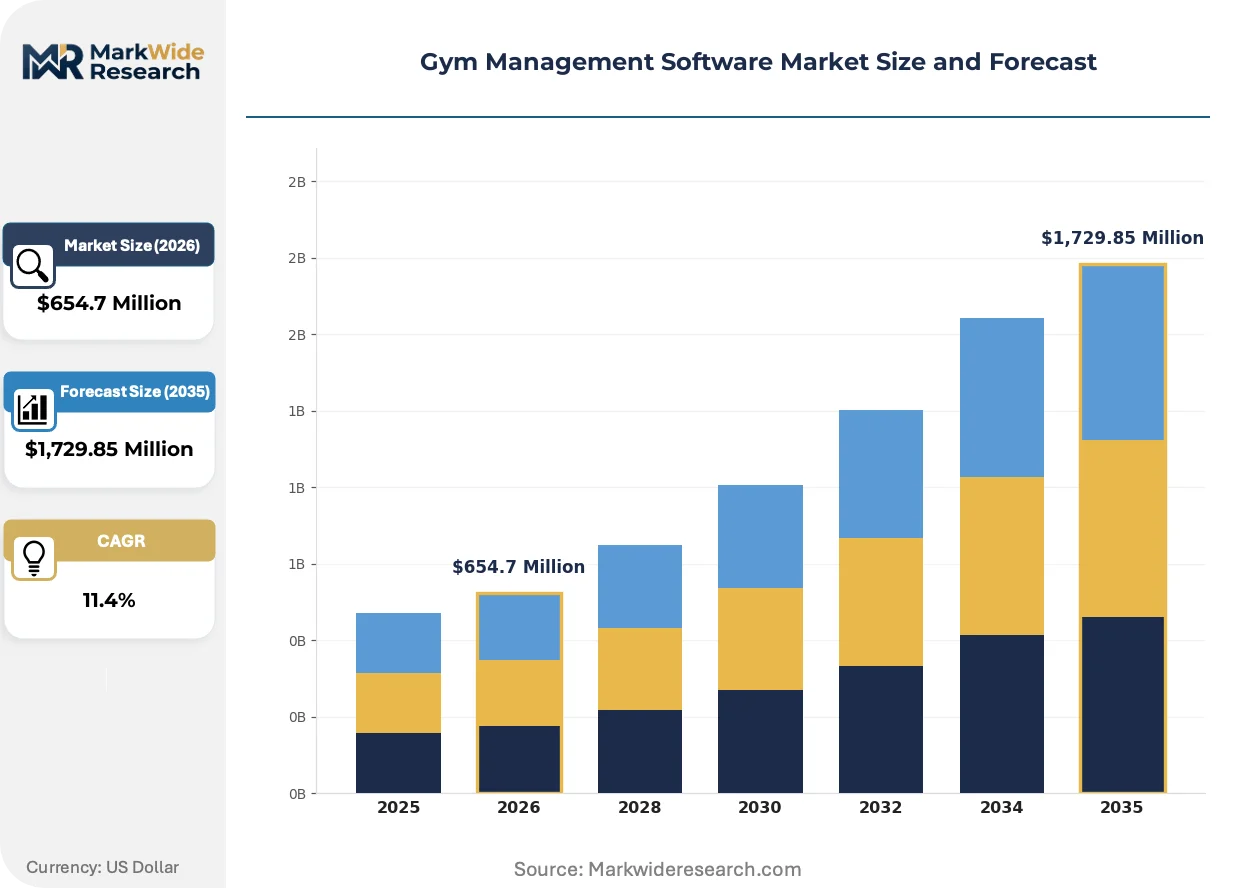
| Market Size in 2026 | $654.7 Million |
| Market Size in 2035 | $1,729.85 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subscription-Based, One-Time Purchase, Freemium, Enterprise Solution End User: Fitness Centers, Personal Trainers, Health Clubs, Corporate Gyms Deployment: Cloud-Based, On-Premises, Hybrid, Mobile App Customer Type: Small Businesses, Medium Enterprises, Large Chains, Individual Trainers |
| Companies Covered | Zen Planner, Wodify, Mindbody, Virtuagym, Perfect Gym, Glofox, 1club, GymMaster, PushPress, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Management Software Market Strategic Shifts
Embedded finance capabilities and edge computing deployments are redrawing competitive boundaries between pure software vendors and vertically integrated fitness platforms.
Edge computing infrastructure is miniaturizing. Local server nodes now process member check-in and access control at individual gym locations, eliminating latency-dependent cloud round-trips. Boutique United States operators with unreliable rural internet are adopting these systems fastest. This architecture is miniaturizing the data center footprint required for real-time facility management, compressing hardware procurement cycles from three-year server refreshes to plug-and-play appliance swaps.
FCC broadband infrastructure mapping requirements are reshaping mobile app reliability standards. Gym software vendors serving United States customers must now engineer offline-first functionality for member-facing features. Studios in broadband-underserved census tracts are demanding local data caching that synchronizes when connectivity resumes. This regulatory pressure is accelerating investment in progressive web app architectures that function across connectivity gaps.
Subscription unbundling is fragmenting traditional all-in-one pricing. United States boutique operators are purchasing standalone scheduling modules from specialized vendors while sourcing billing and CRM from separate providers. This procurement pattern shifts vendor revenue from annual contracts toward usage-based API call metering. CrossFit affiliates and yoga studios in Texas and California clusters are driving this disaggregation fastest, prioritizing best-of-breed functionality over integrated convenience.
Gym Management Software Market Segmentation
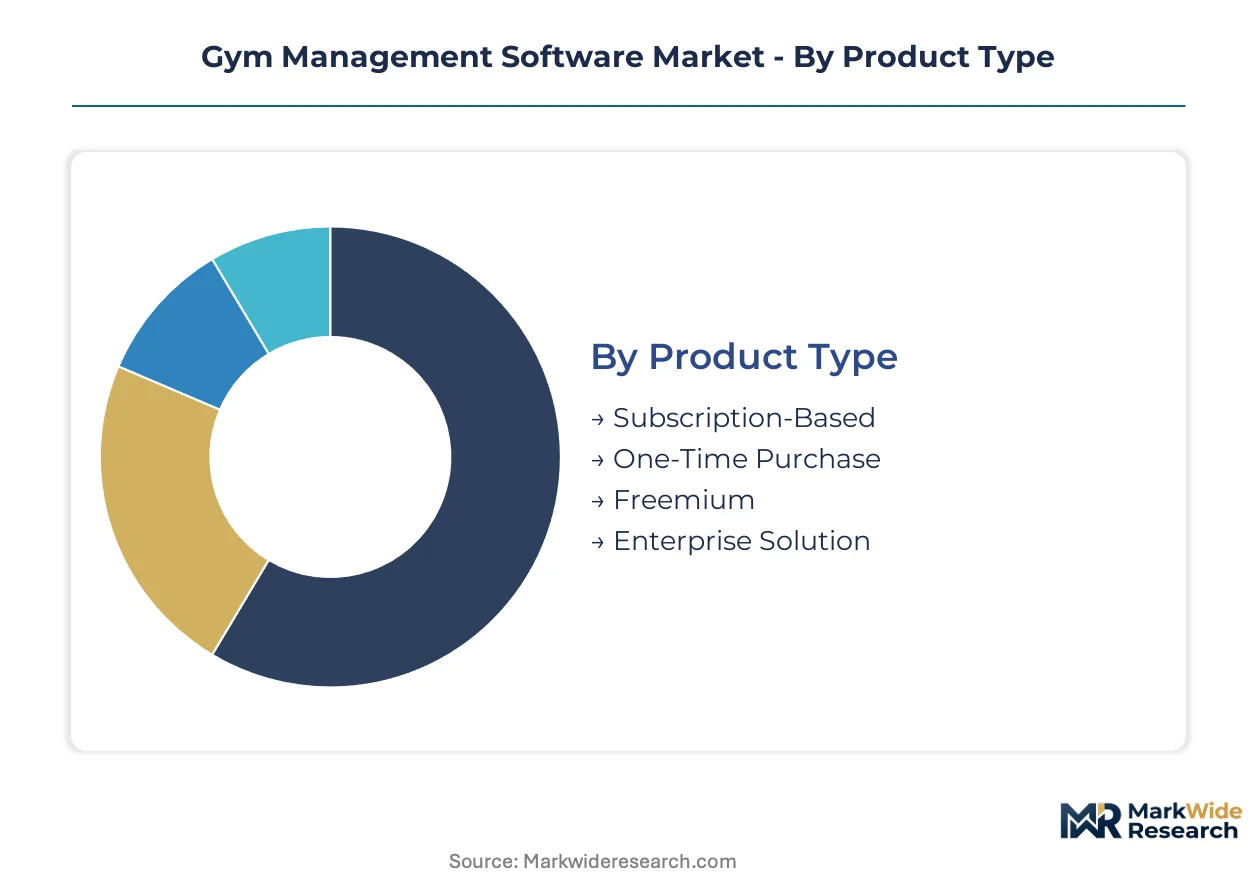
Segmentation in gym management software reveals how vendor business models align with operator scale and technical maturity. Pricing architecture and deployment preferences diverge sharply between boutique studios and franchise chains, creating distinct competitive battlegrounds.
Product Type:
Margin pools concentrate in recurring revenue streams that reduce customer acquisition costs and improve lifetime value predictability for vendors.
- Subscription-Based:Monthly or annual recurring licenses dominate vendor revenue models, with automatic feature updates and tiered service levels locking in multi-year commitments from growing operators. United States boutique fitness chains favor this structure for cash flow predictability and rapid scaling without capital expenditure spikes.
- Enterprise Solution:Custom-branded deployments with centralized multi-location reporting command premium pricing from franchise operators requiring SOC 2 Type II compliance and dedicated support SLAs. Large United States health club chains absorb these costs to maintain legacy ERP integration and proprietary member data architectures.
- One-Time Purchase:Perpetual licensing persists among budget-constrained independent studios preferring ownership over recurring obligations.
- Freemium:Limited-feature entry tiers convert solo trainers and micro-studios to paid plans through usage thresholds.
The dominant share belongs to Subscription-Based models, while Enterprise Solution pricing is climbing fastest as consolidation accelerates among multi-location operators.
End User:
Application intensity varies by facility type, with member volume and operational complexity dictating feature depth requirements.
- Fitness Centers:High-traffic facilities require robust scheduling engines, automated billing reconciliation, and real-time occupancy tracking across multiple workout zones. CrossFit boxes and HIIT studios in Texas and California clusters drive demand for white-label mobile apps with integrated wearable data streams.
- Health Clubs:Full-service operators with spa, pool, and childcare amenities need modular architectures connecting access control, point-of-sale, and CRM through unified member profiles. GDPR Article 9 compliance for biometric check-in systems shapes procurement priorities for European health club chains.
- Personal Trainers:Independent practitioners prioritize lightweight client management, payment processing, and nutrition tracking without facility overhead.
- Corporate Gyms:Employer-sponsored wellness facilities emphasize aggregate reporting and insurance integration over consumer-facing features.
Fitness Centers capture the largest addressable base, though Health Clubs are expanding their software budgets most aggressively as member experience becomes a retention priority.
Deployment:
Volume concentration tracks broadband infrastructure reliability and internal IT capability across operator segments.
- Cloud-Based:Browser-accessible platforms with automatic updates eliminate server maintenance burdens and enable rapid feature deployment. FCC broadband mapping requirements are pushing United States vendors toward offline-first architectures that cache data locally during connectivity gaps.
- Mobile App:Native iOS and Android experiences dominate member-facing interactions, with Bluetooth Low Energy integration for wearable synchronization and Apple HealthKit connectivity. European operators prioritize GDPR-compliant data residency through EU-based cloud regions.
- Hybrid:Split architectures persist among large chains with legacy on-premise ERP dependencies requiring middleware bridges.
- On-Premises:Self-hosted installations survive only in highly regulated environments with strict data sovereignty requirements.
Cloud-Based deployment holds the installed base majority, with Mobile App delivery gaining share fastest as member expectations shift toward smartphone-centric engagement.
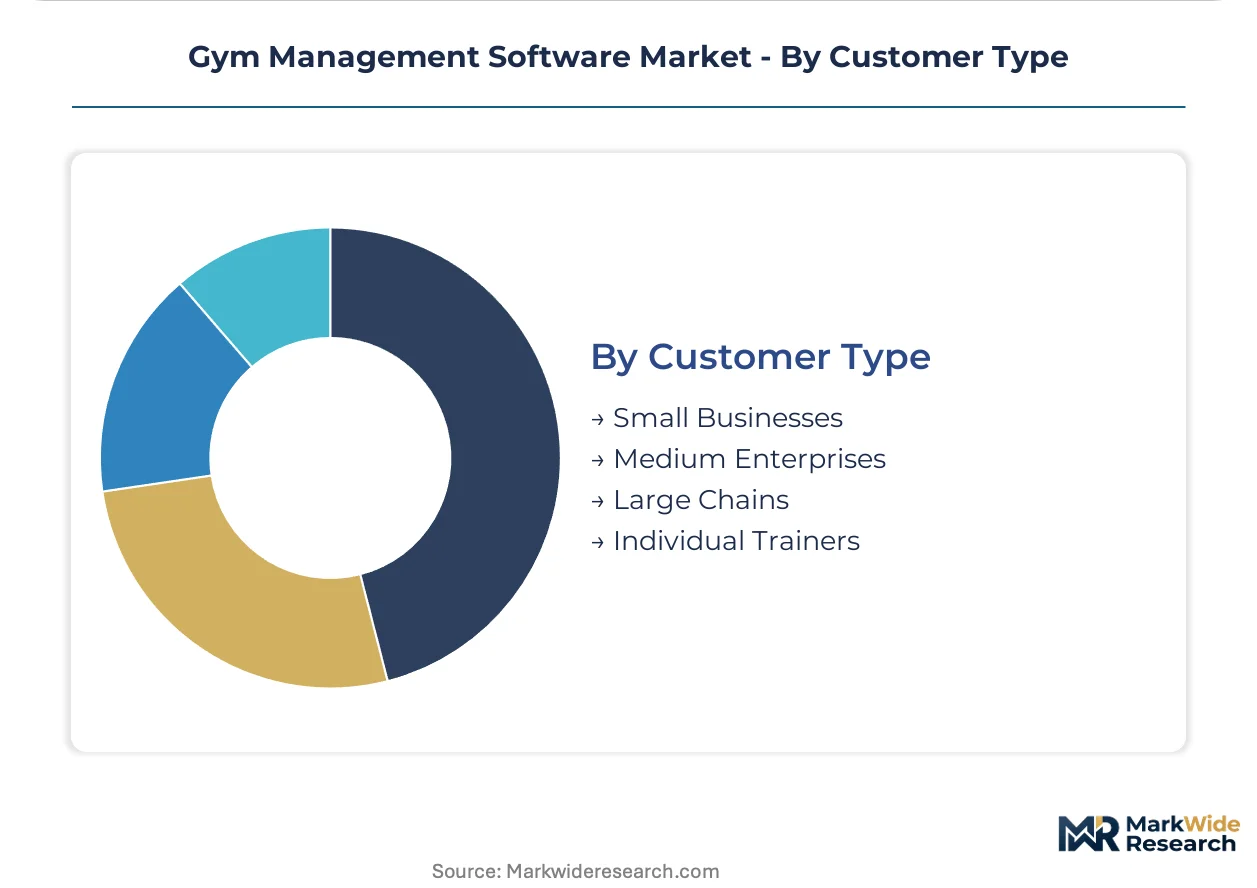
Customer Type:
Customer maturity determines willingness to trade configurability for implementation speed and ongoing support depth.
- Large Chains:Twenty-plus location operators demand API-first architectures, custom branding, and dedicated customer success teams with defined escalation paths. SOC 2 Type II certification gates procurement for United States franchise operators handling payment card data across hundreds of locations.
- Small Businesses:Single-location studios and independent trainers prioritize immediate usability over advanced analytics, accepting standardized workflows to minimize training overhead. India's tier-two city gym operators in this segment respond to sub-$10 monthly pricing tiers aligned with emerging market margins.
- Medium Enterprises:Regional chains with three to fifteen locations balance growth tooling against administrative simplicity.
- Individual Trainers:Solopreneurs require minimal viable feature sets with mobile-first design and frictionless payment collection.
Large Chains generate disproportionate revenue per account, while Small Businesses are expanding their aggregate seat count most rapidly as fitness entrepreneurship proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where franchise chains absorb premium enterprise tiers, while Indian tier-two operators compress vendor margins below ten dollars monthly. This asymmetry shapes regional deployment strategies and feature roadmaps across vendor portfolios.
United States
Boutique fitness proliferation in Texas and California clusters drives modular software procurement from specialized vendors. FCC broadband infrastructure mapping mandates offline-first mobile architectures for studios in connectivity-underserved census tracts. CrossFit affiliates in Austin and HIIT studios in Los Angeles deploy white-label apps with integrated wearable data streams.
Germany
GDPR Article 9 health data processing requirements shape biometric check-in system investments across health club chains. CE marking pathways for heart-rate monitoring kiosks create certification barriers for non-EU vendors. Fitness operators in Bavaria and North Rhine-Westphalia prioritize ISO 27001-certified platforms with EU-based cloud data residency.
United Kingdom
Corporate wellness program expansion drives demand for aggregate reporting and insurance integration capabilities. The Information Commissioner's Office enforces strict biometric data handling protocols for gym access systems. London and Southeast England health clubs lead adoption of AI-driven churn prediction models trained on attendance pattern data.
India
Digital payment acceleration in tier-two cities enables sub-dollar daily software pricing for emerging gym operators. The Reserve Bank of India regulates recurring payment mandates that affect billing system architecture. Fitness entrepreneurs in Maharashtra and Karnataka deploy lightweight mobile-first platforms with frictionless UPI integration.
Australia
Therapeutic Goods Administration oversight of medical-adjacent fitness devices influences hardware-software bundle procurement. Regional gym chains prioritize cloud-native deployment to eliminate server maintenance across dispersed locations. New South Wales and Victoria operators lead adoption of edge computing nodes for unreliable rural internet environments.
Gym Management Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap. The vendor base fragments across specialized boutiques serving CrossFit affiliates and full-stack platforms targeting multi-location franchise chains. Three strategic archetypes dominate: mobile-first design specialists, API-heavy integration platforms, and vertical workflow optimizers. Competitive moves concentrate on geographic expansion into emerging markets and portfolio diversification through embedded finance capabilities.
Within the vertical workflow tier, Zen Planner and Wodify exemplify specialized positioning for functional fitness segments. Mindbody anchors the integration-heavy archetype with extensive third-party marketplace connectivity. Virtuagym occupies a position as the mobile-first design representative competing aggressively for European operator attention. These three companies collectively illustrate how vendor specialization maps to distinct customer maturity segments and geographic priorities.
| Leading Market Players |
|---|
| Zen Planner |
| Wodify |
| Mindbody |
| Virtuagym |
| Perfect Gym |
| Glofox |
| 1club |
| GymMaster |
| PushPress |
| Others |
Value Chain & Pricing Dynamics
Ninety-day SOC 2 Type II audit cycles compress vendor pricing power by delaying enterprise procurement access, while cloud-native deployment eliminates server refresh inventory burdens that once anchored perpetual license premiums. Subscription pricing now dominates as operators trade capital expenditure for operational flexibility, though customization premiums persist for multi-location chains demanding white-label architectures.
Pricing Analysis
The customization-premium spread between configured enterprise deployments and standard SaaS tiers spans three-to-five-fold in annual contract value. Subscription-based SaaS pricing dominates vendor revenue models, with automatic updates and tiered service levels locking in multi-year commitments. Price differentiation hinges on SOC 2 certification grade and white-label customization depth. Cost compression in the mid-tier is intensifying because boutique studios unbundle functionality across specialized vendors. Small businesses in India's tier-two cities exhibit the highest price sensitivity, while United States franchise chains absorb premium pricing for centralized reporting and dedicated support SLAs.
Supply Chain Analysis
Inbound logistics costs for biometric hardware components face volatility through Shenzhen-to-Los Angeles container lane congestion and semiconductor fab capacity constraints. Software development labor concentrates in the United States, India, and Poland, with European GDPR compliance engineering clustering in Germany and the Netherlands. Raw material dependencies include cloud compute credits, payment processor API access, and heart-rate sensor modules. Single-source vulnerability runs through Stripe and Square dominance in United States billing integrations. Distribution runs through direct vendor sales teams for enterprise accounts and self-service digital channels for small business acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-stack developer scarcity in fitness-technology segments is constraining vendor engineering velocity and inflating compensation costs beyond bootstrapped startup reach. This talent gap favors platforms that automate routine coding through low-code configuration and API-first architectures.
For Market Incumbents: Fortify market position by deepening vertical integration into payment processing to reduce Stripe API dependency risk, and by accelerating SOC 2 Type II certification pipelines to capture enterprise procurement cycles ahead of cloud-native challengers. Incumbents must also defend against modular unbundling by boutique operators through best-of-breed feature parity in scheduling and wearable integration. For New Entrants and Emerging Players: CE marking fast-track pathways for biometric check-in kiosks unlock first-mover certification advantages in European health club procurement. White-space targets include India's tier-two cities where sub-$10 monthly pricing aligns with emerging operator margins, and CrossFit affiliate segments in Texas and California demanding specialized workflow tools. A mobile-first go-to-market angle with frictionless UPI integration captures Indian digital payment acceleration. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy ERP vendors with stranded fitness-software assets requiring cloud migration investment. Long-term viability across the analysis window favors API-heavy platforms with embedded finance capabilities over pure workflow tools. The acquisition archetype to prioritize is mobile-first design specialists with European GDPR-compliant data residency. The signal to watch is boutique studio consolidation into regional chains demanding enterprise-tier functionality.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable wearable synchronization and payment processor connectivity for United States operators. |
| Geographic Expansion | Sub-$10 pricing tiers in Indian tier-two cities capture digital payment acceleration among emerging gym entrepreneurs. |
| Acquisition of Specialist Firm | Biometric hardware vendors with CE marking pathways unlock European health club procurement advantages. |
| Product Launch | Offline-first mobile architectures address FCC broadband mapping requirements for connectivity-underserved studios. |
| Strategic Partnership | Embedded finance capabilities with banking-as-a-service providers create vertically integrated fitness platforms. |
Study Parameters
Desk research of SEC filings, App Annie mobile engagement data, and hyperscaler capex disclosures preceded structured interviews with gym software CTOs, boutique studio owners, health club procurement directors, and payment processor integration specialists. Primary fieldwork combined with secondary validation from FCC broadband infrastructure reports and GDPR regulatory guidance documents. Bottom-up sizing of vendor revenue tiers triangulated against top-down fitness operator software spend estimates.
Variance decomposition across deployment models, organization size tiers, vertical specialization, and regional adoption patterns shaped the analytical framework. Segmentation dimensions modeled include cloud-native versus hybrid architectures, single-location versus multi-location operator scale, and United States versus European regulatory compliance clusters. CAGRs were derived from attendance pattern data trends and software budget expansion rates among boutique fitness chains. Industry-specific forecast inputs incorporated wearable device penetration curves and digital payment adoption velocities in emerging markets.
Decision-makers should treat outputs as directional under assumptions of continued cloud migration and API standardization; material deviation in legacy ERP retention rates or biometric hardware regulatory classification would warrant model refresh. Forecasts reflect base-case assumptions of steady boutique studio proliferation and stable payment processor concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Web Framework Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Europe CMMS Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Discount Management Software Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Global Forestry Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Content Marketing Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Statistics Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market