
 Hermetic Food Grain Storage Market | 2026-2036
Hermetic Food Grain Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hermetic Food Grain Storage Market Outlook
ISO 9001 certification is unwinding competitive access across the hermetic storage supply chain, filtering out fabricators lacking documented quality management systems. GrainPro leverages vertical integration from resin sourcing to finished bag production across Southeast Asian markets. Ecotact anchors its position through R&D intensity in multilayer polyethylene formulations that block oxygen transmission. Silo Bag India Private Limited dominates domestic channel control through exclusive distributor networks in Maharashtra and Punjab.
Hermetic food grain storage denotes sealed containment systems engineered to maintain modified internal atmospheres, typically employing multilayer polymer laminates with oxygen transmission rates below 5 cc/m²/day to suppress insect respiration and mold proliferation. The technology's primary commercial purpose centers on eliminating pesticide residues while extending germination viability and nutritional shelf life for stored cereals and pulses. Grain bags command the largest volume share among product types due to low capital requirements for smallholder adoption, though controlled atmosphere silos capture disproportionate margin pools from commercial grain traders. Passive technology leads unit shipments across developing markets, while active systems with automated sensors represent the fastest-expanding segment among food processors seeking real-time inventory monitoring.
The Food Safety and Standards Authority of India enforces moisture content ceilings and structural integrity standards for commercial grain warehouses, directly shaping product specifications for hermetic system manufacturers serving the subcontinent. Kenya's Agriculture and Food Authority mandates phytosanitary certification for imported storage equipment, creating compliance barriers that favor established suppliers with in-country testing partnerships. Stakeholders must monitor evolving national grain reserve policies and subsidy structures, as government procurement programs increasingly specify hermetic performance benchmarks that will determine vendor qualification and contract eligibility.
Market Dynamics
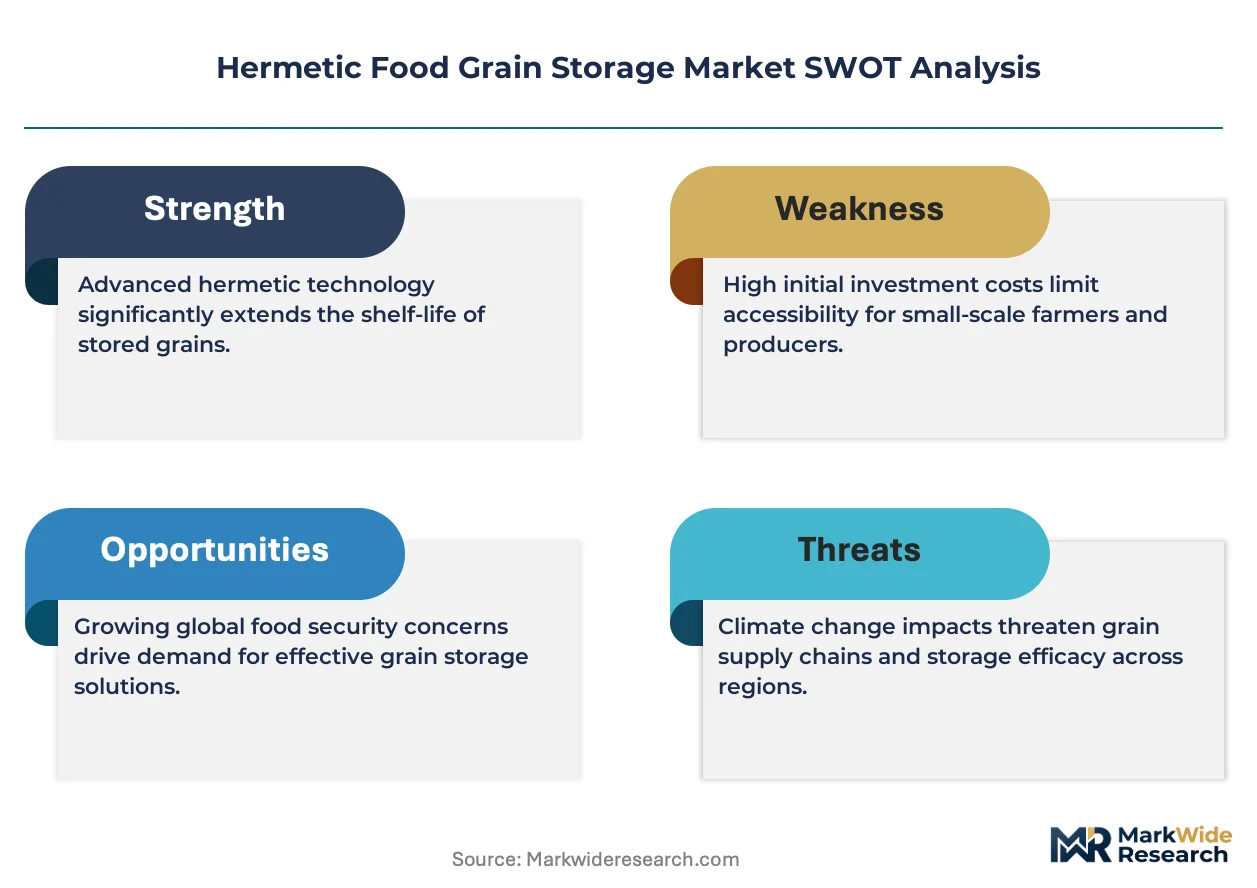
ISO 9001 certification is filtering fabricators lacking documented quality management systems, concentrating supply among vertically integrated producers with captive resin sourcing and in-house multilayer extrusion capabilities.
Growth Catalysts
- FSSAI moisture protocols:India's Food Safety and Standards Authority mandates stricter moisture control ceilings for commercial grain warehouses, forcing warehouse operators toward certified hermetic systems that guarantee compliance.
- Smallholder cooperatives:Kenya's Rift Valley agricultural collectives are pooling capital for bulk procurement of hermetic bags, creating concentrated demand nodes that attract distributor investment.
- Multilayer polyethylene R&D:Advances in oxygen barrier formulations below 5 cc/m²/day are extending germination viability without pesticide residues, opening organic export channels for stored commodities.
Market Restraints
- Petrochemical input volatility:Resin price swings for linear low-density polyethylene directly compress margins for bag fabricators without backward integration into polymer production.
- Import certification barriers:Kenya's Agriculture and Food Authority mandates phytosanitary certification for imported storage equipment, creating compliance timelines that favor established in-country testing partnerships.
- Passive technology ceiling:Bags without sensor integration cannot meet food processor requirements for real-time inventory monitoring, capping addressable market share in premium segments.
Strategic Opportunities
- Active system convergence:Automated sensor integration with passive hermetic bags is creating hybrid offerings for commercial grain traders seeking real-time atmospheric monitoring without full silo investment.
- Government procurement programs:National grain reserve policies in Sub-Saharan Africa are increasingly specifying hermetic performance benchmarks that determine vendor qualification for subsidized distribution schemes.
- Direct-to-cooperative channels:Bypassing traditional agricultural input distributors through mobile-enabled bulk ordering platforms is reducing customer acquisition costs in Kenya's smallholder-dense highlands.
Industry Challenges
- ISO 9001 documentation burden:Smaller fabricators face six-to-twelve-month certification timelines that delay contract eligibility for government tenders and export orders.
- Multilayer extrusion skill scarcity:Specialized technicians capable of calibrating coextrusion lines for sub-5 cc/m²/day oxygen transmission rates command premium wages that strain mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hermetic Food Grain Storage Market |
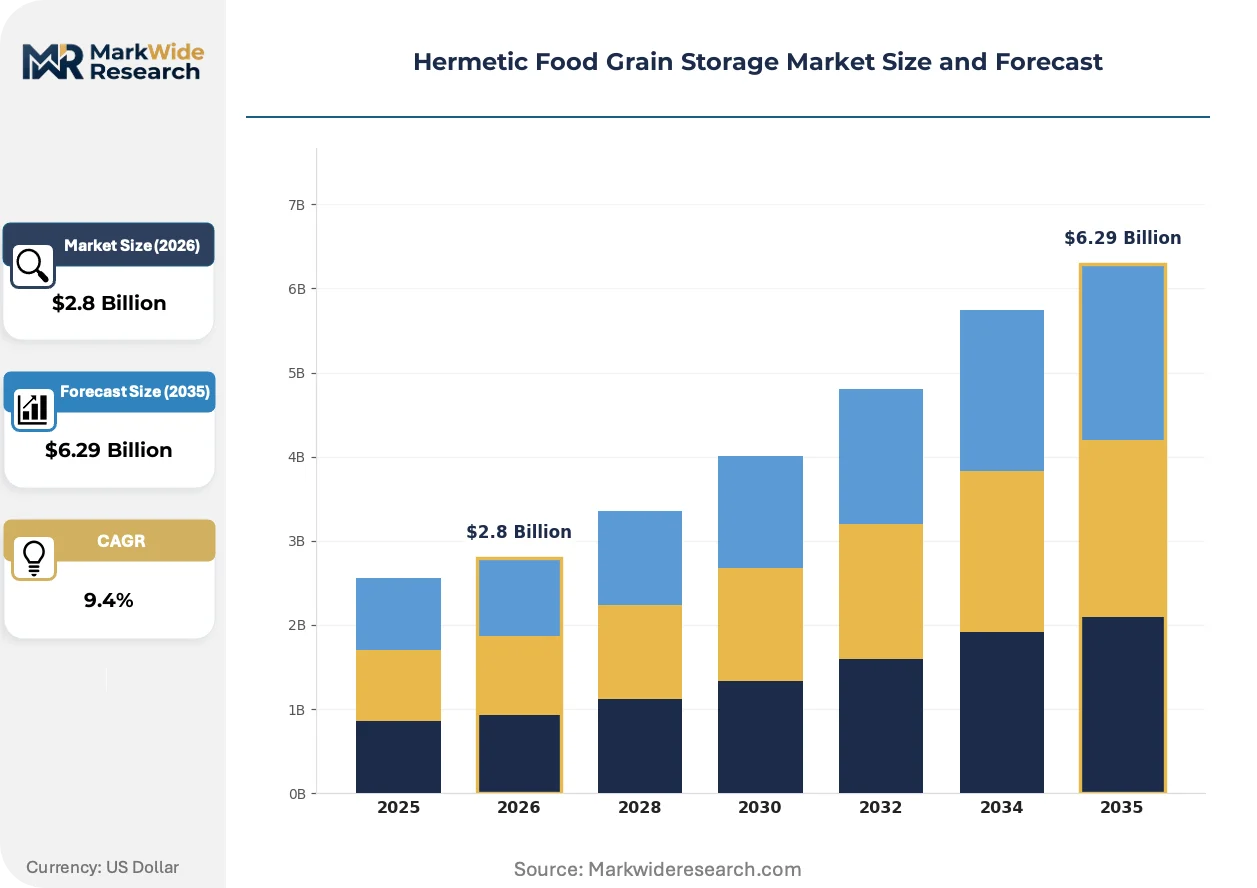
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain Bags, Silos, Containers, Bins End User: Agricultural Producers, Food Processors, Retailers, Importers Material: Plastic, Metal, Fabric, Composite Technology: Active, Passive, Vacuum, Controlled Atmosphere |
| Companies Covered | Ecotact, Silo Bag India Private Limited, GrainPro, Plastika Kritis, Big John Manufacturing, Storezo, Vestergaard, Rishi FIBC Solutions, Swisspack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hermetic Food Grain Storage Market Strategic Shifts
Sensor-enabled hermetic systems are compressing the information gap between stored inventory and commercial decision-makers, while regulatory mandates in major grain economies accelerate specification tightening for moisture and oxygen control.
Multilayer polymer laminates with embedded RFID tracking are decomposing the traditional separation between physical storage and digital inventory management. Large-scale grain traders in Maharashtra and Punjab are piloting these hybrid bags for wheat and rice lots destined for export. The technology is decomposing reliance on manual sampling and third-party warehouse inspection, compressing working capital cycles for commodity financiers.
India's FSSAI has extended structural integrity standards from food processing facilities into commercial grain warehousing, mandating documented moisture control protocols that hermetic systems must certify against. Warehouse operators in Haryana and Uttar Pradesh are retrofitting facilities to meet these specifications ahead of enforcement deadlines. The regulation is reshaping supplier qualification criteria, with FSSAI-recognized testing laboratory partnerships becoming a prerequisite for contract awards.
Smallholder cooperatives are consolidating procurement authority previously dispersed across individual farm households, creating volume nodes that attract direct manufacturer engagement. Kenya's Rift Valley cooperative unions now negotiate hermetic bag purchases in container-load quantities, bypassing fragmented retail agricultural input channels. This concentration is visible across Ethiopia's Amhara region and Tanzania's Southern Highlands, where cooperative-managed grain bulking points are becoming the primary customer interface for storage technology vendors.
Hermetic Food Grain Storage Market Segmentation
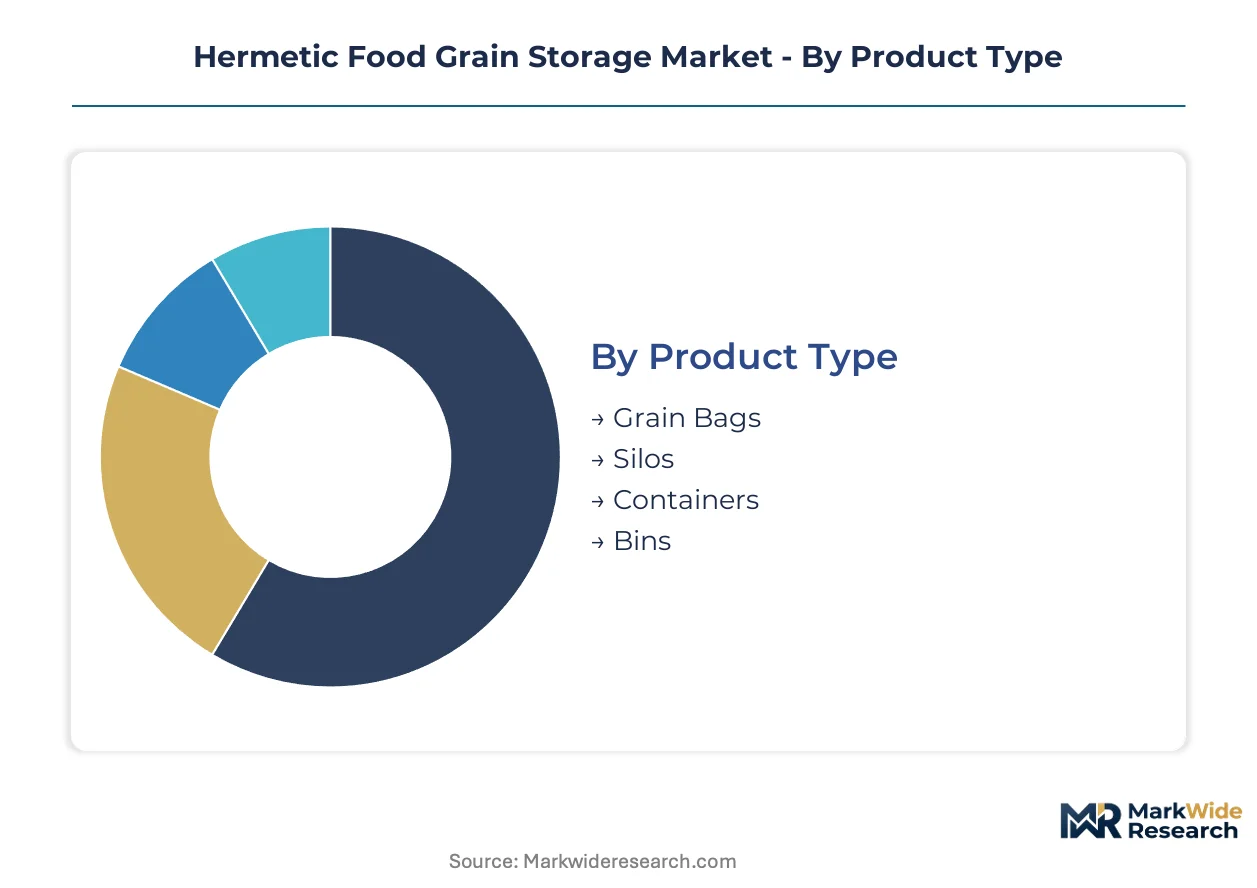
Hermetic storage markets fragment across capital intensity gradients, with low-cost bag systems serving smallholder density and engineered silos capturing commercial trader margins. Material selection and technology tier determine compliance eligibility against tightening FSSAI and phytosanitary mandates.
Product Type:
Margin pools concentrate in silo installations for commercial grain traders, while unit volume flows through bag systems serving cooperative procurement.
- Silos:Engineered steel or concrete structures with controlled atmosphere capability command premium pricing from Maharashtra and Punjab warehouse operators retrofitting for FSSAI moisture compliance. Commercial grain traders in these states specify silo capacity for export-bound wheat and rice lots.
- Grain Bags:Multilayer polyethylene laminates with sub-5 cc/m²/day oxygen transmission rates dominate procurement volumes across Kenya's Rift Valley cooperative unions. Smallholder collectives pool capital for container-load purchases, bypassing fragmented retail channels.
- Containers:Standardized shipping-compatible units serve import-export logistics chains with hermetic sealing for transoceanic transit.
- Bins:Intermediate-capacity steel or polymer vessels fill the gap between bag flexibility and silo permanence for mid-scale agricultural producers.
Silos hold installed capacity. Grain bags are rotating up the share rankings.
End User:
Procurement authority is shifting from individual farm households toward consolidated cooperative structures in high-density smallholder regions.
- Agricultural Producers:Kenya's Rift Valley cooperative unions and Ethiopia's Amhara region bulking points now negotiate direct with manufacturers, concentrating previously dispersed demand. These entities specify hermetic performance benchmarks for subsidized distribution schemes.
- Food Processors:Automated sensor integration requirements from this segment are pulling passive bag manufacturers toward hybrid active-passive offerings. Real-time atmospheric monitoring specifications favor controlled atmosphere silos with telemetry capability.
- Retailers:Urban grain merchants in Indian metropolitan markets source hermetic containers for inventory holding between harvest cycles.
- Importers:Cross-border grain traders specify phytosanitary-certified storage equipment to satisfy Kenya's Agriculture and Food Authority import mandates.
Food processors are climbing the fastest as a demand segment. Agricultural producers retain volume dominance.
Material:
Polymer formulation R&D intensity determines oxygen barrier performance and organic export channel eligibility.
- Plastic:Multilayer polyethylene laminates with embedded RFID tracking are decomposing manual inventory management for Maharashtra and Punjab wheat exporters. Coextrusion capabilities for sub-5 cc/m²/day transmission rates command technician premiums that strain mid-cap fabricators.
- Metal:Galvanized steel silo construction serves permanent installation requirements for commercial grain warehouses in Haryana and Uttar Pradesh facing FSSAI structural integrity deadlines.
- Fabric:Woven polymer composites offer intermediate durability for seasonal storage cycles among Tanzania's Southern Highlands cooperatives.
- Composite:Hybrid material systems combining polymer barriers with structural reinforcement target mobile deployment scenarios for emergency grain reserve programs.
Plastic commands unit shipments. Metal retains margin concentration in commercial installations.
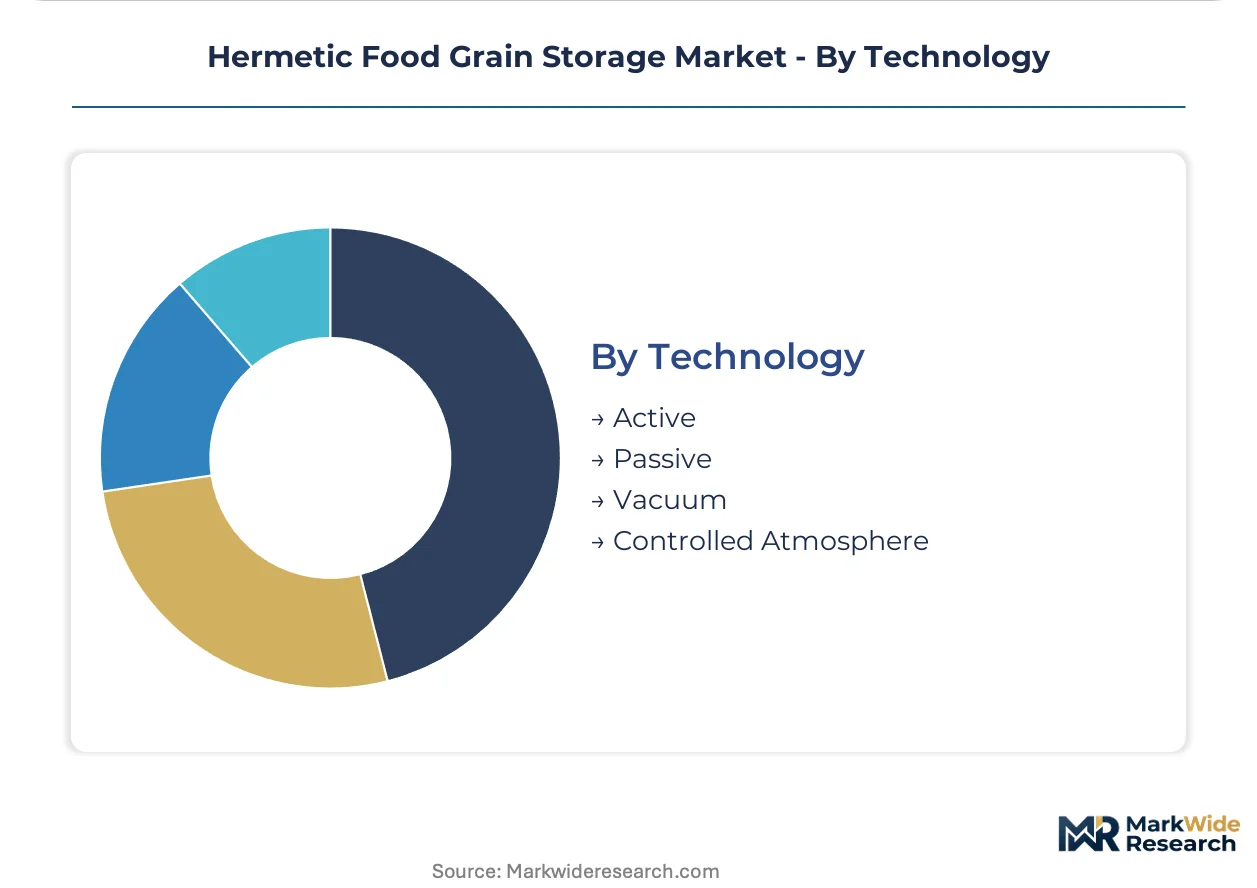
Technology:
Passive systems lead developing market penetration, while active technology opens premium segments through real-time monitoring capability.
- Passive:Sealed containment without powered components dominates Kenya and Ethiopia smallholder adoption due to zero energy requirements and minimal capital outlay. These systems rely entirely on multilayer polymer oxygen barriers for insect suppression.
- Active:Automated sensor networks with telemetry integration are expanding most quickly among food processors and commercial traders seeking inventory visibility. Hybrid offerings combine passive hermetic bags with bolt-on monitoring modules.
- Vacuum:Mechanical oxygen evacuation systems serve high-value seed preservation and germination viability extension for specialty crop producers.
- Controlled Atmosphere:Precision gas mixture management targets commercial silo installations for large-scale grain reserve operations with nitrogen or carbon dioxide injection capability.
Passive technology anchors installed base. Active systems are gaining share fastest in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mombasa-Nairobi Standard Gauge Railway underwrites Kenya's centrality in East African grain logistics, connecting Rift Valley production zones to port export capacity. India's Dedicated Freight Corridors link Punjab and Haryana warehouse clusters to container terminals at JNPT and Mundra. Brazil's Ferrovia Norte-Sul integrates Mato Grosso soy belts with Atlantic export terminals.
Kenya
Rift Valley cooperative unions pool capital for container-load hermetic bag procurement, bypassing fragmented retail channels. Kenya's Agriculture and Food Authority mandates phytosanitary certification for imported storage equipment, favoring established suppliers with in-country testing partnerships. Nairobi-based distributors now maintain direct technical service teams at Eldoret and Nakuru bulking points.
India
Maharashtra and Punjab warehouse operators retrofit facilities to meet FSSAI moisture control ceilings ahead of enforcement deadlines. India's Food Safety and Standards Authority extends structural integrity standards from processing facilities into commercial grain warehousing. Haryana's Karnal and Panipat districts concentrate silo installation activity for wheat export lots.
Brazil
Mato Grosso commercial grain traders specify hermetic performance benchmarks for soybean and corn reserve operations. ANVISA residue monitoring protocols for export-bound commodities drive adoption of pesticide-free storage systems. Sorriso and Lucas do Rio Verde municipalities anchor bag procurement volumes for cooperative-managed production.
Ethiopia
Amhara region cooperative-managed bulking points negotiate direct manufacturer engagement for hermetic storage units. The Ethiopian Agricultural Transformation Agency subsidizes post-harvest technology distribution through designated vendor qualification programs. Bahir Dar and Gondar logistics corridors concentrate demand aggregation for smallholder collectives.
United States
Midwest grain elevators evaluate sensor-enabled hermetic systems for identity-preserved specialty crop segments. USDA warehouse licensing requirements shape moisture documentation protocols for commercial storage operators. Iowa's Council Bluffs-Omaha corridor and Illinois' Peoria-Champaign cluster pilot RFID-embedded bag systems for organic export channels.
Hermetic Food Grain Storage Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with ISO 9001 documentation separating contract-eligible fabricators from informal suppliers. The supply base concentrates among resin-integrated producers with captive multilayer extrusion capabilities and regional distributors with FSSAI-recognized laboratory partnerships. Three archetypes dominate: vertically integrated polymer compounders, cooperative-focused channel specialists, and sensor-technology integrators. Capacity expansion and strategic certification partnerships constitute the dominant competitive moves as vendors position for government tender eligibility.
Among Asia-Pacific fabricators, GrainPro and Silo Bag India Private Limited exemplify divergent archetypes. GrainPro occupies a position consistent with integrated resin-to-finished-product operations across Southeast Asian markets. Silo Bag India Private Limited anchors domestic channel control through exclusive distributor networks in Maharashtra and Punjab. Ecotact represents the R&D-intensive formulation specialist archetype, with positioning aligned to multilayer polyethylene barrier development. These three entities collectively illustrate the competitive spectrum spanning upstream integration, distribution capture, and material science specialization.
| Leading Market Players |
|---|
| Ecotact |
| Silo Bag India Private Limited |
| GrainPro |
| Plastika Kritis |
| Big John Manufacturing |
| Storezo |
| Vestergaard |
| Rishi FIBC Solutions |
| Swisspack |
| Others |
Value Chain & Pricing Dynamics
FSSAI moisture control mandates gate both supplier qualification and price differentiation in India's hermetic storage market, concentrating contract eligibility among ISO-certified fabricators while compressing margins for uncertified competitors. Certification tier creates immediate price stratification between FSSAI-recognized laboratory partners and informal suppliers lacking documented quality systems.
Pricing Analysis
Certification level creates the primary spread between premium FSSAI-compliant systems and economy-grade alternatives. Pricing stratifies across FSSAI-recognized, ISO-certified, and uncertified tiers, with laboratory partnership status commanding material premiums from Maharashtra warehouse operators. Cost compression in the economy tier intensifies due to resin price volatility for linear low-density polyethylene. Agricultural cooperatives in Kenya's Rift Valley exhibit highest price sensitivity, while Indian commercial grain traders prioritize compliance over unit cost.
Supply Chain Analysis
Container availability on Asia-East Africa trade lanes constrains inbound logistics for Kenyan distributor networks, extending procurement timelines for Rift Valley cooperative orders. Resin supply concentrates in Thailand, Saudi Arabia, and Singapore, with multilayer extrusion equipment sourcing from Germany and Italy. Single-source vulnerability in specialized coextrusion technician labor strains mid-cap fabricator expansion. Distribution runs through exclusive state-level distributor networks in Maharashtra and Punjab, supplemented by direct manufacturer engagement at Kenyan bulking points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI structural integrity deadlines for commercial grain warehousing constitute a regulatory inflection accelerating market consolidation among certified suppliers. Sensor-enabled hybrid systems are disrupting traditional passive bag segments.
For Market Incumbents: Fortify backward integration into polymer compounding to insulate margins from resin volatility, while deepening FSSAI-recognized laboratory partnerships ahead of enforcement deadlines. Emerging sensor-technology integrators threaten premium segment capture. Certification investment and captive resin sourcing represent critical defensive levers. For New Entrants and Emerging Players: After-sales technical service gaps at Kenyan bulking points present immediate white-space opportunity, as established suppliers under-serve cooperative-managed grain points with direct technical support. Ethiopia's Amhara region cooperative procurement concentration offers the most penetrable geography. Mobile-enabled bulk ordering platforms provide viable go-to-market angle for bypassing traditional distributor markups. For Investors and Strategic Acquirers: Kenya's Agriculture and Food Authority phytosanitary certification requirements reshape the acquisition landscape, privileging targets with established in-country testing infrastructure over pure manufacturing plays. Long-term viability centers on regulatory compliance capabilities rather than production scale alone. Acquisition target archetype: mid-cap fabricators with backward resin integration and existing African distributor relationships. Signal to watch: government tender specification shifts toward active sensor integration mandates.| Strategic Initiative | Industry Significance |
|---|---|
| FSSAI Laboratory Partnership | Recognized testing partnerships unlock contract eligibility for Indian warehouse retrofit tenders. |
| Sensor Module Integration | Hybrid passive-active offerings capture food processor demand for real-time atmospheric monitoring. |
| Resin Compounding Capacity | Captive polymer production insulates margins from linear low-density polyethylene price swings. |
| Direct Cooperative Channel | Mobile-enabled bulk ordering reduces customer acquisition costs in Kenya's Rift Valley highlands. |
| Multilayer Extrusion Scale-Up | Sub-5 cc/m²/day oxygen barrier capability opens organic export channels for stored commodities. |
Study Parameters
Desk research of trade customs data, FSSAI regulatory filings, and cooperative procurement records preceded structured interviews with grain warehouse operators, agricultural cooperative managers, polymer extrusion technicians, and distributor network heads. Primary fieldwork across Maharashtra, Punjab, Kenya's Rift Valley, and Ethiopia's Amhara region validated secondary estimates. Bottom-up unit shipment analysis triangulated against top-down market value reconstruction.
Variance decomposition across product type, technology tier, material formulation, and end-user concentration shaped analytical framework construction throughout the projection horizon. Segmentation modeling incorporated capital intensity gradients, certification compliance tiers, and regional cooperative density patterns. CAGRs derived from curve-fitting historical adoption trajectories against regulatory deadline schedules and infrastructure investment pipelines. Forecast inputs included FSSAI enforcement timeline assumptions and Standard Gauge Railway capacity expansion for East African logistics.
Forecasts assume regulatory continuity in India's FSSAI implementation and Kenya's Agriculture and Food Authority phytosanitary regimes; material policy shifts would require re-modeling. Commodity price volatility, cooperative procurement consolidation speed, and sensor technology cost curves represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
India Feed Amino Acids Market