
 Touchpad Market | 2026-2036
Touchpad Market Size, Share, and Industry Trends Forecast 2026-2036
Touchpad Market Analytics
Enterprise notebook procurement is consolidating around fewer tier-one OEMs, concentrating order volumes with suppliers capable of multi-million-unit annual contracts. Synaptics Incorporated leverages its force-sensing IP portfolio to secure premium-tier placements with top-tier laptop brands. ALPS ALPINE sustains dominant share in automotive center-console touch modules through dedicated production lines in Japan and Thailand. Goodix competes aggressively on capacitive controller cost, undercutting legacy vendors in Chromebook and education-segment bids.
A touchpad is a capacitive or resistive pointing device that translates finger position and pressure into cursor control through layered electrode grids bonded to glass or PET substrates, typically measuring 65–105 mm diagonally with resolution exceeding 1000 dpi. It serves as the primary human-machine interface in clamshell computers, vehicle infotainment systems, and medical equipment where space constraints preclude external mice. Capacitive touchpads lead unit volume due to their integration into consumer electronics, yet haptic feedback technology commands superior margin pools by eliminating mechanical click assemblies. Gesture recognition functionality is gaining fastest in automotive and home automation applications, where drivers and homeowners demand eyes-free control interfaces.
FCC electromagnetic-emission rules in the United States, CE marking requirements under EU RoHS and REACH frameworks, and China's GB standards for electronic-product safety collectively dictate touchpad shielding designs, material substitutions, and market-access timelines. Japan's METI energy-efficiency guidelines further constrain standby-power budgets for controllers in always-connected devices. Stakeholders must monitor evolving automotive-grade reliability standards and force-sensing patent landscapes to anticipate which technology combinations will secure next-generation design wins.
Market Dynamics
Notebook OEM procurement consolidation is concentrating annual contract volumes among suppliers capable of multi-million-unit force-sensing and haptic integration programs, compressing margins for mid-tier module vendors while rewarding tier-one players with dedicated foundry partnerships.
Growth Catalysts
- EU RoHS material mandates:Phased restrictions on hazardous substances in electronics are accelerating PET substrate and lead-free solder adoption across touchpad manufacturing lines.
- Automotive center-console digitization:Vehicle infotainment systems are replacing mechanical rotary controls with capacitive gesture panels, opening incremental demand pools outside traditional computing.
- China's GB electronic-safety standards:Domestic certification requirements for electronic-product safety are standardizing shielding designs that simplify export qualification for compliant manufacturers.
Market Restraints
- Indium tin oxide price volatility:Transparent conductor costs fluctuate with mining output from concentrated South American and Southeast Asian deposits, squeezing capacitive sensor margins.
- Foundry concentration in Taiwan and South Korea:Over 70 percent of advanced capacitive controller wafer capacity sits within earthquake and geopolitical exposure zones, creating supply interruption risk.
- Mechanical keyboard substitution:Gaming and workstation segments are reverting to precision mouse and trackball peripherals for tasks demanding pixel-level cursor accuracy.
Strategic Opportunities
- India education-technology procurement:Government tablet and Chromebook distribution programs are creating volume demand for cost-optimized capacitive controllers in price-sensitive segments.
- Force-sensing haptic convergence:Integration of pressure detection with localized vibration feedback eliminates physical button assemblies, enabling sealed industrial and medical device designs.
- Japan METI standby-power guidelines:Energy-efficiency mandates for always-connected devices are rewarding ultra-low-power controller architectures with preferential placement in premium notebook lines.
Industry Challenges
- Automotive-grade reliability certification:AEC-Q100 qualification timelines extend 18-24 months for capacitive modules, delaying revenue recognition for suppliers pivoting from consumer electronics.
- Patent thickets around multi-touch gesture IP:Licensing complexity from overlapping university and corporate force-sensing portfolios is inflating legal overhead for new market entrants.
- Legacy Windows driver compatibility:Backward support for older operating system versions fragments firmware development resources and extends validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Touchpad Market |
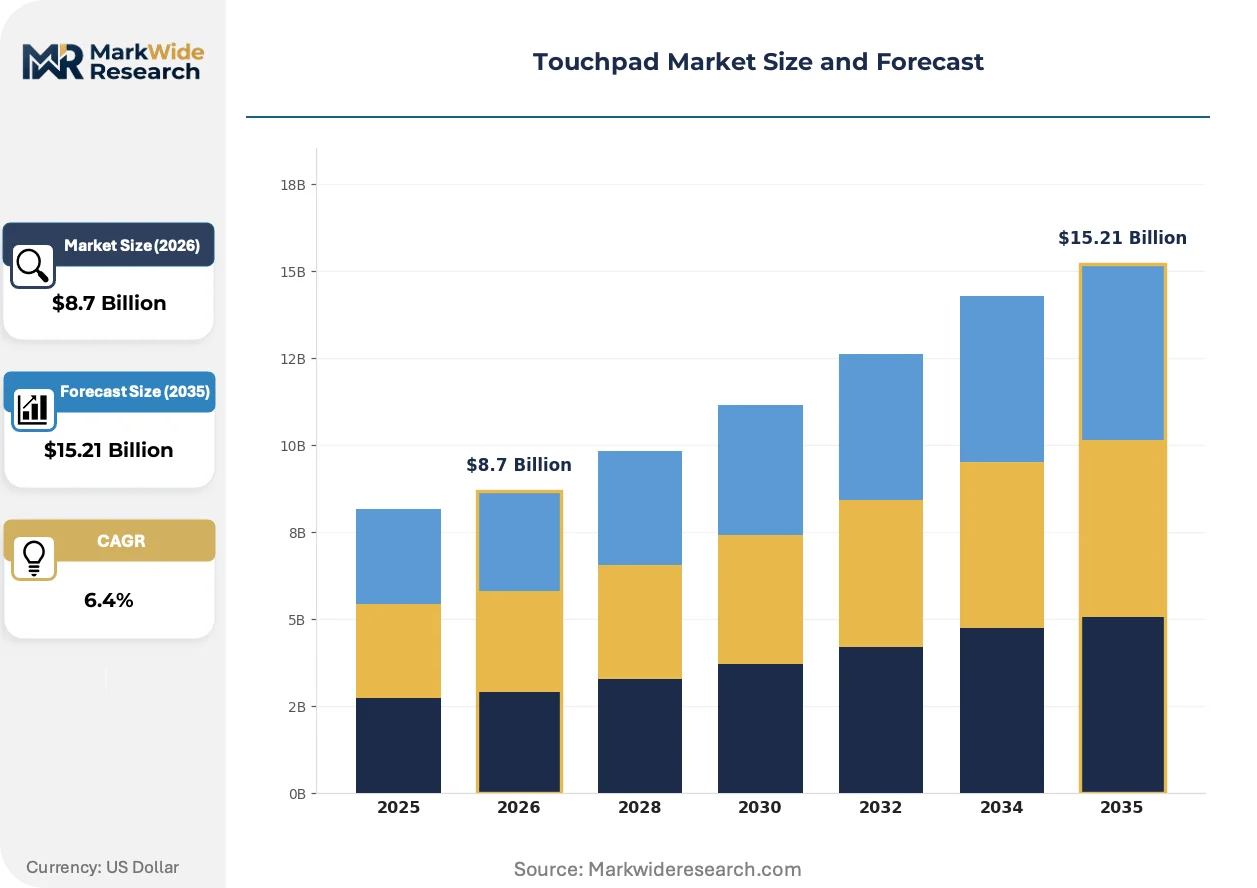
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Optical, Thermal Technology: Multi-Touch, Force Sensing, Gesture Recognition, Haptic Feedback End User: Consumer Electronics, Automotive, Healthcare, Industrial Automation Application: Gaming, Home Automation, Mobile Devices, Point-of-Sale |
| Companies Covered | Elan Microelectronics, Cirque Corporation, Synaptics Incorporated, Microchip Technology Inc., Interlink Electronics, Goodix, ALPS ALPINE, Digimore Electronics, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Touchpad Market Evolving Landscape
Force-sensing actuators and solid-state haptic engines are displacing mechanical click mechanisms across premium computing and automotive interfaces, compressing assembly complexity while raising performance expectations for tactile feedback fidelity.
Solid-state haptic feedback is rewriting the physical architecture of input devices. Piezoelectric actuators embedded beneath glass or PET surfaces generate localized vibration patterns that simulate button depression without moving parts. Automotive OEMs in Germany and Japan are adopting these modules for center-stack controls to achieve IP67 sealing ratings. The technology is compressing bill-of-materials line counts by eliminating dome switches and travel mechanisms.
EU REACH substance restrictions are forcing material substitutions across electrode manufacturing. Candidate list updates targeting persistent organic pollutants are phasing out specific photoresist chemistries and etchant formulations used in capacitive sensor patterning. Touchpad suppliers serving European notebook brands are reformulating production lines to maintain market access, with compliance costs flowing disproportionately to mid-volume contract manufacturers.
Enterprise fleet buyers are consolidating vendor relationships around suppliers offering multi-year total-cost-of-ownership guarantees. Large corporate procurement teams are displacing decentralized IT purchasing with centralized framework agreements that bundle hardware, firmware update subscriptions, and failure-rate warranties. This concentration is most visible in North American financial services and healthcare sectors where standardization reduces help-desk complexity across thousands of deployed units.
Touchpad Market Segmentation
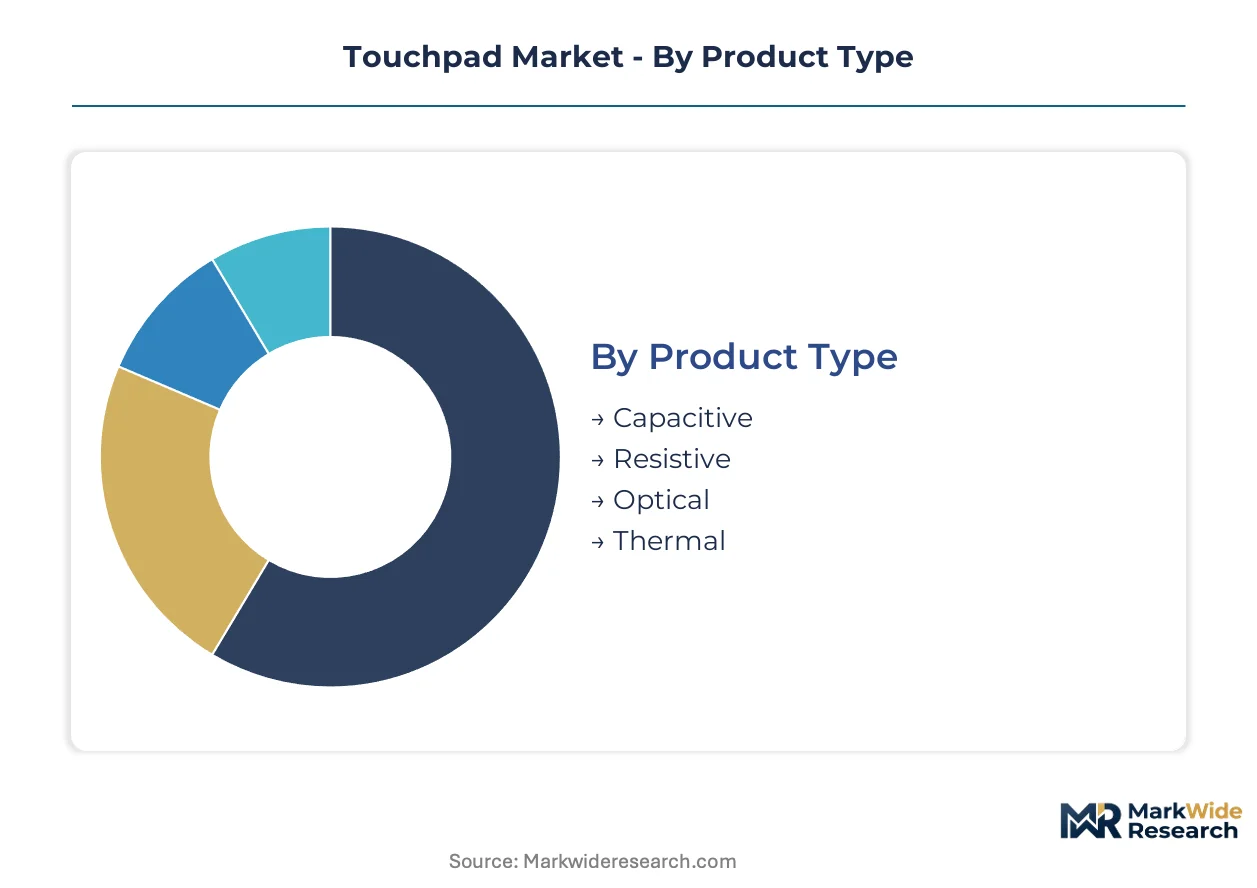
Touchpad procurement patterns diverge sharply across product architectures and end-use environments. Suppliers calibrate electrode density, controller firmware, and surface materials to match the precision, durability, and sealing requirements of each segment tier.
Product Type:
Capacitive sensor foundries in Taiwan and South Korea concentrate wafer output for high-volume notebook contracts, while resistive and specialty optical formats serve sealed industrial niches.
- Capacitive:Electrode grids etched on glass or PET substrates detect finger proximity through mutual capacitance changes. Notebook OEMs in the United States and Germany concentrate procurement here, driven by EU RoHS mandates eliminating hazardous etchants from legacy manufacturing lines.
- Resistive:Pressure-activated membrane stacks of ITO-coated polyester layers register contact through electrical resistance shifts. Demand concentrates in medical equipment and point-of-sale terminals across Japan and China, where cost sensitivity and stylus compatibility outweigh multi-touch performance requirements.
- Optical:Image sensors track finger position through infrared reflection patterns beneath transparent surfaces.
- Thermal:Heat differential detection enables glove-compatible operation in cold-storage logistics and outdoor kiosks.
Today's leader: Capacitive. Tomorrow's challenger: Optical.
Technology:
Controller architecture costs stratify sharply, with force-sensing ASICs commanding premium pricing against commodity multi-touch silicon.
- Multi-Touch:Two-finger scrolling and pinch-zoom algorithms embedded in controller firmware dominate unit economics across Chromebook and education tablet segments. Procurement in India and Indonesia gravitates toward this baseline capability, constrained by government tender price ceilings for mass-deployment programs.
- Force Sensing:Piezoelectric or strain-gauge arrays measure applied pressure to trigger contextual menus and simulate physical button depression. Automotive center-console modules from Germany and Japan integrate this technology to achieve IP67 sealing ratings while eliminating mechanical click assemblies.
- Gesture Recognition:Machine-learning-based pattern recognition enables eyes-free control in vehicle infotainment systems.
- Haptic Feedback:Localized vibration actuators beneath glass surfaces generate tactile button simulations without moving parts.
Multi-Touch captures present volume. Force Sensing captures future margin expansion.
End User:
Application durability requirements dictate substrate material selection and controller qualification timelines.
- Consumer Electronics:Clamshell notebooks and tablets drive annual procurement cycles with 12-18 month product refresh cadences. Supply contracts from Dell, HP, and Lenovo concentrate volumes with Synaptics and ALPS ALPINE, squeezing mid-tier controller vendors on price.
- Automotive:Center-stack and steering-wheel touch modules require AEC-Q100 qualification extending 18-24 months. Tier-1 suppliers in Germany and Japan secure long-term supply agreements with display integrators, locking out consumer-electronics specialists lacking automotive process certification.
- Healthcare:Sealed, disinfectant-resistant surfaces for medical carts and diagnostic equipment.
- Industrial Automation:Glove-compatible, EMI-hardened panels for factory-floor HMI terminals.
Consumer Electronics owns current revenue. Automotive owns the steepest expansion trajectory.
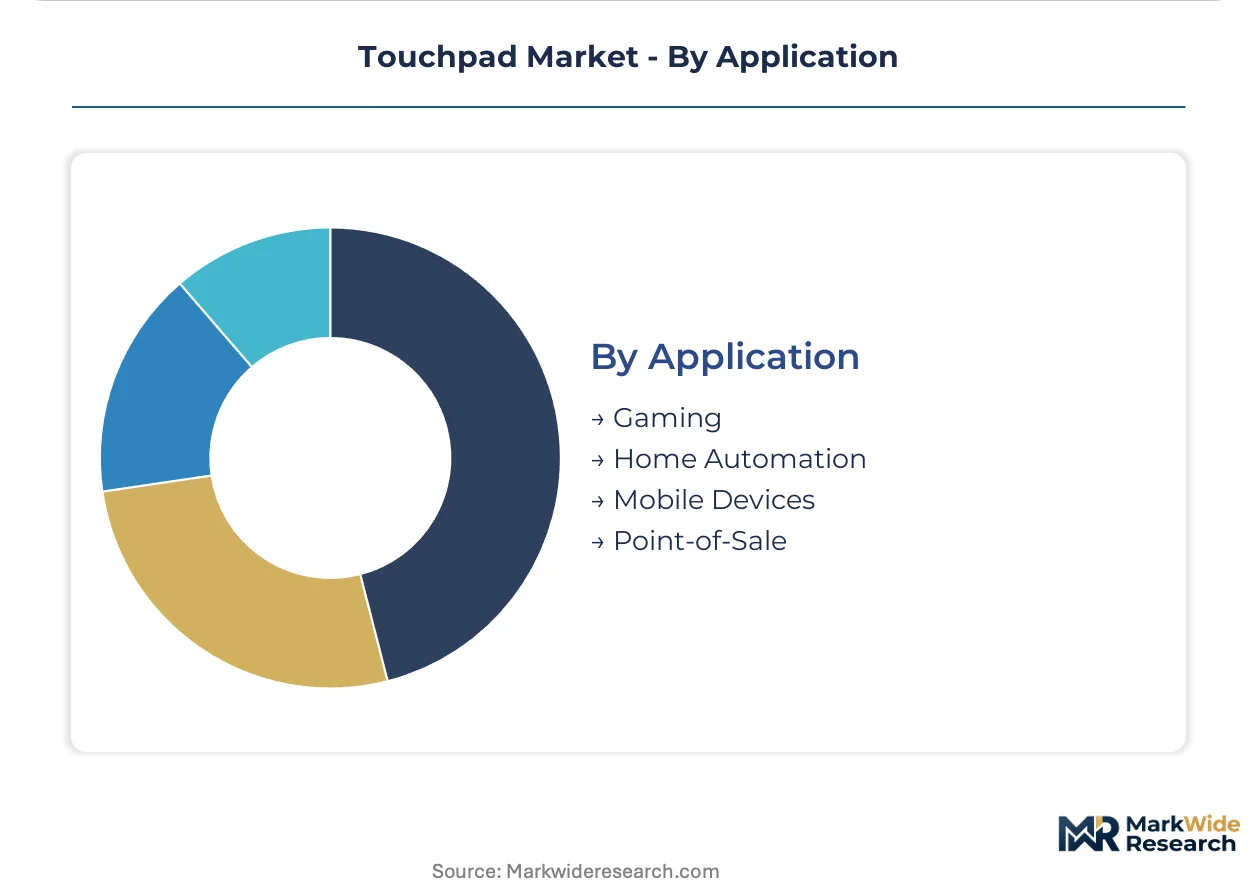
Application:
Input precision requirements fragment controller specifications across use cases.
- Gaming:High-polling-rate controllers with sub-millimeter tracking accuracy support competitive esports peripherals. Demand from South Korea and the United States concentrates with specialized mouse and trackpad OEMs, displacing standard notebook modules for tournament-grade equipment.
- Mobile Devices:Ultra-thin stack-ups below 1.2mm enable smartphone and tablet integration. Procurement from Apple, Samsung, and Xiaomi suppliers in China and Vietnam drives foundry capacity allocation for compact controller die shrinks.
- Home Automation:Wall-mounted capacitive panels for lighting and climate control.
- Point-of-Sale:Resistive and projected capacitive options for retail checkout terminals.
Gaming commands performance premiums. Mobile Devices command volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's capacitive foundry dominance contrasts with Germany's automotive module specialization, while Taiwan and South Korea concentrate wafer capacity. Each geography shapes distinct procurement patterns through local regulations and industrial clustering.
United States
Enterprise notebook procurement from Dell and HP concentrates volumes with tier-one controller vendors. FCC electromagnetic-emission rules dictate shielding designs and material specifications for domestic market access. Austin and Silicon Valley host firmware development centers optimizing force-sensing algorithms for premium laptop lines.
Germany
Automotive OEMs in Stuttgart and Munich drive center-console touch module demand for gesture-controlled infotainment. EU REACH substance restrictions phase out specific photoresist chemistries in electrode manufacturing. Bavaria's automotive supplier ecosystem integrates sealed haptic modules achieving IP67 ratings for luxury vehicle platforms.
China
GB electronic-safety standards standardize shielding designs that simplify export qualification for compliant manufacturers. Yangtze River Delta and Pearl River Delta clusters house capacitive sensor foundries and module assembly operations serving global Chromebook and education tablet contracts. Domestic certification requirements favor local controller vendors in government procurement tenders.
Japan
METI energy-efficiency guidelines constrain standby-power budgets for controllers in always-connected devices. Nagoya and Tokyo industrial corridors sustain dedicated production lines for automotive center-console modules. ALPS ALPINE anchors domestic manufacturing through Thailand-linked supply chains serving Japanese automotive OEMs.
South Korea
Samsung and LG procurement drives ultra-thin stack-up demand for smartphone and tablet integration. MFDS-equivalent consumer electronics safety frameworks align with international certification standards. Seoul Capital Area foundries concentrate advanced capacitive controller wafer capacity alongside Taiwan facilities.
Touchpad Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across controller architecture, module assembly, and haptic integration tiers. Tier-one suppliers secure multi-million-unit annual contracts through dedicated foundry partnerships, compressing margins for mid-volume competitors. Three strategic archetypes dominate: diversified semiconductor conglomerates with broad sensor portfolios, touch-focused specialists leveraging force-sensing IP, and automotive-certified module integrators. Competitive moves center on M&A for haptic technology access and capacity expansion in Taiwan and South Korea foundries.
Within the touch-focused specialist tier, Synaptics Incorporated and Elan Microelectronics exemplify controller architecture vendors competing on force-sensing integration. ALPS ALPINE occupies a position among automotive-certified module integrators with dedicated production lines in Japan and Thailand. Goodix represents the cost-optimized controller archetype, anchoring competitive positioning in Chromebook and education-segment procurement.
| Leading Market Players |
|---|
| Elan Microelectronics |
| Cirque Corporation |
| Synaptics Incorporated |
| Microchip Technology Inc. |
| Interlink Electronics |
| Goodix |
| ALPS ALPINE |
| Digimore Electronics |
| Apple Inc. |
| Others |
Value Network & Pricing Analysis
Indium tin oxide deposition costs cascade through capacitive sensor manufacturing, with South American mining volatility transmitting directly to controller wafer pricing tiers downstream. Foundry concentration in Taiwan and South Korea compresses margin negotiation room for mid-volume module vendors bidding against tier-one suppliers with captive capacity.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for advanced capacitive controller wafers. Three-tier pricing structure across premium, standard, and economy levels stratifies by force-sensing integration depth and AEC-Q100 certification status. Cost compression in Chromebook education segments intensifies because Goodix and Elan Microelectronics compete aggressively on controller die cost. Government tablet procurement teams in India exhibit highest price sensitivity, while German automotive OEMs prioritize sealing ratings and haptic fidelity over unit cost.
Supply Chain Analysis
AEC-Q100 qualification timelines gate supplier access to automotive center-console contracts, filtering out consumer-electronics specialists lacking 18-24 month process certification. Taiwan, South Korea, and China anchor wafer foundry output and module assembly capacity. Supply chains draw from concentrated indium tin oxide deposits, PET substrate roll stock, and piezoelectric actuator ceramics. Single-source vulnerability in Taiwan Strait logistics corridors threatens just-in-time delivery to notebook OEMs. Distribution runs through Tier 1 display integrators and direct OEM procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through cascading certification requirements, with EU REACH substance restrictions and automotive-grade reliability standards progressively filtering supplier viability.
For Market Incumbents: Deploy force-sensing IP licensing as a defensive moat against controller commoditization. Synaptics and ALPS ALPINE should deepen backward integration into piezoelectric actuator supply to secure haptic module margins. Accelerate AEC-Q100 qualification pipelines to lock out consumer-electronics pivot attempts. For New Entrants and Emerging Players: Solid-state haptic feedback engineering talent scarcity opens wedge opportunities in medical device and industrial automation segments underserved by automotive-focused incumbents. Target India's education-technology procurement with cost-optimized resistive controllers for government tablet tenders. Lead with stylus-compatible firmware differentiation to bypass multi-touch patent thickets. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive certification investments exceed $50 million and revenue recognition delays stretch 24 months. Mid-cap module integrators with Thailand-based production lines and Japanese automotive relationships represent viable acquisition targets. Watch for force-sensing patent portfolio auctions as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Force-Sensing ASIC Development | Synaptics secures premium notebook placements through pressure-detection firmware differentiation. |
| Automotive Certification Investment | ALPS ALPINE locks out consumer-electronics rivals via AEC-Q100 qualified Thailand production lines. |
| Haptic Technology Acquisition | Piezoelectric actuator IP purchases eliminate mechanical click assemblies for IP67 sealing ratings. |
| Education Segment Cost Optimization | Goodix undercuts legacy vendors in India government tablet tenders through die-shrunk controller architectures. |
| Low-Power Controller Architecture | Japan METI standby-power compliance wins preferential placement in premium always-connected notebook lines. |
Research Methodology
Bottom-up notebook OEM procurement modeling reconciled against top-down capacitive foundry capacity tracking forms the analytical core. Primary interviews with controller firmware architects, Tier 1 display integrator procurement directors, and automotive HMI platform engineers combined with secondary validation against SEC 10-K filings, customs trade data, and FCC equipment authorization databases. Triangulation across supply-side wafer output and demand-side contract volumes ensures statistical integrity.
Input-output matrices map electrode substrate consumption through module assembly to end-use shipment volumes across the projection horizon. Segmentation dimensions span product architecture, technology tier, end-use durability requirements, and application precision specifications. CAGRs derive from regression analysis of historical procurement cycles and foundry capacity expansion announcements. Indium tin oxide price indices and notebook OEM product refresh cadences feed directly into forecast sensitivity testing.
The model holds under stable foundry capacity allocation and regulatory compliance timelines; deviation in Taiwan Strait logistics disruption or EU REACH substance list expansion would shift trajectory. Forecasts reflect documented assumptions regarding OEM procurement consolidation and automotive digitization penetration. A model refresh is warranted upon material change in force-sensing patent litigation outcomes or China GB standard harmonization with international frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Analog Switches Market
Switches
DC Switchgear Market
Switches
Japan Reed Sensors Switches Market
Switches
China Reed Sensors Switches Market
Switches
Timer Switch Socket Market
Switches
Static Transfer Switches Market
Switches
Hazardous Location Limit Switches Market
Switches
In-Wall Smart Switch Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Smart Pole-Mounted Switch Market
Switches
Fixed Switch Cabinet Market
Switches
KVM Switch Market
Switches
Global High Voltage Switchgear Market
Switches
Low Voltage Switchgear Market
Switches
Solid State Relay Market
Switches
High-Voltage Disconnect Switch Market