
 Drug Testing Equipment Market | 2026-2036
Drug Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Testing Equipment Market Analysis
North American diagnostic manufacturers is consolidating around high-throughput laboratory analyzer production. Thermo Fisher Scientific leverages its chromatography and mass spectrometry portfolio to anchor clinical toxicology workflows. Abbott Laboratories competes through point-of-care immunoassay platforms designed for rapid turnaround. Quest Diagnostics sustains dominance in employer and government contract channels through extensive collection site networks.
Drug testing equipment comprises analytical instruments, consumable kits, and specimen collection systems engineered to detect controlled substances, prescription medications, and alcohol biomarkers in biological matrices such as urine, oral fluid, hair, and blood, with sensitivity thresholds typically ranging from ng/mL to pg/mL depending on target analyte and regulatory cutoff. These systems serve compliance, clinical diagnostics, and forensic verification purposes across institutional and decentralized settings. Laboratory analyzers utilizing mass spectrometry occupy the highest-margin tier due to confirmatory testing requirements, while rapid screening devices lead volume through workplace and law enforcement deployment. Immunoassay technology remains the workhorse for initial screening, though chromatography methods are displacing legacy platforms in forensic laboratories seeking specificity improvements.
FDA regulates premarket notification and clinical validation for diagnostic devices under 21 CFR Part 820 quality system requirements, while SAMHSA certifies laboratories conducting federally mandated workplace testing against strict chain-of-custody protocols. OSHA workplace safety standards and DOT modal administration rules collectively shape employer procurement patterns and testing frequency mandates. Stakeholders must monitor evolving state-level cannabis legalization frameworks and corresponding impairment detection standards that challenge existing metabolite-based testing paradigms.
Market Dynamics
Federally mandated workplace testing programs are tightening validation thresholds for rapid diagnostic devices, compressing development timelines for manufacturers while expanding kit procurement volumes among large employers in safety-sensitive sectors.
Growth Catalysts
- DOT Modal Rules:Federal transportation agencies mandate testing across aviation, rail, and trucking sectors, creating recurring demand for certified collection systems and laboratory confirmation services.
- Oral Fluid Technology:Non-invasive specimen collection is displacing urine-based protocols in pre-employment screening, reducing collection site infrastructure costs for employers.
- Safety-Sensitive Industries:Oil and gas operators, nuclear facilities, and heavy manufacturing employers are expanding random testing programs beyond federal minimums.
Market Restraints
- Mass Spectrometry Instrument Costs:Confirmatory testing requires capital-intensive LC-MS/MS platforms, creating barrier-to-entry for smaller independent laboratories.
- Reagent Supply Concentration:Specialized immunoassay antibodies and chromatography columns depend on concentrated European and North American specialty chemical suppliers.
- Cannabis Metabolite Limitations:Tetrahydrocannabinol detection windows in urine fail to establish current impairment, creating legal exposure for employers in jurisdictions with recreational legalization.
Strategic Opportunities
- Breath-Based Cannabinoid Detection:Real-time impairment measurement technology is expanding into law enforcement roadside testing and workplace fitness-for-duty protocols.
- Hair Specimen Archives:Extended detection windows for chronic substance use patterns serve family court, child custody, and addiction treatment monitoring applications.
- India Clinical Toxicology:Private hospital networks are building in-house reference laboratory capacity for overdose diagnosis and therapeutic drug monitoring.
Industry Challenges
- FDA 510(k) Validation Timelines:Rapid diagnostic manufacturers face extended clinical study requirements for novel biomarker claims and cross-reactivity documentation.
- Chain-of-Custody Documentation:Federally regulated testing demands tamper-evident specimen handling and electronic data integrity systems that increase operational complexity.
- Multi-Analyte Panel Complexity:Synthetic opioid analogues and designer benzodiazepines require continuous assay reformulation to maintain detection relevance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Testing Equipment Market |
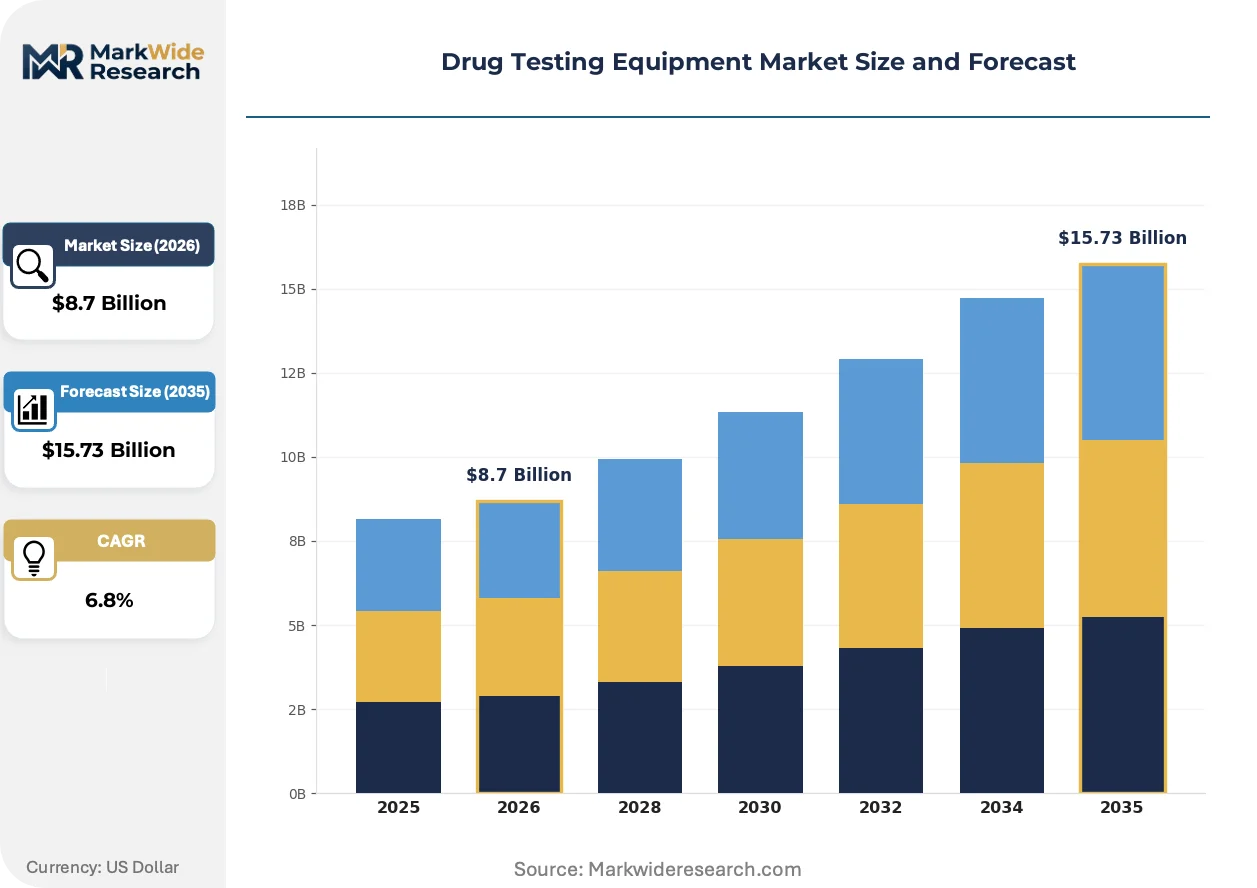
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screening Devices, Laboratory Analyzers, Collection Accessories, Testing Kits Technology: Immunoassay, Chromatography, Mass Spectrometry, PCR End User: Hospitals, Laboratories, Drug Rehabilitation Centers, Law Enforcement Application: Workplace Testing, Sports Testing, Clinical Testing, Home Testing |
| Companies Covered | Quest Diagnostics Incorporated, Thermo Fisher Scientific, Inc., Abbott Laboratories, Laboratory Corporation of America Holdings, F. Hoffmann-La Roche Ltd, Siemens Healthineers, OraSure Technologies, Inc., Bio-Rad Laboratories, Inc., Alfa Scientific Designs, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Testing Equipment Market Emerging Trajectories
Laboratory and point-of-care segments are diverging in technology strategy, with centralized facilities prioritizing analytical specificity while decentralized deployments emphasize result velocity and specimen handling simplicity.
High-resolution mass spectrometry is expanding into forensic toxicology workflows, enabling retrospective data mining for novel psychoactive substances without reanalysis. State crime laboratories and medical examiner offices are adopting these platforms to address synthetic drug surveillance gaps. The technology is compressing method development cycles from months to weeks for emerging drug threats.
OSHA workplace safety standards are incorporating post-accident testing mandates for cannabis and opioids in construction and manufacturing sectors. Employers are responding by contracting with third-party administrators offering 24-hour collection site access and electronic custody forms. The policy shift is accelerating demand for oral fluid and breath-based screening devices that reduce collection site logistics.
Third-party administrator consolidation is reshaping buyer-side procurement, with national occupational health networks capturing multi-site employer contracts through integrated medical review officer services. Regional collection site operators are losing standalone contracts to platforms offering unified scheduling, result reporting, and compliance documentation. This concentration is most visible in United States transportation and logistics sectors with distributed workforces.
Drug Testing Equipment Market Segmentation
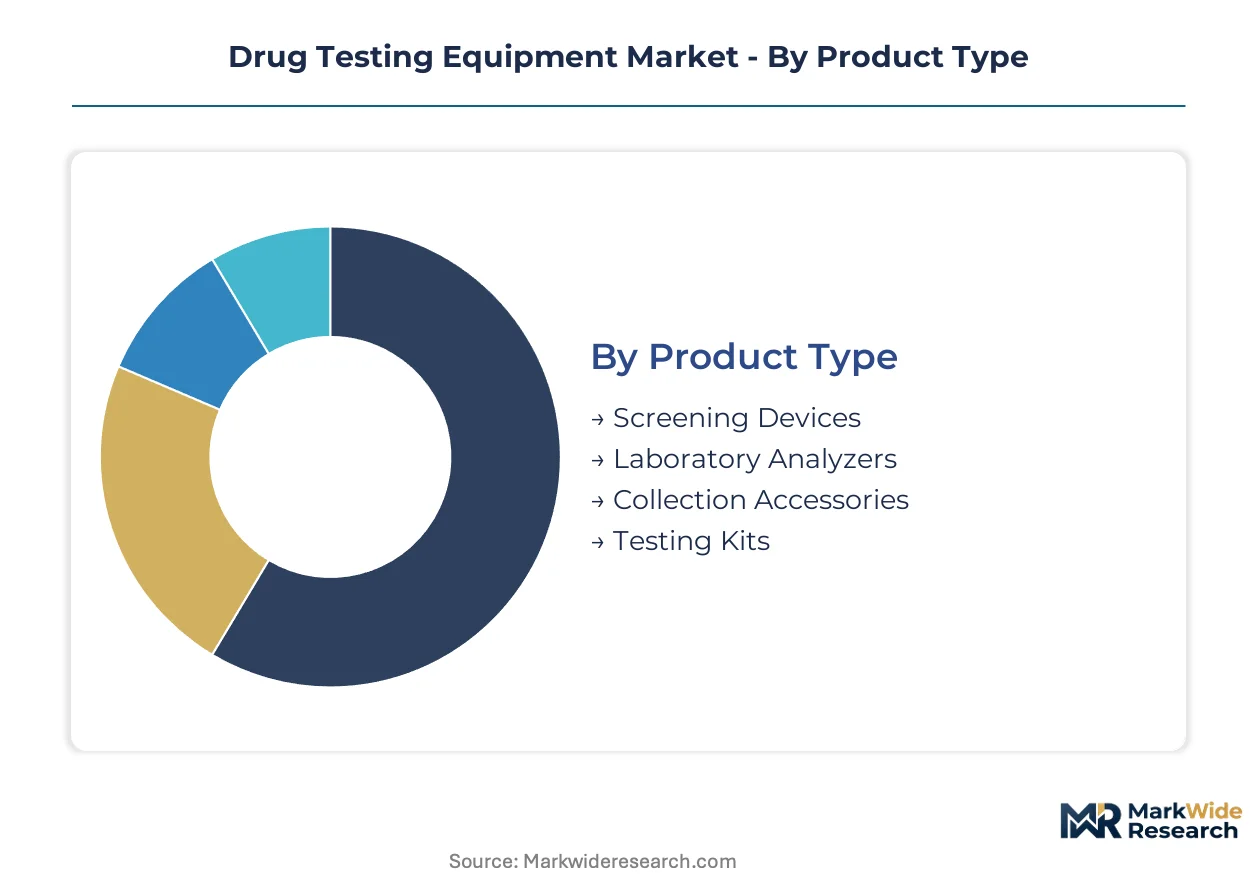
Drug testing equipment segments diverge sharply between high-volume screening deployments and premium confirmatory platforms. Procurement patterns split between federally mandated workplace programs requiring certified laboratory confirmation and decentralized settings prioritizing rapid turnaround. Understanding these tiered demand structures is essential for aligning product development with reimbursement pathways and regulatory compliance requirements.
Product Type:
Volume leadership concentrates in disposable screening formats, while margin capture sits with capital-intensive analytical systems requiring specialized service infrastructure.
- Screening Devices:Portable immunoassay readers and single-use cassettes deliver qualitative results at point-of-collection sites. DOT-mandated workplace programs across aviation, rail, and trucking sectors drive procurement of FDA-cleared rapid test systems with electronic custody documentation.
- Laboratory Analyzers:Automated high-throughput systems process batch confirmations using chromatography and mass spectrometry methods. Federally certified laboratories serving SAMHSA-regulated employers anchor demand for LC-MS/MS platforms with chain-of-custody integration.
- Collection Accessories:Tamper-evident containers, transport media, and temperature monitoring devices ensure specimen integrity during transit.
- Testing Kits:Reagent panels for multi-analyte detection of synthetic opioids, benzodiazepines, and amphetamine analogues require continuous reformulation.
Mature deployment sits with Laboratory Analyzers. Newer deployment is concentrated in Screening Devices.
Technology:
Cost structures stratify between antibody-based screening methods and instrument-dependent confirmatory techniques requiring substantial capital allocation.
- Immunoassay:Enzyme-mediated antibody binding reactions provide initial screening sensitivity at ng/mL thresholds. Workplace and law enforcement applications dominate volume due to minimal operator training requirements and rapid result generation.
- Chromatography:Liquid and gas separation methods resolve complex biological matrices for forensic verification. State crime laboratories expanding synthetic drug surveillance capabilities sustain demand for high-resolution separation platforms.
- Mass Spectrometry:Definitive identification through molecular fragmentation patterns serves as the gold standard for contested results.
- PCR:Nucleic acid amplification enables pharmacogenomic testing for medication metabolism profiling.
Established infrastructure centers on Immunoassay. Emerging adoption clusters in Mass Spectrometry.
End User:
Procurement authority differs between institutional buyers with centralized contracting and distributed facilities requiring flexible ordering patterns.
- Hospitals:Emergency departments and clinical toxicology services require rapid turnaround for overdose diagnosis and therapeutic drug monitoring. Private hospital networks in India are building in-house reference capacity.
- Laboratories:Independent reference facilities and hospital-affiliated toxicology units process federally mandated workplace confirmations. SAMHSA certification requirements create structural barriers limiting competitive entry.
- Drug Rehabilitation Centers:Longitudinal monitoring programs utilize extended detection window technologies for treatment compliance verification.
- Law Enforcement:Roadside impairment screening and evidentiary collection drive demand for portable, legally defensible systems.
Contract concentration rests with Laboratories. Fastest expansion appears in Drug Rehabilitation Centers.
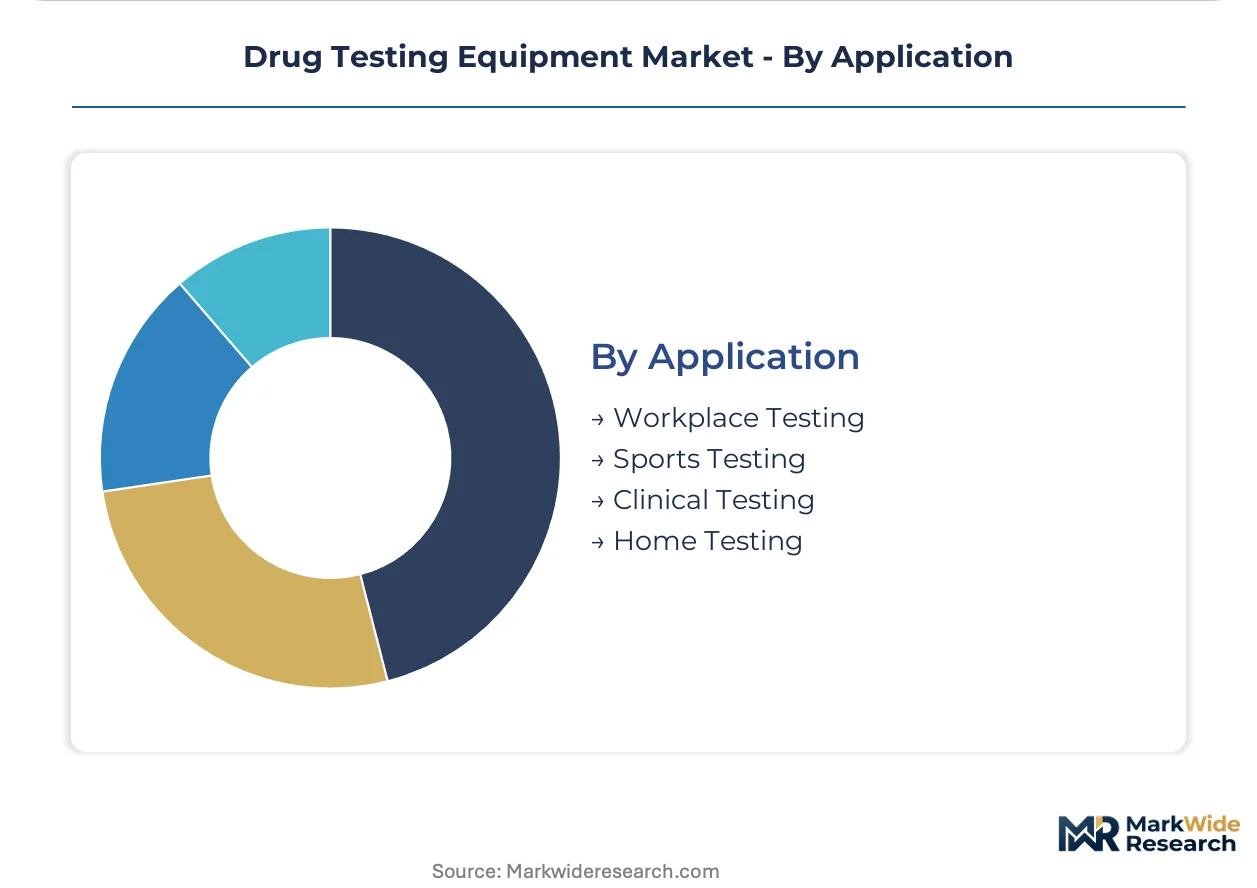
Application:
Regulatory mandates versus discretionary spending create divergent growth trajectories across testing contexts.
- Workplace Testing:Federally regulated transportation sectors and safety-sensitive industries mandate pre-employment, random, and post-accident screening. OSHA standards incorporating cannabis and opioid testing are accelerating oral fluid and breath-based device procurement.
- Sports Testing:Anti-doping agencies and professional athletic organizations require isotope ratio mass spectrometry for peptide hormone and anabolic steroid detection. WADA-accredited laboratories maintain strict chain-of-custody protocols for competition results.
- Clinical Testing:Emergency toxicology and pain management monitoring serve hospital and outpatient settings.
- Home Testing:Direct-to-consumer kits for parental monitoring and personal health tracking operate outside regulated channels.
Regulatory enforcement anchors Workplace Testing. Consumer-directed expansion is gaining share fastest in Home Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical feedstocks for immunoassay reagents concentrate in the Rhine-Ruhr industrial corridor, anchoring European manufacturing networks for chromatography columns and diagnostic antibodies.
United States
DOT modal administration rules and OSHA workplace safety standards drive recurring demand across aviation, rail, and trucking sectors. FDA 510(k) clearance pathways for rapid diagnostic devices are tightening validation requirements for manufacturers. The Dallas-Fort Worth metroplex anchors third-party administrator consolidation for multi-site employer contracts.
Germany
Industrial chemical synthesis capabilities in the Rhine-Ruhr region supply chromatography resins and mass spectrometry consumables to forensic laboratories. EMA regulatory frameworks for in-vitro diagnostic devices shape CE marking requirements for export-oriented manufacturers. Bavaria's Munich-Stuttgart corridor hosts precision engineering clusters serving clinical toxicology analyzer production.
China
NMPA medical device registration pathways are streamlining for domestic point-of-care diagnostic manufacturers. The Yangtze River Delta around Shanghai concentrates contract research organizations conducting cross-reactivity studies for novel psychoactive substance panels. Shenzhen's electronics manufacturing ecosystem supplies portable immunoassay reader components.
India
CDSCO medical device rules are formalizing quality standards for imported laboratory analyzers serving private hospital networks. Maharashtra's Mumbai-Pune corridor is building in-house reference laboratory capacity for clinical toxicology and therapeutic drug monitoring. Gujarat's specialty chemical sector is expanding antibody production for immunoassay reagent kits.
United Kingdom
MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines for diagnostic device approvals. London's financial and legal services sector anchors corporate wellness testing contracts for multinational employers. The Cambridge-Oxford arc sustains academic research partnerships advancing high-resolution mass spectrometry methods.
Drug Testing Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue breath-based cannabinoid detection and real-time impairment measurement. The vendor structure stratifies between capital-intensive laboratory analyzer manufacturers and high-volume rapid screening device suppliers. Three archetypes dominate: diversified life science conglomerates with chromatography portfolios, point-of-care diagnostic specialists, and third-party administrators with integrated collection networks. Competitive moves center on strategic partnerships for chain-of-custody software integration and geographic expansion into India clinical toxicology markets.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Abbott Laboratories exemplify contrasting technology strategies. Thermo Fisher leverages mass spectrometry and chromatography capabilities to anchor forensic toxicology workflows requiring confirmatory specificity. Abbott competes through point-of-care immunoassay platforms designed for rapid turnaround in decentralized settings. Quest Diagnostics occupies a distinct position as a third-party administrator, sustaining employer and government contract channels through extensive collection site networks rather than equipment manufacturing.
| Leading Market Players |
|---|
| Quest Diagnostics Incorporated |
| Thermo Fisher Scientific, Inc. |
| Abbott Laboratories |
| Laboratory Corporation of America Holdings |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| OraSure Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| Alfa Scientific Designs, Inc. |
| Others |
Supply Flow & Price Mechanics
Specialty chemical feedstock indices for chromatography-grade solvents and immunoassay-grade antibodies cascade through three pricing tiers, compressing margins for rapid screening device manufacturers while sustaining premium capture for mass spectrometry system vendors serving SAMHSA-certified laboratories.
Pricing Analysis
Service bundling separates capital-intensive laboratory analyzer vendors from rapid screening device suppliers, with the former embedding multi-year maintenance contracts and reagent supply agreements while the latter compete on unbundled per-unit kit economics. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA 510(k) clearance tier, SAMHSA certification status, and chain-of-custody software integration depth. Price erosion runs through economy-tier rapid screening devices as Chinese point-of-care manufacturers expand NMPA-cleared export capacity. Employer procurement committees demonstrate highest price sensitivity, while forensic crime laboratories exhibit lowest sensitivity due to evidentiary defensibility requirements.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices and China's NMPA localization requirements are forcing reconfiguration of antibody sourcing and electronics assembly footprints. Manufacturing gravity centers on Germany's Rhine-Ruhr corridor for chromatography resins, the United States for mass spectrometry instrumentation, and China's Yangtze River Delta for portable immunoassay reader components. Critical dependencies include European-sourced HPLC columns, North American-manufactured mass spectrometer ion sources, and Shenzhen-originating CMOS sensor arrays. Single-source vulnerability concentrates in specialized immunoassay antibody production. Distribution runs through third-party administrator networks consolidating multi-site employer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as FDA 510(k) validation timelines extend and capital requirements for confirmatory testing platforms exclude sub-scale competitors, forcing independent regional laboratories into acquisition or exit.
For Market Incumbents: To counter breath-based cannabinoid detection entrants, Thermo Fisher Scientific and Abbott Laboratories should deepen service contract penetration in SAMHSA-certified laboratories while acquiring chain-of-custody software vendors to lock employer procurement channels. Backward integration into immunoassay antibody production mitigates European reagent supply concentration. For New Entrants and Emerging Players: CDSCO's formalizing quality standards for imported laboratory analyzers in India opens a window for joint ventures with Maharashtra's emerging reference laboratory networks. Oral fluid technology displacement of urine protocols offers the most penetrable white-space, with roadside law enforcement and oil-field fitness-for-duty protocols as priority beachheads. Direct contracting with third-party administrators bypasses entrenched vendor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional collection site operators in the United States losing standalone contracts to national occupational health networks, available at compressed multiples before TPA consolidation completes. Long-term viability hinges on SAMHSA certification moats and software-integrated service platforms. Watch for OSHA post-accident testing rulemaking as inflection signal for oral fluid and breath-based device procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance for novel biomarker claims secures employer procurement in DOT-mandated sectors. |
| Chain-of-Custody Software Integration | Electronic data integrity systems differentiate vendors for federally regulated workplace contracts. |
| Geographic Expansion into India | Private hospital networks in Mumbai-Pune corridor build reference toxicology capacity. |
| Strategic Partnership with Third-Party Administrators | Unified scheduling platforms capture multi-site employer contracts from regional operators. |
| Acquisition of Breath-Based Detection Specialist | Real-time impairment technology addresses cannabis metabolite limitation legal exposure. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance volumes, SAMHSA laboratory certification trends, and OSHA enforcement activity anchored the trend analysis, supplemented by interviews with toxicology laboratory directors, third-party administrator procurement executives, biomedical engineers at hospital networks, and regulatory affairs leads at diagnostic device manufacturers. Secondary validation drew from FDA 510(k) database filings, SAMHSA National Laboratory Certification Program records, DOT modal administration rulemaking dockets, and SEC 10-K disclosures of publicly traded diagnostic manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, technology platform, end-user institution, and application context informed the analytical framework, with cross-validation against regulatory mandate expansion rates and employer testing frequency surveys. CAGRs were derived from regression analysis of historical procurement data projected across the modeling period. Industry-specific forecast inputs included synthetic opioid analogue surveillance requirements and state-level cannabis legalization policy trajectories.
The model assumes a particular technology adoption path; alternative pathways for mass spectrometry platform displacement by high-resolution alternatives would alter the outlook. Forecasts reflect documented assumptions regarding regulatory timeline adherence and employer compliance cost tolerance. Unforeseen shifts in cannabis impairment detection standards or reagent supply disruptions would necessitate revision. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Allergy Skin Test Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Ige Allergy Blood Tests Market