
 Greece POS Terminals Market | 2026-2036
Greece POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Greece POS Terminals Market Foresight
The Greece POS terminals landscape is shifting along a sharp hardware-software divide. Premium vendors bundle cloud-native platforms with integrated payment acceptance, while commodity providers compete on terminal leasing rates alone. Worldline leverages its European acquiring infrastructure to sustain cross-border transaction capabilities for Greek merchants. Viva Wallet anchors its position through in-house issuer-processor integration, reducing third-party routing costs. Nayax differentiates by specializing in unattended payment solutions for vending and EV charging verticals.
A POS terminal is an electronic device combining secure payment card reading, cryptographic processing, and transaction data transmission through wired or wireless connectivity, typically featuring PCI-DSS compliance and EMV chip certification to authenticate and settle consumer purchases at the point of sale. These devices serve as the terminal node in merchant acquiring networks, converting cardholder payment credentials into cleared funds through gateway and processor infrastructure. Mobile POS terminals lead transaction volume growth in Greek retail due to low upfront hardware commitment and smartphone-based deployment flexibility. Integrated POS systems capture margin concentration in hospitality through bundled inventory, kitchen display, and payment modules that reduce vendor fragmentation. Cloud-based deployment models are displacing on-premise installations as Greek small merchants prioritize remote software updates and centralized reporting dashboards over local server maintenance.
The Bank of Greece enforces payment security and operational resilience standards for terminal vendors, while the Hellenic Data Protection Authority applies GDPR-derived rules to transaction data storage and cross-border flows. PCI Security Standards Council certification requirements shape hardware design priorities, pushing EMV and NFC capability toward universal inclusion in new terminal deployments. Stakeholders must monitor whether Greek tourism recovery patterns and central bank digital currency pilots reshape merchant hardware refresh cycles and processor partnership structures.
Market Dynamics
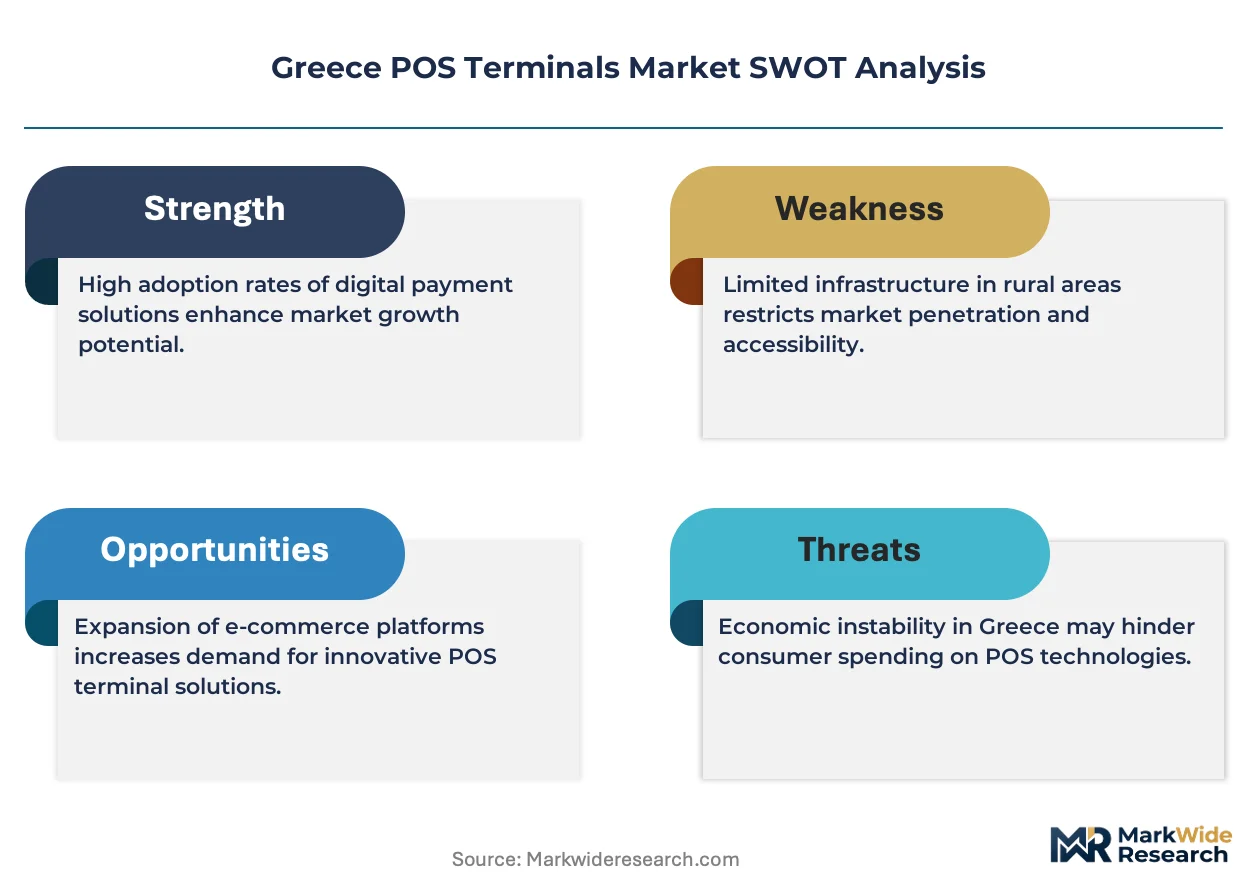
Greek merchants face a forced hardware refresh cycle as the Bank of Greece mandates PCI-DSS 4.0 compliance deadlines and contactless payment thresholds tighten across the acquiring network.
Growth Catalysts
- Regulatory Mandate:The Bank of Greece's payment security directives compel magnetic-stripe terminal replacements, accelerating EMV and NFC hardware deployment across merchant tiers.
- Tourism Concentration:Athens and Thessaloniki merchant density drives acquiring infrastructure investment, with seasonal transaction peaks justifying premium terminal specifications.
- SoftPOS Technology:Smartphone-based acceptance eliminates dedicated hardware costs for micro-merchants, expanding addressable merchant populations beyond traditional POS economics.
Market Restraints
- Hardware Cost Structure:Certified terminal procurement requires upfront capital outlay that strains small hospitality operators operating on thin working capital cycles.
- Supply Concentration:European processor dependency creates vulnerability to cross-border fee adjustments and clearing network policy shifts outside Greek regulatory control.
- Technical Debt:Legacy on-premise installations lock merchants into maintenance contracts that delay cloud migration and remote management capability adoption.
Strategic Opportunities
- Island Tourism Corridors:Cyclades and Dodecanese merchant penetration remains below mainland density, presenting greenfield acquiring opportunities for integrated solution vendors.
- EV Charging Infrastructure:Unattended payment terminals for electric vehicle stations represent an emerging vertical with distinct hardware specifications and recurring revenue potential.
- GDPR-Compliant Analytics:Transaction data monetization through privacy-preserving dashboards offers merchants revenue diversification beyond payment processing margins.
Industry Challenges
- Certification Bottlenecks:Hellenic Data Protection Authority approval timelines for cross-border data flows extend vendor go-to-market schedules and compress implementation windows.
- Integration Complexity:Property management system and kitchen display interoperability demands bespoke middleware development, fragmenting vendor resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece POS Terminals Market |
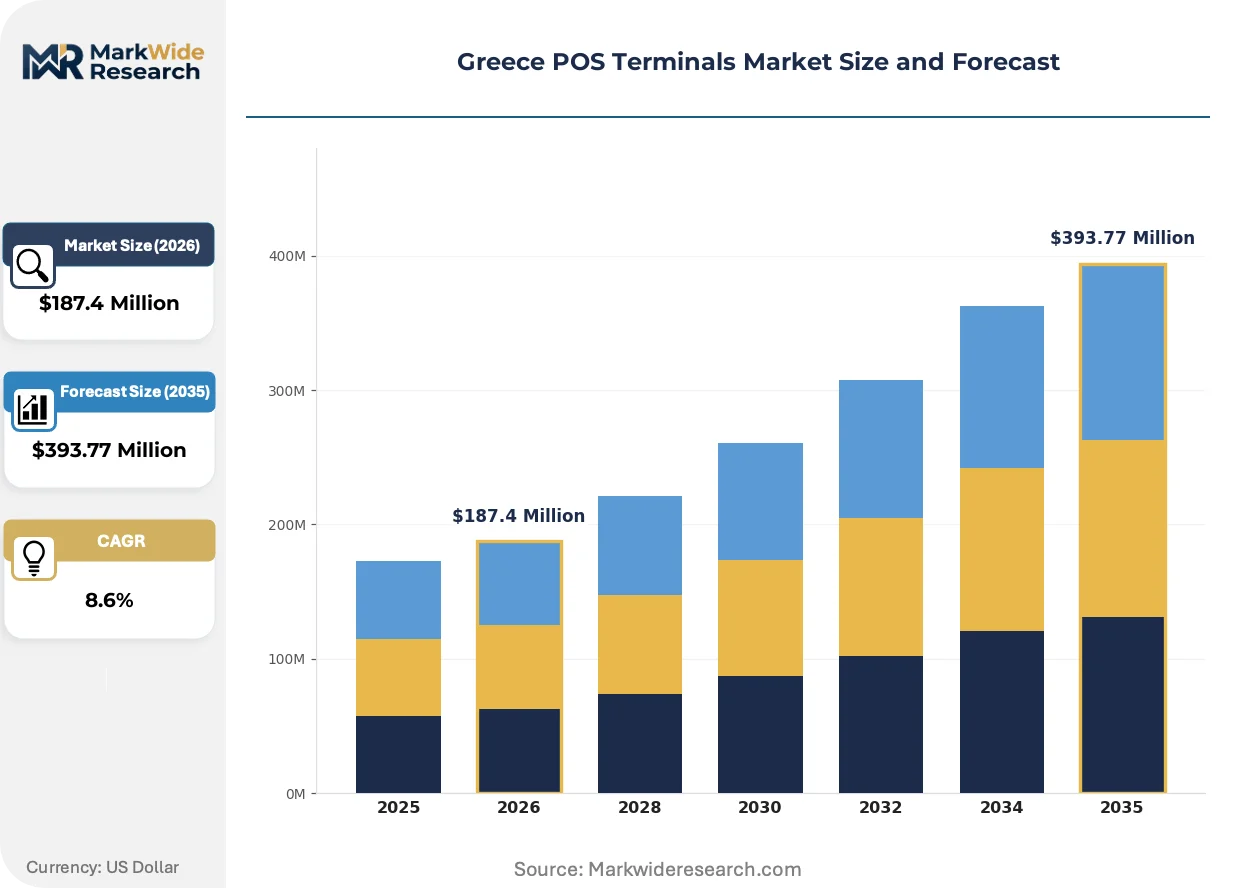
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Integrated POS, Desktop POS, Self-Service Kiosk End User: Retail, Hospitality, Healthcare, Transportation Technology: EMV, NFC, QR Code, Magnetic Stripe Deployment: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | Cardlink, Worldline, NEXI PAYMENTS GREECE SOCIETE ANONYME, Nayax, Viva Wallet, EDPS, Smart POS Software, QuadraPay, myPOS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece POS Terminals Market Shifts & Advancements
Payment acceptance architecture in Greece is bifurcating between cloud-native platforms and residual on-premise installations, with merchant size determining deployment trajectory rather than vertical preference.
Android-based open-platform terminals are expanding into Greek retail and hospitality environments. Mid-size restaurant chains adopt these devices to consolidate payment, inventory, and loyalty applications on single hardware estates. This convergence is expanding into adjacent software revenue streams for terminal vendors previously dependent on hardware margins alone.
The Bank of Greece's operational resilience requirements for payment service providers impose business continuity and incident reporting obligations on terminal operators. Hardware vendors must now embed remote diagnostic capabilities and firmware rollback mechanisms as standard features. Merchant acquirers in Attica and Central Macedonia bear the greatest compliance burden given their transaction concentration.
Merchant purchasing patterns favor integrated solution bundles over standalone terminal procurement. Small hotel operators now specify combined property management, channel management, and payment modules in single vendor relationships. This preference consolidation is most pronounced in Athens hospitality clusters where staff training costs drive simplicity premiums in vendor selection criteria.
Greece POS Terminals Market Segmentation
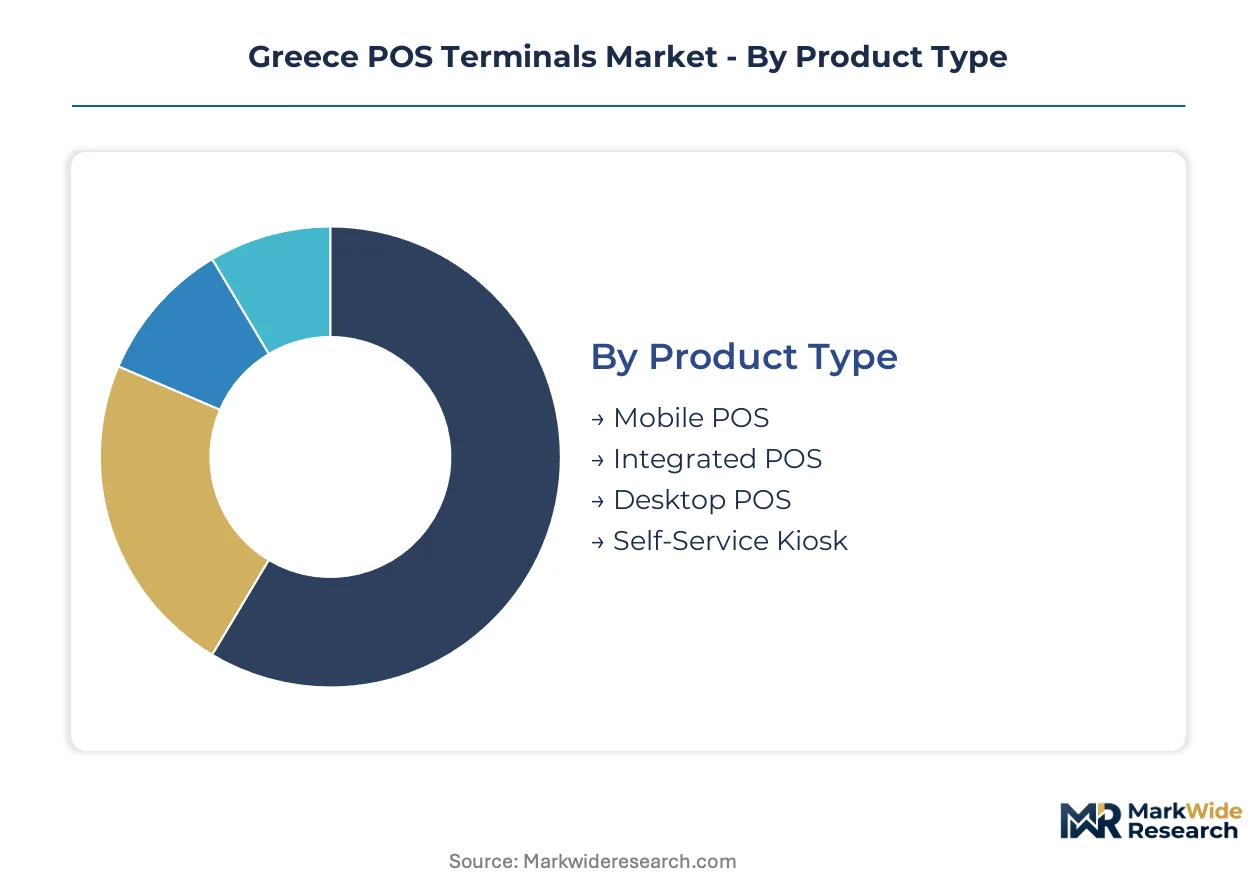
Greek merchant acquiring infrastructure fragments across hardware form factors, end-use verticals, and connectivity architectures. Each segmentation dimension reveals distinct procurement patterns shaped by regulatory deadlines, tourism seasonality, and working capital constraints.
Product Type:
Volume concentrates in low-commitment hardware, while premium tiers capture margin through software bundling.
- Mobile POS:Smartphone-tethered or standalone wireless devices with Bluetooth and cellular connectivity. Athens street vendors and Cyclades seasonal merchants favor these for zero upfront hardware commitment and instant deployment. SoftPOS technology is accelerating displacement of dedicated terminals in micro-merchant tiers.
- Integrated POS:Converged hardware estates combining payment acceptance with inventory, kitchen display, and loyalty modules. Thessaloniki restaurant chains and Attica hotel operators specify these to reduce vendor fragmentation and staff training overhead.
- Desktop POS:Countertop fixed-line terminals with Ethernet connectivity and receipt printing. Legacy hospitality operators in mainland Greece retain these for stable wired connectivity in high-volume transaction environments.
- Self-Service Kiosk:Unattended payment stations with touchscreen interfaces for ordering and checkout. Emerging deployment in Athens quick-service restaurants and EV charging corridors along Attica highways.
Today's leader: Mobile POS. Tomorrow's challenger: Integrated POS.
End User:
Customer type determines specification intensity more than transaction scale alone.
- Retail:Athens convenience stores and Thessaloniki fashion merchants drive contactless terminal refresh cycles. Seasonal tourism peaks justify premium NFC capability for international cardholder acceptance.
- Hospitality:Full-service restaurants and hotels across Attica and Central Macedonia specify property management system interoperability. Integration complexity with kitchen display systems fragments vendor selection.
- Healthcare:Private clinics and pharmacies in Athens urban clusters require HIPAA-aligned transaction data handling. GDPR compliance overlays create certification bottlenecks for cross-border processor routing.
- Transportation:Ferry operators and airport concessionaires across Greek island corridors need offline transaction capability. Maritime connectivity gaps mandate store-and-forward functionality in terminal specifications.
Current procurement concentration: Hospitality. Steepest expansion trajectory: Transportation.
Technology:
Certification mandates are forcing obsolescence curves that advantage cryptographic over legacy protocols.
- EMV:Chip-card authentication with dynamic data encryption. The Bank of Greece's PCI-DSS directives have made this baseline for all new terminal deployments across merchant tiers.
- NFC:Contactless proximity payment enabling tap-to-pay transactions. Athens and Thessaloniki tourism density drives merchant specification of dual-interface EMV-NFC capability for international visitor acceptance.
- QR Code:Optical scan-based payment initiation through merchant-presented or customer-presented codes. Emerging adoption in micro-merchant segments seeking zero hardware cost acceptance pathways.
- Magnetic Stripe:Legacy static data track reading. The Bank of Greece's security directives are accelerating terminal replacement cycles to eliminate this vulnerability vector from active merchant estates.
Dominant installed base: EMV. Gaining share fastest: NFC.
Deployment:
Merchant size and IT staffing determine cloud migration velocity across the Greek market.
- On-Premise:Local server installation with dedicated terminal management. Legacy hotel operators in established Athens clusters retain this model for perceived data sovereignty control.
- Cloud-Based:Centralized software delivery with remote firmware and application updates. Small merchants across Attica prioritize this for zero local IT maintenance burden and real-time reporting dashboards.
- Hybrid:Mixed estate with critical functions local and analytics centralized. Mid-size retail chains in Thessaloniki adopt this to balance transaction continuity with management visibility.
- Remote:Fully distributed terminal management with over-the-air configuration. Island tourism operators in Cyclades and Dodecanese specify this for technical support access without mainland technician dispatch.
Current default: On-Premise. Migration target: Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German merchant acquirers deploy contactless infrastructure faster than Italian operators, while Greek terminal refresh cycles accelerate under central bank mandates. Each Mediterranean market exhibits distinct procurement patterns shaped by tourism density and regulatory enforcement timelines.
Attica
Athens hotel chains and quick-service restaurants drive integrated POS specifications. The Bank of Greece's PCI-DSS 4.0 deadlines compel terminal replacements across Piraeus port concessions and Syntagma Square retail corridors. Piraeus merchant acquirers prioritize EMV-NFC dual-interface capability for cruise passenger transaction peaks.
Central Macedonia
Thessaloniki hospitality clusters specify property management system interoperability in procurement tenders. GDPR compliance overlays from the Hellenic Data Protection Authority extend certification timelines for cross-border processor routing. Thermi industrial zone logistics operators deploy mobile POS for fleet-based delivery acceptance.
South Aegean
Cyclades island merchants favor zero-upfront SoftPOS deployment for seasonal tourism windows. Maritime connectivity gaps mandate store-and-forward functionality in Mykonos and Santorini terminal specifications. Ferry operators require offline transaction capability for island-hopping payment continuity.
Dodecanese
Rhodes and Kos hospitality operators seek remote terminal management to eliminate mainland technician dispatch costs. The Bank of Greece's operational resilience directives impose incident reporting obligations on Dodecanese acquiring infrastructure. Kos airport concessionaires specify unattended kiosk terminals for baggage handling payments.
Greece POS Terminals Market Competitive Landscape
Top-tier vendors anchor integrated platform bundles, while commodity providers compete on terminal leasing rates alone. The Greek POS terminal market exhibits tiered concentration with European payment processors dominating acquiring infrastructure and local software houses capturing hospitality vertical specialization. Three strategic archetypes prevail: cloud-native platform bundlers, issuer-processor integrated challengers, and unattended payment specialists. Competitive moves center on vertical software integration and island tourism corridor expansion.
Within the European processor tier, Worldline and NEXI PAYMENTS GREECE SOCIETE ANONYME represent acquiring infrastructure incumbents with cross-border transaction capabilities. Viva Wallet occupies a position exemplifying issuer-processor integration, reducing third-party routing costs through in-house stack control. Nayax anchors the unattended specialization archetype, serving vending and EV charging verticals with distinct hardware specifications.
| Leading Market Players |
|---|
| Cardlink |
| Worldline |
| NEXI PAYMENTS GREECE SOCIETE ANONYME |
| Nayax |
| Viva Wallet |
| EDPS |
| Smart POS Software |
| QuadraPay |
| myPOS |
| Others |
Supply & Pricing Matrix
Athens hospitality chains and Thessaloniki retail clusters concentrate procurement volume, locking vendors into subscription-based SaaS pricing for integrated terminal bundles rather than transactional per-device models. This buyer concentration rewards vendors who consolidate payment, inventory, and property management modules into single-vendor relationships, while commodity terminal providers compete on monthly leasing rates alone.
Pricing Analysis
Bundled-versus-unbundled service splits define pricing architecture across the Greek market. Premium vendors command three-tier pricing structure across premium, standard, and economy levels based on EMV-NFC certification grade and software integration depth, while hardware-only providers face price erosion from SoftPOS alternatives eliminating dedicated terminal costs. Small island merchants in Cyclades exhibit highest price sensitivity due to seasonal cash flow cycles, whereas Attica hotel operators prioritize interoperability over unit economics. Cost compression in the commodity tier intensifies because Worldline and Viva Wallet absorb third-party routing fees through integrated processor stacks.
Supply Chain Analysis
Domestic-content mandates from the Bank of Greece reshape sourcing toward EU-certified component suppliers, though terminal assembly still concentrates in China, Taiwan, and Vietnam. Secure element chips and NFC antenna modules draw from Taiwanese semiconductor foundries, while plastic enclosures and receipt printers source from mainland Chinese manufacturers. Single-source vulnerability in EMV kernel certification creates bottleneck risk, as only three European labs approve cryptographic firmware for Greek deployment. Distribution runs through Athens-based merchant acquirers who bundle hardware provisioning with acquiring contracts, compressing direct vendor-to-merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Greece functions as a regulatory-arbitrage corridor within European payment infrastructure, where Bank of Greece PCI-DSS enforcement timelines lag Northern European mandates by 12-18 months, creating extended hardware refresh windows for prepared vendors.
For Market Incumbents: Cement dominance in Attica hospitality clusters through exclusive property management system partnerships that raise switching costs for integrated POS deployments. Defend against SoftPOS disintermediation by embedding remote diagnostic capabilities as standard features, leveraging Bank of Greece operational resilience directives to justify premium subscription tiers. Prioritize certification investment in GDPR-compliant analytics modules to capture merchant data-monetization revenue beyond transaction processing margins. For New Entrants and Emerging Players: Enter via Cyclades and Dodecanese island corridors where merchant penetration remains below mainland density and incumbent technical support infrastructure is sparse. Target unattended payment verticals—EV charging stations and ferry ticketing kiosks—where hardware specifications diverge from standard retail terminals and Nayax lacks localized service presence. Pursue white-label SoftPOS partnerships with domestic neobanks to bypass upfront hardware capital requirements. For Investors and Strategic Acquirers: European payment processors with Mediterranean expansion mandates are the most active acquirer in this space, seeking integrated platform capabilities to offset domestic market saturation. Target acquisition archetype: hospitality-vertical software houses with captive POS terminal distribution relationships in Attica and Central Macedonia. Watch for inflection in central bank digital currency pilot announcements, which would reshape hardware refresh cycles and processor partnership structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables remote firmware management required by Bank of Greece operational resilience directives. |
| Island Corridor Expansion | Captures greenfield merchant acquisition in Cyclades and Dodecanese where incumbent density is lowest. |
| EV Charging Infrastructure Partnership | Positions vendors for unattended payment vertical with distinct hardware specifications and recurring revenue. |
| GDPR-Compliant Analytics Development | Unlocks transaction data monetization through privacy-preserving dashboards for merchant revenue diversification. |
| SoftPOS Technology Integration | Eliminates dedicated hardware costs for micro-merchant segments beyond traditional POS economics. |
Research Methodology
Direct dialogue with merchant acquirer executives, hospitality IT directors, terminal vendor product managers, and Bank of Greece regulatory affairs specialists grounded qualitative findings. Secondary validation drew from PCI Security Standards Council certification databases, Hellenic Data Protection Authority cross-border data flow rulings, European Central Bank payment statistics, and customs import records for payment terminal hardware. Bottom-up merchant estate sizing and top-down processor revenue triangulation converged on market estimates.
Bottom-up terminal deployment counts by region and merchant tier were cross-checked against top-down acquiring revenue disclosures across the projection horizon. Segmentation modeling incorporated hardware form factor, end-use vertical, connectivity architecture, and deployment model dimensions. CAGRs derived from fitted growth curves adjusted for regulatory mandate acceleration effects and tourism recovery pattern assumptions. Forecast inputs included cruise passenger volume projections and central bank digital currency pilot timeline scenarios.
The model holds under stable tourism recovery trajectories and incremental regulatory enforcement; deviation in sovereign debt stress or EMU payment system fragmentation would shift merchant hardware investment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United Arab Emirates Mobile Payments Market
Payments
Bill Splitting Apps Market
Payments
Spain Payment Gateway Market
Payments
UK Prepaid Cards Market
Payments
Remote Mobile Payment Market
Payments
Australia Mobile Payment Market
Payments
Clearing Houses and Settlements Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Belgium Payments Market
Payments
Asia Pacific Real Time Payment Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Telecom Cloud Billing Market
Payments
Global Payments As a Service Market
Payments
B2C Payment Market
Payments
Singapore Payments Market