
 Asia-Pacific Mobile Phone Accessories Market | 2026-2036
Asia-Pacific Mobile Phone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mobile Phone Accessories Market Outlook
Market Context with Strategic Players
The premium wireless audio tier is repositioning away from commodity charging cables on brand equity and codec performance. Sony Corporation leverages proprietary LDAC technology to sustain price premiums in Japan and South Korea. Xiaomi Corporation anchors volume through ecosystem bundling with smartphones across India and Southeast Asia. Samsung Electronics Co., Ltd. competes by integrating Galaxy Buds with its device ecosystem, forcing rivals to differentiate on cross-platform compatibility.
Technical Definition and Structural Segments
Asia-Pacific mobile phone accessories encompass electromechanical and passive components—ranging from lithium-ion charging banks with 20W–65W output ratings to tempered glass screen protectors rated at 9H Mohs hardness—designed to extend device functionality, durability, and user convenience. Chargers and earphones command the deepest margin pools as USB-C Power Delivery and true wireless stereo protocols displace legacy micro-USB and 3.5mm analog connections. Cases in silicone and glass hybrid compositions dominate unit volume, while metal-framed variants occupy the premium architectural segment where drop-test certification drives purchasing.
Regulatory Frame and Forward-Looking Close
China's SAMR enforces GB standards for lithium battery safety in power banks, while India's BIS mandates compulsory registration for electronic accessories under the Compulsory Registration Scheme; both frameworks raise compliance costs for unbranded imports and redirect procurement toward certified manufacturers. Japan's METI energy-efficiency labeling for charging adapters further segments efficient GaN-based designs from legacy silicon units. Stakeholders must monitor how ASEAN harmonization of electronics safety protocols reshapes cross-border supply routing and warehouse qualification requirements.
Market Dynamics
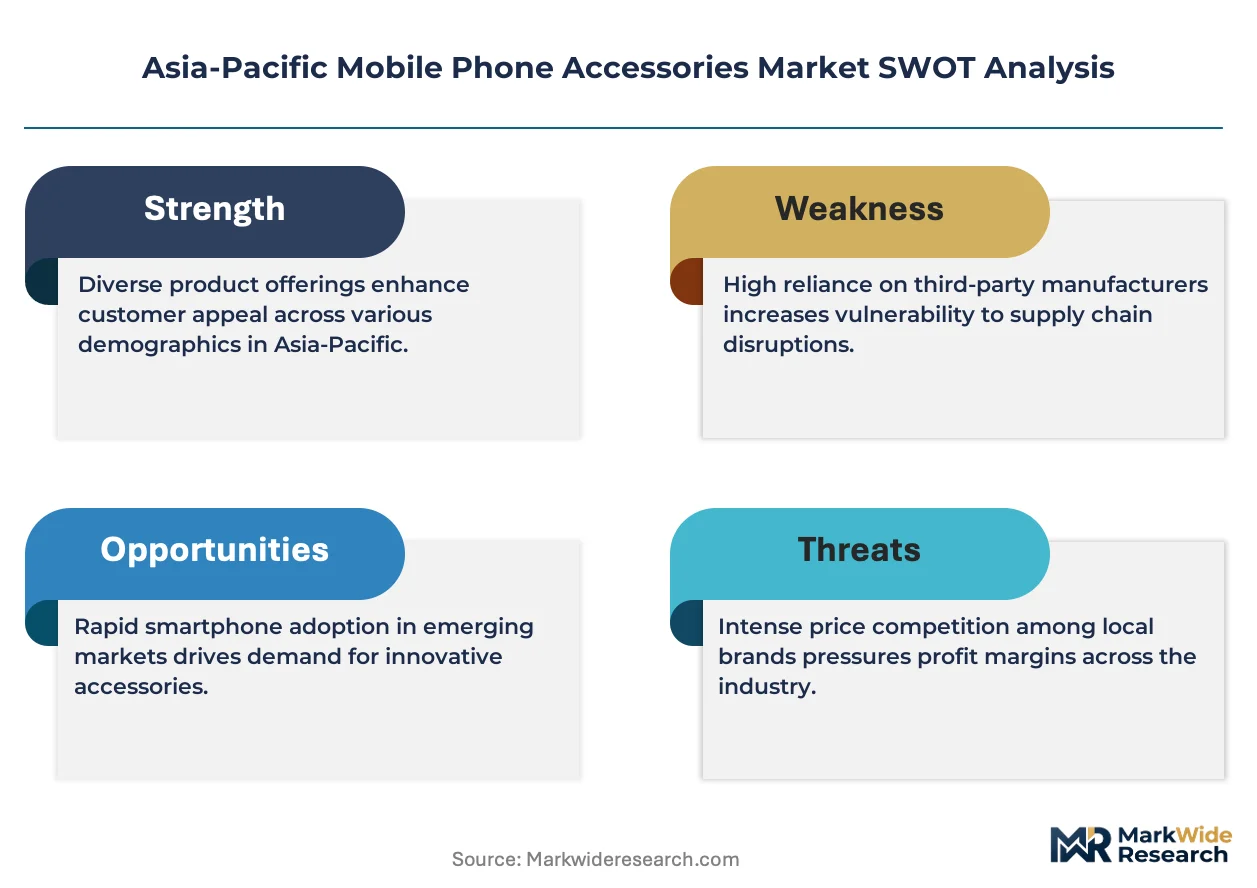
USB-C Power Delivery standardization is compressing charger margins while GaN semiconductor adoption redistributes value toward thermal-efficient designs across Southeast Asian manufacturing clusters.
Growth Catalysts
- India's BIS Compulsory Registration Scheme:Mandatory certification for electronic accessories redirects procurement toward certified domestic manufacturers, elevating quality benchmarks across power banks and adapters.
- True Wireless Stereo protocol penetration:Young professionals in Jakarta, Bangkok, and Ho Chi Minh City drive replacement cycles for wireless earbuds as primary audio devices.
- 20W–65W fast-charging infrastructure:Lithium-ion power bank demand accelerates in China's tier-two manufacturing cities where device density supports peripheral ecosystems.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs fluctuate with electric vehicle demand competition, squeezing power bank assembler margins.
- Shenzhen-Shenzhen supplier concentration:Overreliance on Pearl River Delta contract manufacturers creates single-point vulnerability for regional distribution networks.
- Micro-USB inventory overhang:Legacy connector stockpiles in Indonesian and Philippine retail channels delay full USB-C transition and tie up working capital.
Strategic Opportunities
- Vietnam's northern industrial corridor:Underpenetrated accessory assembly capacity offers alternative sourcing as China labor costs rise.
- Japan's METI energy-efficiency labeling:Regulatory preference for GaN-based adapters creates premium positioning for compliant manufacturers against silicon legacy units.
- E-commerce direct-to-consumer channels:Platform-native brands bypass traditional distributor markups in India's tier-two cities where smartphone penetration outpaces retail infrastructure.
Industry Challenges
- Cross-border GB standard harmonization:China's SAMR lithium battery safety certifications require rework for ASEAN market entry, extending product launch timelines.
- Codec licensing complexity:LDAC, aptX, and AAC intellectual property negotiations fragment wireless audio feature parity across price tiers.
- Drop-test certification capex:MIL-STD-810G and equivalent durability testing equipment demands upfront investment for premium case manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mobile Phone Accessories Market |
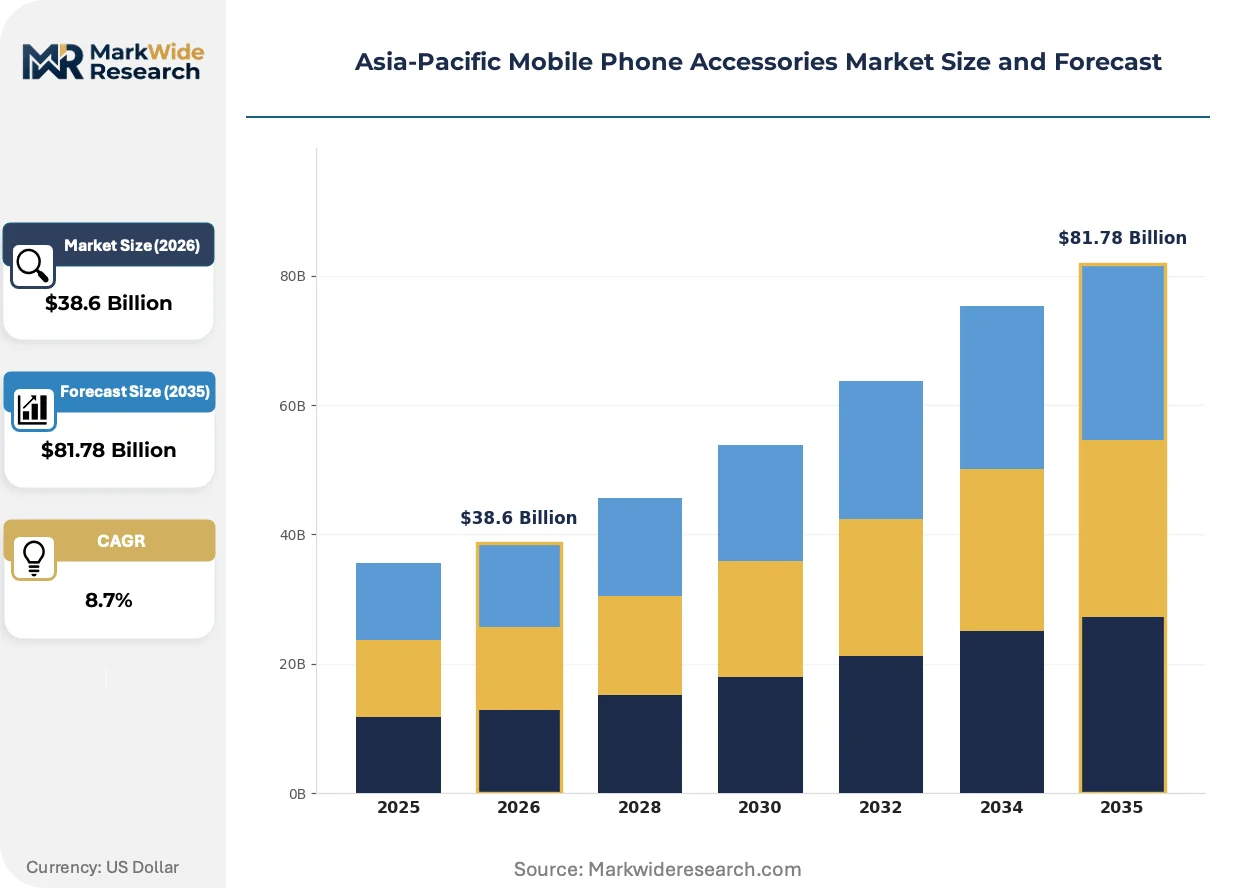
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cases, Chargers, Screen Protectors, Earphones End User: Consumers, Enterprises, Retailers, Distributors Material: Plastic, Silicone, Glass, Metal Distribution Channel: Online, Offline, Retail Stores, Wholesalers |
| Companies Covered | Sony Corporation, Anker Innovations Ltd., Samsung Electronics Co., Ltd., Bose Corporation, Belkin International, Inc., Apple Inc., Huawei Technologies Co. Ltd., Panasonic Corporation, Xiaomi Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mobile Phone Accessories Market Strategic Shifts
GaN semiconductor technology is actively redrawing competitive boundaries in charging peripherals, while regulatory energy-efficiency mandates and platform-driven distribution reshape how accessories reach end-users.
Gallium nitride power semiconductors enable 65W output in adapters one-third the volume of silicon equivalents. Chinese original design manufacturers in Dongguan and Shenzhen are adopting GaN at scale for export markets. This thermal efficiency breakthrough is decentralizing production capacity away from legacy silicon foundry regions toward specialized compound semiconductor facilities.
Japan's METI energy-efficiency labeling program for charging adapters took full effect in 2023, mandating standby power thresholds. The regulation forces importers to source GaN designs or exit the premium segment entirely. Korean and Taiwanese adapter suppliers are responding fastest, while mainland China manufacturers face certification backlog at METI-accredited testing laboratories.
Live commerce and short-video platform storefronts now capture double-digit share of wireless audio sales in Indonesia and Thailand. Traditional electronics distributors in Jakarta and Bangkok are losing shelf-space leverage as creators demonstrate product features in real-time purchase environments. This channel migration is most visible among 18–29 year-old buyers in Southeast Asian capital cities where trust transfers from retail clerks to content creators.
Asia-Pacific Mobile Phone Accessories Market Segmentation
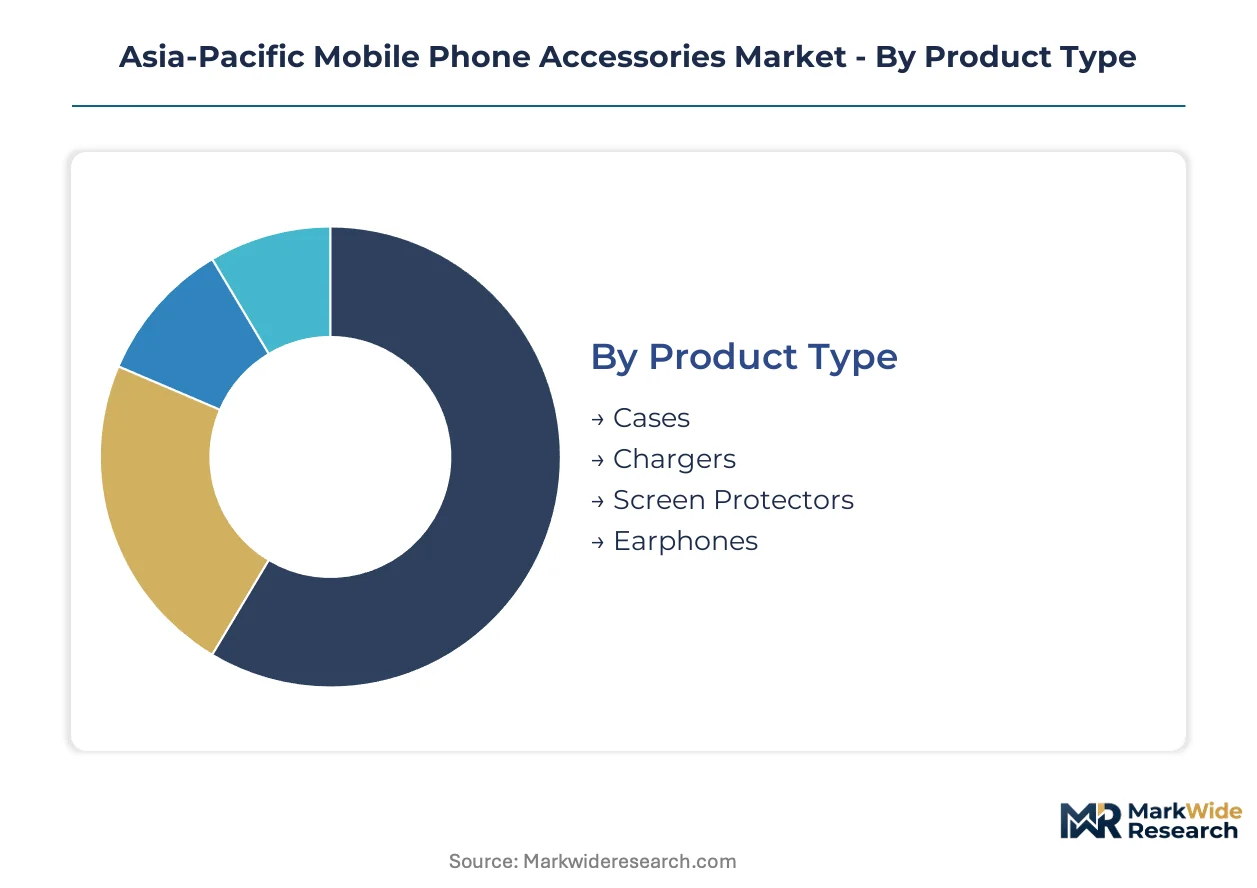
Segmentation in Asia-Pacific mobile phone accessories reveals how purchasing power, device replacement cycles, and retail infrastructure maturity create divergent margin pools across product categories. Understanding these fault lines enables manufacturers to align SKU portfolios with the region's tiered urban development patterns.
Product Type:
Buyers differentiate on functional urgency versus discretionary upgrade appetite, with protective gear serving immediate device preservation needs while audio peripherals satisfy experiential enhancement demands.
- Cases:Silicone and glass hybrid compositions dominate unit volume through mass-market penetration in India's tier-two cities, where drop-test anxiety drives replacement purchases at sub-$15 price points. Glass hybrid variants command premium positioning in Tokyo and Seoul where MIL-STD-810G certification justifies architectural differentiation.
- Chargers:USB-C Power Delivery adapters with 20W–65W output ratings concentrate demand in China's manufacturing clusters, where device density and multi-device ownership patterns accelerate fast-charging infrastructure adoption. GaN semiconductor integration enables thermal-efficient designs that segment premium positioning from legacy silicon units under Japan's METI energy-efficiency labeling.
- Screen Protectors:Tempered glass rated at 9H Mohs hardness anchors replacement cycles in Jakarta and Bangkok retail channels, where installation service bundling sustains margin capture.
- Earphones:True wireless stereo protocol penetration climbs fastest among young professionals in Ho Chi Minh City, where codec performance and cross-platform compatibility drive brand switching.
Volume sits with Cases; growth tilts toward Chargers.
End User:
Purchasing behavior fragments across procurement sophistication, from individual upgrade decisions to enterprise fleet standardization mandates.
- Consumers:Individual buyers in Southeast Asian capital cities drive wireless audio replacement cycles through platform-native discovery on live commerce channels, bypassing traditional distributor markups.
- Enterprises:Corporate fleet procurement in India's expanding tier-two cities standardizes on certified power banks under BIS Compulsory Registration Scheme compliance, redirecting volume toward domestic manufacturers.
- Retailers:Electronics distributors in Jakarta and Bangkok face shelf-space leverage erosion as short-video storefronts capture double-digit share of wireless audio sales.
- Distributors:Regional logistics operators navigate cross-border GB standard harmonization requirements that extend product launch timelines for ASEAN market entry.
Procurement sophistication deepens fastest among Enterprises; transaction frequency peaks with Consumers.
Material:
Cost-to-performance ratios and manufacturing process scalability determine competitive viability across material classes.
- Plastic:Injection-molded polycarbonate dominates economy-tier case production in Vietnam's northern industrial corridor, where labor cost arbitrage supports export competitiveness.
- Silicone:Thermoplastic elastomer formulations capture mid-tier positioning through grip texture differentiation and shock absorption certification in drop-test protocols.
- Glass:Tempered aluminosilicate screen protector substrates concentrate production in Dongguan and Shenzhen manufacturing clusters, where precision cutting equipment achieves economies of scale.
- Metal:Aluminum alloy framing occupies premium architectural segments in Japan and South Korea, where CNC machining tolerances justify price premiums against polymer alternatives.
Manufacturing scale favors Plastic; margin expansion concentrates with Metal.
Distribution Channel:
Channel selection reflects trust formation mechanisms and infrastructure maturity across urban development tiers.
- Online:E-commerce direct-to-consumer channels in India's tier-two cities exploit smartphone penetration outrunning physical retail infrastructure, enabling platform-native brands to bypass traditional markups.
- Offline:Electronics malls and carrier stores in Seoul and Tokyo sustain premium positioning through tactile product demonstration and immediate fulfillment.
- Retail Stores:Neighborhood mobile accessory shops in Indonesian and Philippine markets struggle with Micro-USB inventory overhang that delays full USB-C transition and ties up working capital.
- Wholesalers:Pearl River Delta supplier concentration creates single-point vulnerability for regional distribution networks serving Southeast Asian markets.
Transaction velocity accelerates through Online channels; service attachment sustains Offline relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors production capacity for the Asia-Pacific mobile phone accessories market, with Dongguan and Guangzhou manufacturing clusters supplying USB-C Power Delivery adapters and tempered glass screen protectors across regional distribution networks.
China
Domestic consumption of 65W GaN chargers accelerates in Shanghai and Beijing where multi-device ownership patterns support fast-charging infrastructure deployment. SAMR enforces GB standards for lithium battery safety in power banks, raising compliance costs for unbranded imports. Dongguan precision cutting equipment achieves economies of scale for tempered aluminosilicate screen protector substrates.
India
Enterprise fleet procurement in Bengaluru and Hyderabad standardizes on certified power banks as smartphone penetration outpaces retail infrastructure in tier-two cities. BIS mandates compulsory registration for electronic accessories under the Compulsory Registration Scheme, redirecting volume toward domestic manufacturers. Delhi-NCR logistics operators navigate cross-border certification requirements for ASEAN market entry.
Japan
Premium wireless audio replacement cycles concentrate in Tokyo and Osaka where LDAC codec performance sustains price premiums. METI energy-efficiency labeling for charging adapters forces importers to source GaN designs or exit the premium segment entirely. Nagoya testing laboratories face certification backlog from mainland China manufacturers.
South Korea
Galaxy Buds ecosystem integration drives wireless audio demand in Seoul where cross-platform compatibility forces rival differentiation. MFDS maintains medical-grade standards for wearable audio devices with biometric sensors. Busan-Ulsan industrial corridor supplies compound semiconductor materials for GaN adapter production.
Vietnam
Underpenetrated accessory assembly capacity in the northern industrial corridor offers alternative sourcing as China labor costs rise. Young professionals in Ho Chi Minh City drive true wireless stereo protocol penetration through platform-native discovery channels. Hai Phong port infrastructure supports export routing for Dongguan-sourced component kits.
Asia-Pacific Mobile Phone Accessories Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific mobile phone accessories market. The vendor base stratifies into three tiers: integrated electronics conglomerates with captive semiconductor supply, original design manufacturers with Pearl River Delta fabrication relationships, and platform-native brands exploiting direct-to-consumer channels. Strategic moves concentrate on GaN semiconductor licensing partnerships and live commerce storefront acquisitions that bypass traditional distributor markups.
Among integrated electronics conglomerates, Sony Corporation and Samsung Electronics Co., Ltd. exemplify ecosystem-lock strategies through proprietary codec and device pairing technologies. Xiaomi Corporation occupies a position between scale manufacturing and platform distribution, leveraging smartphone bundling to anchor volume in price-sensitive segments. Anker Innovations Ltd. represents the specialist archetype, concentrating adapter and power bank design without captive device ecosystems.
| Leading Market Players |
|---|
| Sony Corporation |
| Anker Innovations Ltd. |
| Samsung Electronics Co., Ltd. |
| Bose Corporation |
| Belkin International, Inc. |
| Apple Inc. |
| Huawei Technologies Co. Ltd. |
| Panasonic Corporation |
| Xiaomi Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BIS-registered and unbranded accessories splits both pricing power and procurement routing across India and Southeast Asia. Premium positioning rests on GaN thermal efficiency and METI compliance, while commodity tiers compete on labor arbitrage from Vietnam's northern corridor.
Pricing Analysis
Value-based pricing anchors on charging throughput and codec performance rather than unit cost. Three-tier pricing structure across premium, standard, and economy levels separates GaN-certified adapters from silicon legacy units and unbranded imports. Price differentiation stems from BIS registration status and Japan's METI energy-efficiency labeling. Cost compression in economy-tier chargers is intensifying because USB-C Power Delivery standardization erodes feature premiums. Enterprise fleet buyers in India's tier-two cities exhibit highest price sensitivity; Tokyo and Seoul consumers show lowest sensitivity when LDAC or MIL-STD-810G certification is present.
Supply Chain Analysis
Workforce availability constraints in Dongguan and Shenzhen are pushing assembly capacity toward Vietnam's Hai Phong corridor and India's Delhi-NCR logistics nodes. Geographic supply concentration centers on China for precision-cut tempered glass and compound semiconductor substrates, Vietnam for injection-molded polycarbonate cases, and South Korea for wireless audio chipsets. Raw material dependencies draw from lithium carbonate for power banks, gallium nitride wafers for adapters, and aluminosilicate glass for screen protectors. Single-source vulnerability concentrates in Pearl River Delta contract manufacturers. Distribution runs through platform-native direct-to-consumer channels in Indonesia and Thailand alongside traditional electronics malls in Seoul and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification compliance and thermal efficiency leadership, with BIS mandates and GaN adoption forcing unbranded assemblers toward exit.
For Market Incumbents: Deploy GaN licensing partnerships to secure premium positioning before METI labeling fully displaces silicon inventory. Acquire live commerce storefronts in Jakarta and Bangkok to bypass distributor markups eroding traditional channel leverage. Defensive moves must address platform-native brands capturing wireless audio share through creator-driven discovery. For New Entrants and Emerging Players: E-commerce platform operators represent the fastest path to shelf space in India's tier-two cities where retail infrastructure lags smartphone penetration. White-space targets include certified power bank assembly for enterprise fleets and GaN adapter production for Japanese import compliance. Go-to-market execution should anchor on short-video demonstration formats that transfer trust from retail clerks to content creators. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-native brand acquisitions by integrated electronics conglomerates seeking direct-to-consumer channel control. Long-term viability favors compound semiconductor facilities and METI-accredited testing laboratories over legacy silicon foundry exposure. The signal to watch is ASEAN harmonization progress on lithium battery safety protocols, which would reshape cross-border warehouse qualification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Licensing Partnership | Secures thermal efficiency positioning under Japan's METI energy-efficiency labeling mandates. |
| Live Commerce Storefront Acquisition | Bypasses traditional distributor markups in Jakarta and Bangkok retail channels. |
| BIS Certification Investment | Redirects procurement toward compliant manufacturers under India's Compulsory Registration Scheme. |
| Vietnam Assembly Capacity Expansion | Captures labor cost arbitrage as China manufacturing wages rise in Dongguan. |
| Cross-Platform Codec Development | Differentiates wireless audio against Samsung's Galaxy Buds ecosystem lock-in. |
Study Parameters
Trade databases, customs filings, and regulatory registration records formed the secondary backbone for this Asia-Pacific mobile phone accessories analysis. Primary interviews with ODM procurement managers, platform-native brand operators, electronics distributor category heads, and BIS certification consultants validated supply-side and demand-side assumptions. Bottom-up triangulation across component shipment data and top-down reconciliation against end-user device penetration statistics anchored volume estimates.
Historical trendline analysis of lithium-ion power bank and GaN adapter shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-user procurement sophistication, material class, and distribution channel maturity. CAGRs were derived from weighted average of trend extrapolation and driver-based elasticity estimates. Forecast inputs included BIS registration velocity, METI certification backlog duration, and live commerce transaction share in Southeast Asian capital cities.
Caveats apply where lithium carbonate price volatility, ASEAN harmonization delays, or platform algorithm changes could materially shift the outlook. Forecasts reflect documented assumptions about USB-C transition speed and GaN cost-down curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Smart TV Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Action Camera Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Headphones Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Mobile Cases and Covers Market