
 DVD Remote Controls Market | 2026-2036
DVD Remote Controls Market Size, Share, and Industry Trends Forecast 2026-2036
DVD Remote Controls Market Analytics
The EU RoHS directive is repositioning remote control manufacturers toward halogen-free circuit boards and restricted substance compliance across export-bound production lines. Sony leverages its vertically integrated semiconductor fabrication to sustain cost advantages in infrared transmitter modules. Panasonic anchors its position through specialized manufacturing scale in Malaysian assembly plants serving Asian and European OEM contracts. Logitech competes by extending its Harmony programming platform into legacy DVD compatibility, differentiating through software rather than hardware refresh cycles.
A DVD remote control is a handheld wireless input device employing infrared light-emitting diodes or radio frequency transceivers to transmit encoded command signals to a DVD player's onboard receiver, typically operating at wavelengths near 940 nanometers with modulation frequencies between 36 and 40 kilohertz. Its primary commercial purpose is to enable user navigation of optical disc menus, playback functions, and system settings without physical contact with the player unit. Universal remotes occupy the largest volume tier as consumers consolidate multiple legacy devices under single controllers, while smart remotes integrating Bluetooth and Wi-Fi connectivity represent the fastest-expanding technology segment despite higher unit costs. Gaming remotes constitute a niche margin pool, serving specialized aftermarket demand from arcade cabinet builders and retro gaming enthusiasts who require dedicated button mapping for DVD-based game systems.
The Federal Communications Commission regulates RF-enabled remotes through Part 15 emissions standards, while CE marking under the EU Radio Equipment Directive governs market access for Bluetooth and Wi-Fi variants sold in Europe. Japan's Ministry of Economy, Trade and Industry enforces JIS standards for electromagnetic compatibility that shape design specifications for remotes targeting premium electronics channels. Stakeholders must monitor regulatory divergence between infrared-exempt legacy classifications and emerging connected-device frameworks that impose cybersecurity and interoperability testing burdens on smart remote platforms.
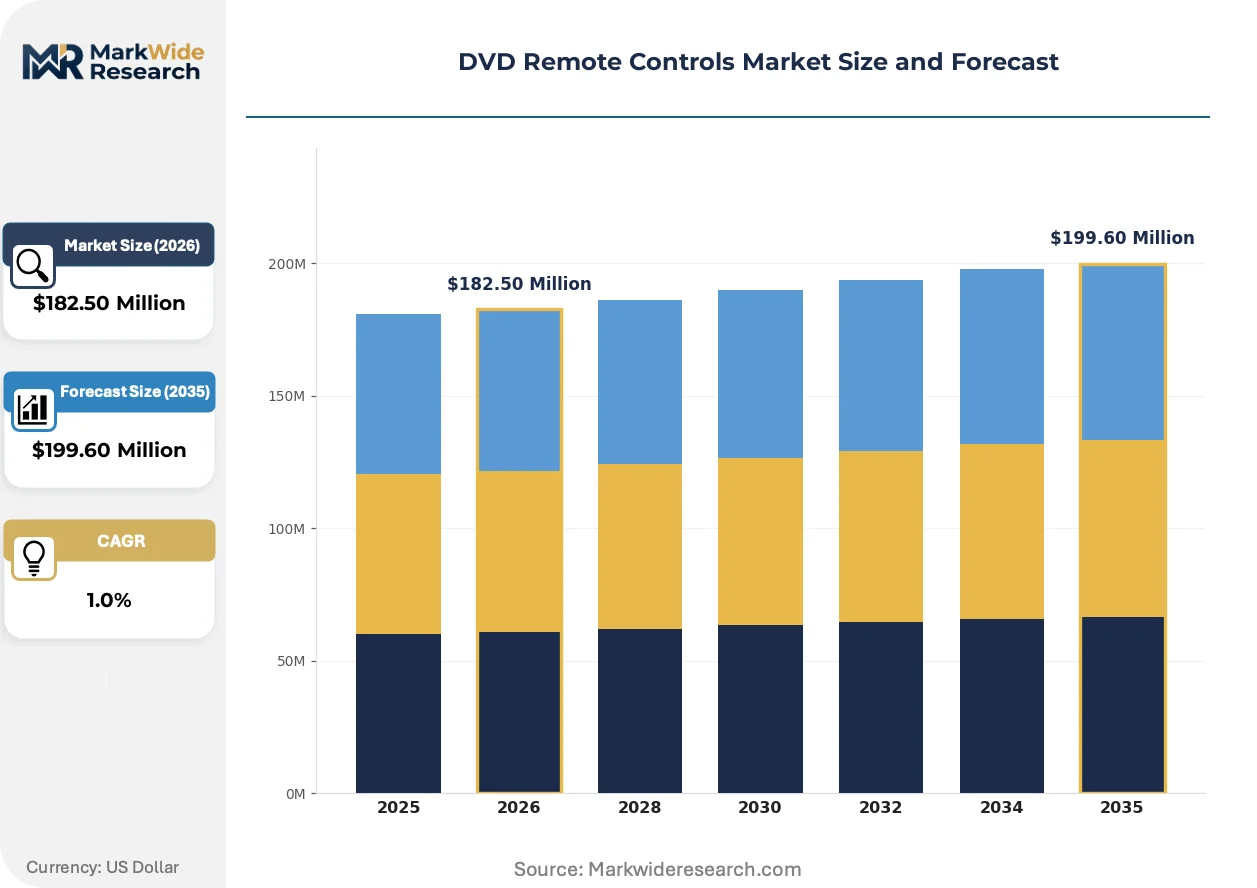
Market Dynamics
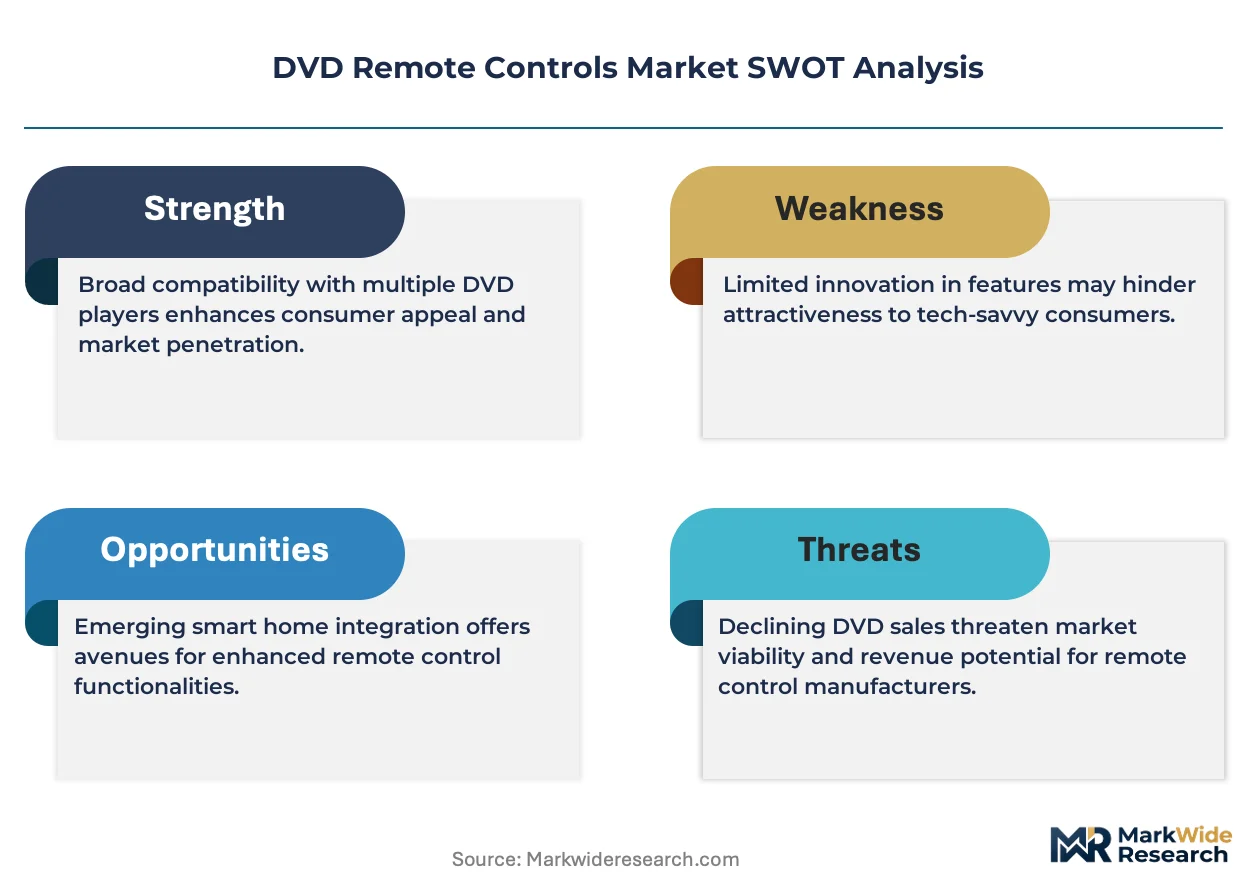
The DVD Remote Controls Market is contracting around legacy device maintenance as streaming platforms displace optical disc playback, forcing manufacturers to pivot toward universal compatibility and collector-tier specialization to sustain replacement demand.
Growth Catalysts
- RoHS Directive Compliance:The European Union's hazardous substance restrictions are accelerating material transitions to lead-free solder and recycled polymers, opening premium positioning for compliant OEM suppliers.
- Collector Market Concentration:Enthusiast communities in the United States and Japan are preserving demand for original-equipment replacement remotes and aftermarket reproductions with period-accurate button layouts.
- Infrared Module Miniaturization:Advances in surface-mount diode packaging are reducing PCB footprint requirements, enabling slimmer industrial designs and lower assembly costs.
Market Restraints
- Input Cost Volatility:ABS plastic resin and copper trace materials face price instability tied to petrochemical feedstock fluctuations, compressing margin buffers for mid-tier producers.
- Substitution by Streaming Interfaces:Smart TV operating systems and mobile application control layers are eliminating dedicated remote dependency for content navigation.
- Supply Concentration Risk:Malaysian and Vietnamese contract manufacturers dominate final assembly capacity, creating vulnerability to regional logistics disruptions.
Strategic Opportunities
- Retro Gaming Integration:Arcade cabinet builders and home theater enthusiasts are sourcing programmable remotes with macro-capable button mapping for DVD-based game systems.
- CE Marking Expansion:The EU Radio Equipment Directive is creating certification arbitrage opportunities for Bluetooth-enabled smart remotes that bypass infrared legacy classifications.
- Refurbishment Channel Development:Secondary market platforms and electronics recyclers are establishing certified pre-owned remote programs with warranty backing.
Industry Challenges
- Electromagnetic Compatibility Testing:RF-enabled variants require FCC Part 15 and CE RED certification cycles that extend time-to-market by four to eight months.
- Firmware Integration Complexity:Universal remote databases must maintain compatibility with thousands of legacy DVD player IR code sets, demanding ongoing cloud infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DVD Remote Controls Market |
| Market Size in 2026 | $182.50 Million |
| Market Size in 2035 | $199.60 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Remotes, Basic Remotes, Smart Remotes, Gaming Remotes Technology: Infrared, RF, Bluetooth, Wi-Fi End User: Residential, Commercial, Educational, Entertainment Pricing Model: Budget, Mid-Range, Premium, Value Packs |
| Companies Covered | Sony, Panasonic, Logitech, Philips, Samsung, Universal Electronics, One For All, RCA, GE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DVD Remote Controls Market Evolving Landscape
Component miniaturization and regulatory recalibration are reshaping how DVD remote controls are engineered, certified, and distributed across shrinking but specialized demand pools.
Bluetooth Low Energy transceivers are integrating into premium remote architectures to enable bidirectional communication with connected DVD players and home theater receivers. Home theater installers and enthusiast buyers are adopting these variants despite unit cost premiums of forty to sixty percent over infrared-only alternatives. The technology is integrating voice-assistant wake-word detection and hub-based automation protocols, compressing the addressable market for standalone infrared-only designs.
The EU RoHS directive's recast amendments are tightening thresholds for cadmium and lead content in electrical contacts and solder joints. Manufacturers serving European distribution channels are retooling surface-mount lines to accommodate tin-silver-copper alloy compositions and halogen-free substrate materials. Bluetooth and Wi-Fi enabled remotes face heightened scrutiny under the Radio Equipment Directive's cybersecurity annex, extending conformity assessment timelines for connected-device platforms.
Collector communities are consolidating purchasing through specialized online marketplaces and enthusiast forums rather than mass retail channels. These buyers prioritize original manufacturer markings, period-correct button textures, and documented provenance over price-sensitive commodity alternatives. Japan's METI standards for electromagnetic compatibility are influencing specification requirements for remotes targeting premium electronics resale channels in Tokyo and Osaka metropolitan clusters.
DVD Remote Controls Market Segmentation
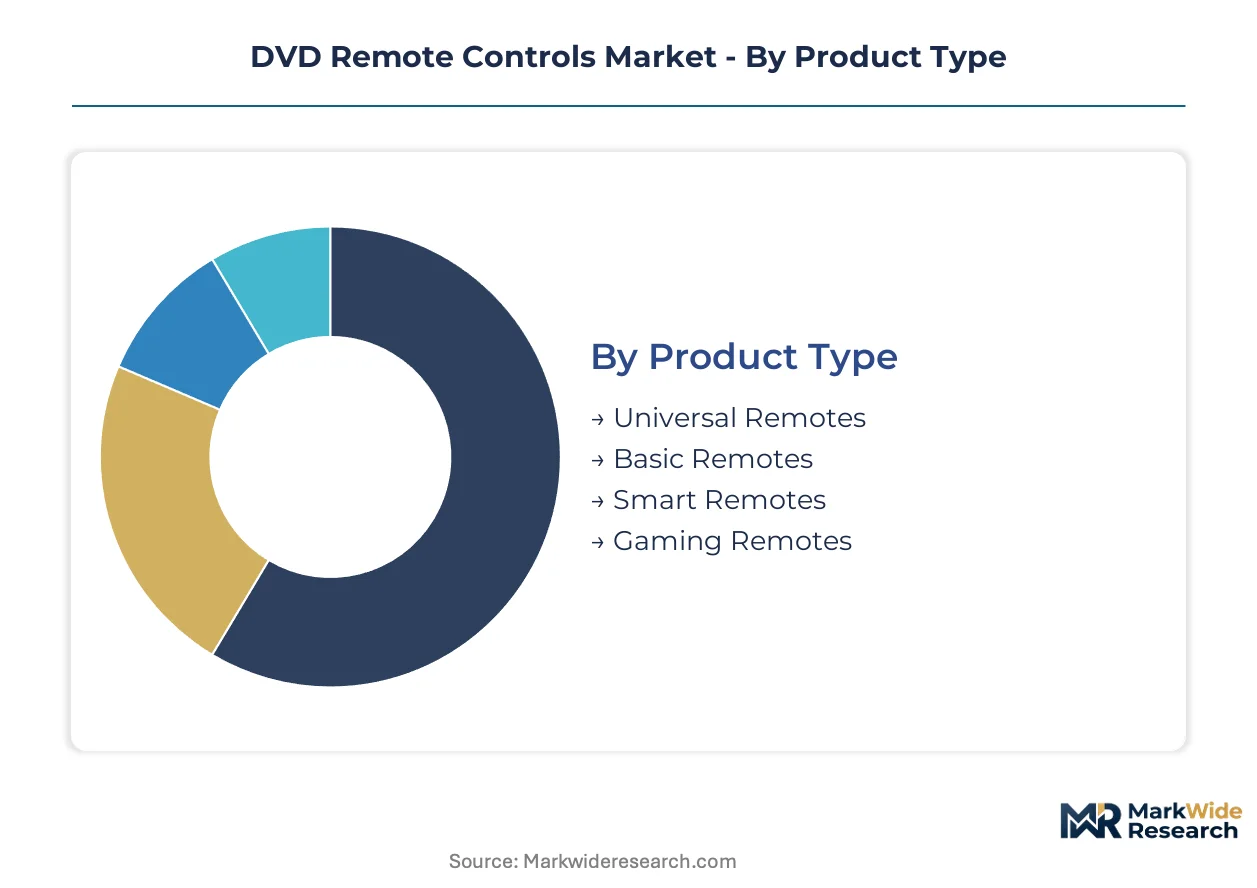
Remote control segmentation reveals divergent engineering priorities between legacy infrared maintenance and connected-device expansion. Each category exposes distinct margin structures and certification burdens that reshape supplier positioning across shrinking but specialized demand pools.
Product Type:
Infrared emitter specifications and programmable memory capacity differentiate functional tiers across replacement and upgrade cycles.
- Universal Remotes:Multi-device programmable units store thousands of IR code sets in onboard EEPROM or cloud-synced databases. Demand concentrates in United States residential markets where consumers consolidate legacy DVD, cable, and audio equipment under single controllers to reduce clutter.
- Smart Remotes:Bluetooth and Wi-Fi enabled variants integrate voice-assistant wake-word detection and hub-based automation protocols. These command forty to sixty percent unit cost premiums and are expanding most quickly among home theater installers and enthusiast buyers seeking bidirectional communication with connected receivers.
- Basic Remotes:Single-device infrared units with fixed code sets serve replacement demand for specific DVD player models. Collector communities in Japan prioritize original-equipment markings and period-accurate button textures over commodity alternatives.
- Gaming Remotes:Specialized controllers with macro-capable button mapping serve arcade cabinet builders and retro gaming enthusiasts requiring dedicated layouts for DVD-based game systems.
Mature deployment sits with Basic Remotes. Newer deployment is concentrated in Smart Remotes.
Technology:
Transmission protocols determine regulatory jurisdiction, certification timeline, and component cost structure for each remote architecture.
- Infrared:Legacy 940-nanometer wavelength transmission at 36-40 kilohertz modulation requires no RF certification and maintains lowest bill-of-materials cost. Surface-mount diode miniaturization is reducing PCB footprint requirements for slimmer industrial designs.
- Bluetooth:Low Energy transceivers enable bidirectional communication and integrate with home automation hubs. FCC Part 15 and CE RED certification cycles extend time-to-market by four to eight months, compressing addressable market for standalone infrared-only designs.
- RF:Radio frequency variants operating in unlicensed bands penetrate cabinet enclosures and eliminate line-of-sight requirements. These serve commercial installations where equipment sits in enclosed racks.
- Wi-Fi:Direct IP connectivity enables firmware updates and cloud-based code library expansion. Cybersecurity annex requirements under EU Radio Equipment Directive impose additional conformity assessment burdens.
Mature deployment sits with Infrared. Newer deployment is concentrated in Bluetooth.
End User:
Application environment shapes durability specifications, warranty expectations, and procurement channel preferences across customer categories.
- Residential:Home theater enthusiasts and collector communities sustain replacement demand through specialized online marketplaces and enthusiast forums rather than mass retail channels.
- Commercial:Corporate training facilities and hospitality installations require bulk procurement of standardized remotes with consistent button layouts across multiple locations.
- Educational:School districts and university media centers maintain legacy DVD equipment for curriculum materials and prioritize budget-tier universal compatibility.
- Entertainment:Arcade operators and home theater installers source programmable units with macro-capable mapping for specialized playback environments.
Mature deployment sits with Residential. Newer deployment is concentrated in Commercial.
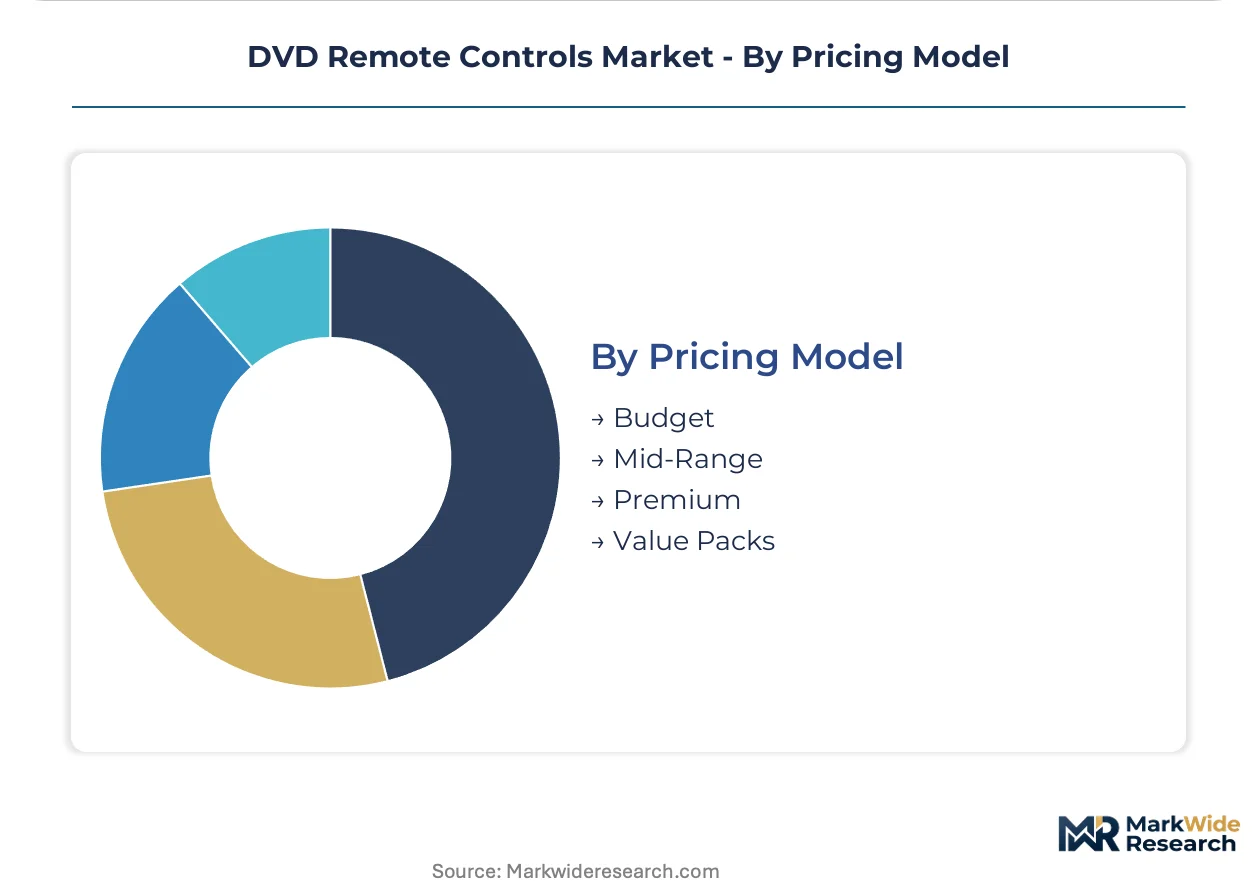
Pricing Model:
Cost tier alignment reflects certification grade, component specification, and volume scale rather than brand premium alone.
- Budget:Fixed-code infrared units with ABS housings and membrane switch assemblies serve price-sensitive replacement demand in educational and secondary market channels.
- Mid-Range:Programmable universal units with rubberized button overlays and extended IR code databases balance functionality against cost constraints in residential upgrade cycles.
- Premium:Metal-finish housings, backlit buttons, and rechargeable lithium-polymer batteries target enthusiast buyers prioritizing industrial design and build quality.
- Value Packs:Multi-unit bundles with shared code libraries reduce per-remote cost for commercial installations requiring standardized controller fleets across multiple rooms.
Mature deployment sits with Budget. Newer deployment is concentrated in Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor anchors manufacturing capacity for infrared transmitter modules and surface-mount assembly serving export markets. The Pearl River Delta's component ecosystem supplies die-cast housings and membrane switch assemblies to OEM brands worldwide.
United States
Legacy DVD player ownership and collector markets in California and Texas sustain replacement remote purchases through specialized online marketplaces. The FCC's Part 15 emissions standards regulate RF-enabled remotes entering commercial channels. Chicago's electronics resale clusters serve enthusiast buyers prioritizing original-equipment markings.
Japan
Premium electronics resale channels in Tokyo and Osaka metropolitan clusters drive demand for period-accurate button textures and documented provenance. METI enforces JIS standards for electromagnetic compatibility that shape design specifications. Nagoya's industrial belt hosts specialized manufacturing for high-fidelity infrared modules.
Germany
RoHS directive compliance requirements are repositioning material choices toward lead-free solder and recycled plastics for export-bound production lines. CE marking under the EU Radio Equipment Directive governs market access for Bluetooth variants. Bavaria's precision electronics sector supplies halogen-free circuit board substrates.
Malaysia
Contract manufacturers in Penang and Selangor dominate final assembly capacity for Asian and European OEM contracts. Regional logistics disruptions create supply concentration vulnerability for mid-tier producers. Johor's free trade zones facilitate duty-efficient component sourcing for re-export programs.
United Kingdom
Home theater enthusiasts in Greater London and the Southeast consolidate legacy devices under single universal controllers. The UK's post-EU regulatory alignment maintains RoHS substance restrictions on imported electronics. Manchester's refurbishment channels are establishing certified pre-owned remote programs with warranty backing.
DVD Remote Controls Market Competitive Landscape
The competitive structure tilts toward vertically integrated electronics conglomerates with captive semiconductor fabrication. Tiered specialization separates universal database platforms from commodity infrared replacement suppliers. Two strategic archetypes dominate: integrated OEMs controlling upstream component supply, and programmable platform specialists differentiating through software ecosystems. Capacity expansion in Malaysian assembly plants and strategic partnerships for voice-assistant integration represent the dominant competitive moves.
Among Japanese electronics conglomerates, Sony and Panasonic exemplify the integrated OEM archetype through upstream control over transmitter module production. Logitech occupies a position within the programmable platform tier, differentiating through extended compatibility databases rather than hardware refresh cycles. These three companies represent the span of competitive positioning from component-level vertical integration to software-centric ecosystem plays.
| Leading Market Players |
|---|
| Sony |
| Panasonic |
| Logitech |
| Philips |
| Samsung |
| Universal Electronics |
| One For All |
| RCA |
| GE |
| Others |
Value Network & Pricing Analysis
Collector-grade procurement specifications for period-accurate button textures and original-equipment markings are forcing contract manufacturers to retain legacy tooling and specialized assembly lines, compressing margin flexibility across mid-tier suppliers serving enthusiast channels.
Pricing Analysis
Certification-grade pricing anchors value to CE marking and FCC Part 15 compliance timelines, with Bluetooth-enabled variants commanding premiums tied to four-to-eight-month regulatory cycles. Three-tier pricing structure across premium, standard, and economy levels separates metal-finish enthusiast units from rubberized mid-range programmable controllers and fixed-code budget replacements. Cost compression in the budget tier is intensifying because ABS resin and copper trace volatility erodes assembler buffers. Educational institutions exhibit highest price sensitivity, while home theater installers absorb premium markups for bidirectional connectivity.
Supply Chain Analysis
Certified pre-owned refurbishment flows through Manchester and Chicago resale clusters are extending product lifecycles and diverting volume from primary manufacturing channels. Final assembly concentrates in Malaysia, Vietnam, and China's Pearl River Delta, drawing from Shenzhen's infrared module ecosystem and die-cast housing suppliers. Copper trace substrates and halogen-free circuit boards rest on petrochemical feedstock and RoHS-compliant mineral sourcing. Single-source vulnerability sits with Malaysian contract manufacturers dominating Asian and European OEM capacity. Distribution runs through specialized online marketplaces and enthusiast forums rather than mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with captive semiconductor fabrication and in-house transmitter module production determining cost position against programmable platform competitors.
For Market Incumbents: Hedge against streaming substitution by deepening Harmony-style software ecosystem investments and securing long-term code library maintenance contracts. Defend margin position through backward integration into surface-mount diode packaging, reducing dependency on Shenzhen component suppliers. RoHS recast amendments threaten non-compliant inventory obsolescence. For New Entrants and Emerging Players: CE marking under the EU Radio Equipment Directive opens a window for cybersecurity-certified Bluetooth remote specialists to bypass infrared legacy classifications. Target the retro gaming integration segment, where arcade cabinet builders seek macro-capable programmable units with dedicated button mapping. Go-to-market through specialized enthusiast forums rather than mass retail. For Investors and Strategic Acquirers: The window for entry favors programmable platform specialists with cloud-synced code databases over commodity infrared assemblers. Long-term viability hinges on universal compatibility maintenance as legacy DVD player populations age. Watch for collector marketplace consolidation signals as authentication and provenance services mature.| Strategic Initiative | Industry Significance |
|---|---|
| Voice-Assistant Integration Partnership | Hub-based automation protocols compress standalone infrared-only addressable markets. |
| RoHS Compliance Retooling Investment | Tin-silver-copper alloy transitions preserve European distribution channel access. |
| Refurbishment Channel Certification | Warranty-backed pre-owned programs capture secondary market enthusiast demand. |
| Retro Gaming Controller Specialization | Macro-capable button mapping serves DVD-based arcade cabinet builders. |
| Malaysian Assembly Capacity Expansion | Penang and Selangor plants anchor Asian and European OEM contract fulfillment. |
Research Methodology
SEC filings, customs trade records, and FCC equipment authorization databases formed the secondary backbone, supplemented by primary interviews with contract manufacturing executives, home theater installation specialists, collector community forum administrators, and electronics refurbishment channel operators. Bottom-up assembly cost modeling triangulated against top-down replacement demand estimates derived from legacy DVD player installed base projections.
Historical trendline analysis of infrared module shipment volumes and Bluetooth certification filings established baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, transmission protocol, end-user environment, and pricing tier dimensions. CAGRs were derived from replacement cycle frequency estimates and collector market penetration rates, with cross-validation against CE marking and FCC Part 15 filing velocity.
The model assumes a particular technology adoption path; alternative pathways for Wi-Fi direct connectivity and mobile application substitution would alter the outlook. Forecasts reflect assumptions regarding RoHS recast implementation timing and streaming platform displacement rates. Practitioners should monitor collector marketplace transaction volumes and refurbishment channel warranty claim rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Tablet Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market