
 Waterproof Speaker Market | 2026-2036
Waterproof Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Speaker Market Analytics
The waterproof speaker category is consolidating around a sharp split between audiophile-grade units commanding triple-digit price points and sub-fifty-dollar commodity models flooding mass retail channels. Ultimate Ears leverages its heritage in professional stage monitoring to sustain premium positioning through ruggedized acoustics. Anker Soundcore competes aggressively on battery efficiency and value engineering, dominating e-commerce shelf space. Bose anchors the high end through proprietary transducer arrays that justify sustained retail premiums.
A waterproof speaker encloses electroacoustic drivers, amplifiers, and power management circuits within sealed polymer housings rated to IEC 60529 ingress protection standards, typically IPX5 through IPX8, enabling audio reproduction in wet, dusty, or submerged environments. Portable Bluetooth configurations lead volume shipments due to lithium-ion energy density improvements and universal smartphone pairing protocols. High-fidelity sound quality segments capture disproportionate margin pools as driver material science advances. Shower speakers represent a maturing niche with saturated household penetration, while floating designs gain traction in pool and marine settings.
IEC 60529 and FCC Part 15 govern ingress protection and radio frequency emissions respectively, with the latter constraining transmitter power and spectrum allocation for Bluetooth and Wi-Fi connectivity variants. REACH and RoHS compliance in Europe restricts halogenated flame retardants and heavy metals in enclosure polymers, elevating material costs for exporters. Stakeholders must monitor evolving battery transport regulations from IATA and national aviation authorities, as lithium-cell capacity thresholds tighten across air freight corridors and reshape regional fulfillment strategies.
Market Dynamics
Waterproof speaker demand is bifurcating sharply between audiophile-grade units and mass-market commodities, with IP67 and IPX8 ratings now table stakes rather than premium differentiators. This compression is forcing manufacturers to differentiate through acoustic engineering, battery chemistry, or marine-specific floating designs.
Growth Catalysts
- Adventure tourism expansion:Outdoor recreation participation in the United States and Germany is accelerating replacement cycles for ruggedized audio equipment.
- IEC 60529 standardization:Universal ingress protection benchmarks reduce consumer confusion and streamline cross-border certification for manufacturers.
- Lithium-ion energy density gains:Improved cell chemistry from South Korean and Japanese suppliers extends playback duration without enclosure volume penalties.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings from Chinese processing concentration compress driver assembly margins unpredictably.
- RoHS and REACH compliance costs:European halogenated flame retardant restrictions elevate enclosure polymer expenses for exporters.
- Smartphone audio quality substitution:Improved onboard speakers in flagship handsets reduce casual buyer willingness to carry secondary devices.
Strategic Opportunities
- India outdoor recreation underpenetration:Emerging middle-class leisure spending creates first-mover positioning for IP-rated audio in trekking and camping segments.
- Marine and pool floating designs:Buoyant form factors with integrated LED lighting capture premium positioning in United States backyard entertainment.
- IATA battery transport thresholds:Tightening lithium-cell air freight regulations favor regional assembly hubs over centralized Far East manufacturing.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in waterproof driver tuning commands premium compensation and extends R&D timelines.
- IPX8 submersion certification duration:Extended IEC validation cycles delay product launches and freeze working capital in pre-production inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Speaker Market |
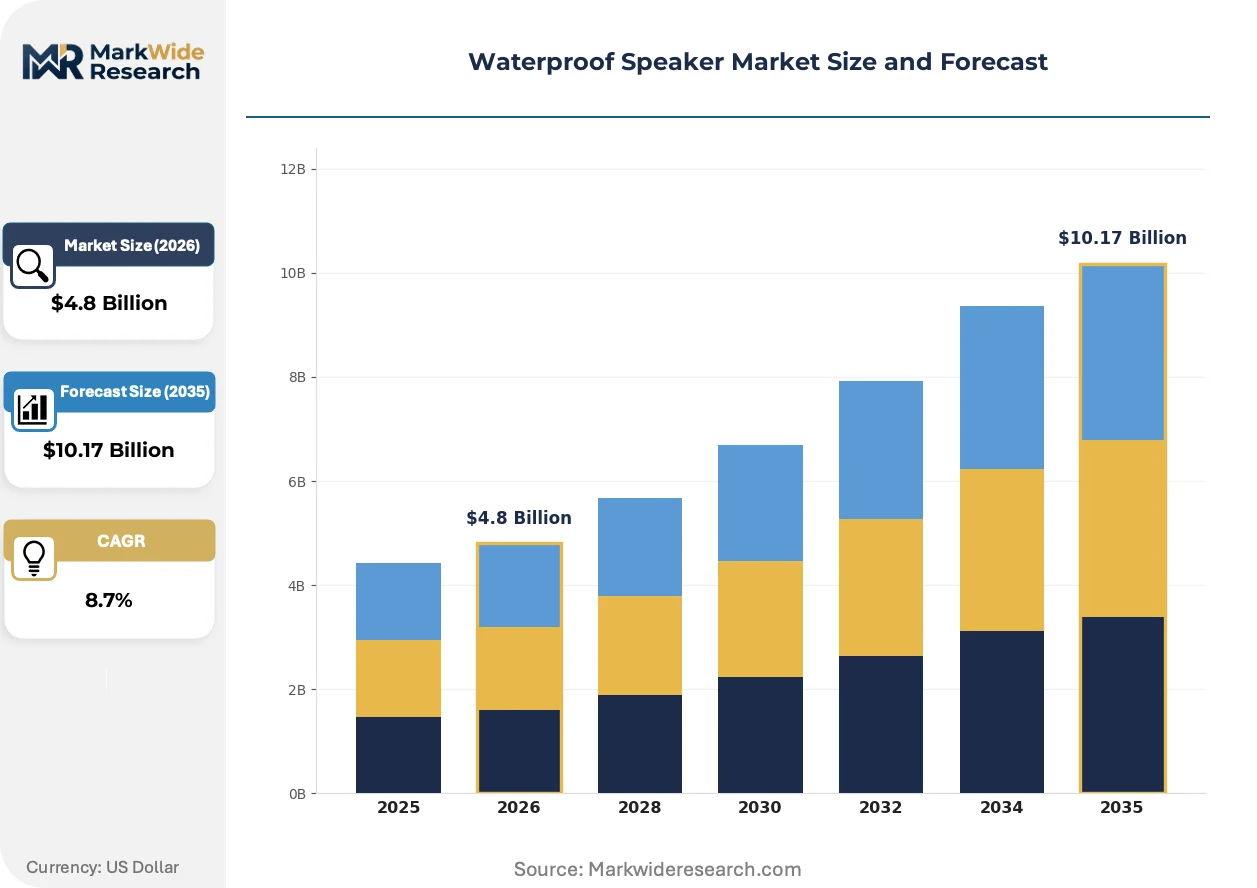
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Mounted, Floating, Shower Connectivity: Bluetooth, Wi-Fi, Wired, NFC End User: Outdoor Enthusiasts, Beach Goers, Fitness Buffs, General Consumers Sound Quality: Standard, High-Fidelity, Surround Sound, Bass Boosted |
| Companies Covered | Bang & Olufsen, Anker Soundcore, Ultimate Ears, Marshall, House of Marley, Sony, Bose, EarFun, JBL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Speaker Market Evolving Landscape
Active driver materials and power management architectures are reshaping competitive positioning in waterproof audio. Manufacturers now compete on acoustic fidelity in wet environments rather than mere survival ratings.
Graphene-enhanced polymer diaphragms are overtaking traditional treated paper and aluminum cones in mid-range and premium waterproof enclosures. Marine recreation buyers in Florida and California are specifying these drivers for salt-air corrosion resistance. The technology is compressing the performance gap between sealed portable units and open-air bookshelf speakers.
REACH substance restrictions in Europe are forcing reformulation of enclosure polymers and adhesive compounds. Manufacturers serving EU distribution channels must validate alternative flame retardants and plasticizers through ECHA notification procedures. Battery compartment sealing adhesives face the most stringent substitution timelines, with suppliers accelerating bio-based epoxy development.
Certification-driven purchasing now dominates commercial procurement for hospitality and fitness verticals. United States hotel chains and gym operators are specifying IP67 minimums in RFPs, displacing price-only evaluations. Procurement teams in Texas and Arizona are bundling speaker replacement into broader outdoor amenity renovation contracts.
Waterproof Speaker Market Segmentation
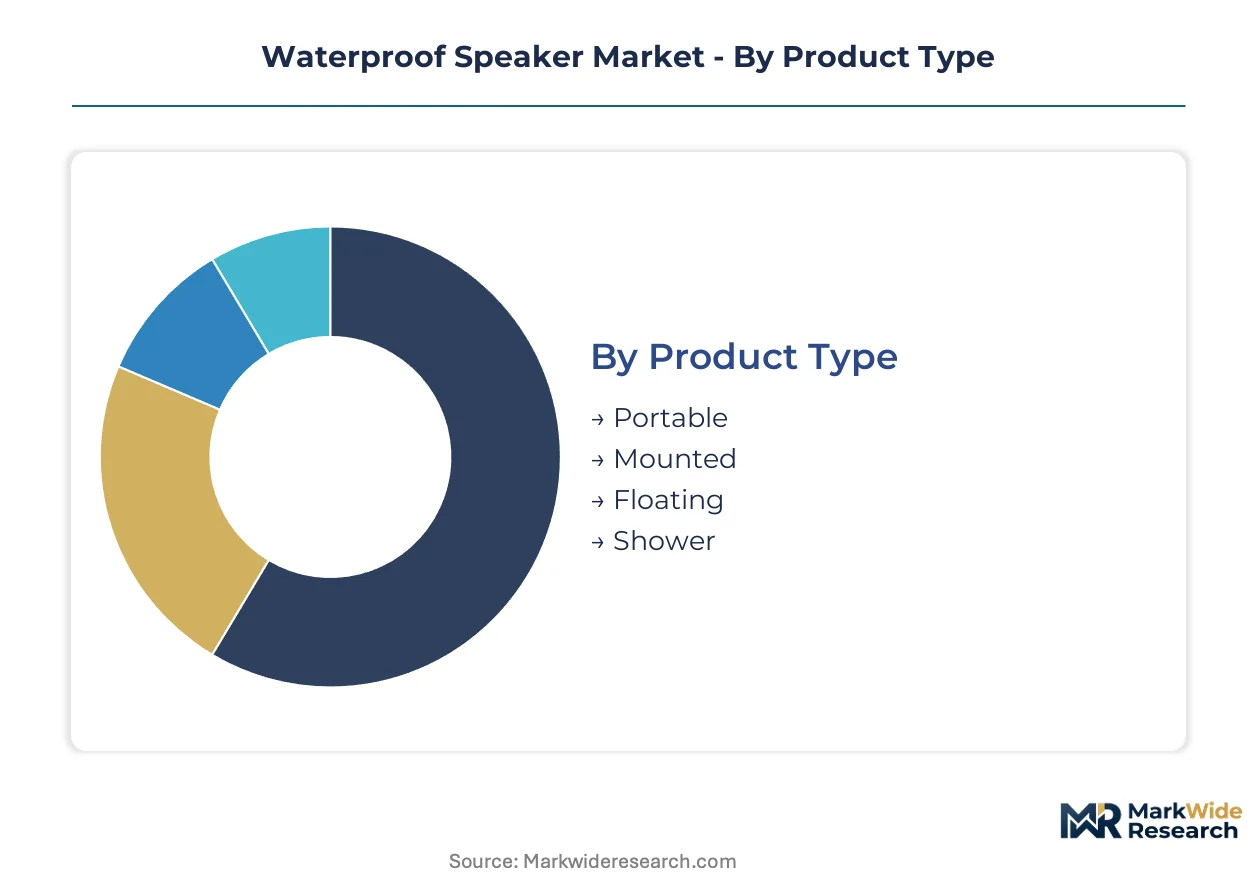
Waterproof speaker segmentation reveals how distinct user scenarios drive hardware specifications. Upgrade cycles vary dramatically across categories, from annual Bluetooth replacements to decade-long marine installations.
Product Type:
Replacement intensity differs sharply by mounting configuration and exposure severity.
- Portable:Battery degradation and enclosure seal fatigue drive 18-24 month replacement cycles among United States outdoor enthusiasts. Lithium-ion chemistry improvements from South Korean suppliers extend playback duration without weight penalties, sustaining premium pricing.
- Floating:Buoyant polymer housings with integrated LED lighting capture backyard entertainment demand in Florida and California. Salt-air corrosion resistance specifications from marine buyers are reshaping driver material selection.
- Mounted:Permanent installation in United States hotel pool decks and Arizona fitness centers favors hardwired power over battery maintenance.
- Shower:Suction-cup and adhesive mounting formats face saturation in North American household penetration.
Portable sits at the top of the volume ranking, with Floating climbing the fastest.
Connectivity:
Protocol selection determines RF certification burden and pairing reliability in wet environments.
- Bluetooth:Universal smartphone compatibility and FCC Part 15 transmitter compliance dominate mass-market shipments. Low-energy protocols from Nordic Semiconductor enable extended standby without enclosure redesign.
- Wi-Fi:Multi-room synchronization and higher bitrate streaming attract whole-home audio integrators in Germany and United States custom installation channels.
- Wired:3.5mm and USB-C connections persist in commercial hospitality deployments where electromagnetic interference concerns override convenience.
- NFC:Tap-to-pair functionality differentiates premium retail SKUs in Japanese and South Korean consumer electronics channels.
Bluetooth captures absolute shipment leadership, while Wi-Fi gains share fastest in residential retrofit applications.
End User:
Activity-specific durability expectations segment the buyer base by replacement trigger.
- Outdoor Enthusiasts:Trekking, camping, and adventure tourism participation in Colorado and Bavaria demands IPX8 submersion ratings and freeze-thaw cycling validation.
- Beach Goers:Sand intrusion and salt spray exposure in Florida and Southern California drive preference for sealed passive radiator designs over ported enclosures.
- Fitness Buffs:Gym operators in Texas and Arizona specify IP67 minimums in bundled amenity renovation contracts.
- General Consumers:Casual poolside and patio use tolerates IPX5 splash resistance at sub-fifty-dollar price points.
General Consumers dominate unit volume, with Outdoor Enthusiasts expanding most quickly as adventure tourism participation rises.
Sound Quality:
Acoustic engineering investment separates margin tiers within identical IP ratings.
- High-Fidelity:Graphene-enhanced polymer diaphragms and multiple driver arrays justify triple-digit pricing for audiophile buyers. Salt-air corrosion resistance specifications from Florida marine recreation users are accelerating treated material adoption.
- Bass Boosted:Passive radiator configurations and DSP-enhanced low-frequency extension target fitness and pool party applications where volume projection overrides accuracy.
- Standard:Single full-range drivers in sealed enclosures satisfy shower and casual outdoor use with minimal acoustic engineering overhead.
- Surround Sound:Stereo pairing protocols and spatial audio processing appeal to home theater extension buyers in United States suburban markets.
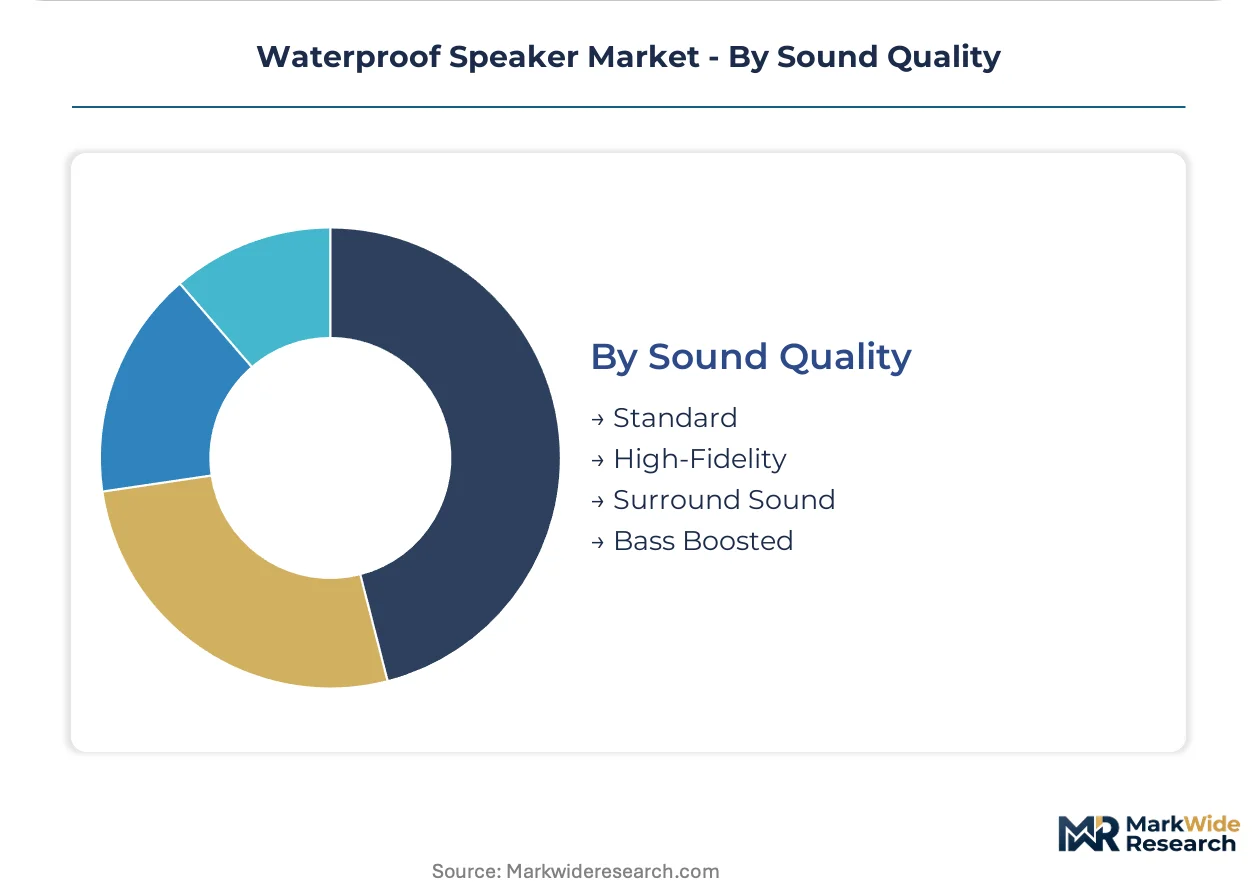
Standard leads absolute shipment volume, with High-Fidelity commanding steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States waterproof speaker demand outpaces German volume by roughly three-to-one, yet Bavarian buyers command higher per-unit acoustic specifications. This divergence reflects distinct recreational cultures rather than income disparities.
United States
Poolside entertainment and marine recreation sustain 18-24 month replacement cycles in Florida and California. FCC Part 15 governs Bluetooth transmitter compliance, streamlining cross-state distribution. Austin and Denver clusters concentrate adventure tourism equipment procurement as trekking participation accelerates.
Germany
Outdoor recreation in Bavaria and North Rhine-Westphalia demands IPX8 submersion ratings for alpine trekking. REACH restrictions on halogenated flame retardants elevate enclosure polymer costs for Asian exporters. Berlin-Brandenburg hosts certification laboratories accelerating IEC 60529 validation timelines.
China
Domestic camping participation in Sichuan and Yunnan provinces creates first-mover positioning for mid-tier IP-rated units. MIIT enforces GB standards for lithium-cell transport alongside IATA thresholds. Shenzhen and Dongguan manufacturing clusters dominate driver assembly and sealed housing fabrication.
Japan
Marina and onsen resort operators in Kanto and Kansai specify corrosion-resistant drivers for salt-air environments. METI oversees JIS alignment with IEC ingress protection benchmarks. Osaka-based distributors channel premium-tier inventory toward hospitality verticals.
India
Emerging middle-class leisure spending in Maharashtra and Karnataka creates penetration opportunities for trekking and camping segments. BIS mandates local certification for lithium-ion imports above specified capacity thresholds. Mumbai logistics hubs facilitate regional fulfillment as air freight regulations tighten.
Waterproof Speaker Market Competitive Landscape
Top-tier vendors anchor premium acoustic engineering, while mass-market specialists compete on battery efficiency and value engineering. The vendor base stratifies across three tiers: audiophile-grade manufacturers commanding triple-digit pricing, mid-tier ruggedized specialists, and sub-fifty-dollar commodity assemblers. Strategic archetypes include heritage audio brands leveraging transducer expertise, consumer electronics conglomerates optimizing supply chain scale, and pure-play outdoor specialists. Dominant competitive moves encompass geographic expansion into underpenetrated trekking markets and portfolio diversification toward marine-specific floating designs.
Within the heritage audio tier, Bang & Olufsen and Marshall exemplify European design-centric positioning, while Sony anchors Japanese conglomerate diversification into ruggedized segments. Bose occupies a position in proprietary transducer arrays justifying sustained retail premiums. Ultimate Ears represents the pure-play outdoor specialist archetype, leveraging stage monitoring heritage for ruggedized acoustics. Anker Soundcore sits within the value engineering tier, dominating e-commerce shelf space through battery efficiency optimization.
| Leading Market Players |
|---|
| Bang & Olufsen |
| Anker Soundcore |
| Ultimate Ears |
| Marshall |
| House of Marley |
| Sony |
| Bose |
| EarFun |
| JBL |
| Others |
Value Network & Pricing Analysis
Graphene-enhanced polymer diaphragm adoption in premium waterproof enclosures simultaneously compresses acoustic performance gaps and concentrates driver assembly margins among South Korean and Japanese material suppliers. This dual shift tightens cost economics for mid-tier manufacturers while elevating pricing power for vertically integrated acoustic specialists serving marine and adventure tourism segments.
Pricing Analysis
Bundled amenity contracts versus unbundled retail purchases split pricing power across the waterproof speaker market. Three-tier pricing structure across premium, standard, and economy levels reflects IP certification grade and acoustic engineering investment, with audiophile-grade units commanding sustained premiums through proprietary transducer arrays. Price differentiation stems from driver material science and battery chemistry efficiency, with cost compression in the sub-fifty-dollar tier intensifying due to commodity lithium-ion cell oversupply. General consumers exhibit highest price sensitivity, while marine recreation buyers in Florida and California demonstrate lowest sensitivity to triple-digit pricing for salt-air corrosion resistance.
Supply Chain Analysis
Direct-to-retail e-commerce channels handle mass-market volume, while specialized outdoor distributors manage premium-tier fulfillment for adventure tourism equipment procurement. Manufacturing concentrates in China, South Korea, and Japan, with Shenzhen and Dongguan clusters dominating sealed housing fabrication and driver assembly. Raw material dependencies include neodymium rare earth magnets, lithium-ion cells from South Korean suppliers, and REACH-compliant flame-retardant polymers. Single-source vulnerability in Chinese rare earth processing creates margin volatility for driver manufacturers. Distribution runs through Amazon and direct-to-consumer platforms for value-tier brands, with specialty retailers controlling premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof speaker margins expand through graphene-enhanced driver adoption that sustains premium pricing despite IP rating commoditization. Battery chemistry improvements from South Korean suppliers simultaneously reduce cost structures and extend replacement cycles.
For Market Incumbents: Anchor premium positioning through proprietary acoustic engineering investments that justify triple-digit pricing against commodity IPX8 alternatives. Defend against Anker Soundcore value engineering by deepening backward integration into driver material supply chains. Secure exclusive distribution partnerships with United States hotel chains and Arizona fitness operators bundling speaker replacement into amenity renovation contracts. For New Entrants and Emerging Players: Capture first-mover positioning in India's underpenetrated trekking and camping segments where emerging middle-class leisure spending creates whitespace for mid-tier IP-rated units. Target Maharashtra and Karnataka outdoor recreation clusters with localized marketing emphasizing IPX8 submersion validation for monsoon exposure. Pursue direct-to-consumer launch through Flipkart and Amazon India to bypass established electronics retail gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among value-engineering specialists with battery efficiency optimization capabilities but limited acoustic R&D depth. Long-term viability favors vertically integrated manufacturers controlling driver material science and sealed enclosure design. Monitor IATA lithium-cell air freight threshold tightening as inflection indicator favoring regional assembly hubs over centralized Far East manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Graphene Driver Material Integration | Salt-air corrosion resistance specifications from Florida marine buyers accelerate treated polymer adoption. |
| Regional Assembly Hub Establishment | IATA battery transport thresholds favor India and Mexico manufacturing over Shenzhen concentration. |
| Marine Floating Design Portfolio | Buoyant LED-integrated form factors capture premium backyard entertainment positioning in California. |
| REACH-Compliant Polymer Reformulation | ECHA notification procedures for alternative flame retardants elevate European export compliance costs. |
| Adventure Tourism Channel Partnership | Austin and Denver equipment clusters concentrate procurement influence for ruggedized acoustic specifications. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with product managers at heritage audio brands and consumer electronics conglomerates, procurement leads at United States hotel chains and gym operators, and distribution channel partners in outdoor recreation retail. Secondary validation draws from FCC Part 15 equipment authorization databases, ECHA REACH substance restriction notifications, IATA lithium battery transport guidelines, and SEC filings of listed acoustic component suppliers. Bottom-up shipment estimates triangulate against top-down consumer electronics spending patterns.
Granularity-level modeling disaggregates volume and value across product type, connectivity protocol, end-user activity segment, and sound quality tier throughout the forecast period. CAGRs derive from replacement cycle analysis by exposure severity and price elasticity estimates by buyer archetype. Industry-specific forecast inputs include lithium-ion energy density improvement curves from South Korean and Japanese cell suppliers and IEC 60529 certification timeline data from Berlin-Brandenburg testing laboratories.
Underlying measurement precision varies by segment; portable and floating product types carry tighter precision than saturated shower speaker categories due to more active SKU turnover and clearer replacement triggers. Forecasts reflect assumptions regarding adventure tourism participation trajectories, rare earth magnet price stability, and regulatory alignment on battery transport thresholds. Periodic stress-testing of base assumptions is recommended against smartphone audio quality substitution effects and emerging market currency volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Consumer Electronic Biometrics Market