
 Gaming Mouse & Keyboards Market | 2026-2036
Gaming Mouse & Keyboards Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Mouse & Keyboards Market Insights
Esports team procurement is broadening beyond traditional sponsor-supplied gear toward direct equipment partnerships with peripheral brands. Logitech G leverages its G Pro line to anchor relationships with tier-one esports organizations through multi-year equipment contracts. Razer competes by sustaining deep integration with streaming platforms and tournament circuits. Corsair differentiates through its Elgato ecosystem, extending peripheral sales into content creation workflows.
Gaming mice and keyboards comprise precision input devices engineered for sub-millisecond response times, with optical switches rated for 100-million-click lifecycles and polling rates up to 8,000 Hz. Mechanical keyboards employ hot-swappable PCB architectures and PBT double-shot keycaps to withstand sustained competitive use. Wireless mouse segments lead unit growth as 2.4 GHz and Bluetooth protocols close latency gaps with wired alternatives. RGB technology commands premium positioning through per-key addressable lighting and software ecosystem lock-in. Professional gamers represent the fastest-growing end-user category as tournament prize pools expand and player careers formalize.
China's MIIT enforces GB standards for wireless transmission power and electromagnetic compatibility, shaping product certification requirements for factory-direct brands. The EU RoHS directive and REACH chemical restrictions limit solder alloys and flame retardants in PCB assemblies, elevating compliance costs for budget manufacturers. Stakeholders must monitor how EPA e-waste rules and evolving right-to-repair legislation in multiple jurisdictions reshape warranty obligations and modular design priorities.
Market Dynamics
Wireless protocol convergence and China's dual carbon mandates are compressing power budgets while simultaneously demanding sub-millisecond latency performance, forcing simultaneous innovation across RF engineering and battery chemistry.
Growth Catalysts
- Esports formalization:Tournament prize pool expansion and player unionization are institutionalizing equipment refresh cycles. Professional teams now mandate standardized peripheral specifications.
- GB standard harmonization:China's MIIT wireless transmission power regulations are accelerating 2.4 GHz optimization investments, creating certification efficiencies for factory-direct brands.
- Optical switch maturation:100-million-click lifecycle ratings are displacing mechanical alternatives in competitive environments, reducing tournament downtime from hardware failure.
Market Restraints
- Rare earth magnet dependency:Neodymium price volatility in motor assemblies for haptic feedback mechanisms compresses margin predictability for mid-tier manufacturers.
- Shenzhen-Dongguan concentration risk:Over 70 percent of PCB assembly capacity sits within 100 kilometers of this cluster, exposing supply continuity to regional power rationing or logistics disruption.
- REACH chemical restrictions:ECHA limitations on halogenated flame retardants are forcing expensive substrate material substitutions without immediate performance equivalence.
Strategic Opportunities
- India peripheral penetration:BIS certification alignment with international wireless standards is opening organized retail channels previously blocked by import complexity.
- Content creator workflow integration:Stream deck and macro key convergence with gaming keyboards is unifying two previously separate hardware categories.
- EU right-to-repair momentum:Draft legislation mandating modular switch replacement and battery accessibility is creating premium positioning for hot-swappable architectures.
Industry Challenges
- Firmware engineering scarcity:8,000 Hz polling rate implementation requires specialized embedded systems talent concentrated among semiconductor vendors, not peripheral brands.
- Multi-jurisdiction certification stacking:Simultaneous FCC, CE, and SRRC approval timelines extend product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Mouse & Keyboards Market |
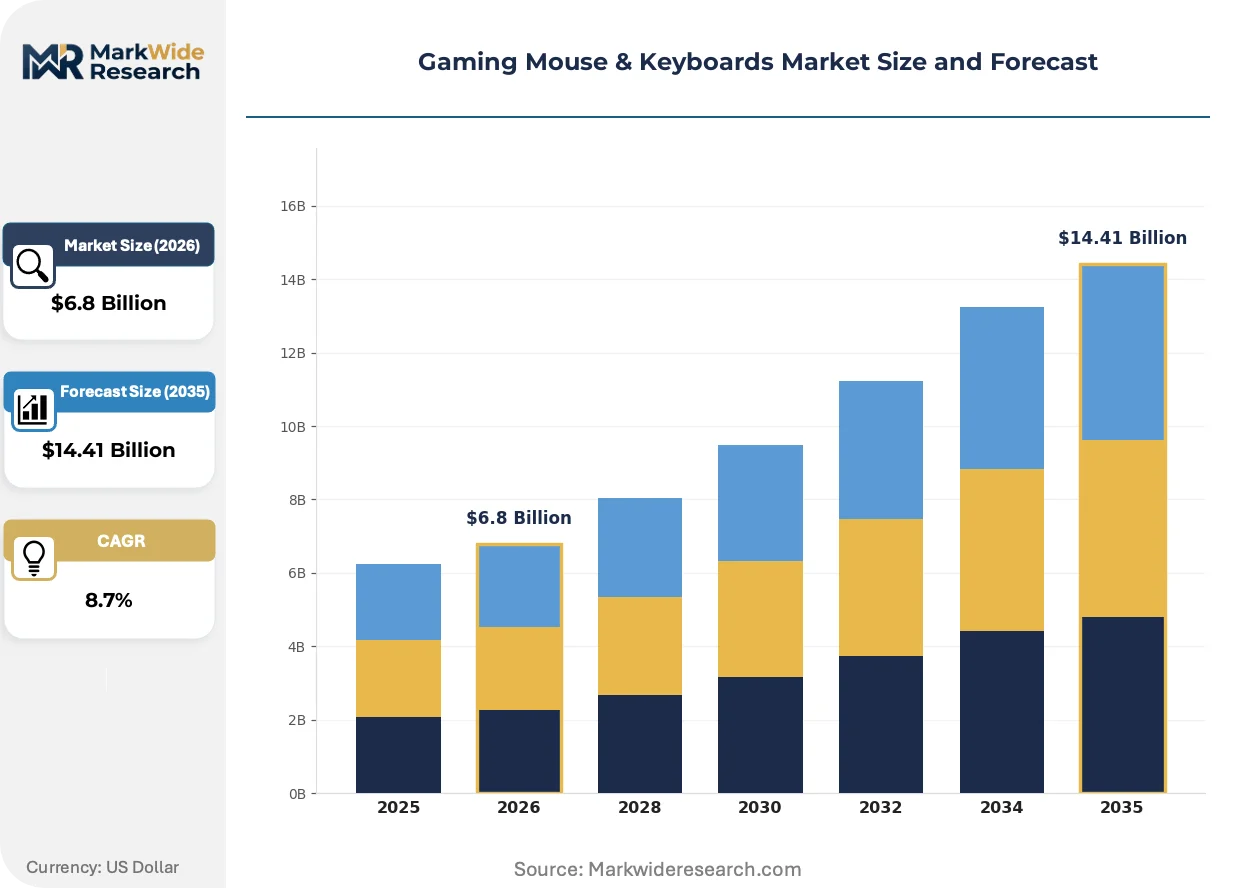
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Mouse, Wireless Mouse, Mechanical Keyboard, Membrane Keyboard End User: Casual Gamers, Professional Gamers, Streamers, Esports Teams Technology: Optical, Laser, RGB, Wireless Distribution Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Marketplaces |
| Companies Covered | Logitech G, Razer, Corsair, SteelSeries, HyperX, Keychron, Cooler Master, ROCCAT, Glorious, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Mouse & Keyboards Market Trends and Innovations
Active unification of previously separate hardware categories—gaming peripherals, streaming equipment, and mobile workstation tools—is collapsing traditional segmentation boundaries and rewiring distribution economics.
Optical-mechanical hybrid switches are unifying the tactile feedback of mechanical keyboards with the speed and durability of optical actuation. Tier-one esports organizations are mandating these architectures in equipment contracts, compressing the competitive viability window for pure mechanical designs. The structural consequence is vendor consolidation around semiconductor partners capable of custom photoelectric sensor integration.
EU RoHS recast directives are tightening cadmium and lead thresholds in PCB solder alloys, forcing alloy reformulation across Dongguan assembly lines. Manufacturers serving European distribution channels are absorbing compliance costs through specification tiering rather than uniform price increases. Gaming mouse SKUs bound for EU retail now carry distinct BOM identifiers from identical-appearance units shipping to other markets.
Direct-to-team procurement contracts are displacing traditional sponsor-mediated equipment distribution in professional esports. Organizations from tier-one leagues now negotiate multi-year peripheral partnerships independent of apparel or beverage sponsors, with dedicated logistics for player-specific form factor customization. This pattern is most visible in South Korean and Chinese team house configurations, where standardized peripheral banks eliminate individual player equipment variance.
Gaming Mouse & Keyboards Market Segmentation
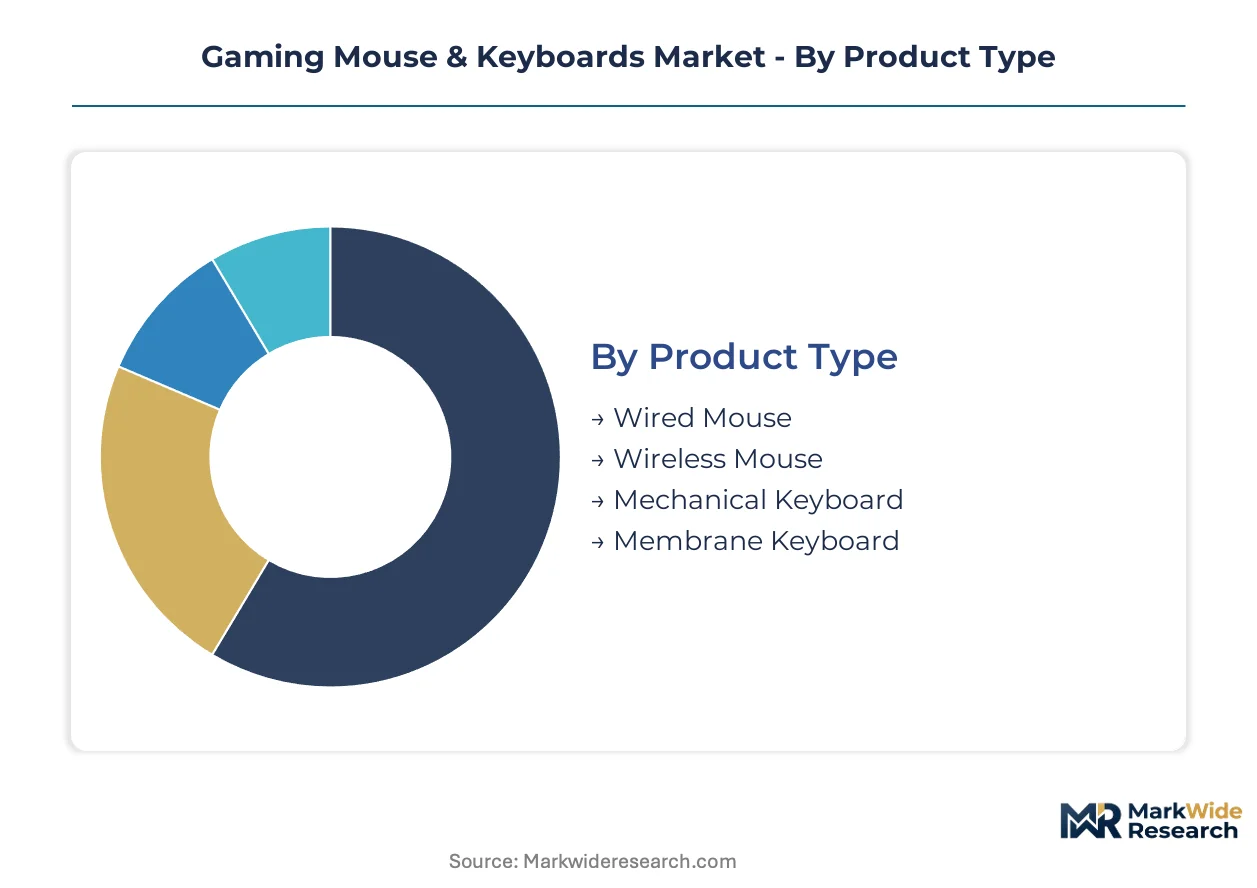
Gaming peripheral segmentation tracks how input device architectures align with distinct performance requirements across competitive intensity levels. Category boundaries are collapsing as streaming workflows and esports standardization force cross-functional hardware design.
Product Type:
Standalone peripherals dominate enthusiast configurations while embedded systems consolidate in OEM gaming laptop bundles.
- Wireless Mouse:2.4 GHz and Bluetooth protocols achieve sub-millisecond latency parity with wired alternatives through proprietary RF optimization. Demand clusters in South Korean and Chinese team house configurations where cable-free setups eliminate drag-induced inconsistency during tournament play.
- Mechanical Keyboard:Hot-swappable PCB architectures with PBT double-shot keycaps withstand sustained competitive use while enabling rapid switch replacement. Professional gamers and esports teams drive procurement as standardized peripheral banks eliminate individual equipment variance in institutional settings.
- Wired Mouse:USB-C and paracord-sleeved cables retain cost-sensitive enthusiast segments through zero-latency assurance without RF engineering premiums.
- Membrane Keyboard:Rubber dome actuation serves entry-level casual gamers and embedded laptop keyboard modules where mechanical switch height constraints apply.
Volume placements concentrate in wired mouse SKUs; the faster expansion belongs to wireless mouse architectures.
End User:
Customer tiers separate by refresh cycle frequency and specification stringency rather than absolute spending power alone.
- Esports Teams:Multi-year equipment contracts with tier-one organizations mandate standardized peripheral specifications and player-specific form factor customization. Procurement runs through direct manufacturer partnerships independent of traditional sponsor mediation, with dedicated logistics for bulk team house deployment.
- Professional Gamers:Tournament prize pool expansion and career formalization institutionalize equipment refresh cycles at 12-18 month intervals. This segment demands 8,000 Hz polling rates and 100-million-click lifecycle ratings as baseline competitive requirements.
- Streamers:Elgato ecosystem integration and macro key convergence unify gaming keyboards with content creation workflows, collapsing previously separate hardware categories.
- Casual Gamers:Price-sensitive volume segment prioritizing RGB aesthetics and brand recognition over sub-millisecond performance specifications.
Revenue concentration sits with esports teams; professional gamers are climbing the fastest as career pathways formalize.
Technology:
Technology layers stack from foundational sensor architectures through surface presentation features, with each tier commanding distinct margin profiles.
- Optical:LED-illuminated sensors dominate competitive environments through surface adaptability without acceleration inconsistencies. Optical-mechanical hybrid switches now unify tactile feedback with photoelectric actuation speed, displacing pure mechanical alternatives in tier-one equipment contracts.
- Wireless:Proprietary 2.4 GHz protocols and Bluetooth Low Energy implementations compress power budgets while maintaining polling rate performance, responding to China's MIIT wireless transmission power regulations and dual carbon mandates.
- Laser:Higher DPI ceiling suits multi-monitor productivity workflows and MOBA titles requiring rapid cursor traversal across extended display arrays.
- RGB:Per-key addressable lighting commands premium positioning through software ecosystem lock-in and streaming visual integration.
Deployment scale favors optical sensors; wireless protocol adoption shows the steepest expansion trajectory.
Distribution Channel:
Channel economics diverge by warranty handling complexity and customization depth requirements.
- Direct Sales:Manufacturer-to-team procurement contracts displace traditional distributor intermediaries for esports organizations requiring player-specific form factor customization and bulk logistics coordination.
- Online Retail:Amazon and specialized gaming peripheral platforms aggregate enthusiast demand through review density and specification comparison tools, serving casual gamers and streamers with standardized SKUs.
- Brick-and-Mortar Stores:Tactile evaluation remains critical for mechanical keyboard switch preference confirmation, sustaining specialty retailer relevance in urban Chinese and South Korean markets.
- Marketplaces:Taobao and AliExpress channels serve factory-direct brands with MIIT certification, bypassing organized retail markups for price-sensitive wireless mouse segments.
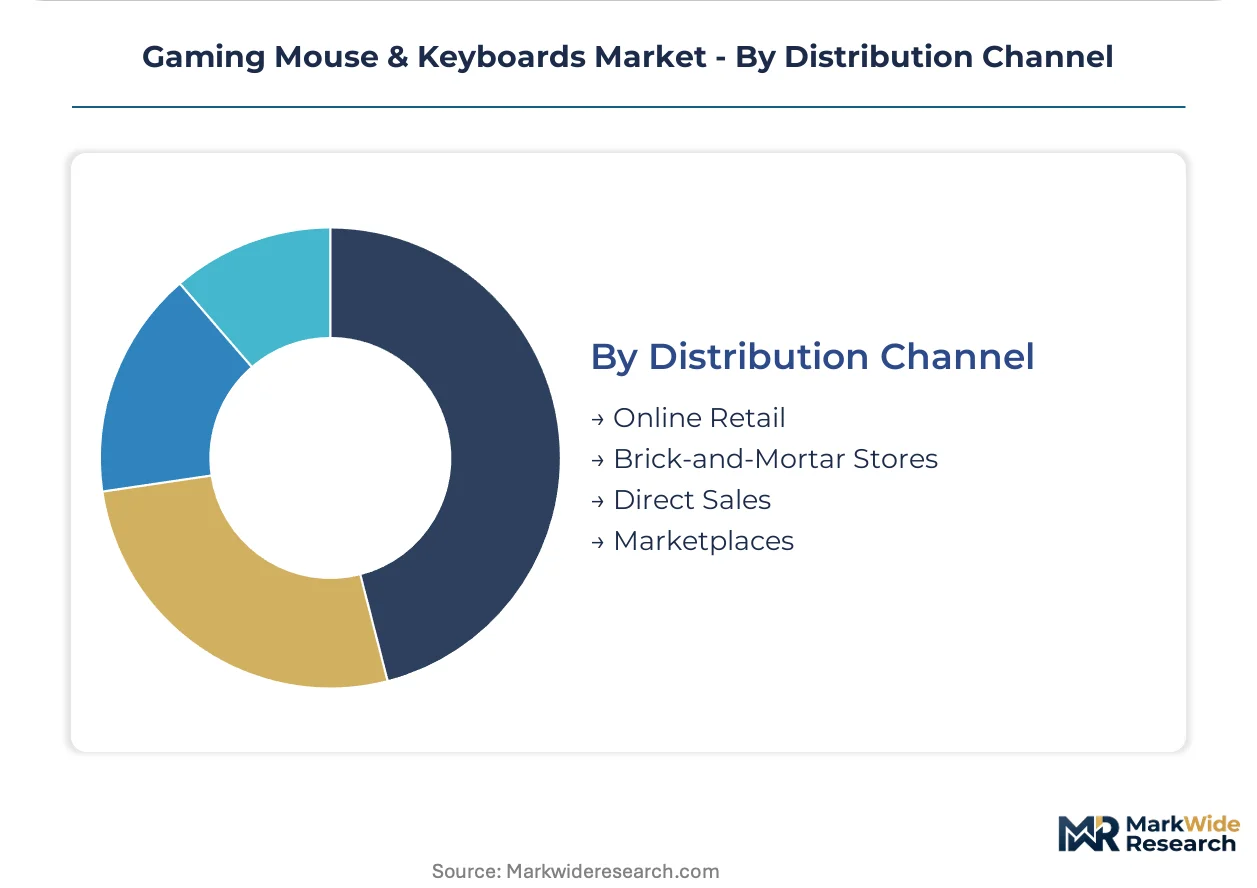
Transaction volume flows through online retail; direct sales channels are gaining share fastest as team procurement formalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates peripheral demand through its Shenzhen-Dongguan manufacturing cluster, while professional esports infrastructure drives procurement intensity in South Korea and the United States. Regulatory divergence across MIIT, FCC, and REACH frameworks shapes certification strategies for factory-direct and premium brands.
China
MIIT's GB standards for wireless transmission power and dual carbon mandates compress power budgets while demanding sub-millisecond latency performance. The Shenzhen-Dongguan corridor houses over 70 percent of PCB assembly capacity within 100 kilometers, with factory-direct brands leveraging Taobao and AliExpress channels to bypass organized retail markups for price-sensitive wireless mouse segments.
United States
Tournament prize pool expansion and player career formalization institutionalize 12-18 month equipment refresh cycles among professional gamers. FCC 2.4 GHz and Bluetooth certification requirements extend product launch timelines, while Amazon and specialized peripheral platforms aggregate enthusiast demand through review density and specification comparison tools serving casual gamers and streamers.
South Korea
Team house configurations in Seoul and Busan mandate standardized peripheral banks that eliminate individual player equipment variance through direct manufacturer partnerships. Korean esports organizations negotiate multi-year equipment contracts independent of traditional sponsor mediation, with dedicated logistics for bulk deployment and player-specific form factor customization.
Germany
ECHA REACH restrictions on halogenated flame retardants force expensive substrate material substitutions without immediate performance equivalence, elevating compliance costs for budget manufacturers serving European distribution channels. Berlin and Munich sustain specialty retailer relevance where tactile evaluation remains critical for mechanical keyboard switch preference confirmation.
India
BIS certification alignment with international wireless standards is opening organized retail channels previously blocked by import complexity. Maharashtra and Karnataka electronics corridors attract peripheral assembly investments as brands localize production to circumvent duty structures and reduce logistics lead times for the price-sensitive volume segment.
Gaming Mouse & Keyboards Market Competitive Landscape
Chinese producers anchor the factory-direct tier through Shenzhen-Dongguan supply chain integration; American and European specialists hold premium positioning through semiconductor partnerships and esports team procurement contracts. The vendor base separates into three strategic archetypes: integrated peripheral-streaming ecosystem builders, RF engineering specialists with proprietary wireless protocols, and contract manufacturers serving white-label channels. Competitive moves concentrate on direct-to-team partnership formalization and hot-swappable architecture patent positioning ahead of EU right-to-repair legislation.
Within the integrated ecosystem tier, Logitech G and Razer exemplify divergent anchoring strategies—one through multi-year equipment contracts with tier-one esports organizations, the other through streaming platform and tournament circuit integration. Corsair occupies a position bridging peripheral hardware with content creation workflow unification. These three companies collectively represent how competitive positioning now depends on collapsing boundaries between gaming input devices, streaming equipment, and mobile workstation tools.
| Leading Market Players |
|---|
| Logitech G |
| Razer |
| Corsair |
| SteelSeries |
| HyperX |
| Keychron |
| Cooler Master |
| ROCCAT |
| Glorious |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply for premium-tier wireless peripherals while compressing power budgets across Dongguan assembly lines. MIIT wireless transmission power regulations create certification efficiencies that factory-direct brands exploit to undercut organized retail pricing, forcing premium positioning through proprietary RF engineering rather than specification tiering alone.
Pricing Analysis
Volume placements concentrate in wired mouse SKUs where per-unit margins compress under commodity competition, while wireless architectures command premium positioning through proprietary protocol investments. Price differentiation separates esports-certified equipment with 8,000 Hz polling rates from casual gaming peripherals where RGB aesthetics substitute for performance specifications. Cost compression in mid-tier mechanical keyboards intensifies as optical switch maturation displaces traditional Cherry MX alternatives. Casual gamers exhibit highest price sensitivity through Taobao and AliExpress channel preference, while esports teams absorb customization premiums for player-specific form factor contracts.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth processing capacity with spot price volatility transmitting directly into haptic feedback mechanism costs. PCB substrate draws from Taiwan and South Korea specialty laminate producers, while optical sensor dies source from American and European semiconductor foundries. Single-source vulnerability concentrates in Shenzhen-Dongguan final assembly where over 70 percent of capacity sits within 100 kilometers. Distribution runs through direct manufacturer-to-team contracts for esports organizations, bypassing traditional distributor markups for standardized peripheral banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where proprietary wireless protocol development and semiconductor partnership anchoring determine tier-one equipment contract access. Players pursue backward integration into optical switch sensor design to escape firmware engineering scarcity concentrated among chip vendors.
For Market Incumbents: To counter firmware engineering scarcity concentrated among semiconductor vendors, anchor tier-one esports contracts through multi-year equipment partnerships with dedicated logistics for player-specific customization. Pursue backward integration into photoelectric sensor design to reduce dependency on external chip vendors for 8,000 Hz polling rate implementation. Lock hot-swappable architecture patents ahead of EU right-to-repair legislation formalization.
For New Entrants and Emerging Players: BIS certification alignment in India opens a window for organized retail channel penetration previously blocked by import complexity. Target Maharashtra and Karnataka electronics corridors for localized assembly investments that circumvent duty structures. Pursue factory-direct brand positioning through Taobao and AliExpress channels serving price-sensitive wireless mouse demand with MIIT-compliant SKUs.
For Investors and Strategic Acquirers: Direct-to-team procurement contract announcements are the leading indicator that esports equipment partnerships are formalizing independent of traditional sponsor mediation. Long-term viability hinges on semiconductor partnership depth and proprietary protocol ownership rather than assembly scale alone. Watch for EU right-to-repair draft legislation progression as the signal for modular architecture premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Wireless Protocol Development | MIIT GB standard compliance creates certification efficiencies that factory-direct brands exploit for margin protection. |
| Optical Switch Semiconductor Partnership | Photoelectric sensor integration anchors tier-one esports equipment contracts displacing mechanical alternatives. |
| Hot-Swappable Architecture Patent Positioning | EU right-to-repair momentum creates premium positioning for modular keyboard designs with rapid switch replacement. |
| Direct-to-Team Procurement Formalization | South Korean and Chinese team house configurations eliminate distributor intermediaries for standardized peripheral banks. |
| India Localized Assembly Investment | BIS certification alignment opens organized retail channels while duty circumvention improves price-sensitive segment access. |
Research Methodology
Document review covered SEC filings from peripheral manufacturers, MIIT certification databases, and esports tournament equipment specifications, complemented by interviews with RF engineering directors at semiconductor vendors, procurement leads at tier-one esports organizations, and Dongguan contract manufacturing executives. Secondary validation drew from FCC equipment authorization records, ECHA REACH substance restriction updates, and BIS wireless standard harmonization notifications. Bottom-up demand modeling from team house deployment volumes triangulated against top-down market sizing from retail channel shipment data.
Cross-referencing historical refresh cycle patterns against panel input from esports organization equipment managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user competitive intensity, wireless protocol implementation, and regional regulatory cluster. CAGRs were derived from equipment replacement rate formalization and tournament prize pool expansion trajectories. Forecast inputs incorporated optical switch lifecycle ratings and 2.4 GHz latency parity achievement curves.
The model assumes a particular technology adoption path where optical-mechanical hybrid switches displace pure mechanical designs; alternative pathways for haptic feedback mechanism advancement would alter the outlook for neodymium dependency and motor assembly cost structures. Forecasts reflect assumptions around esports career formalization velocity and right-to-repair legislative progression. A small set of triggers—MIIT power regulation revision, ECHA flame retardant restriction expansion, and India BIS enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
True Wireless Stereo Earbuds Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Notebook Market
Consumer Electronics
Laptop Accessories Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Mouse Pad Market