
 Portable Speaker Market | 2026-2036
Portable Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Speaker Market Analysis
The portable speaker category is decoupling into two distinct value strata. Premium tiers now command pricing power through spatial audio certification and multi-room ecosystem lock-in, while commodity tiers compete on battery endurance and IP ratings. Bose Corporation leverages its acoustic engineering heritage to sustain margin premiums in the luxury segment. Anker anchors the budget tier through supply chain scale and direct-to-consumer channel control. Sony Group Corporation differentiates across both strata, occupying premium home audio while extending its SRS line into mid-range portability.
A portable speaker is a self-contained, battery-powered electroacoustic transducer system designed to receive audio signals wirelessly via Bluetooth or Wi-Fi protocols, typically incorporating Class D amplification and lithium-ion cells with output ranging from 5W to 40W. Its primary commercial purpose is to deliver personal or small-group audio playback outside fixed installation environments. Bluetooth speakers lead volume shipments due to universal smartphone compatibility and lower bill-of-materials costs. Smart speakers represent the fastest-growing feature-integrated segment, as voice assistant embedding shifts replacement demand toward ecosystem-dependent devices. Waterproofing and extended battery life concentrate margin pools in outdoor and travel end-use scenarios.
The Federal Communications Commission governs wireless transmission standards and RF exposure limits for devices sold in the United States, while the EU Green Deal and RoHS directives restrict hazardous substances in batteries and circuit assemblies across European markets. China's MIIT enforces GB standards for wireless equipment certification, shaping export eligibility for manufacturers based in Shenzhen and Dongguan. REACH compliance in Europe and evolving right-to-repair frameworks in France and Germany are elevating material disclosure and modular design requirements. Stakeholders must monitor regulatory divergence between battery safety mandates and wireless spectrum allocation as these frameworks increasingly determine market access timelines and product architecture decisions.
Market Dynamics
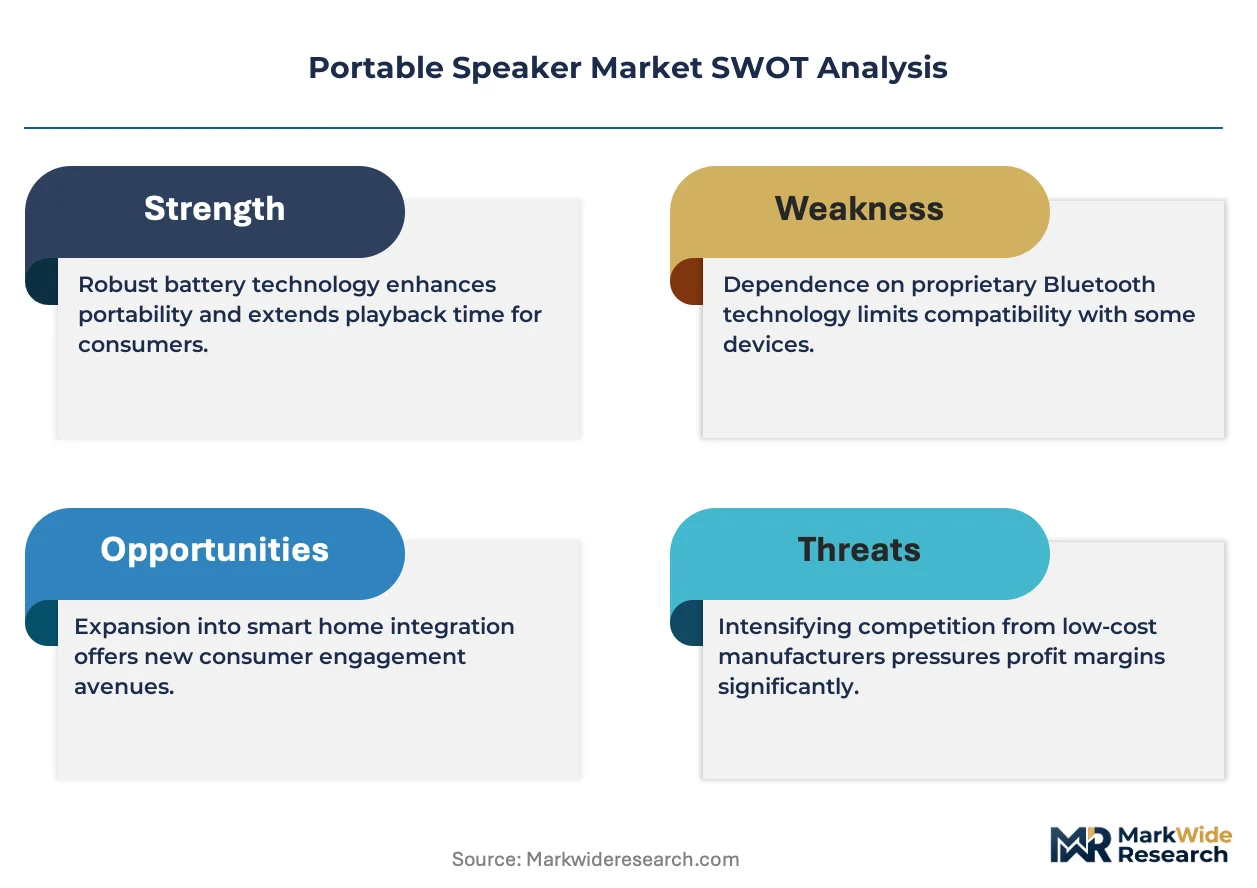
Spatial audio certification and multi-room ecosystem lock-in are bifurcating portable speaker value capture, forcing manufacturers to choose between premium acoustic engineering investments and commodity scale economics.
Growth Catalysts
- EU Green Deal battery mandates:Right-to-repair frameworks in France and Germany are accelerating modular design adoption, extending replacement cycles while opening aftermarket service revenue streams.
- Outdoor recreation expansion:Camping and adventure sports enthusiasts in the United States are compressing replacement demand toward IP-rated, extended-battery configurations.
- Bluetooth Low Energy penetration:Universal smartphone compatibility is lowering switching costs and expanding addressable user bases across emerging economies.
Market Restraints
- Lithium-ion supply concentration:Cell production gravity in China creates input cost volatility and geopolitical exposure for brands without captive supply arrangements.
- FCC RF exposure compliance:Wireless transmission certification timelines in the United States extend product launch windows by four to six months.
- Smartphone audio substitution:Improved onboard speakers and spatial audio processing in flagship handsets reduce discrete speaker necessity for casual users.
Strategic Opportunities
- India PLI scheme leverage:Manufacturing incentives for electronics assembly are attracting contract manufacturers to establish export-competitive production bases.
- Voice assistant convergence:Embedding Alexa and Google Assistant protocols is creating ecosystem-dependent replacement demand among smart home adopters.
- Direct-to-consumer channel expansion:Anker's supply chain scale demonstration proves margin recovery potential through bypassing traditional retail distribution.
Industry Challenges
- Acoustic engineering talent scarcity:Spatial audio codec integration requires specialized DSP firmware expertise concentrated among semiconductor vendors.
- REACH material disclosure complexity:European chemical substance tracking demands granular supply chain visibility that strains mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Speaker Market |
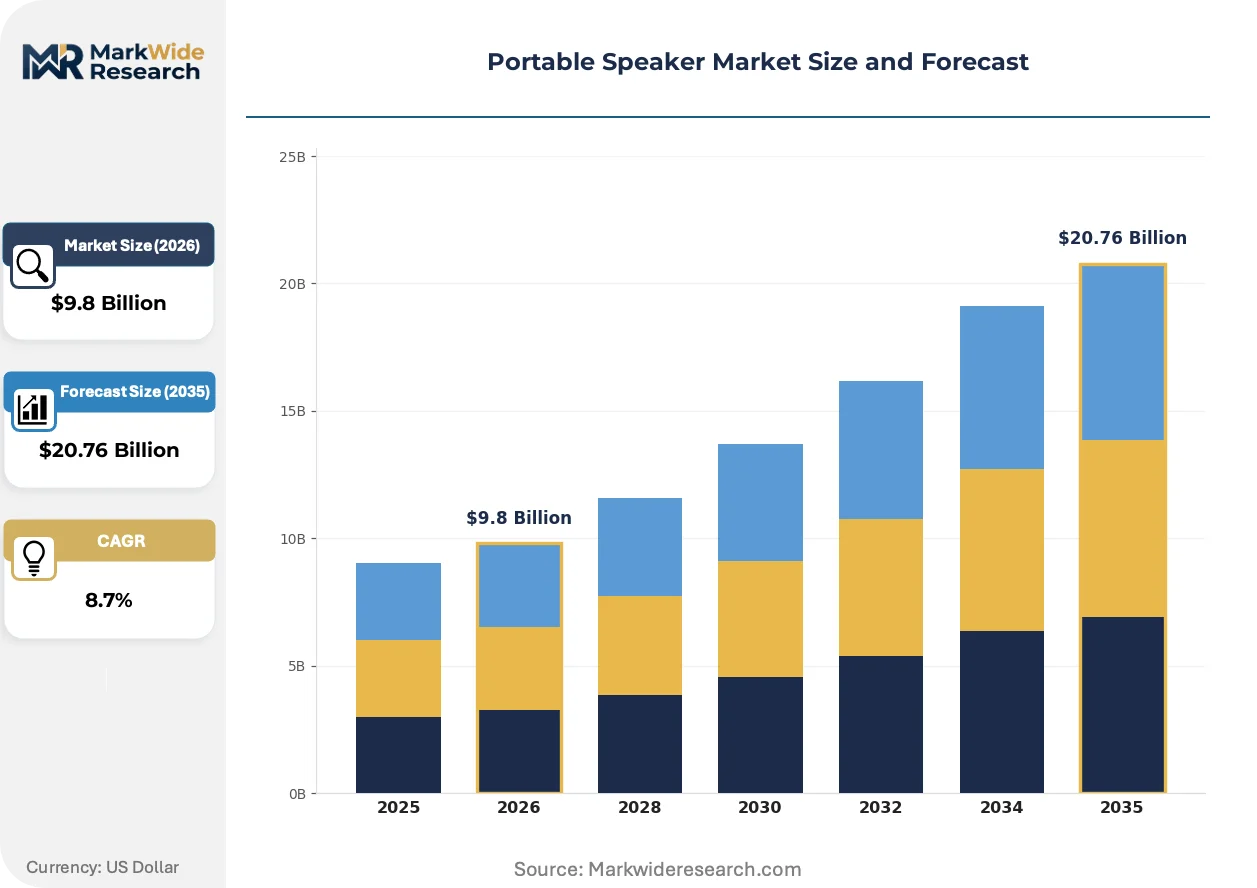
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Speakers, Wireless Speakers, Smart Speakers, Mini Speakers End User: Consumers, Businesses, Travelers, Students Feature: Waterproofing, Voice Assistant, Stereo Sound, Battery Life Pricing Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Bose Corporation, Sony Group Corporation, JBL, Harman International, Ultimate Ears, Apple Inc., Bang & Olufsen, Anker, Marshall Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Speaker Market Emerging Trajectories
Audio playback hardware is fragmenting into ecosystem-locked premium tiers and specification-driven value tiers, with codec compatibility and certification status replacing raw acoustic metrics as primary purchase determinants.
Spatial audio rendering through head-related transfer function processing is modularizing product architecture. Outdoor recreation buyers in the United States and Germany are adopting Dolby Atmos and Sony 360 Reality Audio certification as table stakes for premium positioning. This codec stratification is compressing mid-tier margins by forcing dual-certification investments without commensurate pricing power.
REACH compliance and evolving EU Green Deal battery directives are reshaping material selection protocols. Hazardous substance restrictions in circuit assemblies and lithium-ion cells are extending design validation timelines. Premium manufacturers with dedicated compliance teams are accelerating certification velocity, widening gap-to-market against resource-constrained competitors.
Certification-driven purchasing is displacing specification-based comparison among enterprise and institutional buyers. Facility managers in Germany and the United States are prioritizing CE-marked and FCC-certified inventory for liability reduction. This preference shift is consolidating procurement toward established brands with documented regulatory dossiers, compressing private-label and unbranded import share in commercial channels.
Portable Speaker Market Segmentation
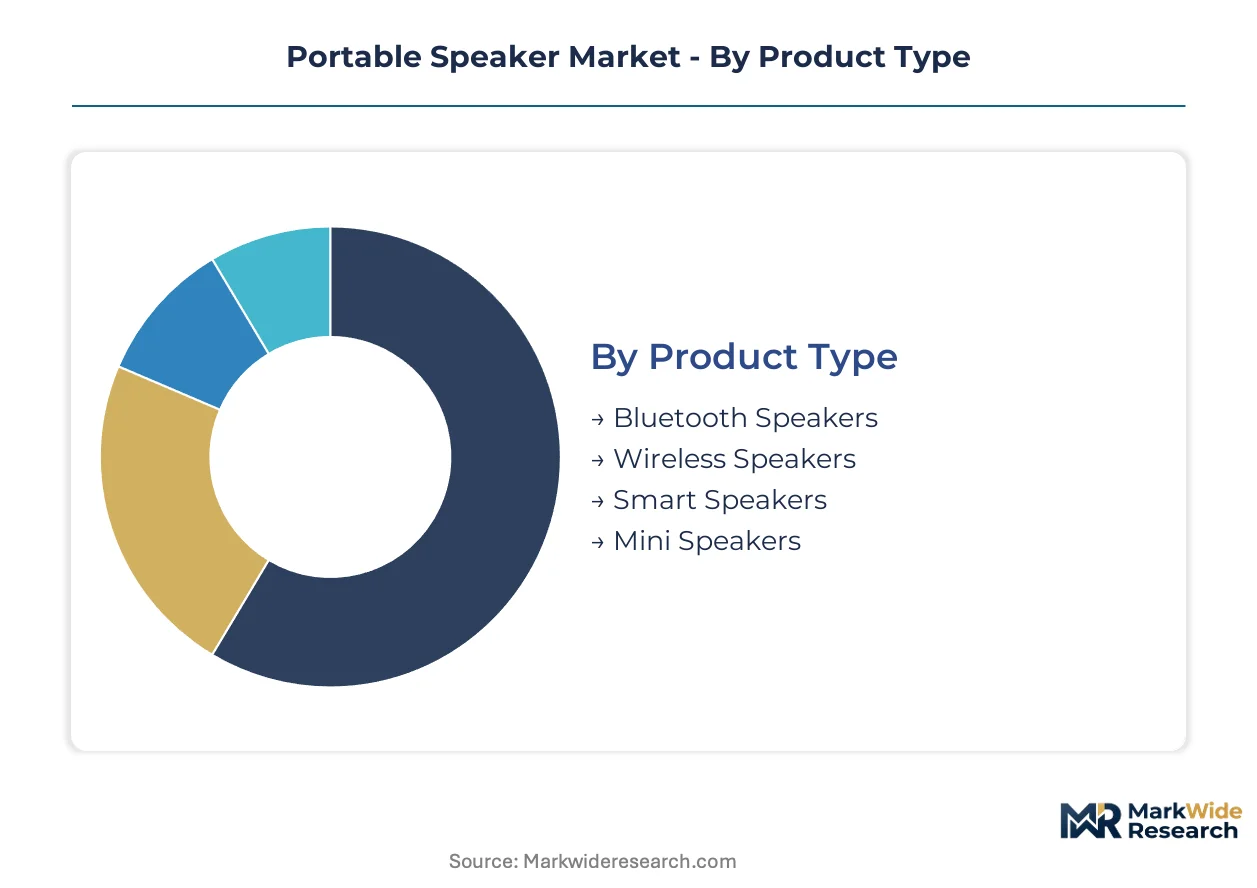
Portable speaker segmentation reveals how certification requirements and ecosystem lock-in reshape competitive boundaries. Manufacturers must align product architecture with specific compliance burdens and buyer willingness to pay for codec compatibility.
Product Type:
FCC Part 15 certification governs Bluetooth transmission power limits in the United States, while MIIT GB standards shape wireless equipment approval for China-bound shipments. Smart speakers carrying Alexa or Google Assistant protocols face additional voice recognition privacy audits.
- Bluetooth Speakers:These devices rely on Class 2 Bluetooth 5.x protocols with 10-30 meter range and 20Hz-20kHz frequency response. Demand concentrates among smartphone users in the United States and Germany seeking universal compatibility without Wi-Fi dependency. FCC RF exposure testing adds four to six months to launch timelines, favoring established brands with dedicated compliance teams.
- Smart Speakers:Voice assistant integration requires far-field microphone arrays and cloud connectivity modules with continuous power draw. Enterprise procurement in Germany prioritizes GDPR-compliant data processing certifications, while consumer demand clusters among smart home adopters in the United States seeking ecosystem convergence.
- Wireless Speakers:Wi-Fi-based streaming supports higher bitrate codecs including lossless formats. Supply chain scale concentrates in Shenzhen and Dongguan contract manufacturers serving premium audio brands.
- Mini Speakers:Ultra-portable form factors below 200 grams sacrifice bass response for pocketability. Student and commuter segments in urban China drive volume shipments through direct-to-consumer channels.
Leading the category by volume: Bluetooth Speakers. Growing fastest: Smart Speakers.
End User:
Cost tier stratification separates disposable income levels and replacement frequency expectations across buyer types.
- Consumers:Household purchasers evaluate spatial audio certification and multi-room ecosystem compatibility as primary selection criteria. Premium positioning requires Dolby Atmos or Sony 360 Reality Audio badges.
- Travelers:IP67 waterproofing and 20+ hour battery endurance command price premiums in outdoor recreation segments. Camping enthusiasts in the United States compress replacement cycles toward ruggedized configurations.
- Businesses:Facility managers prioritize CE-marked and FCC-certified inventory for liability reduction in Germany and the United States. Procurement consolidates toward documented regulatory dossiers.
- Students:Price sensitivity drives demand toward sub-$50 configurations with basic Bluetooth connectivity. Anker's supply chain scale demonstration anchors this tier through direct channel control.
Volume leadership: Consumers. Steepest expansion trajectory: Travelers.
Feature:
Application-specific requirements determine which technical specifications convert to pricing power versus table stakes.
- Waterproofing:IEC 60529 IP ratings define ingress protection standards with IPX7 submersion resistance becoming baseline for outdoor positioning. Adventure sports demand in the United States and Germany elevates IP67 dust-tight specifications.
- Voice Assistant:Microphone array beamforming and wake-word processing add $8-12 to bill-of-materials costs. Smart home ecosystem lock-in creates replacement dependency among Alexa and Google Assistant households.
- Stereo Sound:True wireless stereo pairing enables left-right channel separation across two discrete units. Party and event use cases in Brazil and India favor this configuration.
- Battery Life:Lithium-ion cell capacity scaling from 2000mAh to 10000mAh extends playback duration at 50% volume. REACH compliance for European markets restricts hazardous substance thresholds in cell chemistry.
Dominant by shipment volume: Battery Life specifications. Fastest feature integration: Voice Assistant.
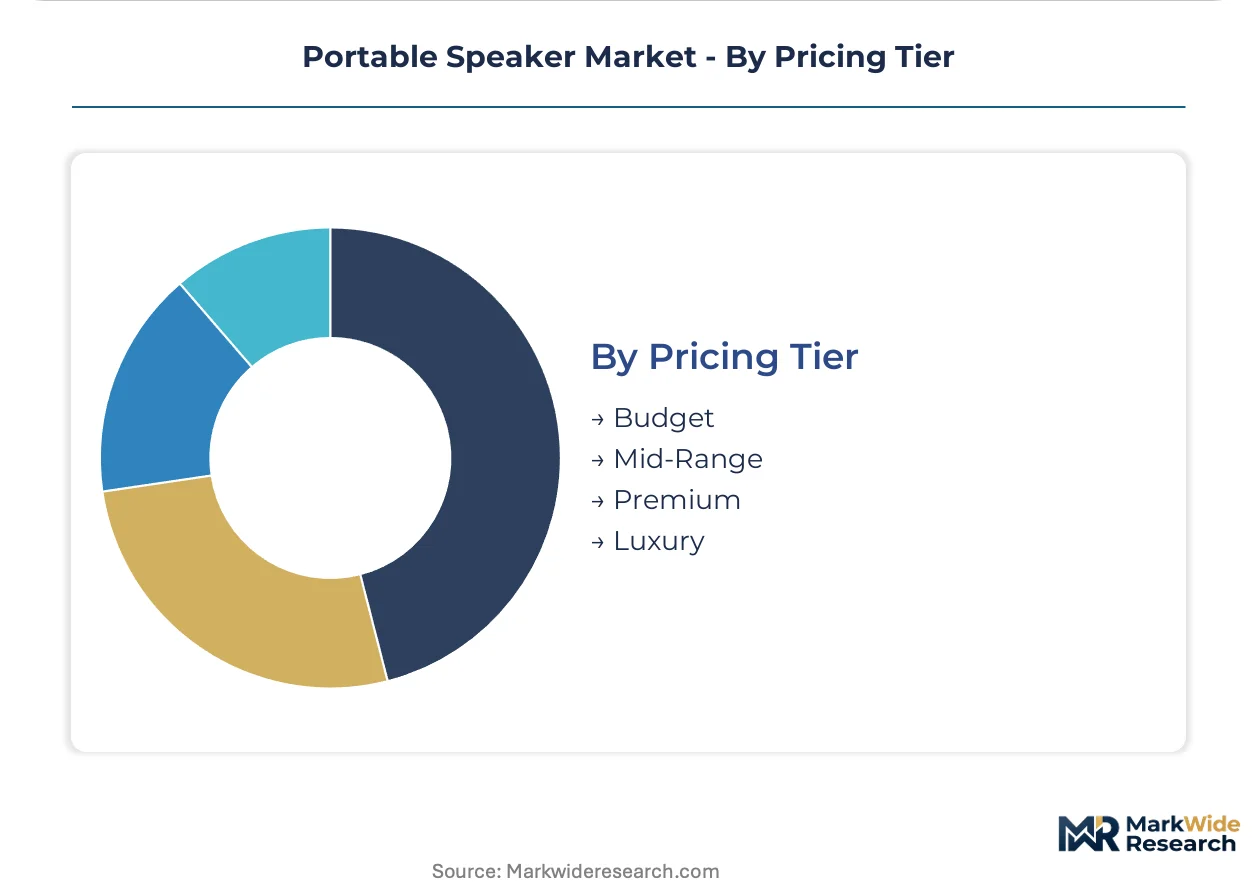
Pricing Tier:
Margin pool distribution follows certification investment recovery and acoustic engineering differentiation.
- Budget:Sub-$50 positioning relies on single-driver configurations and ABS plastic enclosures without spatial audio processing. Supply chain scale and retail distribution bypass define competitive viability.
- Mid-Range:$50-150 bracket faces compression from dual-certification demands without commensurate pricing power. Codec compatibility investments in Dolby Atmos and Sony 360 Reality Audio strain margins.
- Premium:$150-300 tier commands pricing power through acoustic engineering heritage and multi-room ecosystem lock-in. Spatial audio certification replaces raw specification comparison as purchase determinant.
- Luxury:Above-$300 positioning requires aluminum or fabric-wrapped enclosures with custom-tuned DSP profiles. Limited production runs and brand heritage sustain margin premiums.
Highest unit volume: Budget. Gaining share fastest: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors contract manufacturing for portable audio hardware, with Dongguan and Guangzhou forming the Pearl River Delta electronics corridor that supplies components to brands worldwide.
United States
Outdoor recreation enthusiasts in Colorado and California compress replacement cycles toward IP-rated configurations with extended battery endurance. FCC Part 15 certification governs Bluetooth transmission power limits and RF exposure testing, extending product launch timelines. Austin and Seattle host voice assistant engineering teams developing far-field microphone arrays for smart speaker integration.
China
MIIT enforces GB standards for wireless equipment certification, shaping export eligibility for manufacturers in Shenzhen and Dongguan. Dual carbon goals under MEE directives accelerate lithium-ion cell recycling mandates. Guangzhou assembly plants scale production of mini speakers for direct-to-consumer channels targeting Southeast Asian markets.
Germany
Facility managers in Bavaria and North Rhine-Westphalia prioritize CE-marked inventory for liability reduction in commercial procurement. REACH compliance demands granular material disclosure for circuit assemblies and battery chemistries. Berlin audio engineering clusters concentrate spatial audio DSP firmware expertise for premium tier certification.
India
PLI scheme incentives attract contract manufacturers to establish export-competitive assembly bases in Maharashtra and Tamil Nadu. BIS certification requirements for wireless equipment create compliance barriers for unbranded imports. Bangalore and Hyderabad engineering centers develop cost-optimized Class D amplification modules for budget tier positioning.
Japan
METI energy efficiency standards shape battery management system requirements for domestic market entry. Osaka and Nagoya industrial districts concentrate precision acoustic component fabrication for luxury tier enclosures. Tokyo consumer electronics retail channels prioritize Sony 360 Reality Audio certification as a purchase determinant.
Portable Speaker Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification investment recovery and acoustic engineering differentiation. The vendor base stratifies into heritage audio brands with spatial audio certification, consumer electronics conglomerates spanning multiple price tiers, and supply-chain-scale specialists dominating direct channels. Three archetypes dominate: ecosystem-locked premium houses, diversified technology conglomerates, and vertically integrated value players. Competitive moves concentrate on voice assistant licensing partnerships and modular design patents for right-to-repair compliance.
Within the heritage audio tier, Bose Corporation and Bang & Olufsen occupy positions sustained by acoustic engineering credibility and limited production positioning. Sony Group Corporation exemplifies the diversified conglomerate archetype, spanning premium home audio through mid-range portability. Anker anchors the supply-chain-scale specialist tier, demonstrating margin recovery through direct-to-consumer channel control and Shenzhen-based manufacturing proximity.
| Leading Market Players |
|---|
| Bose Corporation |
| Sony Group Corporation |
| JBL |
| Harman International |
| Ultimate Ears |
| Apple Inc. |
| Bang & Olufsen |
| Anker |
| Marshall Group |
| Others |
Supply Flow & Price Mechanics
Acoustic engineering talent concentration in Berlin and Shenzhen establishes labor-cost differentials that widen pricing-tier spreads between premium spatial audio certification and commodity Bluetooth configurations. REACH compliance teams in Germany command salary premiums that feed into luxury-tier markup structures, while Shenzhen assembly labor sustains sub-$50 positioning through direct-to-consumer channel economics.
Pricing Analysis
Value-based pricing anchored to spatial audio certification and multi-room ecosystem lock-in dominates premium tiers, while commodity tiers compete on battery endurance specifications and IP rating thresholds. Price differentiation stems from codec licensing costs and FCC certification investment recovery. Pricing pressure stems from dual-certification demands in the mid-range bracket without commensurate pricing power. Students and commuter segments exhibit highest price sensitivity, while outdoor recreation enthusiasts accept premium positioning for ruggedized configurations.
Supply Chain Analysis
Certification and qualification gating through FCC Part 15 and MIIT GB standards concentrates supply chain leverage among established brands with dedicated compliance teams. Manufacturing gravity centers on China, Vietnam, and India for assembly operations, with lithium-ion cell supply anchored in China and South Korea. Raw material dependencies include neodymium magnets for drivers, lithium carbonate for cells, and ABS or aluminum for enclosures. Single-source vulnerability in rare earth magnet supply creates structural risk. Distribution runs through direct-to-consumer channels and electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive lithium-ion cell supply and in-house DSP firmware development determine margin sustainability. Players are pursuing backward integration into battery cell production as the decisive upstream lever.
For Market Incumbents: To counter smartphone audio substitution and compressed mid-tier margins, deepen ecosystem lock-in through multi-room certification expansion and accelerate modular design patent filings for right-to-repair compliance. Prioritize captive supply arrangements with Shenzhen-based cell manufacturers to insulate against input cost volatility. For New Entrants and Emerging Players: Voice assistant protocol integration as a technology-first wedge opens procurement channels among smart home adopters seeking Alexa and Google Assistant convergence. White-space targets include GDPR-compliant enterprise smart speaker procurement in Germany and IP67-rated outdoor configurations for camping enthusiasts in Colorado and California. Go-to-market leverage rests on direct-to-consumer channel control bypassing traditional retail distribution. For Investors and Strategic Acquirers: Re-rating potential sits with heritage audio brands possessing spatial audio certification dossiers given voice assistant licensing partnership momentum. Long-term viability favors manufacturers with demonstrated FCC and CE certification velocity and documented REACH compliance infrastructure. The signal to watch is modular design patent filing velocity as an inflection indicator for right-to-repair regulatory adaptation.| Strategic Initiative | Industry Significance |
|---|---|
| Spatial Audio Certification Acquisition | Dolby Atmos and Sony 360 Reality Audio badges command pricing power in premium tiers. |
| Voice Assistant Protocol Integration | Alexa and Google Assistant embedding creates ecosystem-dependent replacement demand. |
| Direct-to-Consumer Channel Expansion | Bypassing retail distribution recovers margin compression from certification investments. |
| Modular Design Patent Development | Right-to-repair compliance in France and Germany opens aftermarket service revenue. |
| Lithium-Ion Cell Supply Integration | Captive supply arrangements insulate against geopolitical exposure and input volatility. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with product managers at audio hardware brands, procurement leads at electronics retailers, acoustic engineering directors, FCC compliance consultants, and supply chain planners at Shenzhen contract manufacturers. Secondary sources included FCC equipment authorization databases, MIIT GB standard filings, EU REACH substance registrations, and import-export customs documentation. Bottom-up shipment estimates triangulated against top-down consumer spending data.
Data-stream reconciliation across manufacturer shipment disclosures, retail sell-through tracking, and component procurement patterns informed the analytical framework. Segmentation dimensions modeled included product type, pricing tier, end-user archetype, and feature integration level across the projection horizon. CAGRs derived from regression analysis against macroeconomic indicators and replacement cycle compression factors. Industry-specific inputs incorporated Bluetooth protocol adoption curves and spatial audio codec licensing trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption scenarios or accelerated right-to-repair regulatory expansion. Forecasts reflect assumptions regarding replacement cycle stability and certification timeline consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Nanopresso Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Kindle E-Reader Accessories Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market