
 3D Glasses Chargers Market | 2026-2036
3D Glasses Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
3D Glasses Chargers Market Analytics
East Asian contract manufacturers is decoupling from legacy infrared charging modules as Qi wireless and USB-C protocols gain traction. Samsung Electronics leverages its display ecosystem to bundle proprietary docking stations with premium 3D television lines. Sony Corporation anchors its PlayStation VR charging infrastructure through dedicated RF-compatible base stations. LG Electronics differentiates by integrating multi-device Qi pads that serve both 3D glasses and companion remotes.
3D glasses chargers are electromechanical accessories designed to replenish power cells within active-shutter or polarized eyewear, typically delivering 5V DC via inductive coils or conductive pins with charging cycles under two hours for lithium-polymer cells rated between 70 and 150 mAh. These devices serve cinema exhibitors, gaming peripheral distributors, and consumer electronics retailers by minimizing downtime between 3D content sessions. Wireless charging methods are capturing margin pools as Qi-enabled pads command premium positioning against plug-in alternatives, while USB-C compatibility segments are maturing rapidly due to universal cable standardization. Bluetooth synchronization technology is outpacing infrared in new installations as RF protocols eliminate line-of-sight constraints in theater environments.
FCC Part 15 rules govern unintentional radiators in the US, while CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility for wireless charging pads sold in Europe. China's MIIT enforces GB standards for short-range radio transmission in consumer accessories, creating divergent certification burdens for multi-region suppliers. Stakeholders must monitor evolving battery safety directives from IEC and national regulators as higher-density cells enter next-generation 3D eyewear designs.
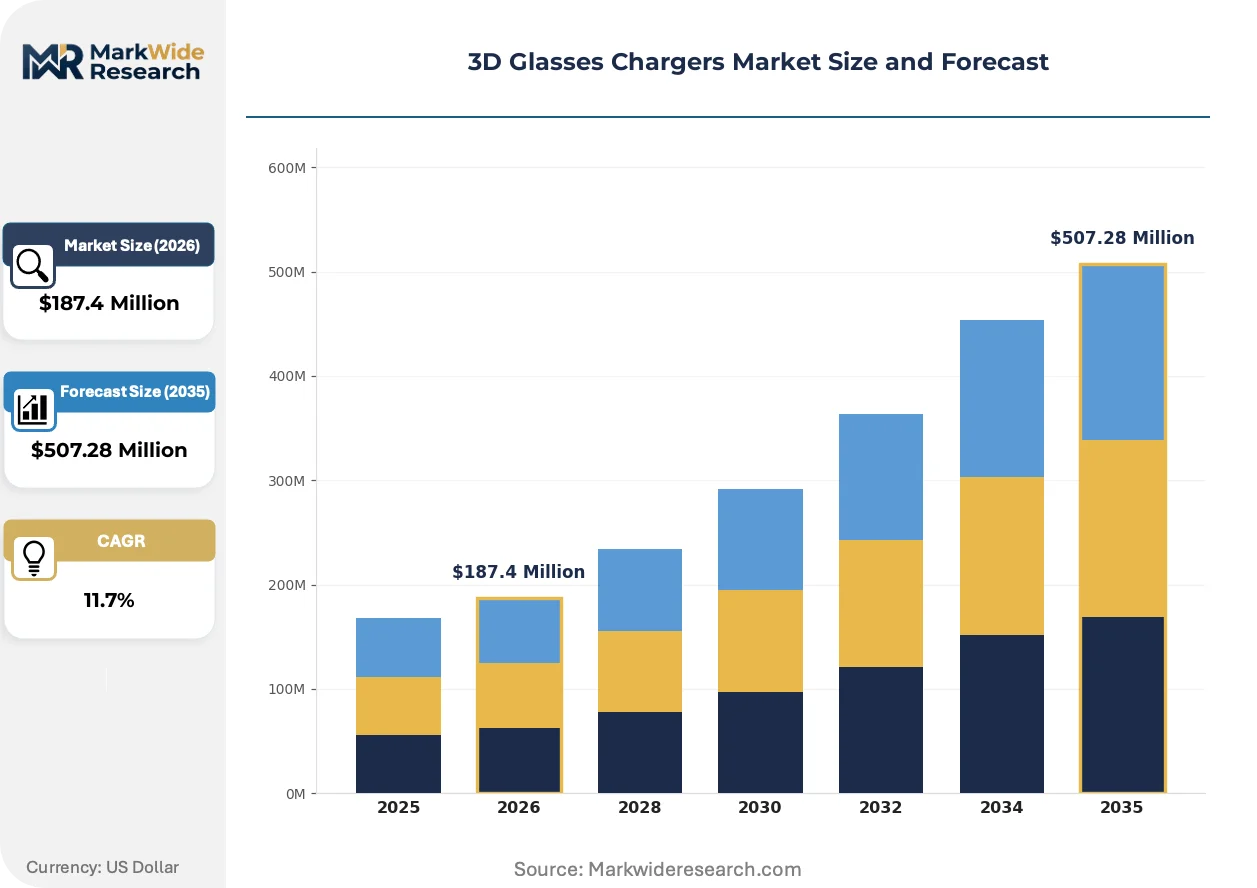
Market Dynamics
Qi wireless charging protocols and USB-C harmonization under IEC standards are compressing legacy infrared modules while forcing multi-region certification stacks on contract manufacturers serving cinema and VR headset supply chains.
Growth Catalysts
- CE marking under EU Radio Equipment Directive:Electromagnetic compatibility mandates for wireless charging pads accelerate design standardization across European consumer electronics retail channels.
- Active-shutter charging systems:Cinema chains expand procurement of rapid-cycle docking stations to minimize downtime between 3D content sessions in multiplex environments.
- Shenzhen electronics clusters:OEM supply chain concentration feeds component cost efficiencies for VR headset accessory manufacturers targeting gaming peripheral distributors.
Market Restraints
- Lithium-polymer cell density limitations:Higher-density battery chemistries required for next-generation 3D eyewear face thermal stability constraints under IEC safety directives.
- MIIT GB standard divergence:China's short-range radio transmission requirements create certification burdens distinct from FCC Part 15 and CE frameworks, fragmenting test protocols.
- Polarized eyewear substitution:Passive 3D glasses eliminate charging infrastructure entirely, threatening addressable demand in budget cinema installations.
Strategic Opportunities
- Multi-device Qi pad convergence:Integration of 3D glasses and companion remote charging on unified inductive surfaces opens premium positioning in home theater installer channels.
- Bluetooth RF synchronization:Elimination of line-of-sight constraints in theater environments enables retrofit opportunities for infrared-dependent legacy installations.
- India's PLI scheme for electronics manufacturing:Contract manufacturer migration to Indian production zones diversifies supply concentration beyond East Asian clusters.
Industry Challenges
- EMC certification timeline compression:Simultaneous FCC Part 15, CE marking, and MIIT GB test sequences extend product launch cycles for multi-region suppliers.
- Legacy infrared inventory obsolescence:Rapid protocol migration leaves stranded component stocks and tooling investments in contract manufacturer warehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Glasses Chargers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active, Passive, Wireless, Plug-In Technology: Infrared, RF, Bluetooth, HDMI Compatibility: VR Headsets, Gaming Consoles, TVs, PC Monitors Charging Method: USB-C, Qi, Solar, Docking Station |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Panasonic Corporation, Epson America, RealD Inc., NVIDIA Corporation, Corning Incorporated, Shenzhen O-Film Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Glasses Chargers Market Evolving Landscape
Wireless power transfer architectures and radio-frequency synchronization protocols are displacing conductive pin and infrared legacy systems across cinema and home theater installations.
Qi inductive charging is converging with USB-C power delivery standards in next-generation 3D glasses dock designs. Home theater installers specify these dual-protocol units to accommodate mixed-device households. The convergence is compressing SKU proliferation for electronics distributors while raising average selling prices against single-method legacy alternatives.
FCC Part 15 rules governing unintentional radiators now require expanded testing for harmonic emissions from multi-coil wireless charging arrays. Cinema exhibitors deploying these systems in multiplex environments face compliance verification delays. US-based peripheral distributors are responding by pre-certifying entire docking station SKUs rather than modular components.
Buyer concentration among cinema chains is compressing negotiation cycles for charging infrastructure procurement. Bulk tender processes displace spot purchasing through traditional AV equipment dealers. This pattern is most visible in China, where Wanda Cinema and Dadi Film Holding centralize accessory procurement through Shenzhen-based OEM direct contracts.
3D Glasses Chargers Market Segmentation
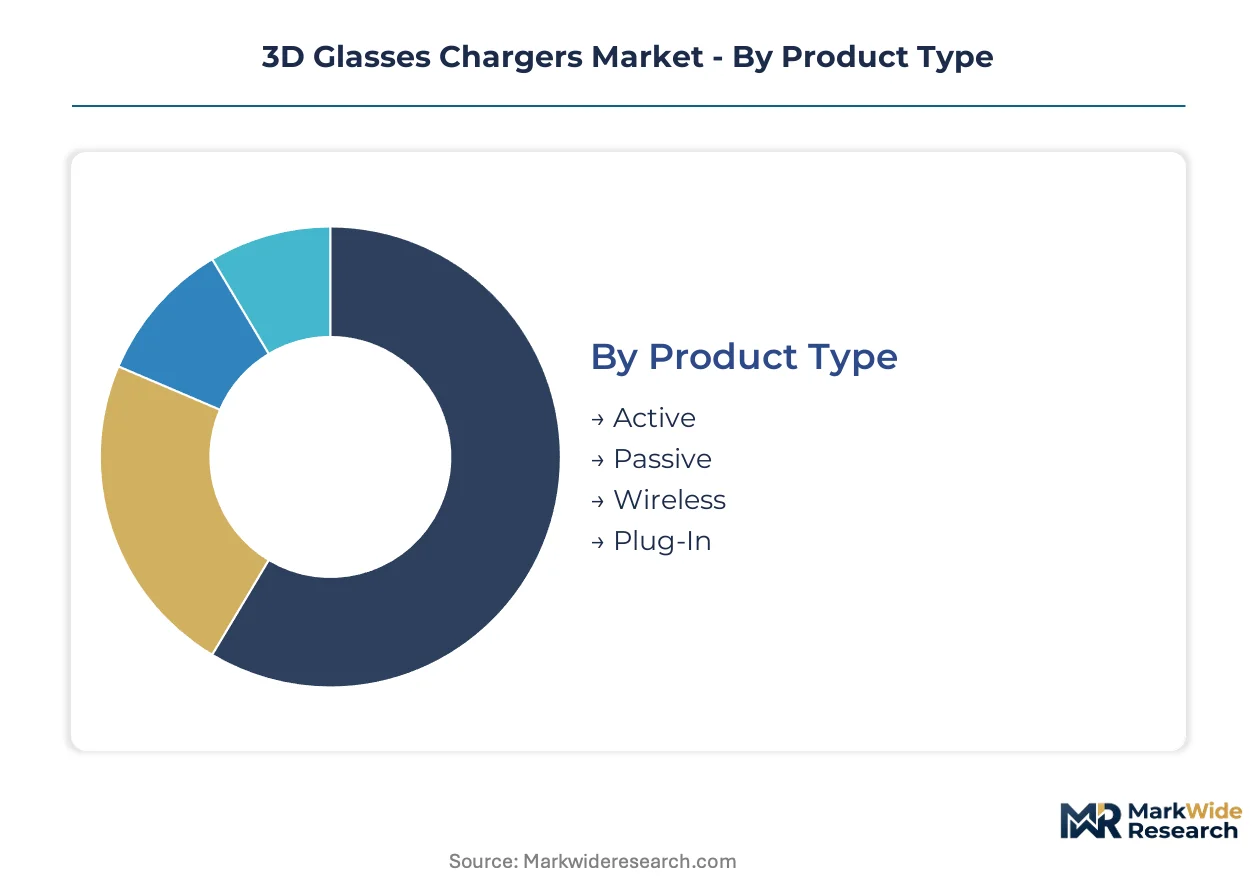
3D glasses chargers fragment across four distinct category axes. Procurement decisions hinge on protocol compatibility, power delivery specifications, and installation environment constraints rather than brand preference alone.
Product Type:
Cost tier determines procurement channel access and margin structure for distributors serving cinema versus home theater segments.
- Active:Electromechanical shutters require lithium-polymer replenishment cycles under two hours via conductive pins or inductive coils. Cinema chains in China centralize procurement of active-shutter docking stations through Shenzhen OEM contracts to minimize multiplex downtime.
- Wireless:Qi-enabled pads eliminate contact-point wear and command premium positioning against plug-in alternatives. Home theater installers specify these units for mixed-device households seeking unified charging surfaces.
- Passive:Polarized eyewear eliminates charging infrastructure entirely, threatening addressable demand in budget cinema installations.
- Plug-In:Legacy conductive pin systems dominate retrofit opportunities for infrared-dependent theater environments.
Volume sits with Active; growth tilts toward Wireless.
Technology:
Application environment dictates RF versus optical protocol selection, with line-of-sight constraints driving replacement cycles in commercial installations.
- Bluetooth:RF synchronization eliminates line-of-sight requirements and enables retrofit opportunities for legacy infrared theater systems. Multiplex operators in the US prioritize Bluetooth base stations to reduce seat-to-seat interference.
- Infrared:Legacy optical modules face rapid displacement as Qi wireless and USB-C protocols compress their installed base. Stranded component stocks accumulate in East Asian contract manufacturer warehouses.
- RF:Dedicated radio-frequency base stations anchor Sony's PlayStation VR charging infrastructure through proprietary docking ecosystems.
- HDMI:Video-integrated power delivery serves niche PC monitor applications requiring synchronized signal and charging pathways.
Deployment concentrates with Bluetooth; replacement demand favors RF.
Compatibility:
Customer type segmentation separates enterprise procurement cycles from consumer retail velocity, with gaming peripheral distributors operating on fundamentally different inventory turns than AV equipment dealers.
- VR Headsets:Shenzhen electronics clusters feed OEM supply chains for Meta and Sony accessory ecosystems, concentrating component sourcing in East Asian manufacturing zones.
- Gaming Consoles:Sony leverages its PlayStation display ecosystem to bundle proprietary charging infrastructure with premium peripheral lines.
- TVs:Samsung bundles proprietary docking stations with premium 3D television lines, locking accessory revenue to display purchase cycles.
- PC Monitors:LG integrates multi-device Qi pads serving both 3D glasses and companion remotes, differentiating through unified inductive surfaces.
Revenue clusters with VR Headsets; margin expansion targets Gaming Consoles.
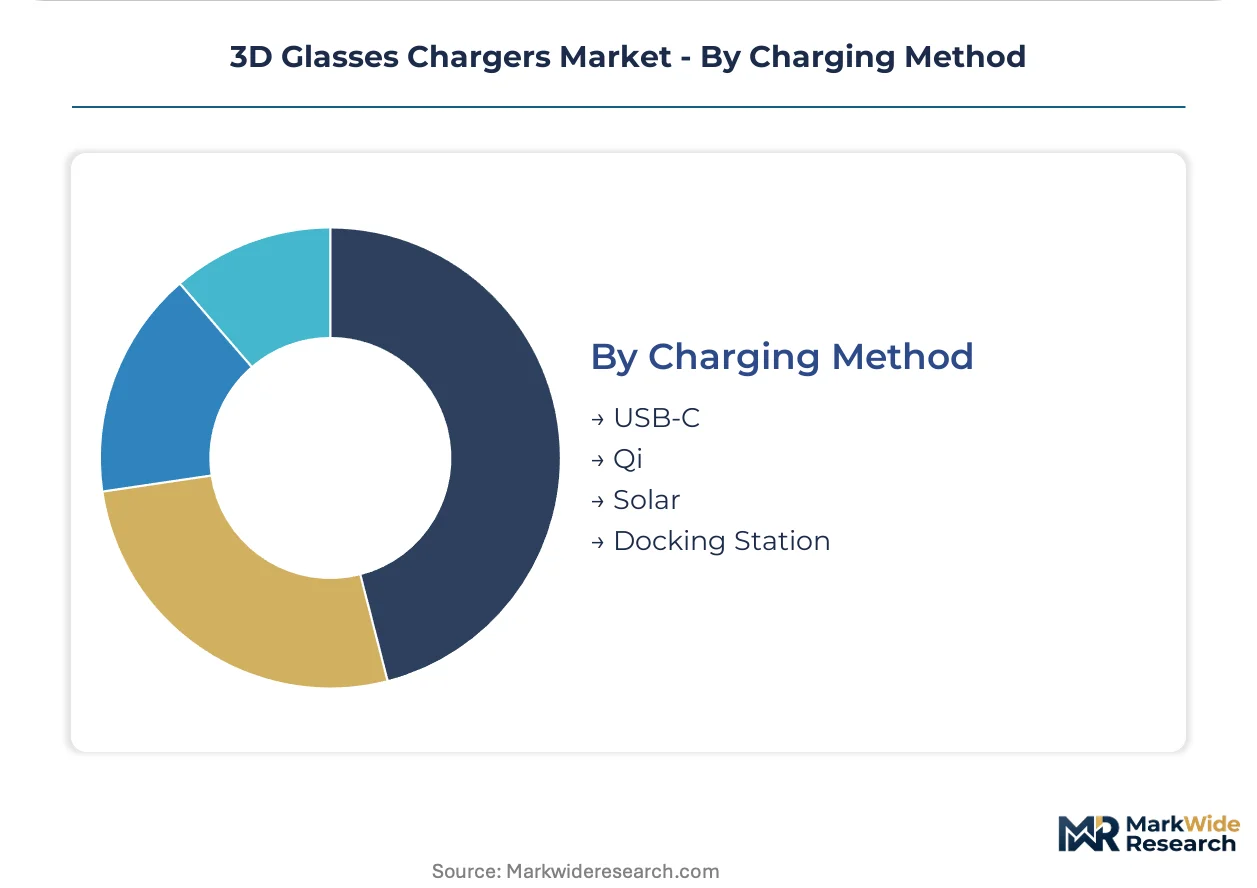
Charging Method:
Maturity curves diverge sharply between harmonized standards and emerging alternatives, with certification timelines compressing design choices for multi-region suppliers.
- USB-C:IEC standardization drives rapid segment maturation as universal cable protocols reduce SKU proliferation for electronics distributors. CE marking under EU Radio Equipment Directive accelerates design standardization across European retail channels.
- Qi:Wireless power transfer architectures capture premium positioning against conductive alternatives, though FCC Part 15 rules now require expanded harmonic emissions testing for multi-coil arrays.
- Solar:Photovoltaic integration remains experimental for low-power eyewear cells, constrained by surface area limitations and theater lighting conditions.
- Docking Station:Bulk tender processes through cinema chains displace spot purchasing, compressing negotiation cycles for charging infrastructure procurement.
Standardization favors USB-C; premium positioning accrues to Qi.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-polymer cell manufacturing concentrates in East Asian industrial zones, with Shenzhen electronics clusters feeding component supply chains for active-shutter charging systems across cinema and VR headset distribution channels.
China
Wanda Cinema and Dadi Film Holding centralize charging infrastructure procurement through direct Shenzhen OEM contracts, compressing negotiation cycles for multiplex operators. MIIT enforces GB standards for short-range radio transmission in consumer accessories, creating certification requirements distinct from Western frameworks. Guangdong Province electronics clusters dominate contract manufacturing for Qi-enabled pad production serving Meta and Sony accessory ecosystems.
United States
Multiplex operators prioritize Bluetooth base stations to reduce seat-to-seat interference in theater environments, driving retrofit demand for infrared-dependent legacy installations. FCC Part 15 rules require expanded harmonic emissions testing for multi-coil wireless charging arrays, extending compliance verification timelines. California-based peripheral distributors respond by pre-certifying entire docking station SKUs rather than modular components.
Germany
CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility for wireless charging pads, accelerating design standardization across European consumer electronics retail channels. Home theater installers in Bavaria and North Rhine-Westphalia specify dual-protocol Qi and USB-C units to accommodate mixed-device households. Industrial clusters around Munich anchor distribution logistics for premium inductive charging surfaces.
Japan
Sony anchors PlayStation VR charging infrastructure through dedicated RF-compatible base stations, locking accessory procurement to gaming peripheral distribution channels. METI standards govern short-range radio equipment certification, creating procedural alignment with export market requirements. Tokyo-Osaka industrial corridors concentrate precision manufacturing for lithium-polymer cell integration in next-generation eyewear designs.
South Korea
Samsung leverages its display ecosystem to bundle proprietary docking stations with premium 3D television lines, capturing accessory revenue through locked purchase cycles. MFDS regulates battery safety protocols for consumer electronics, influencing cell chemistry selection in active-shutter designs. Seoul Capital Area manufacturing zones supply component assemblies for wireless charging coil production.
3D Glasses Chargers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in multi-device convergence and RF synchronization protocols. The vendor base stratifies across three tiers: display ecosystem bundlers leveraging captive hardware channels, contract manufacturers serving cinema chain bulk tenders, and component specialists supplying inductive coil assemblies. Two strategic archetypes dominate competitive positioning—vertical display integrators and independent charging infrastructure suppliers. Capacity expansion and technology licensing represent the dominant competitive moves, with players securing Qi protocol certifications and USB-C IEC harmonization to compress legacy infrared market share.
Among East Asian electronics conglomerates, Samsung Electronics and LG Electronics exemplify the display-integrated archetype, bundling proprietary charging infrastructure with premium television and home theater product lines. Sony Corporation occupies a distinct position anchoring gaming-centric VR charging ecosystems through dedicated base station development. These three entities represent the tier capturing margin through hardware-lock strategies rather than independent accessory distribution.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Panasonic Corporation |
| Epson America |
| RealD Inc. |
| NVIDIA Corporation |
| Corning Incorporated |
| Shenzhen O-Film Tech |
| Others |
Value Network & Pricing Analysis
Cinema chain bulk tender processes for active-shutter charging systems compress supplier margins and force component standardization across Shenzhen-based contract manufacturers, pushing pricing stratification toward volume-tiered contracts rather than spot-market premiums.
Pricing Analysis
Warranty bundling separates premium Qi-enabled docking stations from economy plug-in alternatives, with cinema exhibitors paying for extended service coverage on multiplex deployments. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier differentiation—FCC Part 15 pre-certified units command spreads over uncertified alternatives. Cost compression in the plug-in segment intensifies as USB-C harmonization erodes proprietary connector premiums. Home theater installers show lowest price sensitivity due to project-billing pass-through structures, while budget cinema operators drive hardest negotiation on per-unit procurement.
Supply Chain Analysis
Reverse logistics flows for defective lithium-polymer cells and warranty-returned docking stations concentrate refurbishment activity in Guangdong Province electronics clusters. Component sourcing draws from China, South Korea, and Japan for inductive coil assemblies, battery cells, and RF synchronization modules. Single-source vulnerability sits with Shenzhen-based OEMs feeding Meta and Sony accessory ecosystems. Distribution runs through AV equipment dealers for home theater segments and direct OEM contracts for cinema chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qi wireless charging protocols are displacing legacy infrared modules across cinema and home theater installations, compressing the addressable window for conductive-pin suppliers and reshaping competitive positioning toward RF-synchronization capabilities.
For Market Incumbents: Deploy certification pre-investment as a defensive moat against multi-region compliance fragmentation. Samsung Electronics and LG Electronics should deepen backward integration into inductive coil manufacturing to capture margin from Shenzhen contract manufacturers. Sony Corporation must accelerate RF base station development before Bluetooth synchronization commoditizes theater infrastructure. Threat of passive 3D eyewear substitution in budget cinema segments demands premium feature differentiation through multi-device Qi pad convergence. For New Entrants and Emerging Players: Launch via home theater installer channels where project-based procurement tolerates higher price points and specification complexity. India's PLI scheme for electronics manufacturing offers the most penetrable geography for contract manufacturer migration beyond East Asian concentration. White-space targets include Bluetooth retrofit kits for infrared-dependent legacy theater installations and multi-device Qi pads serving companion remote convergence. Direct-to-installer technical training programs accelerate specification capture against established distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with component specialists holding Qi protocol certifications and USB-C IEC harmonization given standardization catalysts compressing legacy market share. Long-term viability favors suppliers with cinema chain direct-contract relationships rather than AV dealer channel dependence. Acquisition target archetype: mid-cap inductive coil assemblers with MIIT GB pre-certification and Shenzhen manufacturing presence. Signal to monitor: bulk tender announcement velocity from Wanda Cinema and Dadi Film Holding as inflection indicator for infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Qi Protocol Certification Investment | Pre-certification under FCC Part 15 and CE marking accelerates multi-region market access for docking station suppliers. |
| Backward Integration into Coil Manufacturing | In-house production of inductive assemblies captures margin pools from Shenzhen contract manufacturer intermediation. |
| Bluetooth RF Synchronization Development | Elimination of line-of-sight constraints opens retrofit revenue from infrared-dependent legacy theater installations. |
| Multi-Device Qi Pad Convergence | Unified charging surfaces for 3D glasses and companion remotes differentiate premium positioning in home theater channels. |
| India PLI Manufacturing Migration | Electronics manufacturing incentive schemes diversify supply concentration beyond Guangdong Province clusters. |
Research Methodology
Independent corroboration across cinema procurement directors, home theater installer networks, and contract manufacturer operations managers underwrites the qualitative findings in this study. Primary interviews with OEM supply chain executives, AV equipment dealer principals, and lithium-polymer cell engineering teams combined with secondary validation from MIIT GB standard filings, FCC Part 15 equipment authorization databases, and IEC harmonization documentation. Bottom-up demand modeling from cinema chain tender announcements and top-down supply assessment from Shenzhen electronics cluster production data were triangulated for cross-verification.
Comparable-period anchoring to historical procurement cycles and technology replacement waves structured the projection methodology across the analysis window. Segmentation dimensions modeled include product type, technology protocol, compatibility category, and charging method, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived from volume-weighted average growth trajectories incorporating cinema screen expansion rates, VR headset accessory attach rates, and wireless charging adoption curves as sector-specific forecast inputs.
MIIT GB standard divergence, lithium-polymer cell thermal stability constraints, and passive 3D eyewear substitution acceleration are the dominant revision risks to the demand projections. Forecasts reflect assumptions regarding Qi protocol adoption velocity and USB-C harmonization timelines that regulatory shifts or technology disruptions could materially alter. Practitioners should monitor cinema chain bulk tender announcement patterns and VR headset OEM accessory specification changes for early signals of infrastructure replacement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Electronic Equipment Repair Service Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
A/V Cassette Housings & Parts Market