
 Action Camera Market | 2026-2036
Action Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Action Camera Market Analysis
Shortage of specialized optical engineers is bifurcating the competitive landscape between vertically integrated incumbents and component-dependent challengers. GoPro Inc. leverages its captive supply chain to control premium-tier pricing and accelerate iteration cycles. DJI Technology anchors its position through in-house gimbal stabilization expertise that extends into action camera product lines. Insta360 differentiates via 360-degree capture specialization that commands higher margins in the creator economy.
An action camera is a compact, ruggedized imaging device engineered for high-frame-rate video capture in extreme motion environments, typically incorporating CMOS sensors, wide-angle lenses, electronic image stabilization, and sealed enclosures rated for submersion. Its primary commercial purpose is to generate first-person perspective content for sports documentation, travel media, and social platform distribution. Wearable configurations dominate volume shipments among product types due to chest- and head-mount compatibility with athlete workflows. Image stabilization technology captures disproportionate R&D investment as manufacturers compete on smooth footage quality without post-processing. Online retail channels are consolidating share among distribution channels, compressing margins for electronics stores while enabling direct-to-creator relationships.
FCC equipment authorization governs wireless transmission modules in United States-bound units, while CE marking requirements under EU RoHS and REACH directives constrain material composition for European market access. China's MIIT enforces GB standards for radio frequency emissions, creating a three-jurisdiction compliance burden for global suppliers. Waterproof IP ratings and battery safety certifications from IEC further shape product development roadmaps. Stakeholders must monitor how evolving platform content monetization rules alter creator hardware refresh cycles and premium feature prioritization.
Market Dynamics
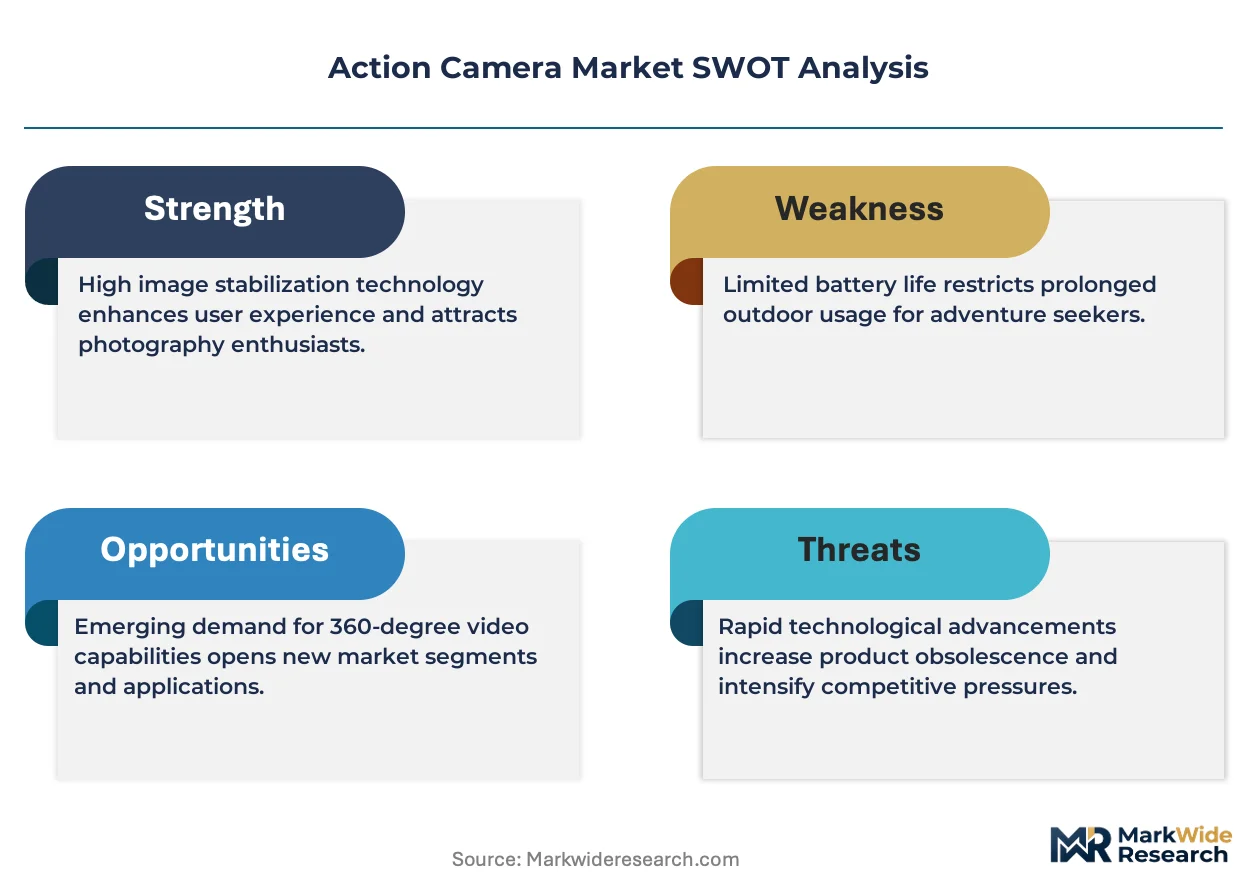
Electronic image stabilization is compressing product lifecycles as manufacturers race to deliver gimbal-grade smoothness without mechanical hardware, forcing R&D budgets toward computational photography and away from lens mechanics.
Growth Catalysts
- Content Creator Economy:Platform monetization rules on YouTube and TikTok incentivize hardware upgrades among mid-tier creators seeking 4K output quality.
- EU Battery Regulation:Standardized replaceability mandates under the 2023 framework are accelerating modular design investments across European-bound product lines.
- Computational Stabilization:AI-driven frame interpolation is reducing dependency on optical stabilization hardware, lowering BOM costs for entry-tier units.
Market Restraints
- CMOS Sensor Concentration:Sony and Samsung control advanced sensor supply, creating allocation risk during foundry capacity crunches.
- Waterproofing Certification Costs:IEC IP68 validation requires destructive testing protocols that add twelve to sixteen weeks to product launch timelines.
- Smartphone Substitution:Flagship phone cameras with Action Mode stabilization capture comparable footage for casual users, eroding impulse-purchase demand.
Strategic Opportunities
- India Creator Surge:Short-form video platform growth in tier-two cities is creating first-time buyer demand for sub-$200 ruggedized units.
- Live Streaming Integration:Built-in RTMP output for Twitch and YouTube Live is opening event-capture applications beyond traditional action sports.
- US IRA Clean Manufacturing Credits:Domestic assembly incentives are enabling cost-competitive production for North American market-bound inventory.
Industry Challenges
- Optical Engineering Talent Scarcity:Lens design expertise concentrates in Japan and Germany, forcing competitors into expensive relocation or remote contracting arrangements.
- Multi-Jurisdiction Certification Burden:Simultaneous FCC, CE, and MIIT approval processes require dedicated compliance teams that strain mid-cap engineering budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Action Camera Market |
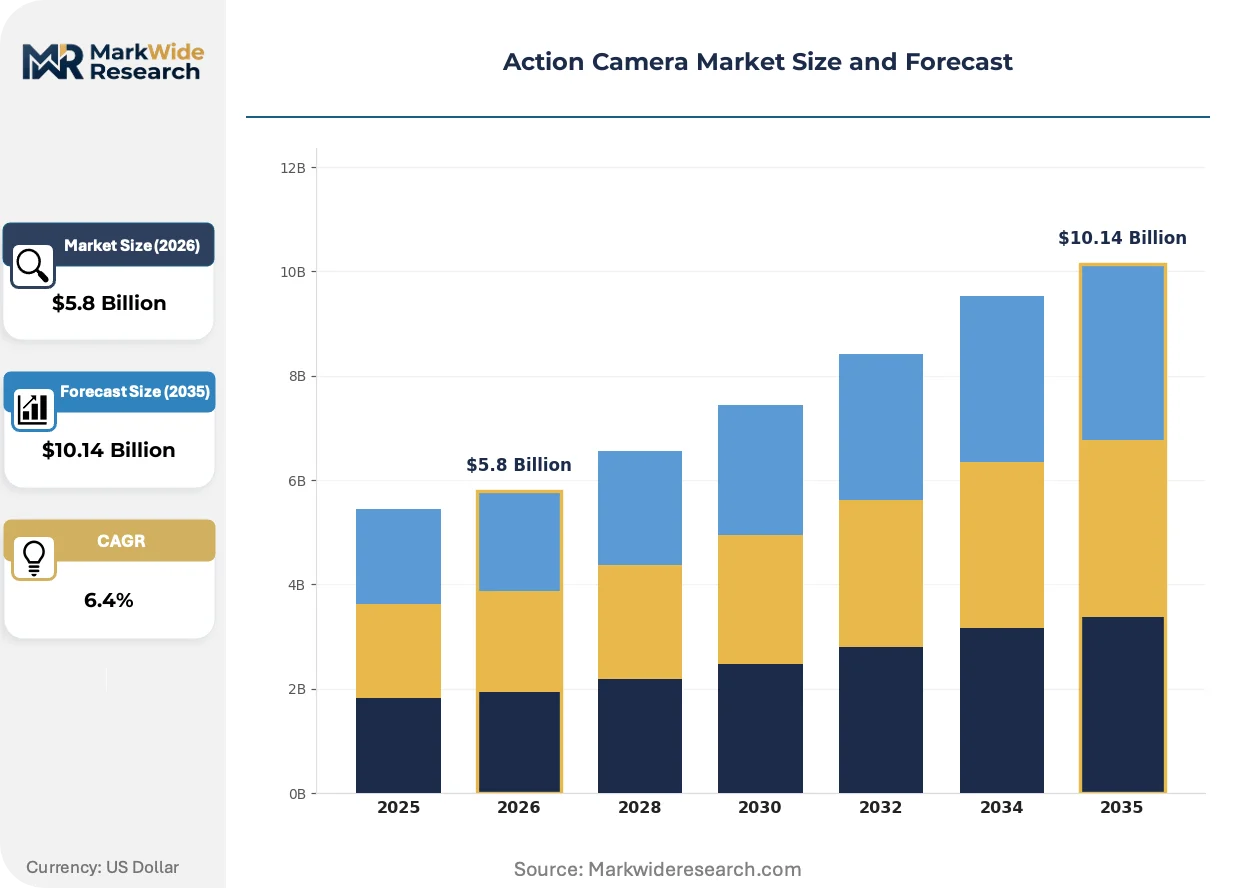
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Handheld, Drone-mounted, Fixed Installation End User: Athletes, Content Creators, Travelers, Outdoor Enthusiasts Technology: 4K Video, Waterproof, Bluetooth, Image Stabilization Distribution Channel: Online Retail, Electronics Stores, Sports Outlets, Specialty Shops |
| Companies Covered | Sony Corporation, Nikon Corporation, GoPro Inc., SJCAM, Akaso, DJI Technology, Garmin Ltd., YI Technology, Insta360, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Action Camera Market Emerging Trajectories
Computational capture methods are redistributing value from hardware specifications to software processing pipelines, altering how manufacturers compete on image quality and feature differentiation.
Sensor-shift stabilization is displacing traditional lens-based optical image stabilization in flagship action camera designs. Adventure sports filmmakers and professional content creators are adopting the technology fastest, prioritizing weight reduction for drone and helmet-mount applications. This shift is compressing margins for lens actuator suppliers while expanding addressable market for fabless semiconductor firms specializing in motion algorithms.
EU REACH substance restrictions are tightening compliance requirements for flame-retardant plastics and battery electrolyte formulations. Manufacturers serving European distribution channels must reformulate enclosure materials and document supply chain chemistry through SCIP database entries. Wearable product lines face the steepest cost adjustments due to skin-contact proximity thresholds under amended annex XVII listings.
Direct-to-creator sales channels are fragmenting traditional electronics retail dominance. Brand-owned storefronts and platform-integrated checkout on TikTok Shop and Instagram Shopping are capturing first-time buyers who previously visited physical stores for hands-on evaluation. This pattern is most pronounced in the United States and United Kingdom, where creator economy platform integration has advanced farthest.
Action Camera Market Segmentation
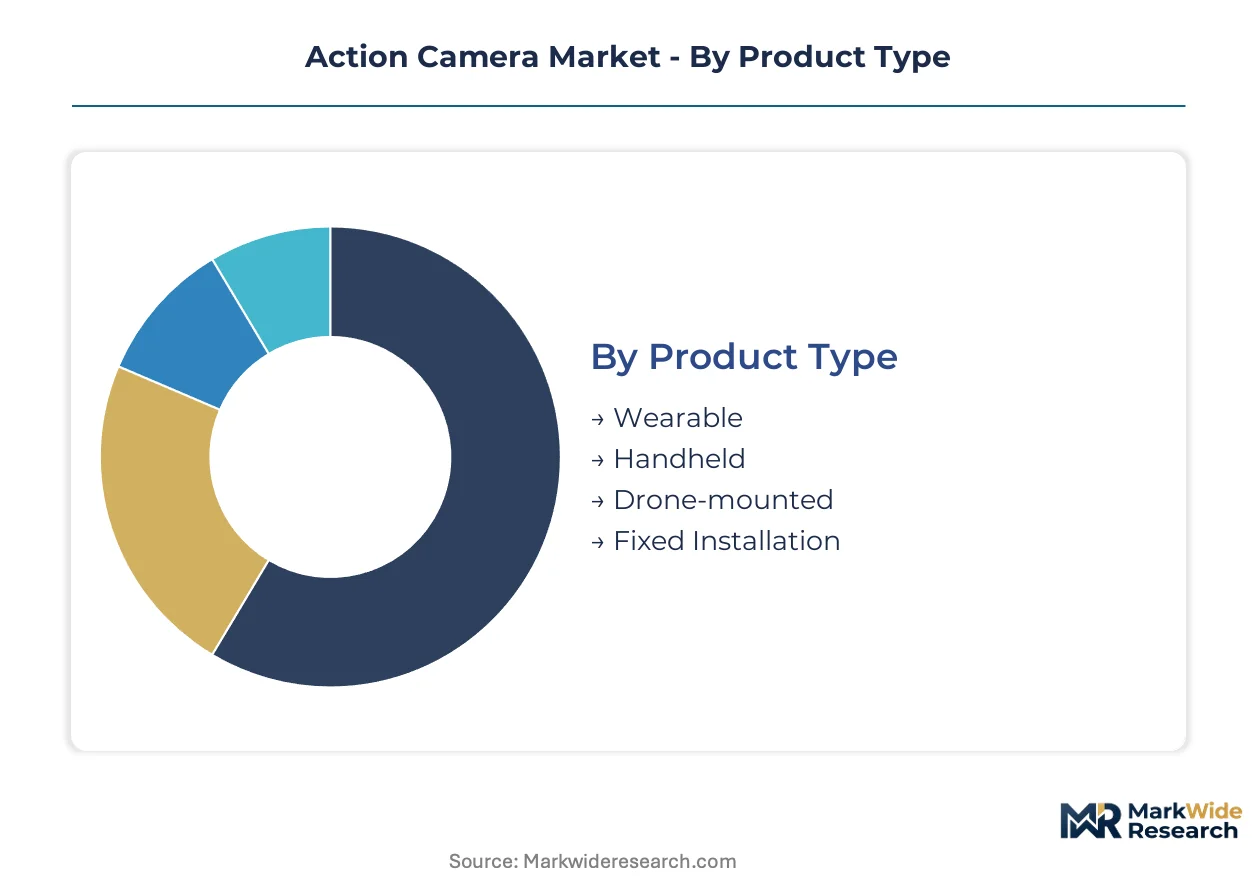
Segmentation in the action camera market reveals how hardware specifications, user workflows, and channel economics split demand across divergent price-performance tiers. Manufacturers configure sensor arrays, mounting systems, and connectivity modules differently for each slice, creating specialized supply chains that resist easy consolidation.
Product Type:
Wearable configurations dominate domestic shipments in the United States and China, while drone-mounted units skew heavily toward export markets serving European aerial cinematography studios.
- Wearable:Chest harness and helmet-clip form factors integrate with athlete biomechanics for first-person perspective capture. Demand concentrates among triathletes and motocross riders in Germany and Australia, driven by platform monetization requirements for stabilized point-of-view footage.
- Handheld:Grip-stabilized housings prioritize vlogger ergonomics and selfie-mode articulation. Travel bloggers in Japan and South Korea drive replacement cycles, constrained by smartphone substitution in casual use cases.
- Drone-mounted:Gimbal-compatible lightweight chassis serve aerial videography professionals.
- Fixed Installation:Permanent-mount enclosures withstand continuous environmental exposure for surveillance and time-lapse applications.
Wearable commands the established base. The steepest expansion runs through drone-mounted.
End User:
Cost tier stratification separates professional creators investing in multi-unit arrays from casual outdoor enthusiasts purchasing single-device entry points.
- Content Creators:Multi-platform producers operating YouTube and TikTok channels require 4K output, log color profiles, and live-streaming RTMP integration. This segment drives premium-tier pricing in the United States and United Kingdom, where platform monetization thresholds demand hardware refresh cycles.
- Athletes:Competitive and recreational sports participants prioritize shockproofing, waterproof IP ratings, and mount ecosystem compatibility. Surfing communities in Australia and Brazil generate concentrated demand for saltwater corrosion resistance.
- Travelers:Lightweight portability dominates purchasing criteria over advanced stabilization features.
- Outdoor Enthusiasts:Hunting, fishing, and camping applications favor extended battery life and weather sealing.
Content creators absorb the highest average selling prices. Outdoor enthusiasts are gaining share fastest in emerging markets.
Technology:
Volume concentration in image stabilization and 4K video modules creates supply bottlenecks, while waterproofing and Bluetooth remain commoditized across price tiers.
- Image Stabilization:Computational and sensor-shift methods displace mechanical gimbals for weight reduction. Professional filmmakers in California and Bavaria adopt these systems for drone-mount applications, forcing R&D allocation toward motion algorithm development.
- 4K Video:High-bitrate encoding at 60fps serves platform algorithms that deprioritize lower-resolution content. Mid-tier creators in India and Indonesia drive volume growth as short-form platforms expand monetization programs.
- Waterproof:IP68-rated sealed enclosures without external housing.
- Bluetooth:Low-energy connectivity for remote trigger and smartphone preview.
4K video commands the established base. Image stabilization is climbing the fastest as manufacturers compete on smooth footage quality.
Distribution Channel:
Channel economics split between high-touch physical evaluation for first-time buyers and algorithm-driven discovery for repeat purchasers.
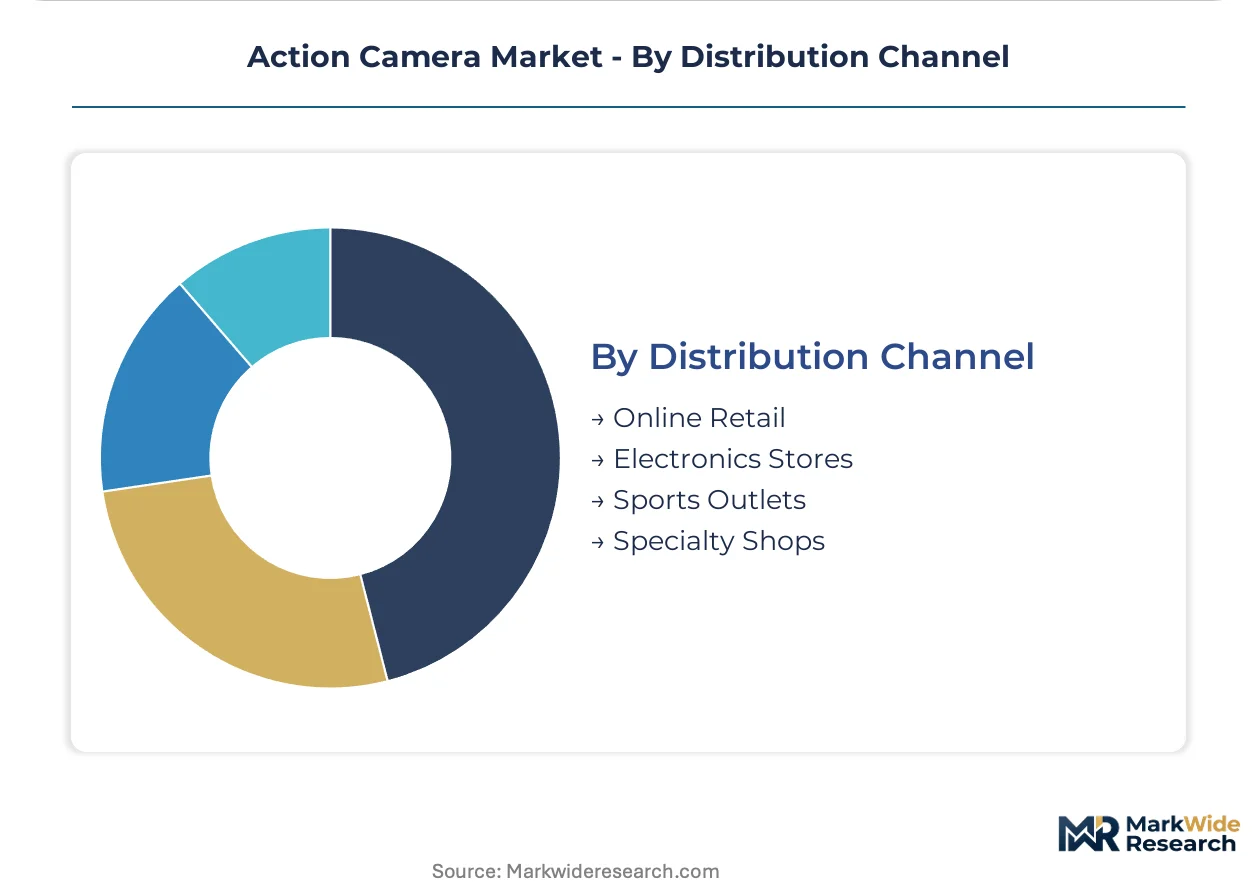
- Online Retail:Brand-owned storefronts and platform-integrated checkout capture creator economy participants. TikTok Shop and Instagram Shopping integration in the United States and United Kingdom compresses traditional electronics store margins while enabling direct-to-creator relationships.
- Electronics Stores:Hands-on demonstration and staff consultation serve first-time buyers evaluating mount compatibility and menu navigation. Retail footprints in Germany and Japan retain relevance for aging demographics less comfortable with pure-digital purchase journeys.
- Sports Outlets:Specialty retail co-located with equipment sales for skiing, cycling, and watersports.
- Specialty Shops:Professional cinematography and broadcast equipment dealers serving production houses.
Online retail commands the established base. Sports outlets are gaining share fastest as manufacturers pursue vertical placement alongside complementary equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creator economy monetization rules drive divergent consumption patterns across major economies. The United States prioritizes premium live-streaming capabilities for platform revenue optimization. Germany emphasizes waterproof durability standards for alpine and watersport documentation. China concentrates on compact form factors for short-form video platform integration.
United States
YouTube and TikTok monetization thresholds push mid-tier creators toward 4K output hardware with RTMP live-streaming integration. FCC equipment authorization governs wireless transmission modules, adding compliance lead time for new product launches. Los Angeles and Austin host dense creator economy clusters where hardware refresh cycles accelerate alongside platform algorithm changes.
Germany
Alpine skiing and mountain biking communities generate concentrated demand for shockproofing and helmet-mount compatibility. CE marking requirements under EU RoHS and REACH directives constrain material composition, particularly for flame-retardant plastics in wearable enclosures. Bavaria's outdoor equipment manufacturing corridor drives co-development partnerships between camera makers and mount system suppliers.
China
Short-form video platform dominance creates volume demand for sub-$200 units with integrated stabilization algorithms. MIIT enforces GB standards for radio frequency emissions, creating a parallel certification track for domestic-market inventory. Shenzhen's electronics manufacturing ecosystem anchors component sourcing for sensor modules and motion processing chipsets.
Japan
Travel vloggers and adventure filmmakers prioritize compact handheld form factors for solo content production. METI oversees industrial standards coordination, while PMDA regulates any health-adjacent wearable applications. Tokyo and Osaka metropolitan areas concentrate professional creator studios that drive premium-tier feature prioritization.
Australia
Surfing and ocean sports communities generate sustained demand for saltwater corrosion resistance and extended waterproof ratings. The country's national communications regulator enforces electromagnetic compatibility standards for wireless-enabled units. Gold Coast and Sydney host action sports content production hubs where hardware durability testing occurs in parallel with commercial filming.
Action Camera Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Vertically integrated incumbents control captive supply chains for premium-tier positioning and accelerated iteration cycles. Component-dependent challengers concentrate on modular designs and price-accessible entry points. Dominant competitive moves include backward integration into sensor calibration capabilities and geographic expansion through platform-integrated direct sales channels.
Within the integrated tier, GoPro Inc. and DJI Technology occupy positions defined by supply chain control and in-house stabilization expertise respectively. Insta360 exemplifies the specialist archetype through 360-degree capture specialization that commands differentiated margins. Garmin Ltd. anchors the durability-focused segment with navigation-adjacent positioning. These three company structures represent how competitive advantage distributes across integration depth versus feature specialization.
| Leading Market Players |
|---|
| Sony Corporation |
| Nikon Corporation |
| GoPro Inc. |
| SJCAM |
| Akaso |
| DJI Technology |
| Garmin Ltd. |
| YI Technology |
| Insta360 |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for CMOS sensor supply lock in both component access and cost visibility for vertically integrated manufacturers, insulating premium-tier producers from spot-market volatility while forcing challengers into higher-risk procurement strategies. This contract-structure pattern concentrates pricing power with Sony and Samsung as dominant sensor suppliers, compressing margins for brands dependent on allocation-based purchasing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the action camera market, with differentiation driven by stabilization performance tier and IP certification grade. Premium units command sustained margins through in-house gimbal calibration and 4K log-color output, while entry-tier pricing faces compression from smartphone substitution in casual use cases. Content creators show lowest price sensitivity due to platform monetization requirements, whereas outdoor enthusiasts in emerging markets exhibit highest elasticity.
Supply Chain Analysis
CMOS sensor fabrication chokepoints in Japan and South Korea tether global production to foundry capacity allocations at Sony and Samsung facilities. Supply draws from Taiwanese packaging houses for image signal processors, Chinese PCB manufacturers for compact enclosures, and German optical houses for lens elements. Single-source vulnerability concentrates in advanced sensor nodes, while distribution runs through Shenzhen hub operations serving Asia-Pacific demand and direct-to-creator channels in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative against smartphone Action Mode stabilization, which erodes impulse-purchase demand among casual users and forces hardware differentiation toward professional-grade features.
For Market Incumbents: Secure captive sensor calibration capabilities to defend premium-tier positioning against component-dependent challengers. Accelerate RTMP live-streaming integration to capture creator economy platform monetization workflows. Invest in modular battery architectures ahead of EU replaceability mandates to preempt compliance-driven cost disadvantages. For New Entrants and Emerging Players: Anchor in India's tier-two creator surge through sub-$200 ruggedized units with integrated stabilization algorithms. Target sports outlet placement alongside complementary equipment to bypass electronics store margin compression. Pursue platform-native checkout integration on TikTok Shop and Instagram Shopping to capture first-time buyers outside traditional retail channels. For Investors and Strategic Acquirers: Specialist firms with 360-degree capture expertise and direct-to-creator channel control represent priority acquisition targets. Long-term viability hinges on software processing pipeline differentiation as computational methods redistribute value from hardware specifications. Watch creator platform monetization rule changes as the inflection signal for hardware refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Calibration | Captive supply of stabilized imaging modules insulates GoPro and DJI from allocation crunches at Sony. |
| Direct-to-Creator Channel Expansion | Platform-integrated checkout on TikTok Shop captures first-time buyers outside traditional electronics retail. |
| Modular Battery Architecture Investment | EU Battery Regulation compliance ahead of mandate reduces European-bound product line redesign costs. |
| RTMP Live-Streaming Integration | Built-in output for Twitch and YouTube Live opens event-capture applications beyond action sports. |
| Computational Stabilization R&D | AI-driven frame interpolation lowers BOM costs for entry-tier units competing with smartphone substitution. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product managers at camera OEMs, optical engineering leads at lens houses, procurement directors at sensor distributors, and content creator equipment specialists. Secondary validation drew from FCC equipment authorization filings, MIIT GB standard registrations, EU REACH SCIP database entries, and customs trade data for CMOS sensor imports. Bottom-up shipment estimates triangulated against top-down market sizing across wearable, handheld, drone-mounted, and fixed installation configurations.
Across the analysis window, volume and value outputs reflect segmentation by product type, end user archetype, stabilization technology tier, and distribution channel. CAGRs were derived from trend extrapolation of creator economy platform monetization expansion, smartphone substitution elasticity curves, and regulatory compliance cost trajectories. Industry-specific inputs included sensor foundry capacity utilization rates, IP certification lead times, and platform algorithm changes affecting hardware refresh cycles.
Material uncertainties — foundry allocation crunches, platform content monetization rule revisions, and REACH substance restriction amendments — sit outside the modeled envelope. Forecasts reflect assumptions about sustained short-form video platform growth and stable trade policy conditions for electronics components. Practitioners should keep alternative scenarios live as creator hardware refresh cycles and premium feature prioritization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Baby Monitor Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Noise Cancelling Headphones Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Consumer Electronics Retail Market
Consumer Electronics
Smart DJ Controller Market