
 North America Smart TV Market | 2026-2036
North America Smart TV Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart TV Market Intelligence
Quantum dot film is expanding its share of premium panel stacks as manufacturers seek wider color gamut without OLED cost structures. Samsung Electronics Co., Ltd. leverages vertical control over quantum dot inkjet deposition to sustain margin advantages in QLED lines. LG Electronics Inc. anchors its North American position through OLED exclusivity in large-format panels. TCL Corporation competes aggressively on price-performance ratios in LED backlighting tiers.
A North America Smart TV is an internet-connected television set integrating embedded operating systems, application processors, and network interfaces to deliver on-demand content, interactive services, and over-the-air broadcasting through a single display device, typically featuring 4K resolution panels with refresh rates of 60Hz to 120Hz and HDR10 or Dolby Vision compliance. Its primary commercial purpose is to consolidate entertainment, gaming, and smart home control functions while capturing viewer data for programmatic advertising and subscription revenue sharing. LED displays occupy the highest shipment volumes across household and commercial installations, though OLED commands disproportionate margin pools in the home theatre application segment. Streaming remains the dominant application driver, while gaming-oriented panels with variable refresh rate technology represent the fastest-expanding niche within the product type matrix.
The FCC governs broadcast reception standards and electromagnetic emissions for connected displays sold in the United States, while Industry Canada sets parallel technical requirements for equipment authorization in Canadian markets. Energy Star certification and evolving EPA efficiency thresholds directly influence consumer purchasing incentives and retailer stocking decisions across both countries. Stakeholders must monitor how HDMI specification releases and regional energy mandates alter hardware refresh cycles and component sourcing requirements.
Market Dynamics
Hospitality chains across the United States and Canada are accelerating fleet-wide replacements of legacy displays with internet-connected screens, compressing replacement cycles and redistributing procurement volume toward commercial-grade panels with embedded content management systems.
Growth Catalysts
- FCC Digital Television Transition Mandates:Broadcast reception standards continue reshaping hardware procurement criteria for consumer and commercial installations, forcing upgrades across installed bases.
- Broadband Infrastructure Expansion:California, Texas, and Ontario concentrate demand where fiber and cable networks support 4K and 8K streaming adoption at household scale.
- Quantum Dot Film Adoption:Manufacturers seek wider color gamut performance without OLED cost structures, expanding premium panel stack configurations.
Market Restraints
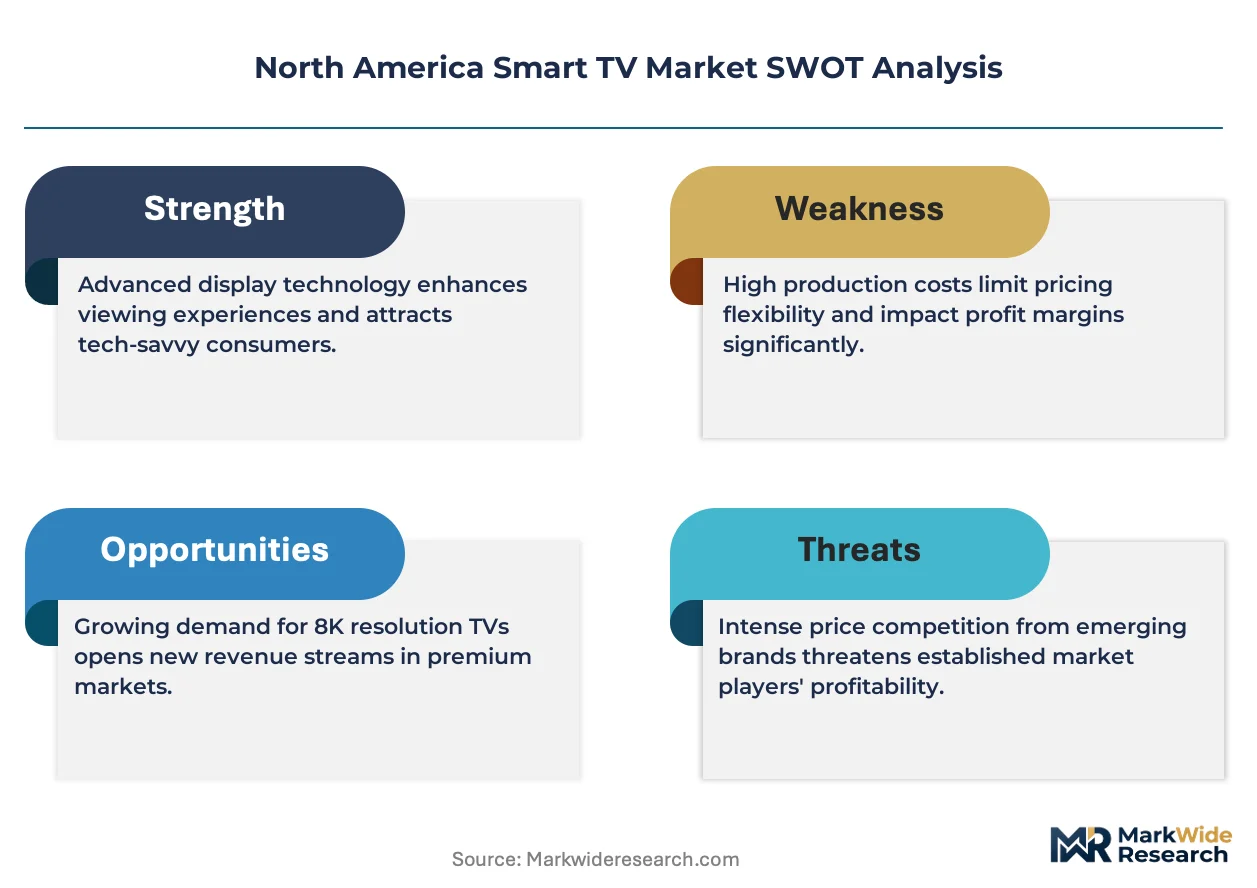
- Panel Cost Volatility:LCD substrate and semiconductor input prices fluctuate with foundry capacity constraints, squeezing margin predictability for LED backlighting tiers.
- Supply Concentration Risk:Display driver IC fabrication concentrates in Taiwan and South Korea, creating geographic vulnerability for North American assembly operations.
- HDMI Specification Fragmentation:Advancing port standards force premature obsolescence of otherwise functional displays, irritating commercial buyers with compressed amortization schedules.
Strategic Opportunities
- Gaming Panel Expansion:Variable refresh rate technology penetration in Ontario and Texas households opens premium pricing tiers for 120Hz and 144Hz configurations.
- Energy Star Certification Tailwinds:EPA efficiency thresholds directly influence consumer purchasing incentives and retailer stocking decisions across both countries.
- Smart Home Convergence:Integration between display operating systems and voice-controlled home automation platforms creates stickier ecosystem lock-in.
Industry Challenges
- Firmware Development Talent Scarcity:Embedded Linux and Android TV optimization expertise concentrates among a limited pool of specialists, slowing feature rollouts.
- Certification Timeline Compression:Industry Canada equipment authorization and FCC electromagnetic emissions testing create sequential bottlenecks for simultaneous US-Canada launches.
- Legacy Broadcast Integration Complexity:ATSC 3.0 NextGen TV deployment requires backward compatibility engineering that diverts resources from streaming-first architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart TV Market |
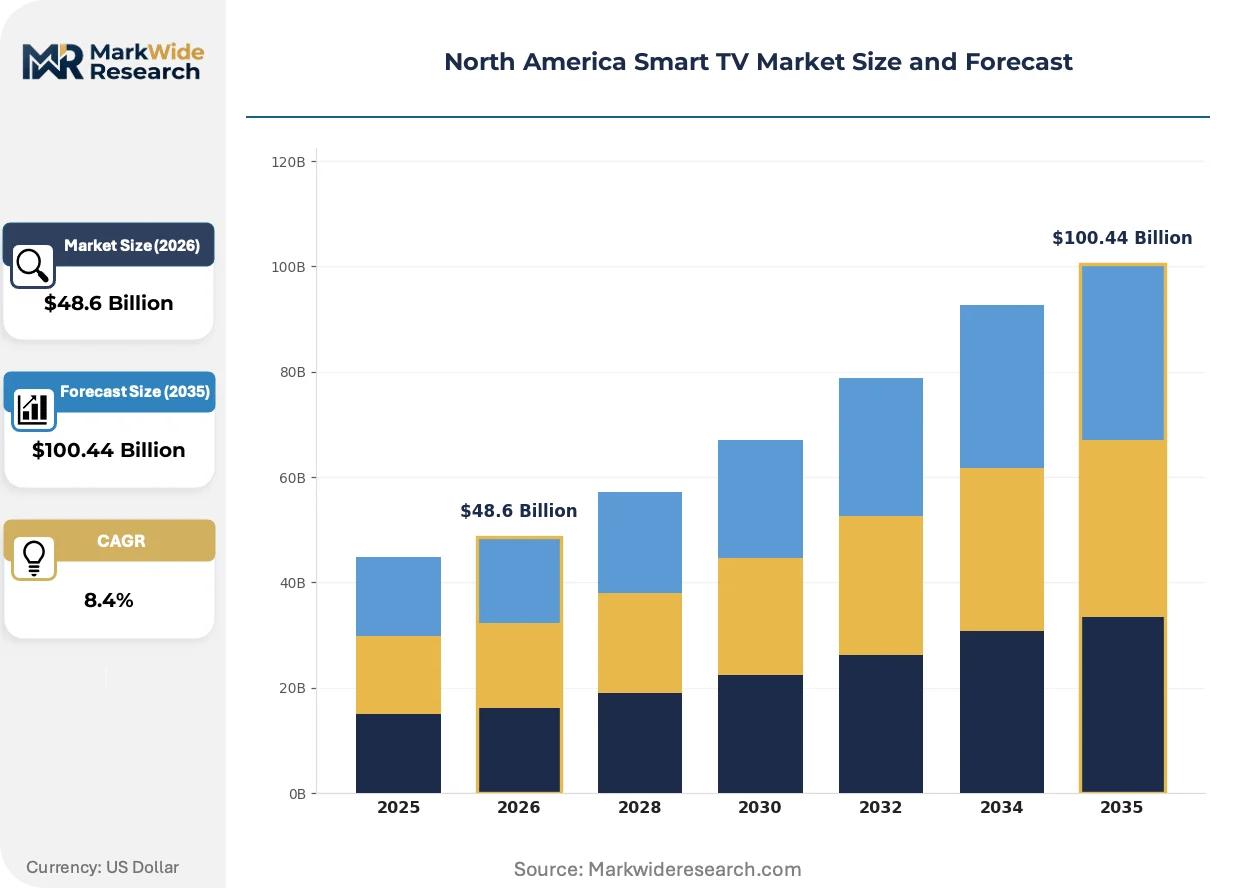
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $100.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, NanoCell Connectivity: Wi-Fi, Ethernet, Bluetooth, HDMI End User: Households, Enterprises, Educational Institutions, Hotels Application: Streaming, Gaming, Sports, Home Theatre |
| Companies Covered | TCL Corporation, Hisense Group, Samsung Electronics Co., Ltd., Sharp Corporation, Panasonic Corporation, LG Electronics Inc., Vizio Inc., Philips, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart TV Market Strategic Shifts & Innovations
Display technology evolution and regulatory energy mandates are actively restructuring competitive positioning across the North American Smart TV landscape, with particular pressure on component sourcing and software architecture decisions.
Mini-LED backlighting is electrifying premium tier competition by delivering localized dimming performance approaching OLED contrast ratios at substantially lower panel costs. Hospitality and corporate buyers in Texas and California are specifying these configurations for high-ambient-light installations. The technology is electrifying price-performance repositioning across what had been rigid premium-mid-economy tier boundaries.
Energy Star certification thresholds issued by the EPA are tightening standby power and active mode efficiency requirements for displays sold in the United States. Retailers including Best Buy and Costco use these certifications as gating criteria for shelf placement, filtering manufacturer participation. Canadian markets follow parallel Natural Resources Canada guidelines, creating harmonized but stringent efficiency expectations across the integrated North American supply chain.
Commercial procurement of hospitality-grade smart displays is consolidating through direct manufacturer relationships rather than traditional AV integrator channels. Hotel chains in Ontario and Florida are negotiating fleet-wide operating system customization and centralized content management. This disintermediation concentrates volume with fewer suppliers while demanding dedicated enterprise support infrastructure that consumer-focused manufacturers struggle to provision.
North America Smart TV Market Segmentation
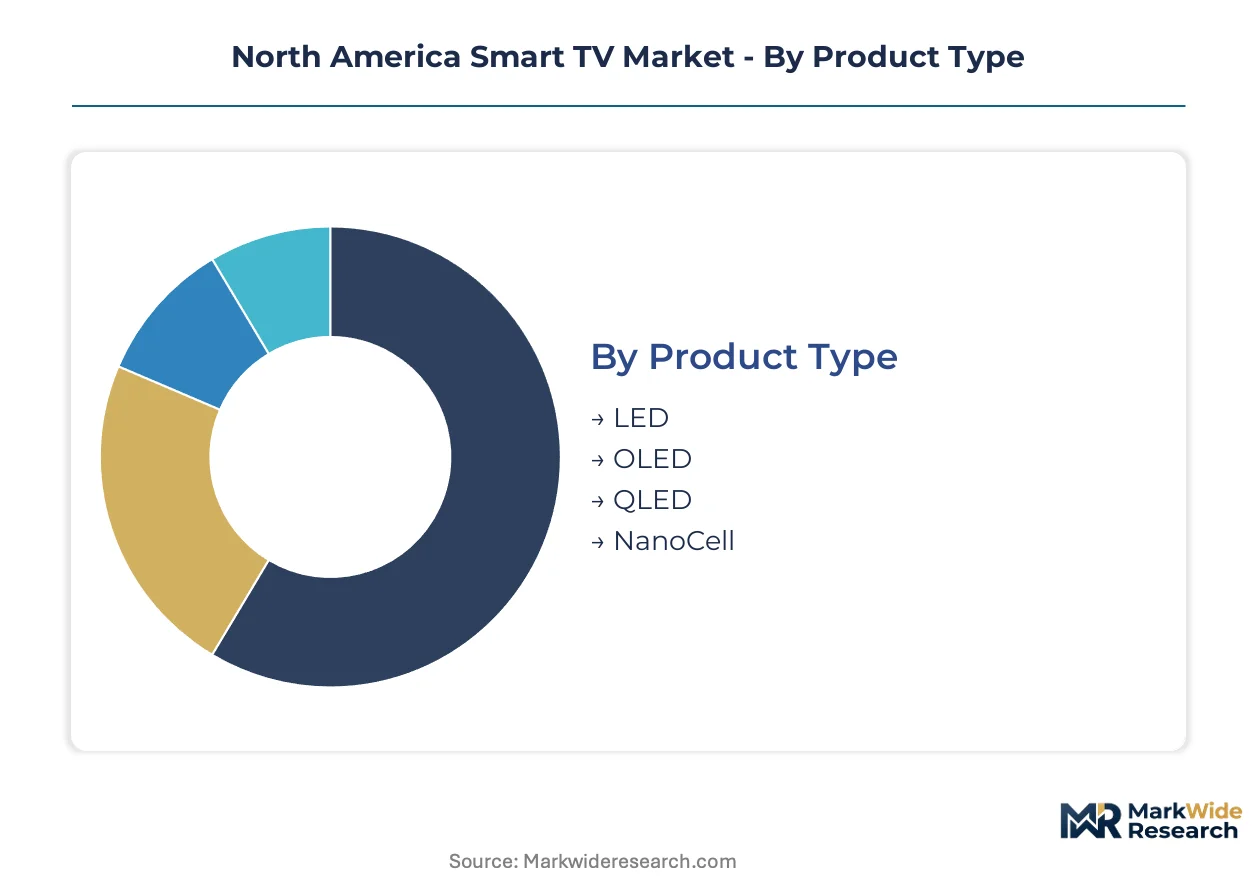
Smart TV purchasing decisions in North America diverge sharply across display technology, network architecture, and use-case intensity. Procurement criteria for hospitality fleets in Texas differ fundamentally from household gaming setups in Ontario or educational deployments across California school districts.
Product Type:
Resolution and contrast performance anchor household willingness-to-pay, while commercial buyers prioritize panel durability and content management compatibility.
- LED:Edge-lit and full-array backlighting configurations dominate unit economics across mid-tier household installations. California and Texas households concentrate volume here where broadband penetration supports streaming but OLED premiums face resistance.
- OLED:Self-emissive pixel architecture delivers infinite contrast ratios through organic compound layers. Home theatre applications in Ontario and premium hospitality suites in Florida absorb disproportionate margin pools despite higher panel costs.
- QLED:Quantum dot film deposition expands color volume without burn-in risk.
- NanoCell:IPS-derived liquid crystal filtering improves off-axis color accuracy for multi-viewer living rooms.
Volume sits with LED; growth tilts toward OLED as manufacturing scale compresses premium pricing.
Connectivity:
Network topology choices reflect installation environment constraints and latency sensitivity for interactive applications.
- Wi-Fi:Dual-band and Wi-Fi 6E implementations enable cord-free placement flexibility. Households across broadband-saturated Texas and California metro areas drive specification upgrades as mesh network adoption accelerates.
- Ethernet:Gigabit wired connections eliminate contention in high-density hospitality and enterprise deployments. Hotel chains in Ontario mandate RJ45 ports for centralized property management system integration.
- Bluetooth:Peripheral pairing for soundbars and gaming controllers.
- HDMI:2.1 specification ports enable 4K/120Hz signal passthrough from next-generation consoles.
Wi-Fi captures household volume; Ethernet climbs fastest in commercial replacement cycles.
End User:
Procurement authority and amortization horizons reshape operating system requirements and support infrastructure demands.
- Households:Individual purchasing decisions prioritize streaming application breadth and voice assistant compatibility. California and Texas zip codes with fiber deployment show strongest 4K and 8K adoption intensity.
- Hotels:Fleet-scale negotiations demand custom launcher interfaces and remote management APIs. Chains across Florida and Ontario are disintermediating traditional AV integrators for direct manufacturer relationships.
- Enterprises:Corporate lobby and conferencing applications require calendar integration and wireless casting protocols.
- Educational Institutions:K-12 and university procurement emphasizes durability warranties and classroom management software interoperability.
Households anchor volume; hotels are gaining share fastest through compressed replacement cycles.
Application:
Content consumption patterns dictate refresh rate, input lag, and HDR processing requirements.
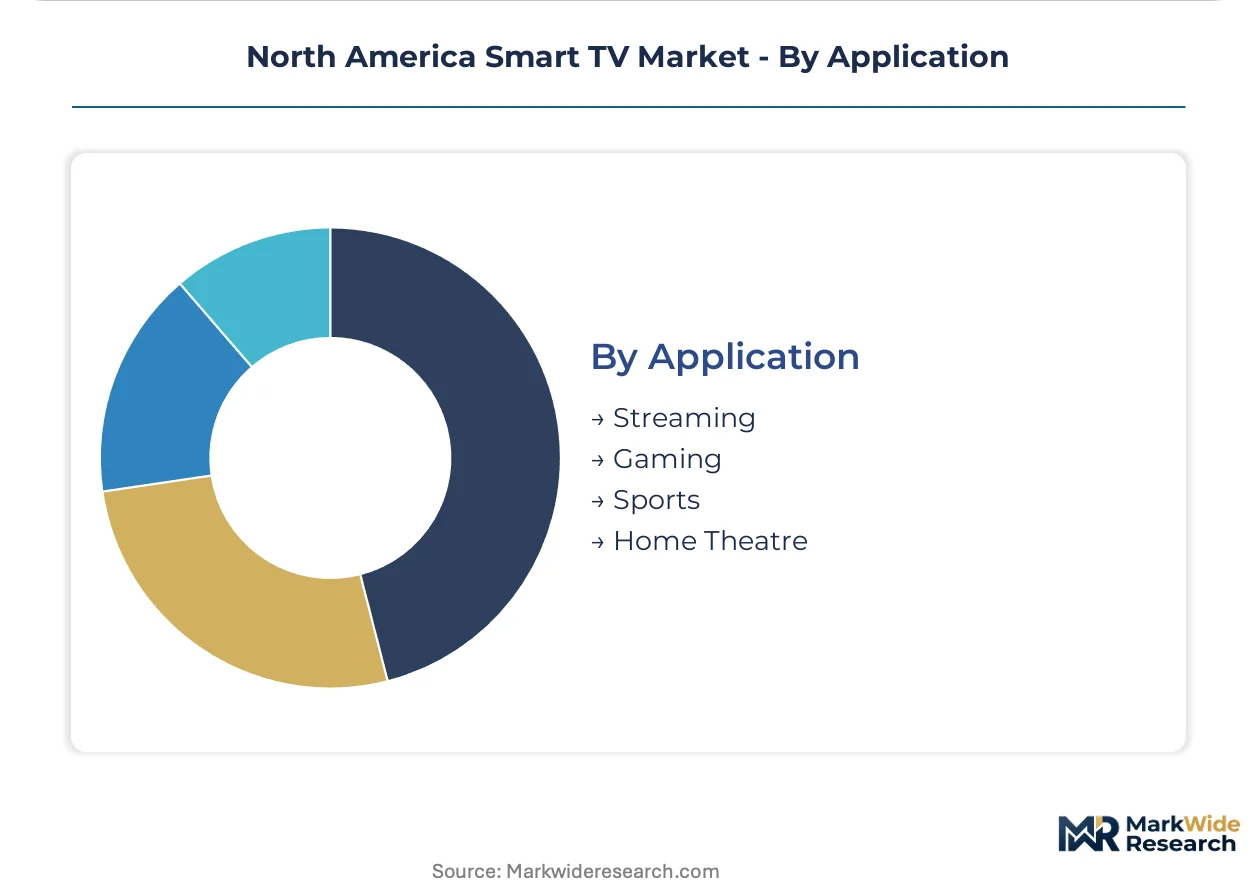
- Streaming:On-demand video consumption through embedded applications represents the baseline use case. Netflix, Disney+, and Max certification requirements influence SoC selection across all price tiers.
- Gaming:Variable refresh rate technology and auto low-latency mode command premium positioning. Texas and Ontario households with console and PC gaming penetration are driving 120Hz and 144Hz panel specifications.
- Sports:Motion handling algorithms and anti-reflection coatings address daytime viewing.
- Home Theatre:Dark-room optimization and Dolby Vision IQ processing target cinephile segments.
Streaming commands installed base; gaming shows steepest expansion trajectory as console cycle peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maquiladora zones along the US-Mexico border concentrate television assembly operations, drawing component flows from Asian foundries and finished goods distribution into US retail channels.
United States
FCC digital television transition mandates and EPA Energy Star certification thresholds reshape procurement criteria across consumer and commercial installations. California, Texas, and Florida absorb disproportionate volume where broadband infrastructure supports 4K and 8K streaming adoption. Hospitality chains in Florida and Texas accelerate fleet-wide replacements, compressing replacement cycles toward internet-connected screens with embedded content management.
Canada
Industry Canada equipment authorization requirements and Natural Resources Canada efficiency guidelines create harmonized but stringent standards across the integrated North American supply chain. Ontario concentrates household demand where fiber deployment enables premium panel adoption. Hotel chains across Ontario negotiate direct manufacturer relationships for fleet-scale operating system customization and centralized content management.
Mexico
Maquiladora assembly operations leverage duty-free component import regimes and proximity to US distribution networks. Baja California and Chihuahua host television manufacturing clusters serving North American retail replenishment. Mexican assembly operations capture volume from brands seeking to diversify production geography while maintaining US market access.
North America Smart TV Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing electronics conglomerates commanding premium positioning while volume production concentrates among diversified Asian industrials. The vendor base organizes around three strategic archetypes: vertically integrated display panel producers, brand-licensing operators with outsourced manufacturing, and contract assemblers serving multiple labels. Competitive moves center on quantum dot deposition scale and direct hospitality procurement relationships that disintermediate traditional AV integrators.
Among Korean and Chinese electronics conglomerates, Samsung Electronics Co., Ltd., LG Electronics Inc., and TCL Corporation occupy positions spanning panel production through retail distribution. Samsung exemplifies vertical control over quantum dot inkjet deposition, while LG anchors large-format OLED exclusivity. TCL represents aggressive price-performance positioning in LED backlighting tiers, competing on volume scale rather than premium technology differentiation.
| Leading Market Players |
|---|
| TCL Corporation |
| Hisense Group |
| Samsung Electronics Co., Ltd. |
| Sharp Corporation |
| Panasonic Corporation |
| LG Electronics Inc. |
| Vizio Inc. |
| Philips |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
Mini-LED backlighting diffusion simultaneously compresses manufacturing yields and redistributes cost economics across panel tiers, concentrating margin pressure on legacy LED configurations while elevating foundry demand for precision semiconductor backplanes in Taiwan and South Korea.
Pricing Analysis
Volume concentrates in LED backlighting tiers where aggressive price-performance positioning by Chinese manufacturers compresses margins, while OLED and quantum dot configurations capture disproportionate margin pools through technology differentiation. Price differentiation rests on panel architecture complexity and Energy Star certification tier, with hospitality procurement in Texas and Florida showing lowest sensitivity due to fleet-scale amortization. Cost compression in mid-tier LED segments intensifies because LCD substrate foundry capacity constraints elevate input costs. Household buyers in California broadband markets exhibit highest price sensitivity for sub-65-inch installations.
Supply Chain Analysis
Reverse-logistics flows for hospitality fleet refreshes in Florida and Ontario create secondary refurbishment channels, extending panel lifecycles while diverting volume from primary manufacturing. Component sourcing draws from Taiwan and South Korea for display driver ICs, China for LCD glass substrates, and Mexico for final assembly in maquiladora zones. Single-source vulnerability concentrates in Taiwan-based foundry capacity for advanced node semiconductors. Distribution runs through big-box retail consolidation at Best Buy and Costco, with direct manufacturer relationships displacing traditional AV integrators in commercial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Display driver IC foundry bottlenecks in Taiwan prop pricing resilience across premium tiers, insulating margin pools even as LED backlighting segments face cost compression.
For Market Incumbents: Anticipate hospitality procurement disintermediation by building dedicated enterprise support infrastructure for fleet-scale operating system customization. Defend margin position through captive quantum dot inkjet deposition capacity. Counter TCL price aggression with certification-led differentiation at EPA Energy Star thresholds. For New Entrants and Emerging Players: AV integrator partnerships offer immediate channel access without direct manufacturer infrastructure investments. White-space concentrates in gaming-oriented 120Hz and 144Hz panel specifications across Texas and Ontario households. Target educational procurement in California school districts with durability warranty bundling and classroom management software interoperability. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by Korean and Chinese electronics conglomerates seeking North American distribution scale. Long-term viability favors vertically integrated panel producers with quantum dot or OLED exclusivity rather than brand-licensing operators. Monitor HDMI specification release cadence as inflection indicator for premature obsolescence risk and compressed replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum Dot Deposition Scale-Up | Samsung's inkjet control widens color gamut without OLED burn-in risk. |
| Hospitality Fleet Direct Relationships | Hotel chains in Ontario bypass integrators for customized content management. |
| Energy Star Certification Investment | EPA thresholds gate Best Buy and Costco shelf placement decisions. |
| Gaming Panel Specification Expansion | Variable refresh rate technology captures Texas console upgrade cycles. |
| Maquiladora Assembly Footprint | Mexican duty-free zones diversify production geography for US access. |
Research Approach
Multi-period observation of panel shipment volumes, broadband penetration rates, and hospitality procurement cycles anchored the trend analysis, supplemented by interviews with display technology procurement directors, hotel chain AV managers, retail category buyers, semiconductor foundry planners, and regulatory compliance officers. Secondary validation drew from FCC equipment authorization databases, EPA Energy Star certified product listings, Industry Canada technical standards, SEC 10-K filings from publicly traded electronics manufacturers, and customs import records for display panel components. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Input-output matrices mapped display technology adoption rates against connectivity specification upgrades and end-use intensity patterns across the projection horizon. Segmentation dimensions modeled include panel architecture, network topology, procurement authority, and application intensity. CAGRs were derived through regression analysis of historical replacement cycles and forward projection of regulatory mandate impacts. Forecast inputs incorporated foundry capacity utilization rates and ATSC 3.0 deployment timelines.
Caveats apply where semiconductor foundry capacity constraints, tariff regime shifts, or ATSC 3.0 backward compatibility engineering failures could materially shift the outlook. Practitioners should monitor Taiwan foundry utilization rates and HDMI specification release announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
4K Television Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Smart Connected Speaker Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Ultraman Peripheral Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Vape Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Ereader and Enotetaking Devices Market