
 Asia Pacific E-Commerce Market | 2026-2036
Asia Pacific E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific E-Commerce Market Outlook
Multi-source marketplace aggregation is repositioning how inventory reaches end buyers across the Asia Pacific E-Commerce Market. Alibaba Group Holding Ltd. leverages its Cainiao logistics arm to control fulfillment density in tier-three Chinese cities. JD.com sustains same-day delivery promises through in-house warehousing and captive last-mile fleets. SEA Group (Shopee) competes across Southeast Asia by subsidizing cross-border shipping from Chinese manufacturing clusters.
Asia Pacific E-Commerce encompasses digitally mediated transactions for physical goods and services, executed through web-based storefronts or native mobile applications with integrated payment rails, inventory management APIs, and algorithmic recommendation engines. Its primary commercial purpose is to collapse geographic distance between dispersed consumer populations and centralized production bases, replacing traditional wholesale intermediation with direct-to-consumer data loops. Electronics commands the largest transaction volume within product type segmentation, while beauty products generates the highest per-unit margin due to repeat purchase frequency and influencer-driven discovery mechanics. E-wallet penetration within payment method segmentation outpaces credit card adoption across Indonesia, Philippines, and Vietnam, where banking infrastructure remains sparse and mobile-first financial services from telecommunication providers fill the gap.
India's Reserve Bank of India governs payment aggregator licensing and data localization mandates, while China's SAMR enforces anti-monopoly provisions against platform self-preferencing and merchant exclusivity clauses. Japan's METI coordinates cross-border e-commerce facilitation agreements with ASEAN counterparts to harmonize customs clearance and consumer protection standards. Stakeholders must monitor how divergent data sovereignty requirements across these jurisdictions fragment otherwise unified supply chain orchestration.
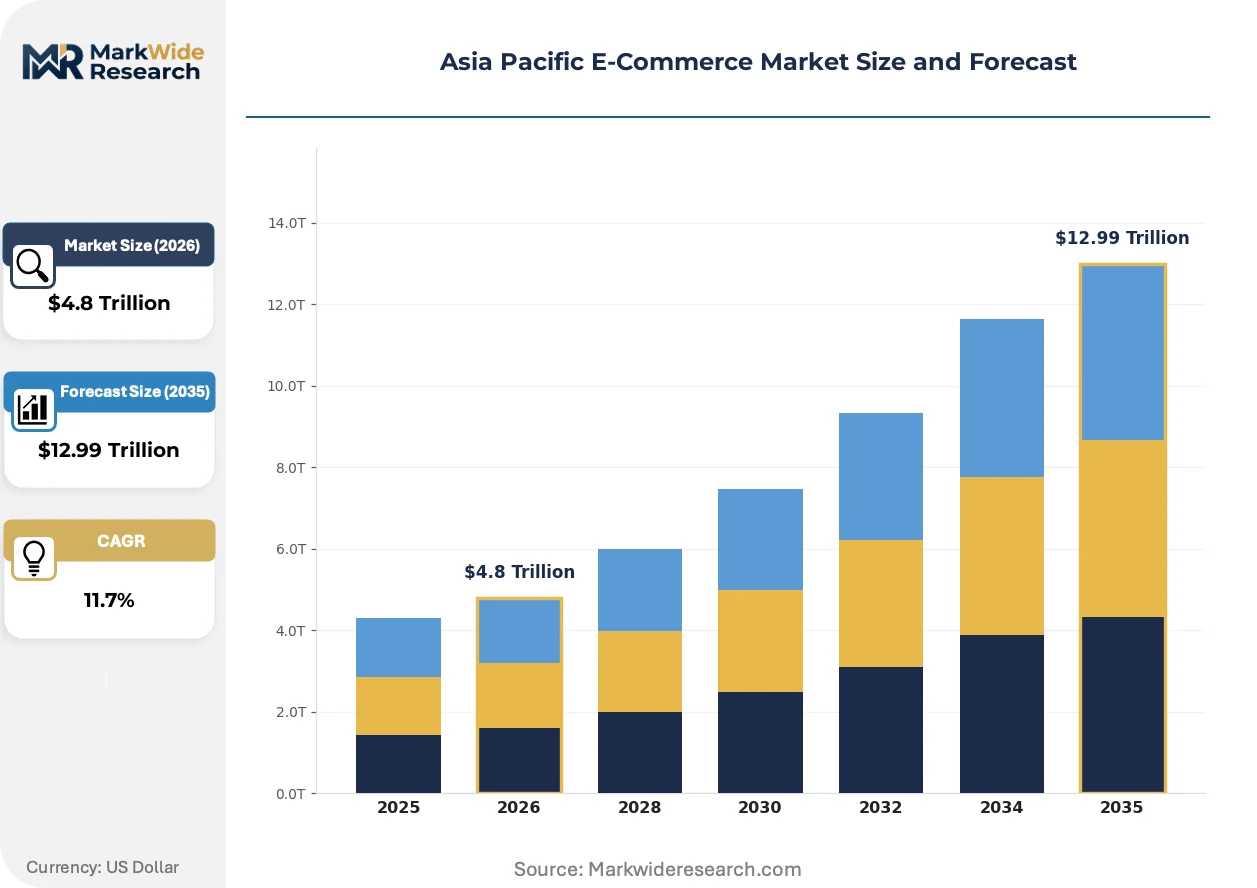
Market Dynamics
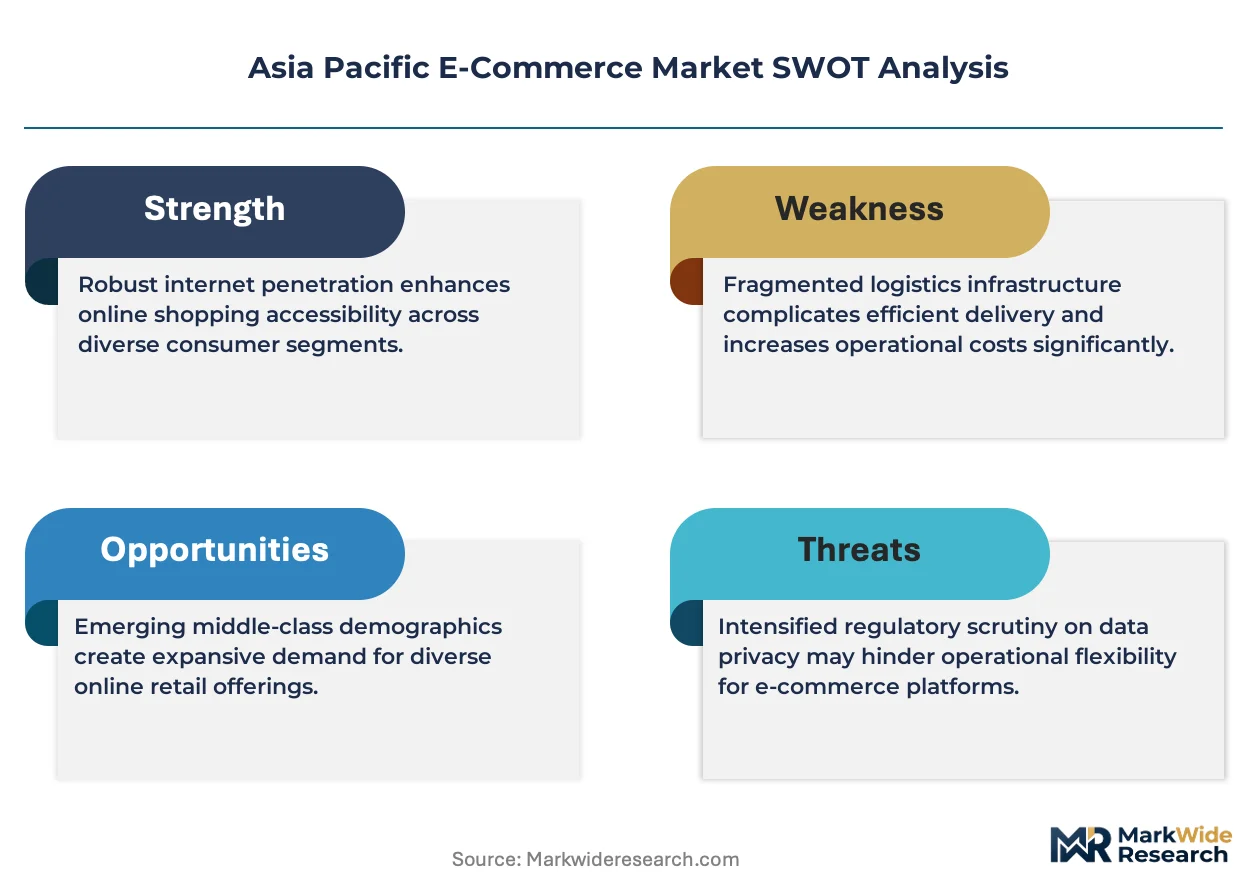
Platform consolidation across Southeast Asia is compressing merchant margins while India's RBI mandates on data localization force infrastructure replication across national borders, fragmenting what were once unified fulfillment networks.
Growth Catalysts
- India's UPI Protocol:Real-time retail payment settlement at zero merchant discount rate eliminates friction in cash-on-delivery conversion, expanding addressable consumer bases beyond credit-card holders.
- Cross-Border Customs Harmonization:ASEAN Single Window protocols reduce clearance dwell times for electronics imports from China into Indonesia, Vietnam, and Thailand, compressing end-to-end delivery windows.
- Live Commerce Integration:Short-form video platforms with embedded checkout are absorbing impulse purchase behavior previously captured by physical retail, particularly in beauty and fast-fashion verticals.
Market Restraints
- Last-Mile Fuel Cost Volatility:Diesel price fluctuations across archipelago logistics corridors in Indonesia directly erode per-unit economics for same-day delivery promises in tier-two cities.
- Merchant Exclusivity Enforcement:China's SAMR anti-monopoly provisions against platform self-preferencing create operational uncertainty for marketplace operators with captive logistics arms.
- Cross-Border Data Localization:Divergent national requirements for consumer data storage fragment supply chain orchestration, forcing redundant infrastructure deployment.
Strategic Opportunities
- Vietnam's Manufacturing-to-Consumer Channels:Direct export storefronts from factory clusters in Bac Ninh and Hai Phong bypass wholesale intermediation, capturing margin previously lost to trading houses.
- Telecommunication-Provider Wallets:GCash in the Philippines and Dana in Indonesia leverage subscriber bases to displace traditional banking for e-commerce settlement, opening underbanked segments.
- Japan-ASEAN Facilitation Agreements:METI-coordinated customs pre-clearance and consumer protection harmonization reduces compliance overhead for Japanese retailers entering Southeast Asian markets.
Industry Challenges
- Inventory Forecasting Talent Scarcity:Demand for data scientists capable of modeling seasonal spikes across fragmented geographies outpaces supply, particularly in Indonesia's outer islands.
- Legacy Warehouse Management System Integration:Older ERP architectures in established Japanese retail chains resist API connectivity with marketplace platforms, delaying omnichannel rollout.
- Cross-Border Return Logistics Complexity:Reverse supply chains for consumer electronics face customs documentation mismatches between China export protocols and India import requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific E-Commerce Market |
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $12.99 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Home Goods, Beauty Products Payment Method: Credit Card, E-Wallet, Bank Transfer, Cash on Delivery Customer Type: Individual Consumers, Businesses, Government, Non-Profit Organizations Sales Channel: Direct Sales, Marketplace, Apps, Social Media |
| Companies Covered | Alibaba Group Holding Ltd., JD.com, SEA Group (Shopee), Lazada Group, Coupang, Rakuten Group Inc., Flipkart Internet Pvt. Ltd., Pinduoduo Inc., Tokopedia PT, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific E-Commerce Market Strategic Shifts
Algorithmic personalization engines and embedded finance products are reconfiguring how discovery and payment occur within single-session mobile experiences, collapsing the traditional funnel into instantaneous transaction loops.
Generative AI-powered product description and visual asset creation is absorbing merchant marketing workflows previously outsourced to creative agencies. Mid-market sellers across Thailand and Malaysia now deploy automated localization tools to generate Bahasa, Thai, and Vietnamese listings from single Mandarin source material. This compression of content production cycles enables SKU proliferation without proportional headcount expansion.
India's RBI payment aggregator licensing framework is tightening capital reserve and data escrow requirements for foreign-owned platforms. The regulation forces non-domestic operators to establish local legal entities and ring-fenced infrastructure, increasing compliance overhead but creating defensive moats for incumbent Indian payment processors. Electronics and high-value beauty categories face the steepest documentation burdens under enhanced due diligence protocols.
Social commerce discovery through influencer-curated storefronts is displacing traditional search-based procurement patterns among cohorts under thirty-five. Live-streaming hosts in Guangdong manufacturing hubs now sell directly to Philippine consumers via embedded checkout, bypassing marketplace listing fees. This behavioral shift concentrates transaction volume during scheduled broadcast windows, creating fulfillment demand spikes that strain warehouse labor scheduling across Shenzhen export corridors.
Asia Pacific E-Commerce Market Segmentation
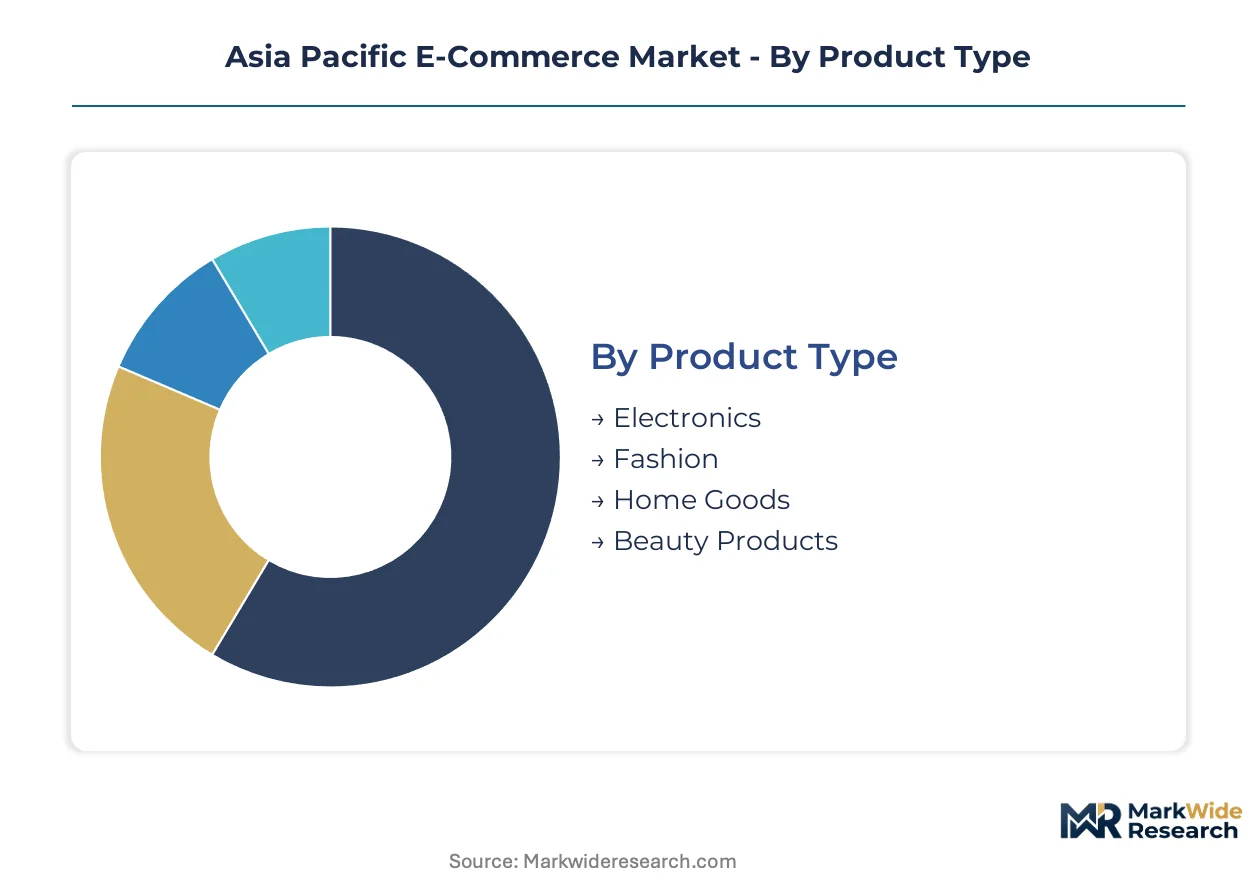
Segmentation reveals how divergent compliance burdens and infrastructure readiness fragment addressable demand across the Asia Pacific E-Commerce Market. Each dimension carries distinct regulatory weight, from RBI payment aggregator licensing to SAMR platform governance.
Product Type:
Certification requirements vary sharply across physical goods categories, with India's BIS mandatory standards and China's GB compliance protocols creating divergent entry barriers.
- Electronics:Smartphones, laptops, and consumer appliances dominate transaction volume. India's BIS registration and China's CCC certification impose multi-month approval timelines. Demand concentrates in Shenzhen-to-Jakarta export corridors, where ASEAN Single Window customs harmonization compresses clearance dwell times.
- Fashion:Apparel and footwear carry lighter regulatory burden but face steep return logistics complexity. Vietnamese manufacturing clusters in Bac Ninh now ship direct-to-consumer, bypassing wholesale intermediation. Live commerce integration through short-form video platforms absorbs impulse purchase behavior previously captured by physical retail.
- Home Goods:Furniture and household appliances require regional safety standard adherence.
- Beauty Products:Skincare and cosmetics generate highest per-unit margin through repeat purchase frequency and influencer-driven discovery mechanics.
Electronics sits at the top of the volume ranking, with beauty products climbing the fastest.
Payment Method:
Cost tier stratification separates premium credit-card infrastructure from mass-market digital wallet penetration across underbanked populations.
- E-Wallet:Mobile-first financial services from telecommunication providers displace traditional banking across Indonesia, Philippines, and Vietnam. GCash and Dana leverage subscriber bases for e-commerce settlement. India's UPI protocol enables real-time retail payment settlement at zero merchant discount rate.
- Credit Card:Concentrated among urban professional cohorts in Singapore, Japan, and South Korea. Higher transaction limits support electronics and cross-border purchases. Banking infrastructure density determines geographic penetration limits.
- Bank Transfer:Preferred for B2B procurement and high-value transactions.
- Cash on Delivery:Persists in tier-three Indian cities and Indonesian outer islands where digital trust remains underdeveloped.
E-wallet commands the broadest addressable base, with credit card yielding the highest average transaction value.
Customer Type:
Application maturity separates individual consumer spontaneity from institutional procurement rigor and compliance documentation.
- Individual Consumers:Mobile-native buyers across Southeast Asia drive platform traffic through algorithmic recommendation engines. Social commerce discovery through influencer-curated storefronts displaces search-based procurement among cohorts under thirty-five.
- Businesses:B2B procurement platforms integrate inventory management APIs with enterprise ERP systems. Japanese retail chains face legacy warehouse management system integration delays.
- Government:Public sector e-procurement mandates create dedicated marketplace segments.
- Non-Profit Organizations:Specialized donation and relief supply channels operate under distinct tax documentation requirements.
Individual consumers anchor transaction volume, with businesses expanding most quickly as ERP integration matures.
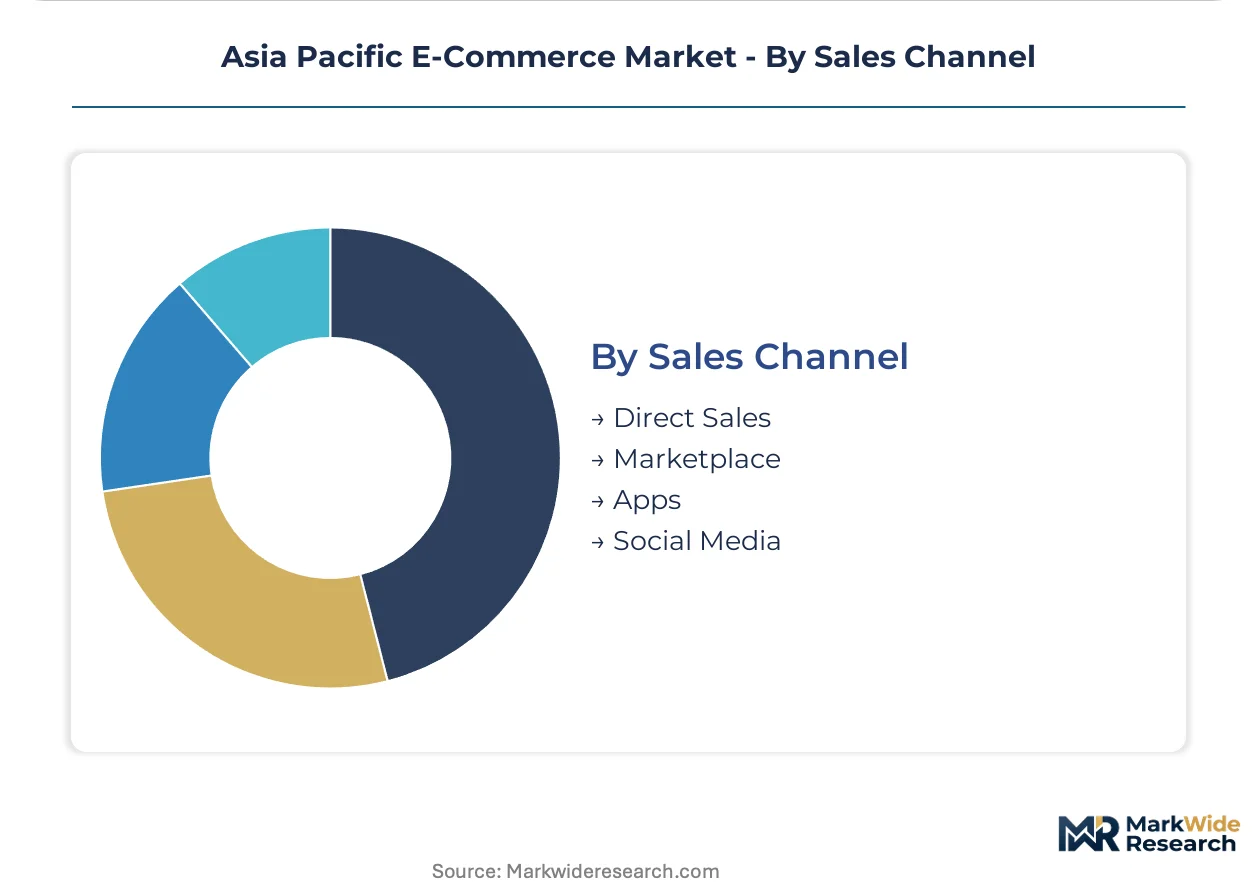
Sales Channel:
Supply concentration distinguishes captive fulfillment networks from aggregator-dependent merchant models.
- Marketplace:Third-party platforms aggregate inventory from dispersed merchants. Alibaba's Cainiao logistics arm controls fulfillment density in tier-three Chinese cities. JD.com sustains same-day delivery through in-house warehousing.
- Direct Sales:Brand-owned storefronts capture margin previously lost to platform fees. Vietnam's factory clusters in Hai Phong bypass trading houses entirely.
- Apps:Native mobile applications with embedded checkout dominate session time.
- Social Media:Live-streaming hosts in Guangdong sell directly to Philippine consumers via embedded checkout, bypassing marketplace listing fees.
Marketplace retains volume leadership, with social media gaining share fastest through scheduled broadcast windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's export manufacturing clusters anchor cross-border fulfillment corridors into Southeast Asia, while regulatory divergence across national jurisdictions fragments unified supply chain orchestration.
China
Guangdong province's factory-to-consumer live commerce channels absorb impulse purchase behavior through embedded checkout mechanics. SAMR anti-monopoly provisions against platform self-preferencing create operational uncertainty for marketplace operators with captive logistics arms. Shenzhen export corridors concentrate electronics volume bound for Jakarta and Manila through ASEAN Single Window customs harmonization.
India
UPI protocol penetration eliminates friction in cash-on-delivery conversion, expanding addressable consumer bases beyond credit-card holders into tier-three cities. RBI payment aggregator licensing mandates data localization and capital reserve requirements for foreign-owned platforms. Bangalore's technology corridor hosts merchant-facing inventory management API providers serving domestic marketplace integration.
Indonesia
Telecommunication-provider wallets displace traditional banking across underbanked populations in the archipelago's outer islands. National data sovereignty requirements force redundant infrastructure deployment for cross-border supply chain orchestration. Surabaya's logistics corridors face diesel price volatility eroding per-unit economics for same-day delivery promises in tier-two cities.
Japan
Legacy warehouse management systems in established retail chains resist API connectivity with marketplace platforms, delaying omnichannel rollout. METI coordinates cross-border facilitation agreements with ASEAN counterparts to harmonize customs clearance and consumer protection standards. Tokyo's metropolitan fulfillment networks sustain premium-tier delivery expectations through dense warehousing infrastructure.
Vietnam
Manufacturing-to-consumer export channels from Bac Ninh factory clusters bypass wholesale intermediation, capturing margin previously lost to trading houses. Cross-border customs harmonization reduces clearance dwell times for electronics imports through ASEAN Single Window protocols. Hai Phong's port logistics corridors compress end-to-end delivery windows for direct-to-consumer storefronts.
Asia Pacific E-Commerce Market Competitive Environment
Global majors compete with regional champions across fulfillment network density and payment integration depth. Platform consolidation compresses merchant margins while captive logistics arms differentiate delivery promise reliability. Three archetypes dominate: integrated ecosystem operators with in-house warehousing, marketplace aggregators dependent on third-party fulfillment, and social commerce platforms leveraging influencer-curated discovery. Competitive moves concentrate on cross-border shipping subsidization and algorithmic personalization engine deployment.
Within the integrated ecosystem tier, Alibaba Group Holding Ltd. and JD.com represent contrasting fulfillment philosophies. SEA Group (Shopee) occupies a position exemplifying regional marketplace aggregation with cross-border subsidization mechanics. These three entities anchor the competitive structure across divergent national regulatory environments.
| Leading Market Players |
|---|
| Alibaba Group Holding Ltd. |
| JD.com |
| SEA Group (Shopee) |
| Lazada Group |
| Coupang |
| Rakuten Group Inc. |
| Flipkart Internet Pvt. Ltd. |
| Pinduoduo Inc. |
| Tokopedia PT |
| Others |
Value Chain & Pricing Dynamics
Captive logistics integration anchors both fulfillment density and pricing power across the Asia Pacific E-Commerce Market. Alibaba's Cainiao arm and JD.com's in-house warehousing create cost advantages that compress third-party merchant margins while sustaining same-day delivery premiums in tier-three Chinese cities and Southeast Asian corridors.
Pricing Analysis
Diesel cost pass-through from Surabaya's archipelago logistics corridors directly erodes per-unit economics for same-day delivery promises in Indonesian tier-two cities. Three-tier pricing structure across premium, standard, and economy delivery windows separates urban professional cohorts from mass-market digital wallet users. Cost compression in cross-border subsidization is intensifying because SEA Group's Shopee absorbs shipping losses to capture market share. Individual consumers in Philippine and Vietnamese outer islands exhibit highest price sensitivity, while Japanese metropolitan buyers accept premium tiers for dense warehousing reliability.
Supply Chain Analysis
Workforce availability constraints in Bac Ninh and Hai Phong factory clusters limit direct-to-consumer export capacity from Vietnamese manufacturing hubs. Supply concentrates in Guangdong electronics corridors, Jakarta's import distribution nodes, and Bangalore's technology service corridors. Component dependencies span Shenzhen semiconductor assemblies, Indonesian packaging materials, and Indian software API layers. Single-source vulnerability runs through ASEAN Single Window customs harmonization protocols. Distribution runs through marketplace aggregators with captive logistics arms, direct-export storefronts from factory clusters, and telecommunication-provider wallet settlement rails.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific E-Commerce Market operates as a regulatory compounder where India's RBI payment aggregator licensing and China's SAMR anti-monopoly provisions continuously reshape competitive boundaries. These mandates force infrastructure replication that fragments unified fulfillment networks while creating defensive moats for compliant operators.
For Market Incumbents: Acquire captive last-mile fleet density in tier-three cities to offset diesel volatility erosion in Indonesian archipelago corridors. Consolidate cross-border customs pre-clearance capabilities before Japan-ASEAN facilitation agreements mature. Platform self-preferencing scrutiny from SAMR threatens margin structures dependent on captive logistics subsidization.
For New Entrants and Emerging Players: Telecommunication-provider wallet partnerships unlock underbanked segments in Philippine and Indonesian outer islands where GCash and Dana subscriber bases displace traditional banking. Target Vietnam's manufacturing-to-consumer export channels from Bac Ninh clusters where direct storefronts bypass trading house intermediation entirely. Embedded checkout integration with short-form video platforms captures impulse purchase behavior among cohorts under thirty-five.
For Investors and Strategic Acquirers: Roll-up economics work for regional marketplace aggregators because platform consolidation compresses merchant margins while algorithmic personalization engines create switching costs. Five-to-ten year viability hinges on data localization compliance infrastructure rather than pure transaction volume scale. Monitor RBI capital reserve requirement enforcement as inflection indicator for foreign-owned platform exit pressures.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Shipping Subsidization | SEA Group absorbs losses to lock in Southeast Asian market share against Alibaba's Cainiao density. |
| Captive Logistics Fleet Expansion | JD.com's in-house warehousing sustains same-day delivery promises that third-party merchants cannot match. |
| Telecommunication Wallet Integration | GCash and Dana leverage subscriber bases to displace traditional banking in underbanked Philippine and Indonesian corridors. |
| Live Commerce Platform Development | Guangdong factory hosts sell directly to Philippine consumers via embedded checkout, bypassing marketplace listing fees. |
| Data Localization Infrastructure Deployment | RBI mandates force foreign-owned platforms to establish ring-fenced legal entities and redundant storage architecture. |
Study Parameters
Direct dialogue with marketplace operations executives, logistics corridor managers, payment aggregator compliance officers, and telecommunication wallet product leads grounded qualitative findings in operational reality. Secondary validation drew from RBI payment aggregator licensing circulars, SAMR anti-monopoly enforcement disclosures, ASEAN Single Window customs protocols, and METI cross-border facilitation agreements. Bottom-up merchant volume modeling and top-down regional GDP elasticity approaches were triangulated against customs trade flow data.
Bottom-up segmentation analysis modeled transaction volume and value across product type, payment method, customer archetype, and sales channel dimensions throughout the forecast period. Electronics certification timelines, e-wallet penetration curves, and social commerce adoption rates informed CAGR derivation. Cross-border shipping subsidization burn rates and diesel price elasticity for archipelago logistics corridors served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RBI data localization enforcement intensity and ASEAN customs harmonization protocol expansion. Assumptions reflect current regulatory trajectories and infrastructure deployment schedules. Material deviation in SAMR platform governance rulings or UPI protocol adoption velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
United States E-Commerce Market