
 China Ecommerce Logistics Market | 2026-2036
China Ecommerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
China Ecommerce Logistics Market Outlook
Merchant sourcing of fulfillment capacity is rebalancing from pure outsourced models toward hybrid captive-third-party structures. JD Logistics anchors its competitive position through backward integration into warehouse robotics and autonomous vehicle fleets. SF Express leverages premium time-definite express services to sustain margin density in coastal tier-one corridors. Cainiao Network competes through data-layer coordination across fragmented last-mile carrier pools.
China ecommerce logistics encompasses the integrated movement, storage, and order-fulfillment of goods sold through digital commerce channels, operating across temperature bands from ambient to controlled cold-chain specifications. The sector orchestrates parcel sortation at throughput velocities exceeding 100,000 items per hour in mega-hubs while maintaining pharmaceutical distribution compliance at 2-8°C. Last mile delivery occupies the largest value pool given urban density and consumer same-day expectations, though drone delivery represents the fastest-expanding technology segment as regulatory airspace permissions widen. Warehousing margins concentrate in automated systems deployment where robotic pick-to-light configurations reduce unit labor costs.
SAMR enforces platform-merchant contractual fairness rules that reshape third-party logistics pricing transparency, while MIIT's 5G-plus-industrial internet standards mandate real-time cargo visibility for network license eligibility. NMPA's Good Supply Practice for pharmaceuticals imposes temperature-validation documentation across all distribution handoffs, raising compliance barriers for non-specialized carriers. Stakeholders must monitor evolving GB national standard revisions for autonomous delivery vehicle road access as municipal pilot programs multiply.
Market Dynamics
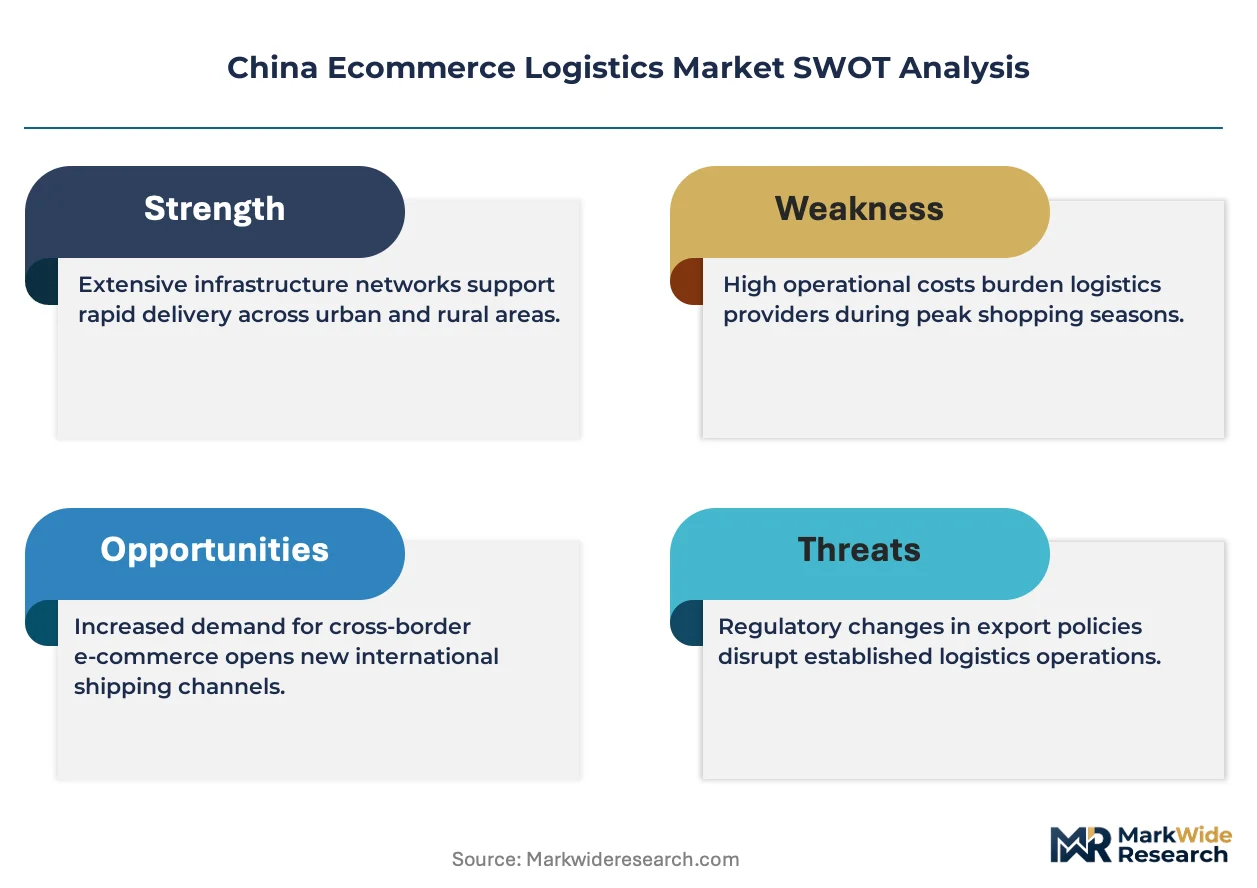
Merchant fulfillment sourcing is rebalancing from pure outsourced models toward hybrid captive-third-party structures as warehouse robotics and autonomous vehicle fleets rewrite cost structures across the Yangtze River Delta corridor.
Growth Catalysts
- MIIT's 5G-plus-industrial internet mandates:Real-time cargo visibility requirements for network license eligibility force platform investments in IoT infrastructure across mega-hubs.
- Fresh produce cold-chain expansion:Temperature-controlled fulfillment anchors adoption growth as urban consumers demand same-day delivery of perishables in Shanghai, Jiangsu, and Zhejiang.
- Pharmaceutical distribution compliance:NMPA's Good Supply Practice rules impose 2-8°C validation documentation across all handoffs, raising barriers for non-specialized carriers.
Market Restraints
- Autonomous vehicle road access uncertainty:Evolving GB national standard revisions for municipal pilot programs create deployment timeline risk for last-mile robot fleets.
- Warehouse robotics capex concentration:Automated pick-to-light configurations require substantial upfront investment, favoring scaled operators over regional carriers.
- Platform-merchant contractual friction:SAMR's fairness enforcement rules reshape third-party logistics pricing transparency, compressing margin flexibility.
Strategic Opportunities
- Drone delivery airspace permissions:Regulatory widening of low-altitude flight corridors creates fastest-expanding technology segment for urban parcel distribution.
- Dual carbon goals alignment:Electric vehicle fleet mandates and renewable warehouse energy standards unlock green financing for logistics infrastructure.
- Cross-border e-commerce corridors:Bonded zone integration with Southeast Asian markets enables temperature-controlled pharmaceutical export channels.
Industry Challenges
- Robotics technician scarcity:Automated sortation systems exceeding 100,000 items per hour require specialized maintenance skills concentrated in coastal tier-one cities.
- Temperature-validation audit complexity:Pharmaceutical handoff documentation across fragmented last-mile carrier pools creates compliance verification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Ecommerce Logistics Market |
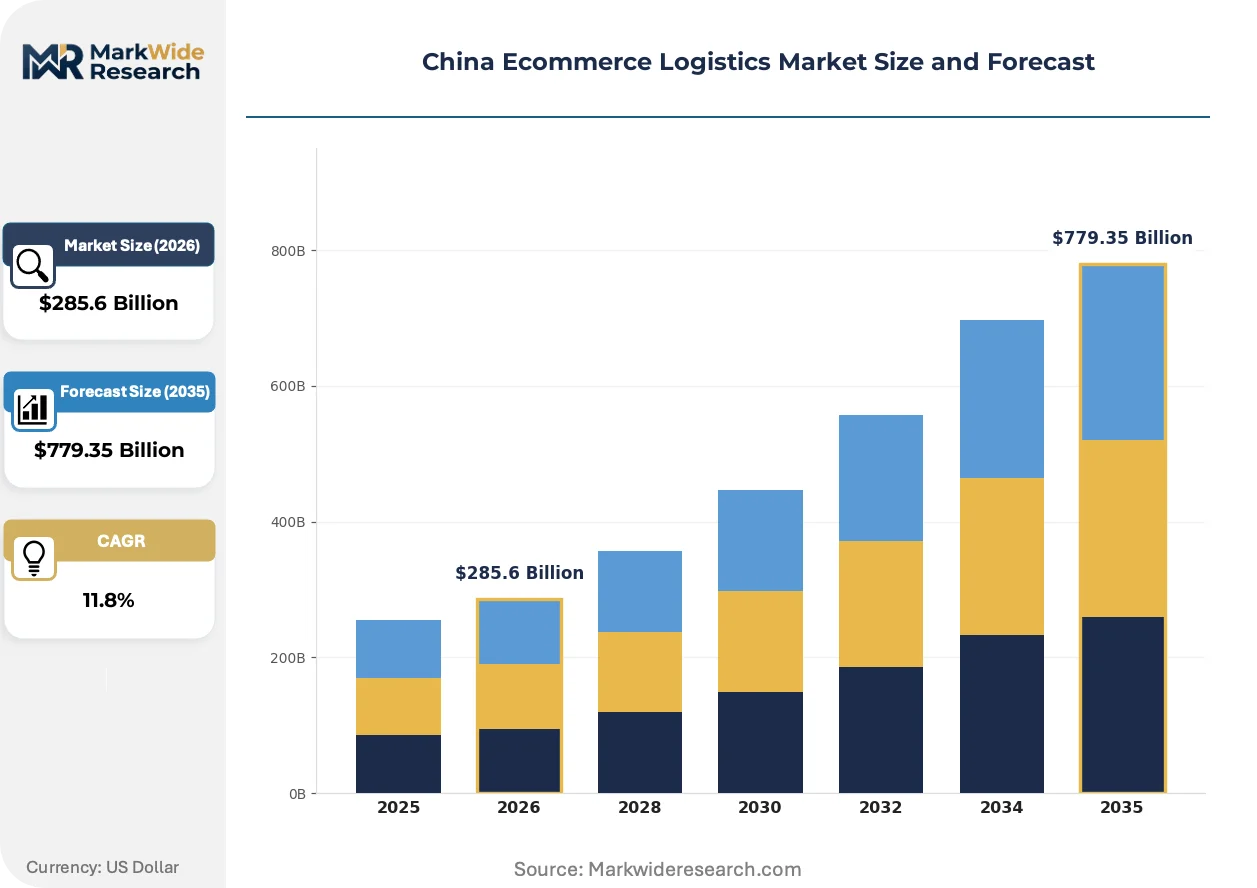
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $779.35 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Warehousing, Transportation, Fulfillment Customer Type: B2C, B2B, C2C, Direct-to-Consumer Technology: Automated Systems, Tracking Solutions, Inventory Management, Drone Delivery Distribution Channel: Online Platforms, Mobile Apps, Social Media, Third-Party Marketplaces |
| Companies Covered | SF Express, JD Logistics, Cainiao Network, ZTO Express, YTO Express, Yunda Express, STO Express, Best Inc., J&T Express, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Ecommerce Logistics Market Strategic Shifts
Parcel sortation velocity thresholds and temperature-band compliance requirements are simultaneously escalating as merchants demand ambient-to-frozen flexibility from single fulfillment partners.
Autonomous delivery vehicle fleets are rewriting last-mile economics in dense urban corridors. Municipal pilot programs in Shanghai and Hangzhou are expanding road access permissions for robotic couriers operating at speeds up to 40 km/h. The technology is compressing labor cost exposure in same-day delivery while creating new infrastructure requirements for charging and maintenance depots.
NMPA's pharmaceutical distribution rule tightening is mandating end-to-end cold-chain documentation. Warehouse operators must deploy continuous temperature monitoring with blockchain-verified handoff records to maintain carrier eligibility. Fresh produce and vaccine logistics segments face the steepest compliance investment requirements.
Merchant fulfillment contracts are unbundling warehousing from delivery to enable multi-carrier rate optimization. Platform sellers in the Yangtze River Delta are segmenting inventory across captive and third-party facilities based on product velocity and temperature requirements. This procurement fragmentation is most visible in pharmaceutical and premium perishable categories where compliance certification drives carrier selection.
China Ecommerce Logistics Market Segmentation
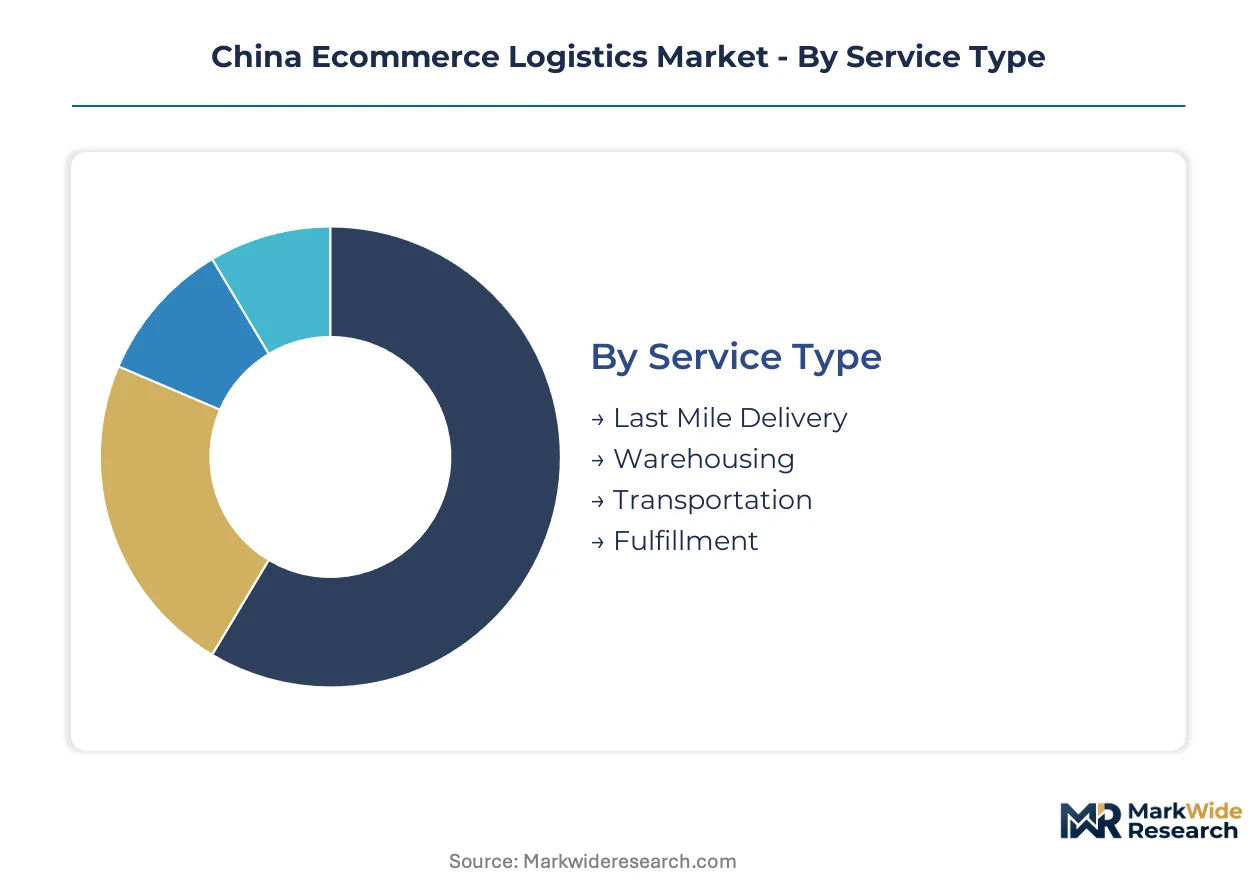
China ecommerce logistics operators segment their service portfolios around temperature compliance, delivery velocity, and merchant scale. Each segmentation axis reveals distinct margin structures and capital intensity requirements across the Yangtze River Delta corridor.
Service Type:
Merchant scale and product temperature sensitivity differentiate procurement patterns across service categories.
- Last Mile Delivery:Urban parcel distribution operates through electric vehicle fleets and autonomous robots in Shanghai and Hangzhou municipal pilot zones. Same-day delivery expectations in tier-one cities concentrate demand with operators holding MIIT 5G-plus-industrial internet licenses for real-time cargo visibility.
- Warehousing:Automated pick-to-light configurations reduce unit labor costs in mega-hubs processing over 100,000 items hourly. NMPA pharmaceutical certification requirements impose 2-8°C validation documentation, raising barriers for ambient-only facilities.
- Transportation:Long-haul freight connects Yangtze River Delta production clusters to consumption centers.
- Fulfillment:Integrated warehousing-plus-delivery contracts dominate merchant procurement for high-velocity SKUs.
Volume sits with Last Mile Delivery; growth tilts toward Warehousing as robotics capex concentrates with scaled operators.
Customer Type:
Contractual complexity and order frequency separate procurement behaviors across buyer categories.
- B2C:Individual consumers drive same-day delivery expectations through platform interfaces. Urban density in Shanghai, Jiangsu, and Zhejiang enables route consolidation economics that subsidize rural delivery losses.
- B2B:Enterprise procurement demands temperature-validated pharmaceutical distribution with blockchain-verified handoff records under NMPA Good Supply Practice rules.
- C2C:Peer-to-peer parcel exchange relies on third-party carrier pools coordinated through data-layer platforms.
- Direct-to-Consumer:Brand-owned channels bypass platform fees but require captive fulfillment infrastructure.
Revenue concentrates in B2C; compliance investment is steepest in B2B pharmaceutical corridors.
Technology:
Capital deployment intensity and regulatory approval timelines segment technology adoption curves.
- Automated Systems:Robotic sortation and pick-to-light configurations dominate mega-hub investments. Technician scarcity for maintenance above 100,000 items hourly throughput limits deployment to coastal tier-one cities.
- Tracking Solutions:IoT sensor networks satisfy MIIT real-time visibility mandates for network license eligibility.
- Inventory Management:Warehouse management systems integrate with merchant ERP platforms for multi-location stock segmentation.
- Drone Delivery:Low-altitude airspace permissions in municipal pilot programs enable fastest-expanding technology segment for urban parcel distribution.
Installed base favors Automated Systems; regulatory momentum accelerates Drone Delivery.
Distribution Channel:
Platform control over merchant data and logistics pricing transparency shapes channel selection.
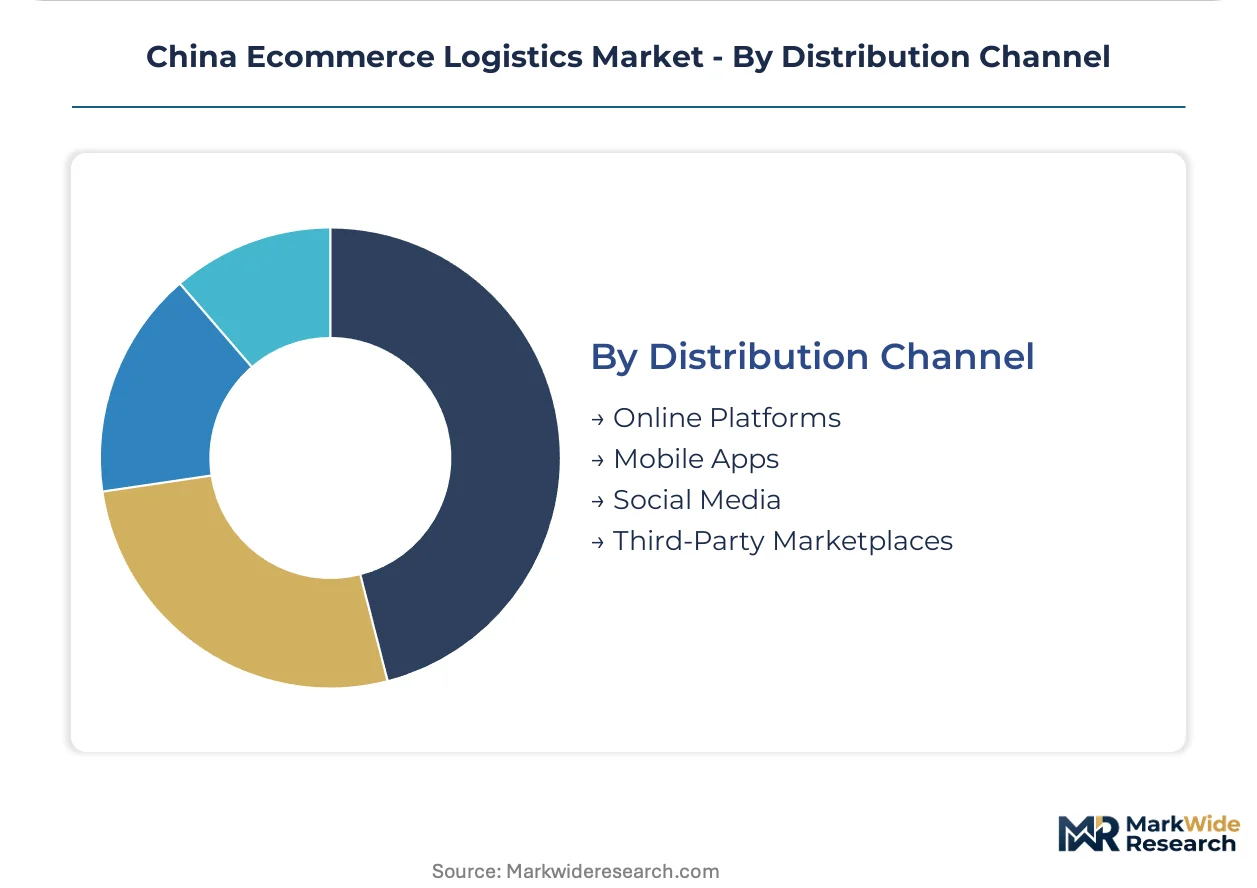
- Online Platforms:Dominant ecommerce marketplaces enforce SAMR contractual fairness rules that reshape third-party logistics pricing structures. Merchant fulfillment contracts unbundle warehousing from delivery to enable multi-carrier rate optimization.
- Mobile Apps:Super-app ecosystems integrate ordering, payment, and delivery tracking in single interfaces.
- Social Media:Live-stream commerce drives impulse purchases requiring rapid fulfillment turnaround.
- Third-Party Marketplaces:Aggregator platforms fragment carrier selection across fragmented last-mile pools.
Transaction volume flows through Online Platforms; Social Media channels are climbing fastest as live-stream commerce penetrates lower-tier cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors China's ecommerce logistics density, with Shanghai's port infrastructure feeding automated mega-hubs across Jiangsu and Zhejiang provinces.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang concentrate over half of national parcel volume through integrated fulfillment networks. MIIT's 5G-plus-industrial internet mandates require real-time cargo visibility for network license eligibility across this corridor. Automated sortation facilities in Hangzhou and Suzhou process over 100,000 items hourly while maintaining NMPA pharmaceutical cold-chain compliance.
Pearl River Delta
Guangdong's manufacturing base generates massive cross-border ecommerce flows through Shenzhen's bonded zones. SAMR's platform-merchant contractual fairness rules reshape third-party logistics pricing transparency for exporters. The Guangzhou-Shenzhen corridor hosts dense last-mile networks serving same-day delivery expectations in tier-one consumption centers.
Beijing-Tianjin-Hebei
North China's political and regulatory center drives compliance-heavy pharmaceutical and fresh produce logistics demand. NMPA's Good Supply Practice rules impose 2-8°C validation documentation across all distribution handoffs in this region. Tianjin's port infrastructure supports temperature-controlled import channels for vaccine and biologic distribution.
Sichuan-Chongqing
Western China's consumption growth creates expansion opportunities for logistics operators building inland hub capacity. Dual carbon goals alignment unlocks green financing for electric vehicle fleet deployment across Chongqing's mountainous terrain. The Chengdu-Chongqing economic circle attracts automated warehousing investment as coastal costs rise.
Shandong Peninsula
Shandong's agricultural output drives fresh produce cold-chain expansion connecting farms to eastern consumption markets. Provincial regulators enforce GB national standard revisions for autonomous delivery vehicle road access in Qingdao and Yantai pilot programs. Temperature-controlled fulfillment networks here anchor adoption growth for perishable ecommerce segments.
China Ecommerce Logistics Market Competitive Environment
Backward integration into warehouse robotics and autonomous vehicle fleets dominates the current landscape, with operators rebalancing from pure outsourced models toward hybrid captive-third-party structures. The vendor base concentrates around three archetypes: platform-captive logistics arms, premium express specialists, and data-layer coordinator networks. Capacity expansion and technology licensing represent the primary competitive vectors as scaled operators deploy automated pick-to-light configurations.
Among platform-affiliated operators, JD Logistics and Cainiao Network occupy positions as archetypal captive and coordinator models respectively. SF Express anchors the premium express specialist tier through time-definite service positioning. These three entities exemplify the strategic divergence between backward integration, data-layer coordination, and premium service density as competing routes to margin sustainability.
| Leading Market Players |
|---|
| SF Express |
| JD Logistics |
| Cainiao Network |
| ZTO Express |
| YTO Express |
| Yunda Express |
| STO Express |
| Best Inc. |
| J&T Express |
| Others |
Value Chain & Pricing Dynamics
Platform-affiliated merchants in the Yangtze River Delta concentrate procurement power through unbundled warehousing and delivery contracts, driving contract structures toward outcome-based pricing with temperature-compliance premiums layered atop base logistics fees.
Pricing Analysis
Warranty and service bundling splits sharply between captive platform logistics and third-party carriers. Three-tier pricing structure across premium, standard, and economy levels reflects NMPA certification grade and real-time visibility capability under MIIT mandates. Price differentiation hinges on temperature-validation documentation and 5G-plus-industrial internet license status. Cost compression in economy-tier ambient parcel delivery is intensifying because SAMR fairness rules constrain margin flexibility, while B2C consumers remain most price-sensitive and pharmaceutical B2B buyers least.
Supply Chain Analysis
Direct-to-merchant channels handle hyperscale platform demand through JD Logistics and Cainiao Network integration, while fragmented last-mile carrier pools serve smaller sellers. Manufacturing concentration centers on China for warehouse robotics and autonomous vehicle fleets, with South Korea and Japan supplying precision sensor components. Lithium-ion battery cells, LIDAR modules, and cold-chain insulation materials constitute critical input dependencies. Single-source vulnerability in semiconductor chips for automated sortation systems creates procurement risk. Distribution runs through tier-one coastal clusters before radiating inland via Chongqing and Chengdu hub expansions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China ecommerce logistics sits in a technology-transition phase where warehouse robotics and autonomous vehicle fleets displace labor-intensive legacy operations across the Yangtze River Delta corridor.
For Market Incumbents: Deepen backward integration into robotic pick-to-light manufacturing to defend against technician scarcity bottlenecks. Expand autonomous vehicle fleet deployment in Hangzhou and Shanghai municipal pilot zones before GB standard revisions widen road access. Priority lever rests on securing NMPA pharmaceutical certification moats as compliance barriers rise.
For New Entrants and Emerging Players: Begin with drone delivery airspace permissions in low-altitude corridors where regulatory momentum outpaces scaled operator presence. Target Sichuan-Chongqing inland hub capacity gaps as coastal costs rise and dual carbon goals unlock green financing. Go-to-market angle centers on temperature-controlled fresh produce segments underserved by ambient-focused incumbents.
For Investors and Strategic Acquirers: The window for entry favors mid-cap automated warehousing specialists with existing MIIT license eligibility. Long-term viability over the coming decade hinges on robotics capex concentration trends favoring scaled operators. Signal to monitor involves municipal pilot program expansions for autonomous vehicle road access permissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Vehicle Fleet Expansion | Municipal pilot programs in Shanghai and Hangzhou compress last-mile labor costs. |
| Pharmaceutical Cold-Chain Certification | NMPA Good Supply Practice rules create compliance moats against generalist carriers. |
| Drone Delivery Airspace Licensing | Low-altitude corridor permissions enable fastest-expanding urban parcel technology segment. |
| Robotics Manufacturing Backward Integration | In-house production of pick-to-light systems reduces technician dependency and unit costs. |
| Cross-Border Bonded Zone Integration | Southeast Asian corridor development unlocks temperature-controlled pharmaceutical export channels. |
Study Parameters
Trade publications, MIIT regulatory filings, and NMPA distribution guidance documents formed the secondary backbone, supplemented by customs records and platform logistics capex disclosures. Primary interviews with warehouse operations directors, last-mile carrier fleet managers, pharmaceutical supply chain leads, and robotics maintenance technicians informed demand-side validation. Bottom-up parcel volume modeling and top-down GDP elasticity approaches were triangulated against secondary data benchmarks.
Historical trendline analysis of parcel throughput velocities and cold-chain infrastructure deployment informed projection frameworks across the modeling period. Segmentation dimensions included service type, customer category, technology tier, and regional regulatory cluster. CAGRs were derived from elasticity modeling against ecommerce penetration curves and autonomous vehicle regulatory milestone timelines. Forecast inputs incorporated MIIT 5G license issuance patterns and municipal pilot program expansion schedules.
Underlying measurement precision varies by segment; last-mile delivery and automated warehousing carry tighter precision than emerging drone delivery categories. Forecasts reflect assumptions regarding regulatory airspace permissions and GB standard revision timelines. Periodic stress-testing of base assumptions is recommended given autonomous vehicle deployment uncertainty and SAMR enforcement intensity variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Malta E-Commerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market