
 Canada E-Commerce Market | 2026-2036
Canada E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Canada E-Commerce Market Analysis
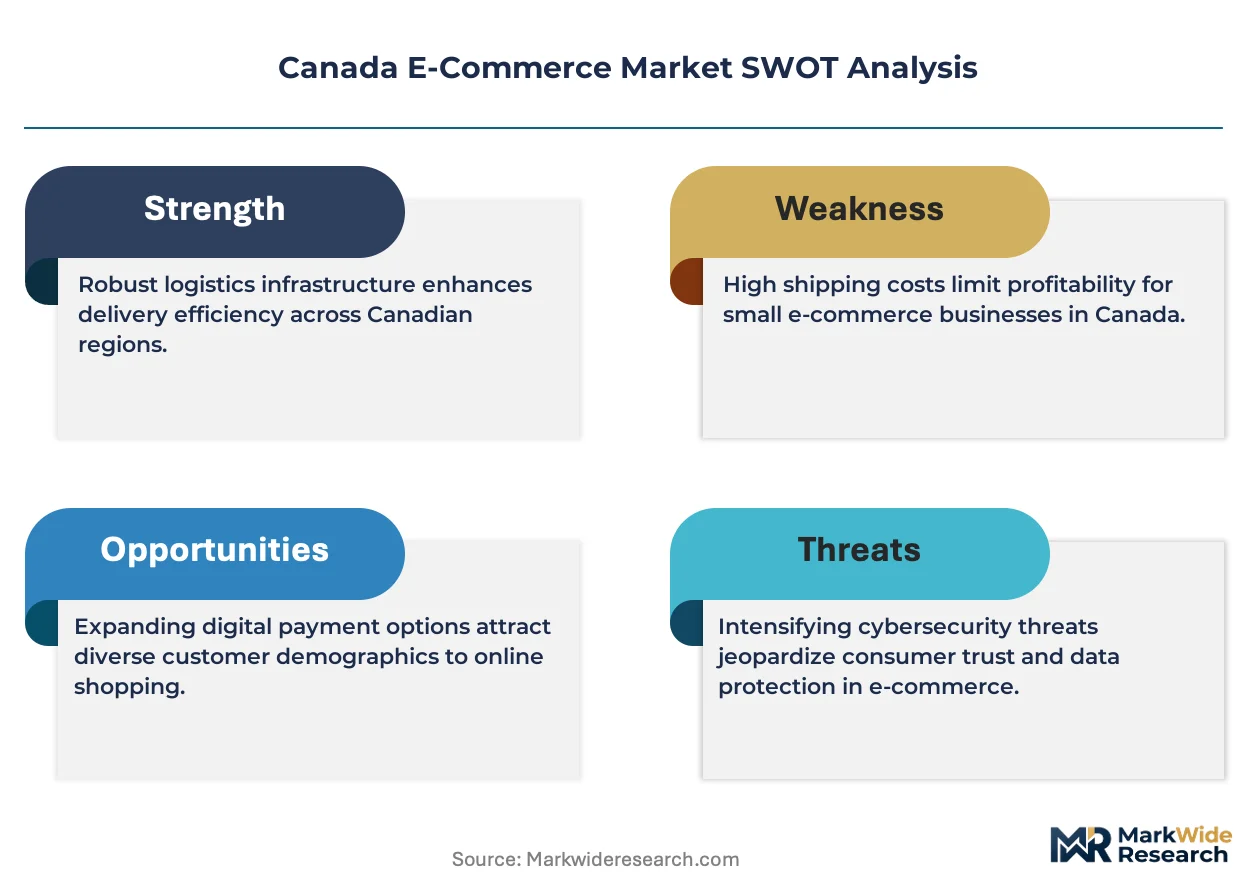
Platform licensing revenue is narrowing as a margin pool as major retailers build proprietary fulfillment capabilities rather than depend on third-party infrastructure. Amazon Canada leverages its captive logistics network to control last-mile delivery economics across the Prairie provinces. Walmart Canada anchors its competitive stance through grocery pickup integration with existing supercenter footprints. Shopify specializes in software-as-a-service tools that let independent merchants compete against scaled marketplaces without building custom technology stacks.
Canada e-commerce comprises digitally mediated transactions for goods and services executed through web-based storefronts, mobile applications, and embedded checkout interfaces, relying on encrypted payment gateways, inventory management systems, and algorithmic recommendation engines to match supply with dispersed demand. Fashion and electronics product categories generate the highest transaction volumes, though home goods is deepening its share as furniture retailers invest in augmented reality visualization tools that reduce return rates. Direct-to-consumer sales channels capture premium margin pools by eliminating intermediary fees, while marketplace channels sustain volume leadership through consolidated traffic and trust infrastructure.
Health Canada and the Competition Bureau shape product safety and advertising standards for goods sold through digital channels, while the Office of the Privacy Commissioner enforces consent requirements under PIPEDA that affect customer data collection practices. Provincial regulators in Quebec and British Columbia layer additional language and consumer-protection obligations onto national frameworks. Stakeholders must monitor how forthcoming federal privacy legislation and provincial sales-tax harmonization rules will alter compliance costs and platform liability structures.
Market Dynamics
Same-day fulfillment infrastructure is compressing delivery windows across Canadian urban corridors, forcing retailers to localize inventory positioning and reconfigure last-mile economics around grocery and household essentials penetration.
Growth Catalysts
- PIPEDA consent modernization:Health Canada and the Office of the Privacy Commissioner are tightening data-handling standards, creating competitive separation for retailers with compliant first-party data architectures.
- Quebec language obligations:Provincial consumer-protection frameworks mandate French-language interfaces, accelerating localization technology adoption among national marketplace operators.
- Grocery pickup integration:Supercenter footprint leverage is converting routine household purchases to digital channels faster than discretionary categories.
Market Restraints
- Last-mile labor scarcity:Courier capacity constraints in Ontario and British Columbia inflate per-package delivery costs during peak seasonal windows.
- Interprovincial tax fragmentation:Provincial sales-tax harmonization gaps create checkout friction and compliance overhead for cross-border fulfillment networks.
- Return logistics density:Furniture and home goods visualization gaps sustain elevated return rates that erode margin pools in high-ticket categories.
Strategic Opportunities
- Prairie province logistics gaps:Manitoba and Saskatchewan present underpenetrated corridors where captive delivery networks can preempt third-party platform dependence.
- Augmented reality convergence:3D product visualization tools are reducing return rates for furniture retailers investing in spatial computing interfaces.
- Direct-to-consumer channel expansion:Independent merchants using software-as-a-service infrastructure are capturing premium margin pools outside consolidated marketplace traffic.
Industry Challenges
- First-party data engineering talent:PIPEDA compliance complexity outpaces supply of privacy-technical specialists capable of architecting consent-management systems.
- Fulfillment center capex cycles:Urban land scarcity in Vancouver and Toronto accelerates facility cost inflation ahead of revenue maturation timelines.
- Legacy inventory system integration:Real-time stock synchronization across supercenter, warehouse, and dropship nodes demands middleware investment many mid-market retailers have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada E-Commerce Market |
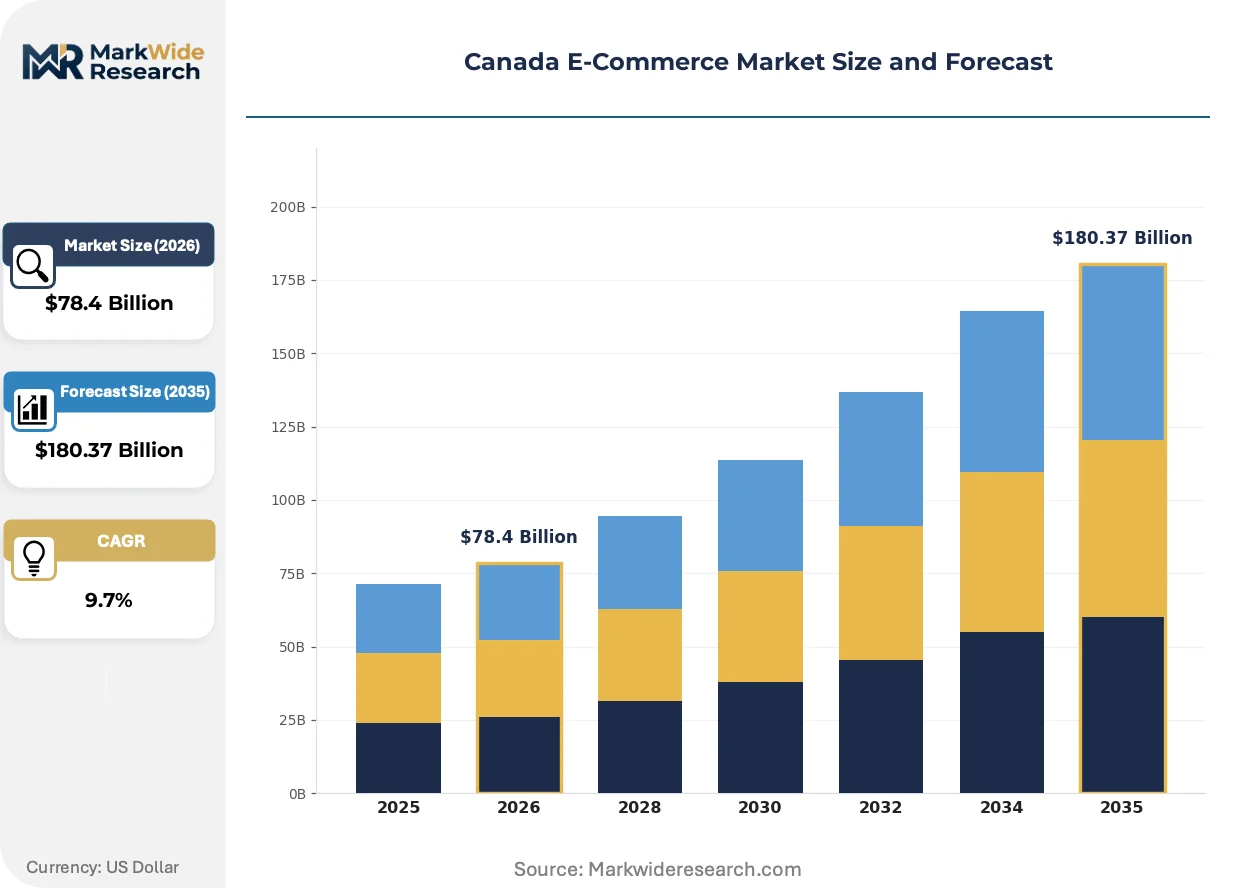
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Goods, Beauty Products Sales Channel: Direct-to-Consumer, Marketplaces, Social Media, Subscription Services Customer Type: Businesses, Consumers, Institutions, Non-profits Payment Method: Credit Cards, Digital Wallets, Bank Transfers, Buy Now Pay Later |
| Companies Covered | Amazon Canada, Walmart Canada, Shopify, Canadian Tire, Costco Canada, Best Buy Canada, Home Depot Canada, Loblaw Companies, Apple Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada E-Commerce Market Emerging Trajectories
Algorithmic recommendation engines and encrypted payment gateways are merging with localized fulfillment infrastructure to reshape how Canadian retailers match dispersed demand with inventory positioning.
Augmented reality visualization tools are collapsing the information gap between digital browsing and physical product assessment. Furniture and home goods retailers deploying spatial computing interfaces report measurable return rate compression. Canadian consumers in Ontario and British Columbia demonstrate highest adoption velocity for room-scale product preview features.
The Digital Charter Implementation Act is restructuring liability frameworks for platform operators handling cross-provincial transactions. Federal privacy legislation expands consent documentation requirements beyond existing PIPEDA baselines. Marketplace channels face disproportionate compliance burden relative to direct-to-consumer merchants with simpler data architectures.
Subscription replenishment models are displacing discrete purchase cycles for household essentials. Grocery and personal care categories show fastest migration toward automated reordering systems. Urban density corridors in Toronto and Vancouver generate sufficient order frequency to sustain micro-fulfillment node economics that remain unviable in dispersed Prairie markets.
Canada E-Commerce Market Segmentation
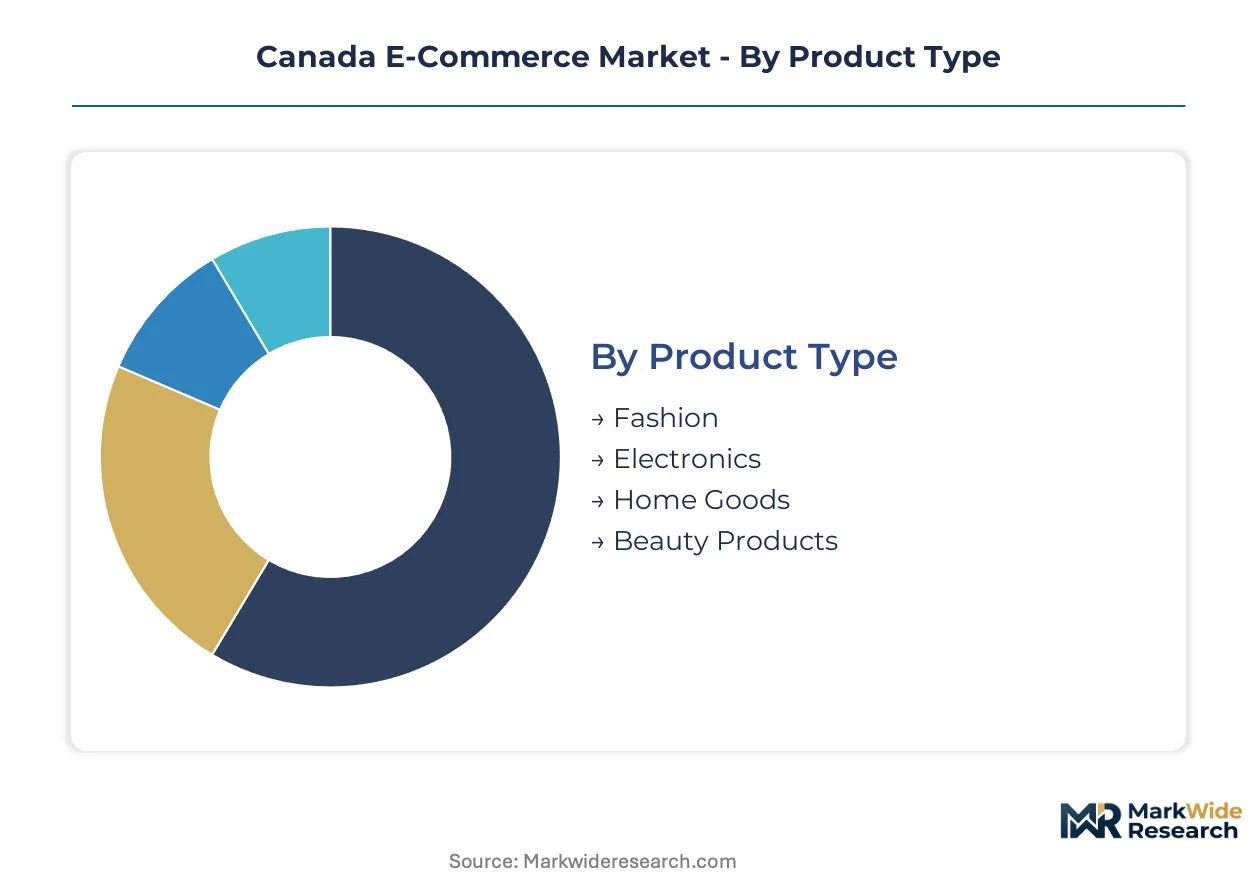
Segmentation in the Canada E-Commerce Market reveals how purchasing behavior fragments across product categories, channel preferences, and payment infrastructures. Each dimension carries distinct margin profiles and compliance obligations under federal and provincial frameworks.
Product Type:
Use-case spectrum spans impulse-driven discretionary purchases to planned replenishment of household necessities, with visualization technology and return logistics shaping economics differently across categories.
- Fashion:Apparel and accessories dominate transaction frequency with size-fit variability driving return rates. Ontario and British Columbia urban corridors concentrate demand where same-day fulfillment networks compress delivery windows for seasonal collections.
- Electronics:High-consideration purchases involving specification comparison and warranty validation. Quebec consumers demonstrate elevated adoption of French-language product detail pages, accelerating retailer localization investments.
- Home Goods:Furniture and décor sustained by augmented reality visualization tools that reduce return friction.
- Beauty Products:Personal care and cosmetics with subscription replenishment models displacing discrete purchase cycles.
Established volume favors Fashion; emerging adoption favors Home Goods.
Sales Channel:
Channel economics diverge sharply based on traffic ownership, data architecture complexity, and PIPEDA compliance burden.
- Direct-to-Consumer:Merchant-controlled storefronts capturing premium margin pools by eliminating intermediary fees. First-party data architectures under Health Canada and Office of the Privacy Commissioner oversight create competitive separation for compliant operators.
- Marketplaces:Consolidated traffic infrastructure with trust mechanisms and review systems. Federal privacy legislation imposes disproportionate consent documentation burdens relative to simpler direct-to-consumer data architectures.
- Social Media:Embedded checkout interfaces merging discovery with transaction completion.
- Subscription Services:Automated replenishment systems converting routine household purchases to recurring revenue streams.
Marketplaces dominate transaction volume; Direct-to-Consumer channels expand most quickly.
Customer Type:
Procurement patterns separate institutional bulk purchasing from individual consumer behavior, with tax treatment and fulfillment scale determining channel viability.
- Businesses:B2B procurement platforms with negotiated pricing tiers and invoice-based settlement. Prairie province logistics gaps in Manitoba and Saskatchewan present underpenetrated corridors where captive delivery networks preempt third-party dependence.
- Consumers:Individual purchasers driving algorithmic personalization and recommendation engine investment.
- Institutions:Government and educational procurement with compliance documentation requirements.
- Non-profits:Donation-driven and mission-aligned purchasing with restricted budget cycles.
Consumers anchor absolute volume; Businesses show steepest expansion trajectory.
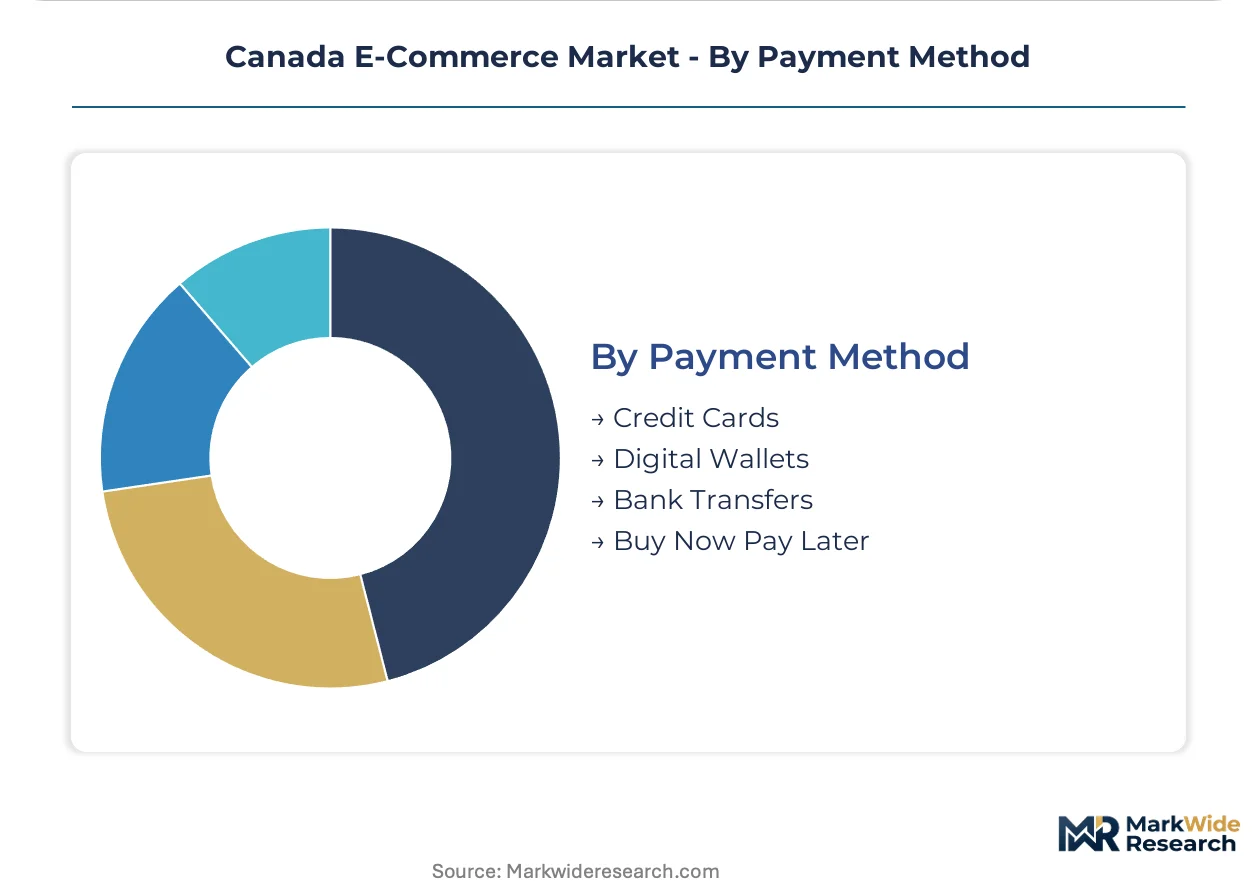
Payment Method:
Settlement infrastructure choices reflect credit access, regulatory treatment of deferred payment products, and merchant fee sensitivity.
- Credit Cards:Dominant payment rails with established chargeback protections and reward program integration. Interprovincial tax fragmentation creates checkout friction where provincial sales-tax harmonization gaps persist.
- Digital Wallets:Mobile-optimized stored credentials with biometric authentication layers.
- Bank Transfers:Lower-fee settlement for high-ticket purchases with delayed confirmation cycles.
- Buy Now Pay Later:Point-of-sale credit products facing heightened Competition Bureau scrutiny over disclosure standards.
Credit Cards maintain incumbent position; Buy Now Pay Later gains share fastest among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian e-commerce demand exhibits sharp elasticity variation across provinces, with Ontario and British Columbia buyers demonstrating lowest price sensitivity for same-day convenience while Prairie province consumers prioritize cost over speed.
Ontario
Toronto and Ottawa corridor drive transaction density through grocery pickup integration and micro-fulfillment node economics. The federal Digital Charter Implementation Act imposes consent documentation burdens that favor retailers with compliant first-party data architectures. Kitchener-Waterloo technology cluster anchors logistics software development for inventory positioning algorithms.
Quebec
Montreal and Quebec City consumers accelerate French-language interface adoption across electronics and fashion categories. Provincial consumer-protection frameworks mandate bilingual storefront compliance, creating localization technology demand. Laval distribution hubs concentrate last-mile infrastructure investment for cross-provincial fulfillment networks.
British Columbia
Vancouver and Victoria urban density sustains same-day delivery economics for household essentials and beauty subscription services. The Office of the Privacy Commissioner enforces PIPEDA consent requirements affecting customer data collection practices. Burnaby fulfillment centers face land scarcity inflation ahead of revenue maturation timelines.
Alberta
Calgary and Edmonton corridors present underpenetrated logistics infrastructure relative to Ontario and British Columbia benchmarks. Provincial sales-tax harmonization gaps with federal frameworks create checkout friction for cross-border marketplace operators. Rocky View County distribution facilities expand captive delivery network coverage.
Prairie Provinces
Manitoba and Saskatchewan demonstrate lowest same-day delivery penetration among Canadian provinces, with Winnipeg and Saskatoon anchoring sparse fulfillment coverage. Health Canada product safety standards shape advertising compliance for goods sold through digital channels. Regina logistics gaps present strategic opportunities for retailers building proprietary last-mile capabilities.
Canada E-Commerce Market Vendor Landscape
Capability concentration sits with software-as-a-service specialists; scale advantage sits with integrated marketplace operators with captive logistics networks. The market structure tiers between platform-dependent merchants and infrastructure-controlling retailers. Three strategic archetypes dominate: captive logistics operators, software enablers for independent merchants, and supercenter-anchored grocery integrators. Competitive moves center on fulfillment center capacity expansion and proprietary delivery network buildout.
Among marketplace operators with captive infrastructure, Amazon Canada and Walmart Canada exemplify the scale-driven archetype through logistics network control, while Shopify occupies a position within the software-enablement tier empowering independent merchant competitiveness without custom technology investment.
| Leading Market Players |
|---|
| Amazon Canada |
| Walmart Canada |
| Shopify |
| Canadian Tire |
| Costco Canada |
| Best Buy Canada |
| Home Depot Canada |
| Loblaw Companies |
| Apple Canada |
| Others |
Supply Flow & Price Mechanics
The Toronto-Montreal freight corridor anchors cost dynamics for Canadian e-commerce, with fuel surcharges and driver scarcity in Ontario creating tiered delivery pricing that separates same-day urban premiums from Prairie province economy tiers. Supply concentration in Vancouver and Toronto fulfillment hubs feeds downstream price differentiation between captive logistics operators and third-party dependent merchants.
Pricing Analysis
After-sales revenue through subscription replenishment and extended warranty tiers drives lifetime value capture across grocery and household essentials categories. Three-tier pricing structure across premium same-day, standard next-day, and economy ground delivery levels reflects urban density gradients and courier capacity constraints. Cost compression in last-mile labor pools is intensifying because seasonal demand spikes outstrip Ontario and British Columbia courier availability. Small and mid-market retailers exhibit highest price sensitivity, while integrated marketplace operators with captive networks demonstrate lowest sensitivity due to volume-leveraged carrier negotiations.
Supply Chain Analysis
Supplier financing through extended payment terms and supply-chain finance facilities enables mid-market retailers to defer middleware investments for real-time inventory synchronization. Geographic supply concentration draws from China for electronics components, Vietnam for apparel manufacturing, and domestic Ontario and British Columbia for grocery fulfillment infrastructure. Raw material dependencies include lithium-ion cells for warehouse robotics, corrugated packaging from Quebec pulp mills, and cloud compute capacity from hyperscaler regions. Single-source vulnerability in last-mile courier networks creates structural risk during peak seasonal windows. Distribution runs through captive fulfillment centers for scaled operators and third-party logistics nodes for independent merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian e-commerce is recovering from a cyclical trough driven by interest-rate sensitivity in consumer discretionary spending, with grocery and household essentials providing defensive ballast.
For Market Incumbents: Insulate margin pools by accelerating proprietary last-mile buildout in Manitoba and Saskatchewan before third-party platforms consolidate Prairie province coverage. Anchor defensive positioning through backward integration into micro-fulfillment node real estate in Toronto and Vancouver land-scarce corridors. Counter emerging direct-to-consumer SaaS-enabled merchants by deepening supercenter grocery pickup integration that independent operators cannot replicate without footprint scale.
For New Entrants and Emerging Players: Establish a beachhead in augmented reality visualization tools for furniture and home goods retailers seeking return rate compression. Target Quebec's French-language localization gap where provincial consumer-protection mandates create compliance friction for national marketplace operators. Pursue a go-to-market angle through Shopify ecosystem partnerships that bypass proprietary technology stack requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy retailers with deferred inventory system integration and stranded middleware investments. Long-term viability hinges on first-party data architecture compliance under PIPEDA modernization and Digital Charter Implementation Act expansion. Watch Health Canada enforcement patterns on product safety advertising as an inflection indicator for platform liability cost allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Last-Mile Network Expansion | Prairie province logistics gaps in Manitoba and Saskatchewan reward proprietary delivery buildout ahead of third-party consolidation. |
| Augmented Reality Visualization Deployment | Furniture retailers using spatial computing interfaces report measurable return rate compression in Ontario and British Columbia urban corridors. |
| First-Party Data Architecture Investment | PIPEDA consent modernization creates competitive separation for compliant operators under Office of the Privacy Commissioner oversight. |
| Micro-Fulfillment Node Siting | Toronto and Vancouver land scarcity accelerates facility cost inflation, favoring early-mover real estate capture. |
| Quebec Localization Technology Adoption | Provincial French-language mandates accelerate bilingual storefront compliance demand among national marketplace operators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, Canadian retail trade association reports, and Office of the Privacy Commissioner enforcement disclosures. Primary interviews engaged e-commerce platform executives, logistics operations directors, grocery retail category managers, and provincial consumer protection regulators. Secondary validation drew from customs and trade data, fulfillment center permitting records, and PIPEDA compliance documentation. Bottom-up merchant revenue estimates and top-down addressable market calculations were triangulated against census consumer expenditure patterns.
Forecast inputs include algorithmic personalization investment cycles, grocery pickup integration penetration curves, and fulfillment center capex deployment timelines across the projection horizon. Segmentation dimensions modeled span product type, sales channel architecture, customer procurement pattern, and payment settlement infrastructure. CAGRs were derived from historical transaction velocity trends and infrastructure capacity expansion schedules. Industry-specific inputs incorporate courier capacity utilization rates in Ontario and British Columbia peak windows and Quebec language compliance technology adoption curves.
Sensitivities concentrate around interprovincial tax harmonization rule changes, federal privacy legislation implementation timing, and Prairie province logistics infrastructure buildout pace. Forecasts reflect documented assumptions on consumer channel migration and fulfillment technology deployment. Macroeconomic deviation in household discretionary spending, regulatory enforcement intensity shifts, or augmented reality adoption velocity changes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market