
 Asia Pacific B2B E-Commerce Market | 2026-2036
Asia Pacific B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific B2B E-Commerce Market Outlook
China's dual carbon goals is recalibrating procurement priorities across industrial supply chains. Alibaba Group Holding Ltd anchors cross-border wholesale flows through integrated trade finance and customs clearance tools. JD.com Inc. competes on fulfillment velocity, sustaining same-day delivery capabilities for enterprise buyers in tier-one manufacturing clusters.
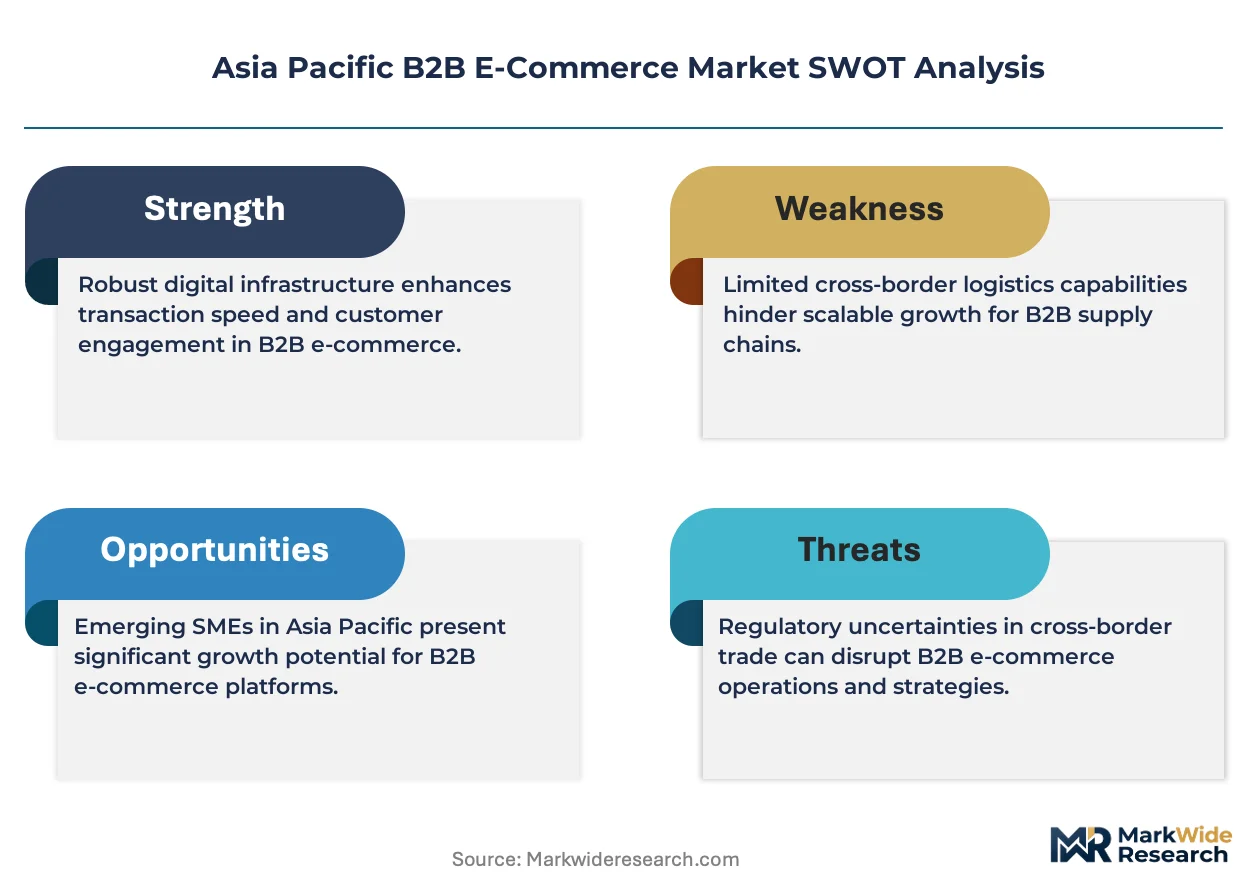
Asia Pacific B2B E-Commerce denotes digitally intermediated transactions between enterprises across software, hardware, services, and payment solutions, executed through online platforms, direct sales channels, marketplaces, and dedicated B2B portals. The infrastructure layer relies on API-first architecture connecting ERP systems to supplier networks, enabling automated purchase order generation and invoice reconciliation. Services and payment solutions command expanding margin pools as manufacturers prioritize embedded finance over standalone procurement tools. Online platforms and marketplaces lead transaction volume, though direct sales channels retain dominance in specialized industrial equipment where technical specification negotiation requires human intervention.
China's SAMR enforces data localization mandates for cross-border e-commerce operators, while India's RBI governs payment aggregator licensing for B2B transaction settlement. Japan's METI promotes SME digitization through standardized electronic invoicing protocols. Stakeholders must monitor divergent data sovereignty requirements as they architect multi-country platform deployments.
Market Dynamics
API-first procurement architectures are compressing purchase order cycles across Asia Pacific manufacturing networks, eroding the traditional role of procurement intermediaries in favor of direct platform integration between ERP systems and supplier marketplaces.
Growth Catalysts
- India's PLI scheme:Electronics manufacturing incentives mandate supplier digitization, forcing component vendors onto B2B platforms to qualify for government subsidies.
- Embedded finance adoption:Manufacturers prioritize trade credit and invoice financing tools integrated directly into procurement workflows over standalone banking relationships.
- China's industrial belt concentration:Factory-direct platform purchasing in Shenzhen, Dongguan, and Suzhou clusters establishes template procurement behaviors that diffuse across Southeast Asian supplier networks.
Market Restraints
- Data localization mandates:China's SAMR requires domestic storage of cross-border transaction records, fragmenting platform architectures and inflating compliance infrastructure costs for multi-country operators.
- Payment aggregator licensing:India's RBI imposes capital reserve requirements on B2B settlement providers, constraining fintech entrants and preserving incumbent bank dominance in enterprise transactions.
- Technical specification complexity:Specialized industrial equipment procurement resists full digitization as buyers require human negotiation for performance guarantees and customization terms.
Strategic Opportunities
- Vietnam's manufacturing expansion:Electronics and textile producers migrating from China create greenfield demand for B2B platform infrastructure without legacy procurement system baggage.
- Japan's SME digitization push:METI's standardized electronic invoicing protocols reduce adoption friction for platform vendors targeting fragmented supplier bases in Osaka and Nagoya industrial corridors.
- Blockchain-IoT convergence:Immutable shipment verification combined with sensor-tracked inventory enables pay-on-delivery financing models that reduce working capital friction for buyers and suppliers.
Industry Challenges
- ERP integration complexity:Legacy SAP and Oracle deployments in established manufacturers resist API connectivity, requiring costly middleware development for platform onboarding.
- Cross-border tax compliance:Divergent GST, VAT, and customs documentation requirements across ASEAN markets fragment checkout flows and inflate platform engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific B2B E-Commerce Market |
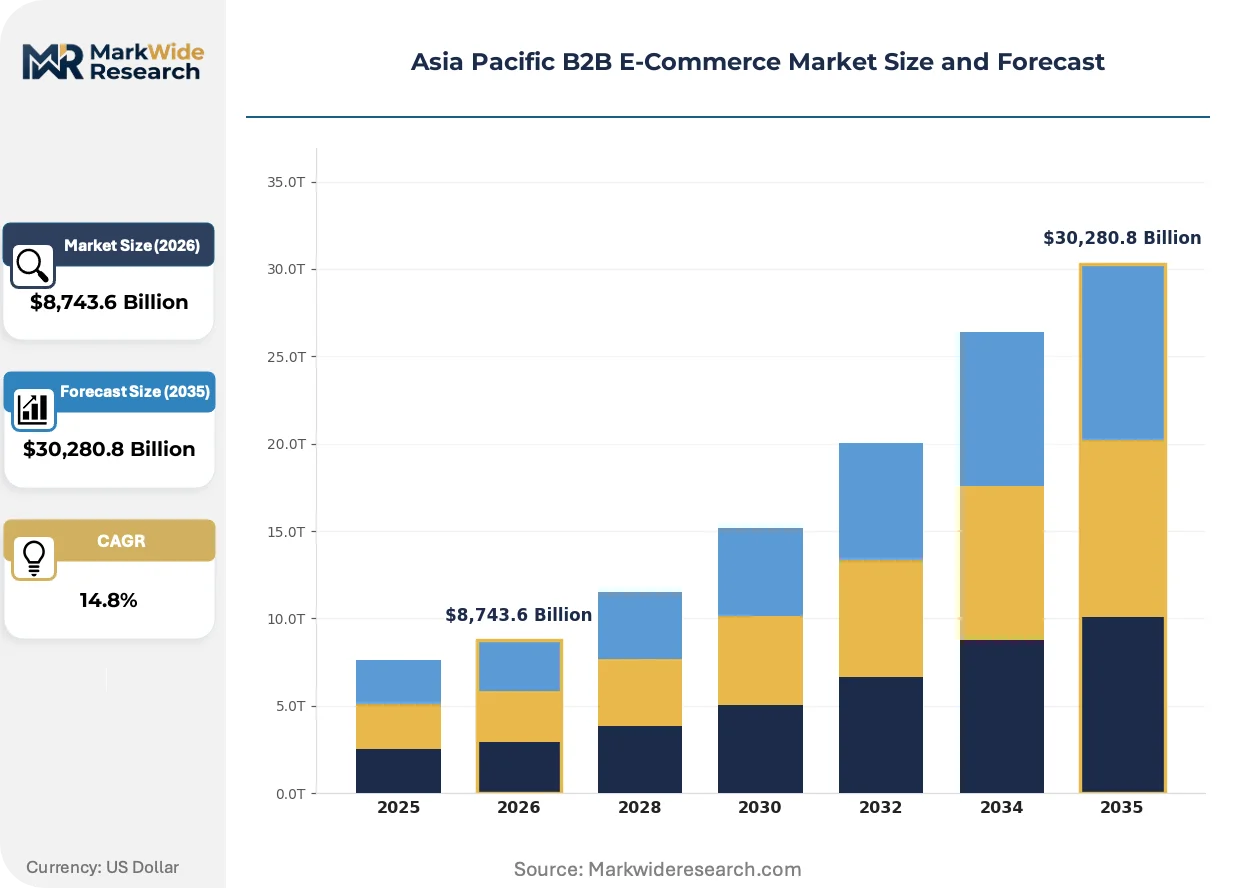
| Market Size in 2026 | $8,743.6 Billion |
| Market Size in 2035 | $30,280.8 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Payment Solutions End User: Manufacturers, Wholesalers, Distributors, Retailers Sales Channel: Online Platforms, Direct Sales, Marketplaces, B2B Portals Service Type: Logistics, Customer Support, IT Solutions, Marketing |
| Companies Covered | Alibaba Group Holding Ltd, JD.com Inc., Amazon.com Inc., IndiaMart InterMesh Ltd, Flipkart Online Services Pvt Ltd, Rakuten Group Inc., eBay Inc., Coupang Corp., Global Sources Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific B2B E-Commerce Market Strategic Shifts
Intelligent procurement systems are displacing rule-based automation across Asia Pacific industrial supply chains, compressing the gap between demand signal and supplier response from days to hours.
Machine learning-powered demand forecasting is automating inventory replenishment decisions for electronics manufacturers in China's Pearl River Delta. Foxconn-tier contract manufacturers deploy these tools to synchronize component orders with production schedules. The technology is automating procurement planner roles and consolidating purchasing authority within centralized platform dashboards.
Japan's METI electronic invoicing mandate accelerates B2B payment digitization across keiretsu supplier networks. The regulation eliminates paper-based reconciliation processes that previously delayed settlement cycles. Automotive and machinery sectors in Aichi and Kanagawa prefectures face the steepest compliance deadlines and are prioritizing platform vendors with pre-certified invoice formatting.
Factory procurement officers now specify fulfillment velocity as a primary vendor selection criterion, displacing price-centric evaluation frameworks. JD.com's same-day delivery capabilities in tier-one Chinese manufacturing clusters establish performance benchmarks that buyers export to cross-border supplier relationships. Electronics assemblers in Vietnam and Indonesia increasingly penalize delivery window misses with contract termination clauses.
Asia Pacific B2B E-Commerce Market Segmentation
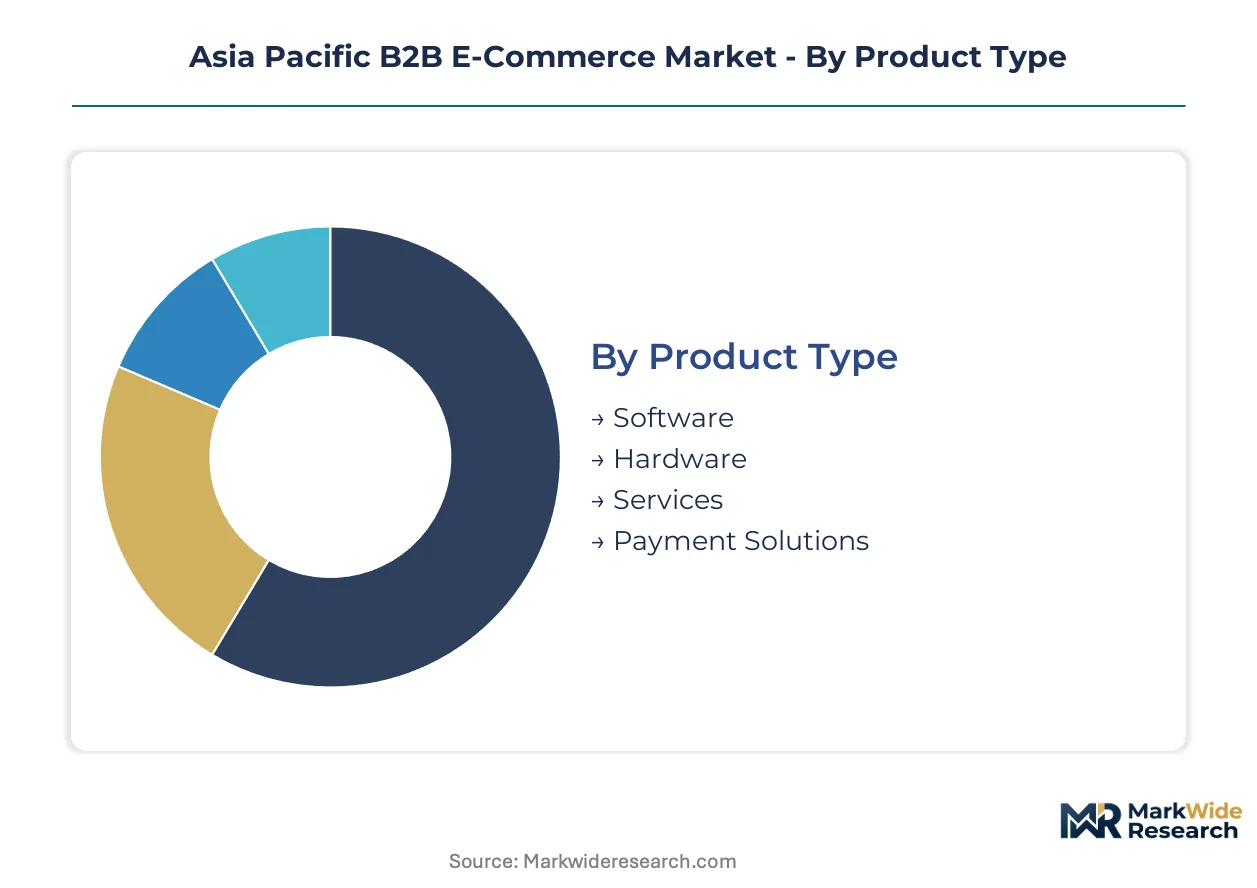
Segmentation in Asia Pacific B2B e-commerce reveals how capital deployment and procurement complexity vary sharply across product types and buyer categories. Platform operators calibrate their infrastructure investments and partnership strategies based on these structural divisions.
Product Type:
Capital intensity peaks in hardware and payment infrastructure, where physical fulfillment networks and regulatory compliance impose heavy upfront burdens.
- Software:Cloud-native procurement suites and ERP integration modules dominate transaction orchestration. China's industrial belt cities in Shenzhen and Dongguan drive concentrated demand as manufacturers digitize purchase order workflows under SAMR data localization mandates.
- Payment Solutions:Embedded trade finance and invoice factoring tools capture expanding margin pools. India's RBI licensing requirements for B2B settlement providers constrain fintech entrants, preserving bank-led infrastructure in Mumbai and Bangalore enterprise corridors.
- Hardware:Industrial IoT devices and procurement terminals require significant manufacturing partnerships.
- Services:Implementation and consulting support follows software adoption curves.
Payment solutions absorb the bulk of installed capacity; software is expanding most quickly.
End User:
Procurement sophistication and transaction scale diverge dramatically across buyer types, with manufacturers commanding platform development priorities.
- Manufacturers:Electronics and automotive producers in Vietnam's northern industrial zones and Indonesia's Batam corridor generate the highest transaction velocities. India's PLI scheme mandates supplier digitization, forcing component vendors onto platforms to qualify for government incentives.
- Distributors:Multi-brand intermediaries in Thailand and Malaysia require complex inventory synchronization tools. Cross-border tax compliance across ASEAN markets fragments their checkout engineering requirements.
- Wholesalers:Bulk commodity traders in commodity-dependent economies.
- Retailers:Omnichannel merchants with fragmented supplier bases.
Manufacturers anchor platform revenue; distributors are gaining share fastest.
Sales Channel:
Channel economics reflect the tension between transaction velocity and customization depth in industrial procurement.
- Online Platforms:API-first architectures connecting ERP systems to supplier marketplaces dominate volume. JD.com's same-day fulfillment capabilities in tier-one Chinese manufacturing clusters establish performance benchmarks exported to Southeast Asian buyer expectations.
- Direct Sales:Specialized industrial equipment procurement resists full digitization. Japanese machinery buyers in Aichi prefecture require human negotiation for performance guarantees and customization terms.
- Marketplaces:Horizontal aggregation models compete on supplier breadth.
- B2B Portals:Vertical specialization in chemicals and metals trading.
Online platforms command transaction volume; direct sales retains margin concentration.
Service Type:
Service layer investments track where platform differentiation creates switching costs versus commoditized competition.
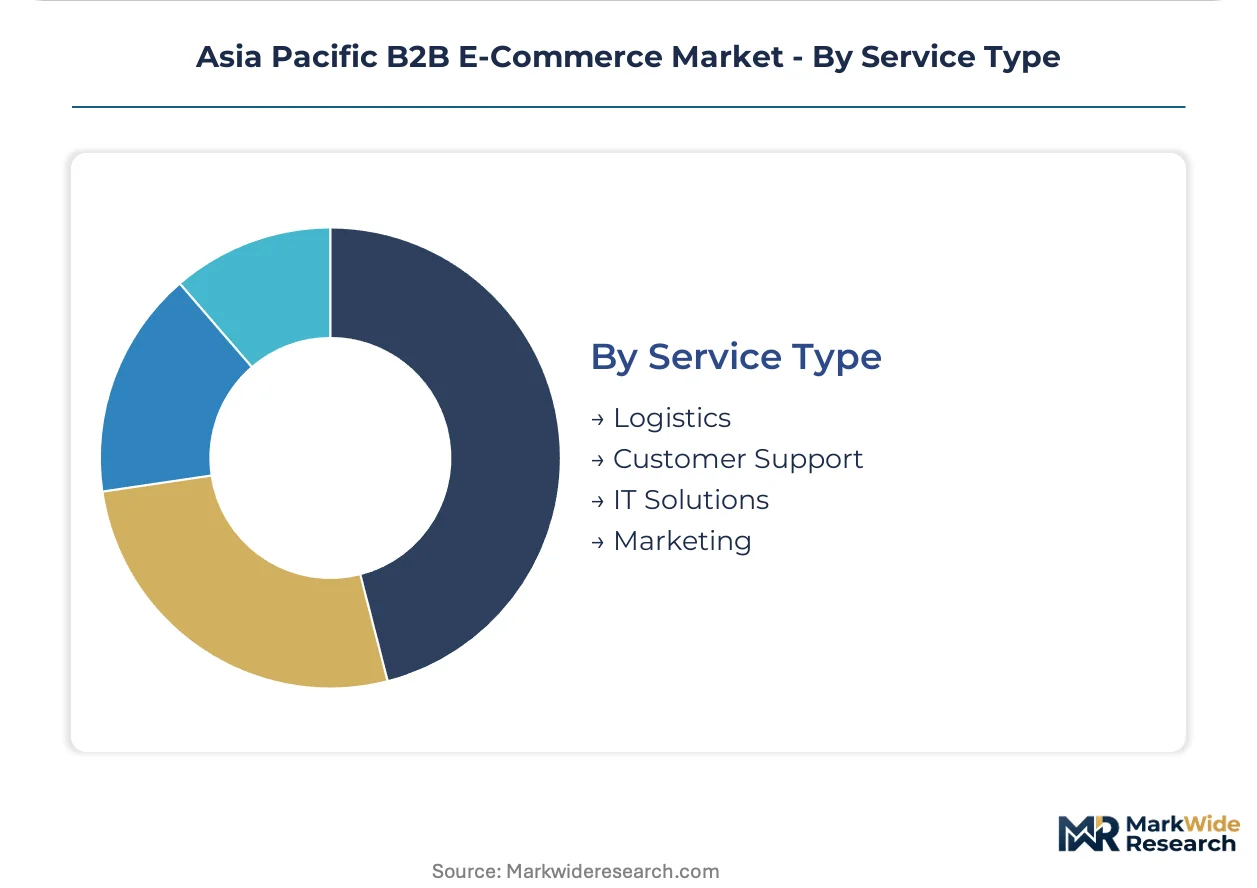
- Logistics:Same-day and next-day fulfillment networks require warehouse density and last-mile partnerships. Electronics assemblers in Vietnam increasingly penalize delivery window misses with contract termination clauses.
- IT Solutions:ERP integration and middleware development address legacy SAP and Oracle resistance in established manufacturers. Japan's METI electronic invoicing protocols reduce adoption friction for platform vendors targeting keiretsu supplier networks.
- Customer Support:Technical specification consultation for complex procurement.
- Marketing:Supplier discovery and demand generation tools.
Logistics absorbs the heaviest infrastructure investment; IT solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors platform transaction density across the Asia Pacific B2B e-commerce landscape. Factory-direct procurement in the Pearl River Delta cluster establishes behavioral templates that diffuse throughout Southeast Asian supplier networks.
China
Electronics manufacturers in Dongguan and Suzhou drive concentrated demand for API-first procurement architectures. SAMR data localization mandates fragment platform architectures and inflate compliance infrastructure costs for cross-border operators. JD.com's same-day fulfillment capabilities in tier-one manufacturing clusters establish performance benchmarks exported regionally.
India
Electronics component vendors face digitization mandates under the PLI scheme to qualify for government subsidies. RBI capital reserve requirements for B2B settlement providers constrain fintech entrants and preserve bank-led infrastructure in Mumbai and Bangalore enterprise corridors. India's northern industrial zones generate accelerating transaction velocities as supplier networks modernize.
Japan
Automotive and machinery sectors in Aichi and Kanagawa prefectures face steep METI electronic invoicing compliance deadlines. Standardized protocols eliminate paper-based reconciliation processes that previously delayed settlement cycles. Keiretsu supplier networks in the Chubu industrial corridor prioritize platform vendors with pre-certified invoice formatting.
Vietnam
Electronics and textile producers migrating from China create greenfield demand for B2B platform infrastructure. Northern industrial zones around Hanoi and Hai Phong lack legacy procurement system baggage. Electronics assemblers increasingly penalize delivery window misses with contract termination clauses.
South Korea
Busan-Ulsan manufacturing clusters demand fulfillment velocity as a primary vendor selection criterion. The Seoul Capital Area concentrates enterprise software adoption for ERP integration modules. Platform operators target the Daegu-Gyeongbuk corridor with logistics-heavy infrastructure investments.
Asia Pacific B2B E-Commerce Market Competitive Environment
The competitive structure tilts toward integrated platform operators with captive fulfillment networks. Horizontal marketplace aggregators compete on supplier breadth against vertical specialists with deep category expertise. Three archetypes dominate: ecosystem conglomerates with trade finance integration, logistics-first operators with same-day capabilities, and vertical specialists in industrial equipment. M&A activity concentrates on embedded fintech capabilities and cross-border customs clearance tools.
Among China-based ecosystem operators, Alibaba Group Holding Ltd and JD.com Inc. occupy positions defined by integrated trade finance and fulfillment velocity respectively. IndiaMart InterMesh Ltd exemplifies the vertical marketplace archetype targeting SME supplier digitization. Rakuten Group Inc. represents Japan-focused platform consolidation across keiretsu-adjacent procurement workflows.
| Leading Market Players |
|---|
| Alibaba Group Holding Ltd |
| JD.com Inc. |
| Amazon.com Inc. |
| IndiaMart InterMesh Ltd |
| Flipkart Online Services Pvt Ltd |
| Rakuten Group Inc. |
| eBay Inc. |
| Coupang Corp. |
| Global Sources Ltd |
| Others |
Value Chain & Pricing Dynamics
API-first procurement architectures are compressing transaction economics across Asia Pacific manufacturing networks, simultaneously eroding intermediary margins and concentrating pricing power within integrated platform operators that control fulfillment velocity and embedded finance tools.
Pricing Analysis
Fulfillment velocity anchors value-based pricing for enterprise buyers, with same-day delivery capabilities commanding premium positioning against standard multi-day alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration depth, with API-native ERP connectivity carrying the highest tier. Cost compression in standard tiers is intensifying because JD.com and Alibaba scale logistics density, forcing regional challengers to absorb margin erosion. Small and medium manufacturers show greatest price sensitivity, while automotive and electronics assemblers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale procurement demand from China's Pearl River Delta electronics clusters, bypassing traditional distributor layers. Supply concentrates in China, Vietnam, and India, with Shenzhen and Dongguan anchoring hardware component flows and Hanoi-Bac Ninh corridor absorbing textile and electronics migration. Semiconductor chips, rare earth magnets, and industrial plastics constitute critical input dependencies. Single-source vulnerability runs through Taiwan Strait logistics chokepoints. Distribution runs through platform-integrated fulfillment networks with customs pre-clearance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded finance capacity constraints prop platform pricing power, as RBI licensing requirements and SAMR data localization mandates limit fintech entrants capable of offering integrated trade credit.
For Market Incumbents: Deepen captive fulfillment infrastructure in Vietnam's northern industrial zones before greenfield demand crystallizes around established competitors. Acquire specialized customs clearance technology providers to defend against cross-border tax compliance fragmentation. Vertical integration into warehouse robotics addresses labor cost escalation threatening margin structures. For New Entrants and Emerging Players: Begin with Japan's SME supplier digitization push, where METI electronic invoicing mandates create urgent replacement demand without entrenched platform loyalty. Target machinery sector procurement officers in Aichi prefecture requiring human-negotiated performance guarantees. Deploy pre-certified invoice formatting as the initial go-to-market wedge. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing embedded finance licenses given India's PLI scheme accelerating supplier digitization mandates. Five-to-ten year viability favors platform operators with captive logistics networks rather than pure software plays. Monitor RBI payment aggregator licensing velocity as the inflection signal for fintech competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Integration | Trade credit tools anchored in JD.com's fulfillment workflows capture margin pools banks cannot access. |
| API-First ERP Connectivity | Direct SAP and Oracle integration eliminates procurement intermediary layers in Dongguan manufacturing clusters. |
| Cross-Border Customs Pre-Clearance | Alibaba's integrated trade finance and customs tools compress delivery windows for Southeast Asian buyers. |
| Same-Day Fulfillment Network Expansion | Warehouse density investments in tier-one Chinese cities establish benchmarks exported to Vietnam and Indonesia. |
| Vertical Marketplace Specialization | IndiaMart's SME-focused digitization captures supplier networks too fragmented for horizontal platform consolidation. |
Study Parameters
Multi-period observation of procurement platform transaction velocities, embedded finance adoption curves, and logistics network density anchored the trend analysis, supplemented by interviews with B2B platform product managers, ERP integration specialists, electronics manufacturing procurement directors, and trade finance operations leads. Secondary validation drew from SAMR regulatory filings, RBI payment aggregator licensing records, METI electronic invoicing protocol documentation, and customs trade flow databases. Bottom-up transaction volume modeling and top-down market sizing triangulated final estimates.
Input-output matrices mapped platform revenue drivers against manufacturing demand signals, segmentation dimensions across product type, end user category, sales channel, and service layer, and regional adoption clusters throughout the projection horizon. CAGRs derived from logistics infrastructure investment trajectories, supplier digitization mandate compliance timelines, and cross-border payment volume elasticity. Forecast inputs incorporated API penetration rates in legacy ERP installations and electronic invoicing regulatory rollout schedules.
Underlying measurement precision varies by segment; payment solutions and online platforms carry tighter precision than direct sales channels where human negotiation resists quantification. Forecasts reflect assumptions around regulatory enforcement consistency and logistics network buildout pacing. Periodic stress-testing of base assumptions is recommended given tariff exposure and data sovereignty requirement evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market