
 E-Tailing Solutions Market | 2026-2036
E-Tailing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
E-Tailing Solutions Market Foresight
Merchant sourcing of e-commerce infrastructure is restructuring from single-vendor suites toward modular, best-of-breed stacks. Shopify Inc. anchors small-business onboarding through templated storefronts and embedded payment flows. Salesforce, Inc. competes in enterprise segments by extending its CRM data layer into order management and AI-driven personalization. Adobe Inc. differentiates through creative-to-commerce workflows that tie content production directly to storefront performance analytics.
E-tailing solutions encompass software platforms, cloud infrastructure, and payment orchestration layers that enable digital storefront operation, inventory synchronization, and transaction processing across multiple customer touchpoints. These systems typically integrate API-first architectures with sub-100-millisecond checkout latency to support high-conversion mobile commerce. The clothing segment within product type categories generates the deepest margin pools due to return-rate complexity and size-variation logistics, while the mobile apps sales channel is capturing the fastest growth as in-app checkout reduces cart abandonment versus browser-based flows. Digital wallet payment methods now dominate transaction volume in Asia-Pacific markets, displacing traditional card-on-file systems.
The Federal Trade Commission in the United States enforces consumer protection standards that shape refund policy transparency and subscription billing disclosures, while the EU AI Act imposes algorithmic accountability requirements on product recommendation engines deployed in European jurisdictions. India's Reserve Bank regulates payment aggregator licensing, creating compliance barriers for foreign fintech entrants seeking merchant acquisition share. Stakeholders must monitor how divergent data-localization mandates across Brazil, India, and the European Union fragment cloud architecture strategies and inflate operational redundancy costs.
Market Dynamics
Merchant adoption of composable commerce architectures is fragmenting vendor lock-in patterns, forcing platform providers to expose deeper API functionality and interoperability layers to retain enterprise accounts.
Growth Catalysts
- GDPR and state-level privacy statutes:California's CCPA and Virginia's CDPA mandate granular consent management, expanding demand for customer data platforms with built-in governance tooling.
- Headless commerce APIs:Retailers decouple frontend presentation from backend order management, enabling faster storefront iteration without replatforming costs.
- India's PLI scheme for electronics manufacturing:Domestic production incentives reduce hardware import dependency for fulfillment infrastructure, lowering total cost of ownership for merchant onboarding.
Market Restraints
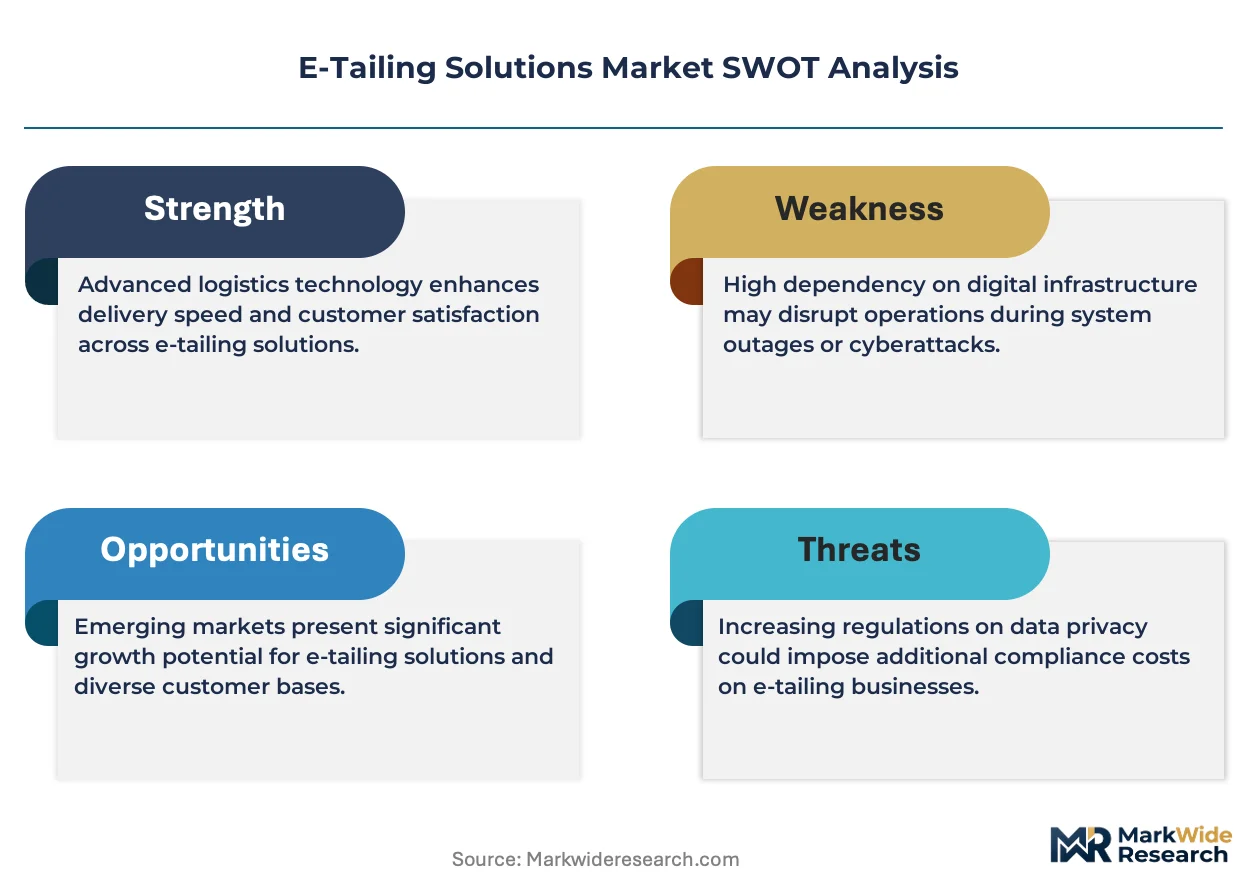
- Cloud infrastructure concentration:Hyperscaler dominance in compute and storage layers creates single-point-of-failure exposure for multi-tenant e-tailing platforms during regional outages.
- Payment aggregator licensing:India's RBI mandates net-worth requirements and data localization for foreign fintech entrants, delaying market entry timelines by 18-24 months.
- Technical debt in legacy ERP integrations:Batch-synchronization protocols between modern storefronts and decades-old inventory systems introduce latency that degrades real-time stock accuracy.
Strategic Opportunities
- Brazil's PIX instant payment rails:Central bank infrastructure enables zero-interchange checkout flows that undercut card network economics for high-volume merchants.
- AI-driven visual search:Computer vision convergence with mobile camera interfaces reduces text-based query friction in fashion and home décor verticals.
- Social commerce livestreaming:Embedded checkout within video platforms captures impulse purchase behavior that traditional product pages fail to convert.
Industry Challenges
- API security talent scarcity:Penetration testing and OAuth implementation expertise commands premium compensation, constraining mid-market platform expansion.
- Cross-border VAT compliance automation:Real-time tax calculation across 160+ jurisdictions requires continuous regulatory monitoring that fragments engineering roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Tailing Solutions Market |
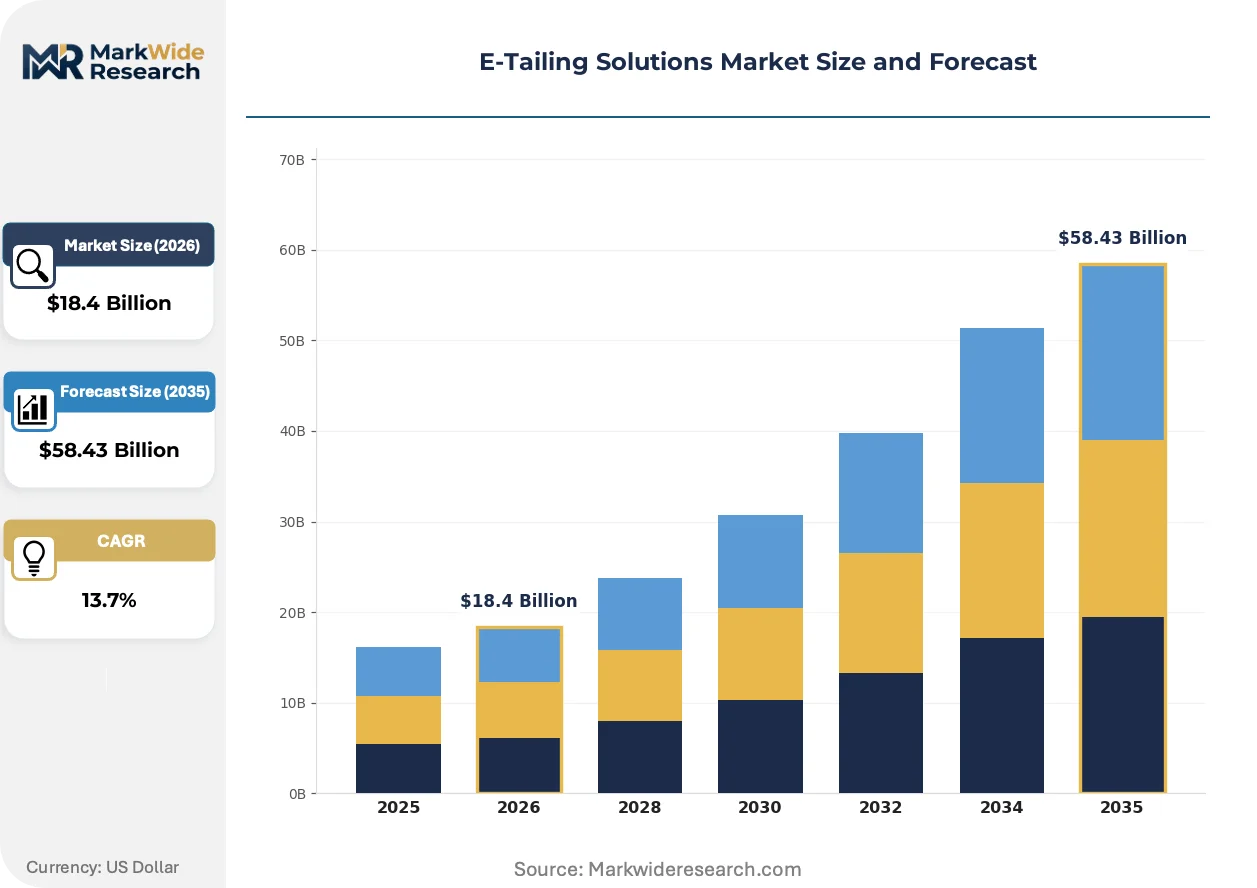
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $58.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Home Goods, Beauty Products Customer Type: Individual Consumers, Small Businesses, Large Enterprises, Non-profits Sales Channel: Online Marketplaces, Direct-to-Consumer, Social Media, Mobile Apps Payment Method: Credit Card, Digital Wallet, Bank Transfer, Cash on Delivery |
| Companies Covered | Shopify Inc., Salesforce, Inc., Adobe Inc., BigCommerce Holdings, Inc., Oracle Corporation, SAP SE, Wix.com Ltd., Squarespace, Inc., Automattic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Tailing Solutions Market Shifts & Advancements
Edge computing deployment at points of presence is compressing checkout latency thresholds, redefing performance benchmarks for conversion optimization in mobile-first markets.
Serverless functions at the network edge is rewriting how merchants handle peak traffic events. Flash-sale retailers in Southeast Asia deploy auto-scaling compute within 50 kilometers of cellular towers. This architecture eliminates origin-server roundtrips that previously caused cart abandonment during inventory drops.
The EU AI Act imposes algorithmic accountability requirements on product recommendation engines deployed in European jurisdictions. E-tailing platforms must document training data provenance and enable human override for automated decisions. Fashion marketplaces with AI-curated feeds face the steepest compliance retrofit costs.
Buy-now-pay-later unbundling from traditional credit products is disrupting checkout financing. Younger demographics in Germany and the Netherlands abandon card-on-file enrollment for installment options embedded directly at payment selection. Merchant acquirers respond by white-labeling lending infrastructure rather than building proprietary credit stacks.
E-Tailing Solutions Market Segmentation
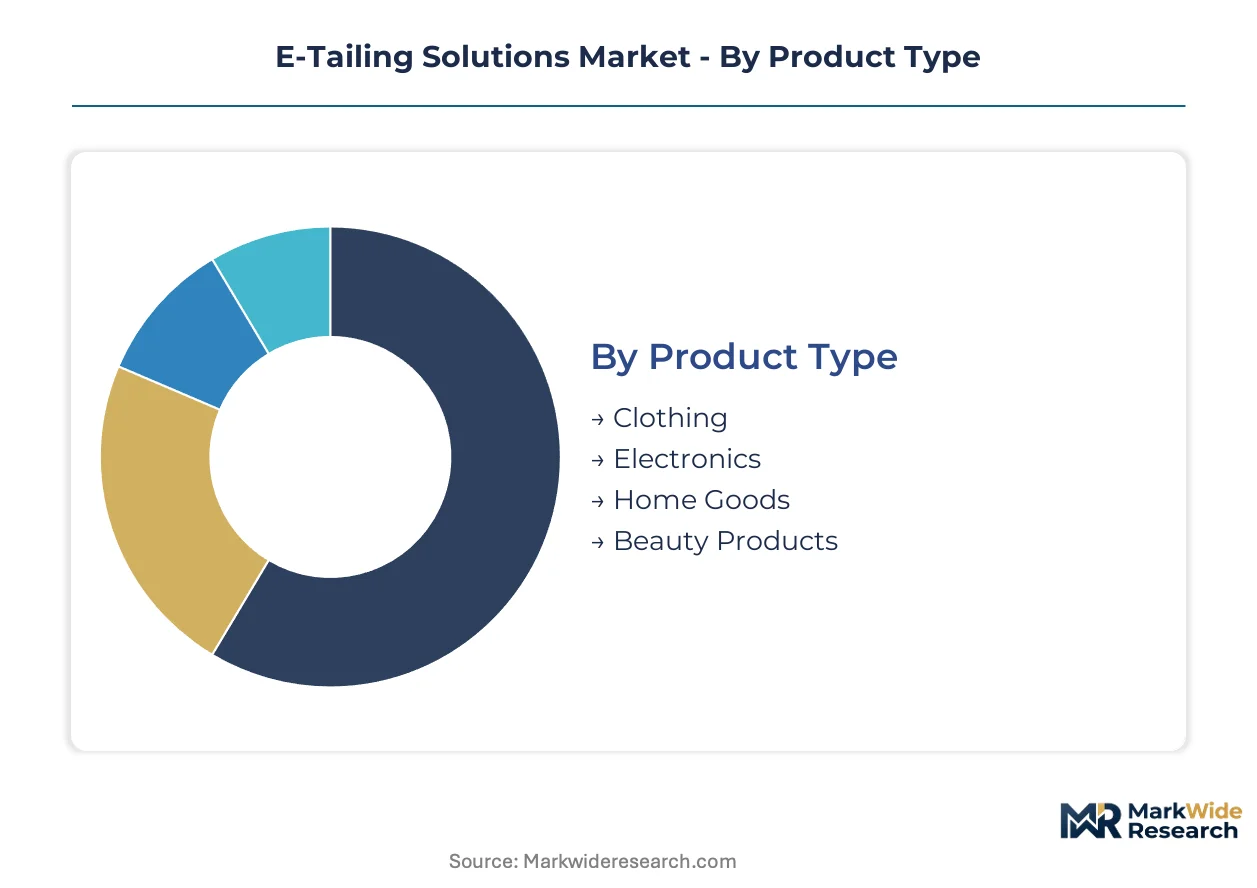
E-tailing solutions segment along four distinct axes that determine platform architecture requirements and margin capture potential. Product type dictates fulfillment complexity, while sales channel selection shapes checkout latency tolerances and API integration depth.
Product Type:
Specification intensity varies dramatically across physical goods categories, with dimensional variability and return rates driving divergent backend requirements.
- Clothing:Size-variation logistics and elevated return rates demand sophisticated inventory synchronization and reverse-logistics APIs. India's garment exporters leverage PLI scheme incentives to deploy sizing algorithms that reduce fit-related returns by integrating body-measurement capture into mobile checkout flows.
- Electronics:High-value, low-velocity transactions require warranty orchestration and serial-number tracking at SKU level. German retailers face EU AI Act documentation requirements when deploying automated product recommendation engines for consumer electronics categories.
- Home Goods:Bulky freight economics favor regional fulfillment node placement over centralized distribution.
- Beauty Products:Regulatory serialization for cosmetics compliance adds batch-tracking overhead to inventory systems.
Clothing leads on scale; mobile-optimized electronics capture momentum fastest.
Customer Type:
Organizational scale determines procurement authority, integration budget, and compliance exposure across data governance frameworks.
- Individual Consumers:Friction-sensitive checkout experiences with sub-100-millisecond latency requirements. California's CCPA mandates granular consent management for California-based shoppers, forcing storefronts to embed preference centers directly into account creation flows.
- Large Enterprises:Multi-tenant architectures with SSO federation and custom SLA negotiations. India's RBI data-localization requirements for payment aggregators create 18-24 month entry delays for foreign fintechs serving enterprise merchant portfolios.
- Small Businesses:Template-driven onboarding with limited API customization budgets.
- Non-profits:Donation-specific tax receipt automation and reduced transaction fee structures.
Large enterprises dominate revenue concentration; individual consumers expand most quickly.
Sales Channel:
Touchpoint architecture determines frontend-backend coupling decisions and conversion optimization strategies.
- Mobile Apps:Native SDK implementations with biometric authentication and push-notification re-engagement. Southeast Asian flash-sale retailers deploy edge-computing nodes within 50 kilometers of cellular towers to eliminate origin-server roundtrips during inventory drops.
- Social Media:Embedded checkout within content feeds capturing impulse purchase behavior. Brazil's PIX instant payment rails enable zero-interchange flows that undercut card network economics for high-volume social commerce merchants.
- Online Marketplaces:Multi-seller inventory aggregation with unified fulfillment orchestration.
- Direct-to-Consumer:Brand-controlled data layers enabling first-party personalization without intermediary constraints.
Online marketplaces lead on scale; social commerce climbs the fastest.
Payment Method:
Settlement infrastructure selection shapes working capital cycles, fraud exposure, and cross-border expansion feasibility.
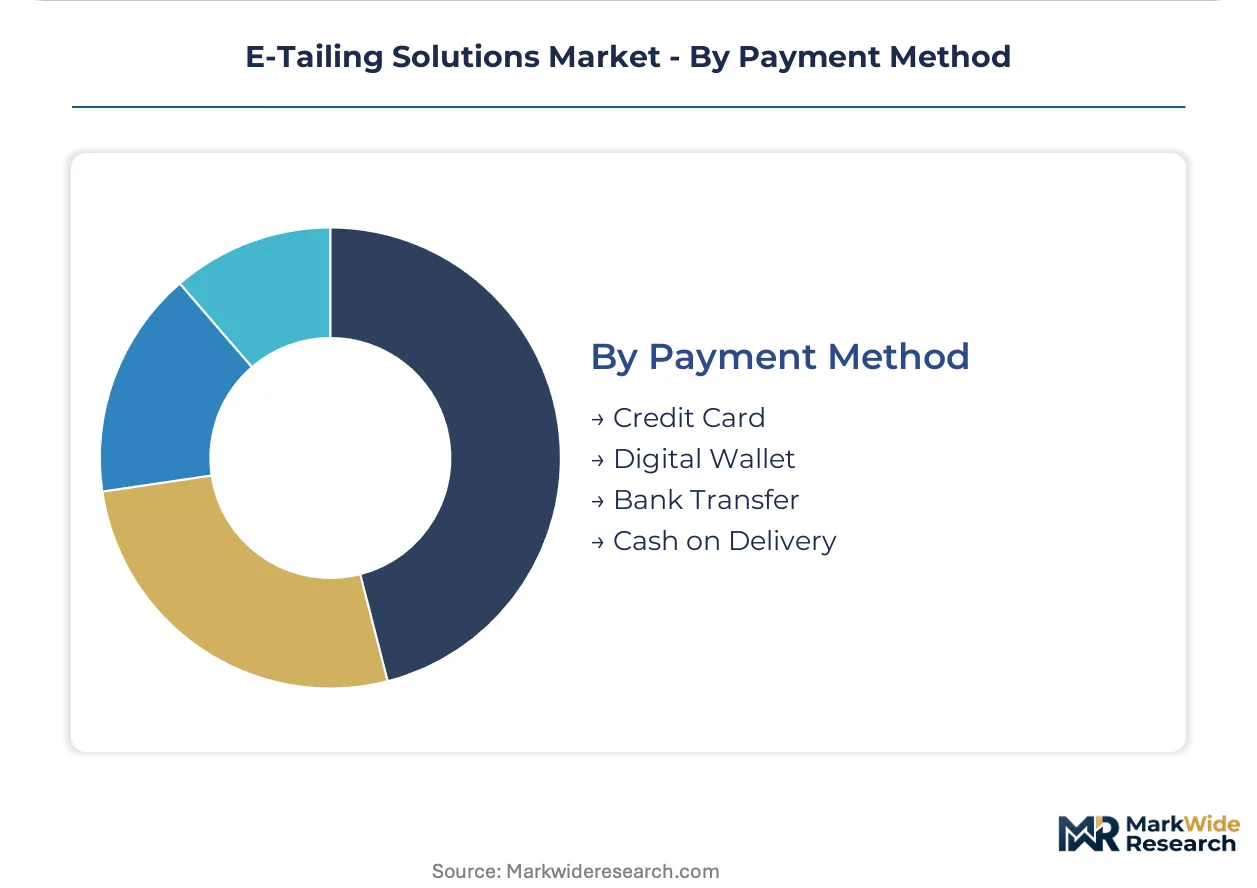
- Digital Wallet:Tokenized credentials with one-tap authorization reducing cart abandonment versus card-on-file enrollment. Asia-Pacific markets have displaced traditional card systems as wallet penetration saturates urban consumer bases.
- Credit Card:Interchange-funded rewards programs retaining preference among high-ticket purchasers in North American and European markets.
- Bank Transfer:Lower processing costs favoring B2B and subscription billing use cases with established customer relationships.
- Cash on Delivery:Trust bridge for underbanked segments in emerging markets with limited card penetration.
Credit card retains revenue leadership; digital wallet gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's Koramangala-Whitefield corridor anchors merchant technology adoption, hosting India's densest cluster of direct-to-consumer brand headquarters and SaaS development centers.
United States
California's CCPA and Virginia's CDPA drive demand for consent-management platforms with embedded governance tooling. The FTC enforces refund policy transparency standards that shape subscription billing architecture. San Francisco Bay Area venture deployment concentrates in headless commerce API startups decoupling frontend presentation from backend systems.
India
The RBI's payment aggregator licensing mandates net-worth requirements and data localization for foreign fintech entrants. Domestic PLI scheme incentives reduce hardware import dependency for fulfillment infrastructure. Mumbai's BKC financial district hosts merchant acquisition teams targeting garment exporters deploying sizing algorithms into mobile checkout flows.
Germany
Younger demographics abandon card-on-file enrollment for installment options embedded at payment selection. The EU AI Act imposes algorithmic accountability requirements on automated product recommendation engines. Berlin's Friedrichshain startup cluster specializes in buy-now-pay-later infrastructure white-labeling for merchant acquirers.
Brazil
Central bank PIX instant payment rails enable zero-interchange checkout flows undercutting card network economics. Social commerce livestreaming captures impulse purchase behavior through embedded checkout within video platforms. São Paulo's Pinheiros district concentrates flash-sale retailers deploying edge-computing nodes within 50 kilometers of cellular towers.
United Kingdom
GDP-level privacy statutes mandate granular consent management expanding customer data platform procurement. Fashion marketplaces with AI-curated feeds face steep compliance retrofit costs under algorithmic accountability requirements. London's Shoreditch corridor hosts composable commerce vendors exposing deeper API functionality to retain enterprise accounts.
E-Tailing Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular API-first architectures that fragment vendor lock-in patterns. The vendor landscape stratifies across three functional tiers: CRM-anchored enterprise suites, template-driven small-business platforms, and creative-to-commerce workflow specialists. Consolidation pressure intensifies as composable commerce architectures force incumbents to expose interoperability layers. Dominant competitive moves include strategic partnerships expanding payment orchestration coverage and portfolio diversification into AI-driven personalization engines.
Within the enterprise-suite tier, Salesforce, Inc. and Oracle Corporation exemplify CRM-data-layer extension strategies that embed order management into existing customer relationship infrastructure. Adobe Inc. occupies a distinct position bridging creative production tools with storefront performance analytics. Shopify Inc. anchors the small-business vector through templated onboarding and embedded payment flows. These three archetypes—enterprise CRM extension, creative-commerce convergence, and SMB templated entry—collectively map the competitive structure without exhaustively cataloging participant strategies.
| Leading Market Players |
|---|
| Shopify Inc. |
| Salesforce, Inc. |
| Adobe Inc. |
| BigCommerce Holdings, Inc. |
| Oracle Corporation |
| SAP SE |
| Wix.com Ltd. |
| Squarespace, Inc. |
| Automattic |
| Others |
Supply & Pricing Matrix
Merchant demand for sub-100-millisecond checkout latency is compressing infrastructure procurement toward edge-computing nodes, forcing cloud providers to deploy localized points of presence and reshaping cost-to-serve economics across tiered service levels.
Pricing Analysis
Input-cost pass-through from hyperscaler compute and storage tariffs dominates SaaS-tiered subscription models, with platform providers segmenting across premium API-access tiers, standard self-service bundles, and economy template-only entry points. Price differentiation rests on customization depth and SLA guarantees, with enterprise accounts commanding dedicated infrastructure pools. Pricing pressure stems from modular API competition eroding suite-bundle premiums. Small businesses exhibit highest price sensitivity, while large enterprises prioritize latency performance over per-seat costs.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts component sourcing to audited hyperscaler regions, concentrating cloud infrastructure supply across the United States, Ireland, and Singapore. Raw material dependencies center on advanced silicon for edge servers, submarine cable capacity for intercontinental latency, and renewable energy contracts for carbon-neutral compute pledges. Single-source vulnerability in Taiwan semiconductor fabrication creates concentration risk for merchant hardware provisioning. Distribution runs through direct API provisioning and channel partner systems integrators serving mid-market verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in e-tailing solutions derives from edge-computing deployment cost curves flattening and enterprise buyers migrating toward premium API-access tiers with dedicated infrastructure guarantees.
For Market Incumbents: Extend API interoperability layers to defend against composable commerce fragmentation threatening suite-bundle retention. Salesforce and Oracle must deepen vertical-specific order-management modules before headless entrants capture enterprise replatforming cycles. Certification investment in EU AI Act documentation tooling creates switching-cost barriers for fashion marketplace accounts. For New Entrants and Emerging Players: Social commerce livestreaming infrastructure presents the most penetrable white-space target, with embedded checkout SDKs capturing impulse purchase behavior that incumbent product pages fail to convert. India's garment exporter segment offers underserved demand for sizing-algorithm APIs that reduce fit-related returns. A direct-to-developer go-to-market through GitHub-integrated documentation accelerates technical evaluation cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with API-first personalization engine specialists serving GDPR-mandated consent-management workflows. Long-term viability across the analysis window favors vendors with demonstrated RBI payment-aggregator licensing navigation in India. The signal to watch is central-bank instant-payment rail adoption velocity as a predictor of checkout-finance infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Expansion | São Paulo and Bengaluru deployments compress checkout latency below 50 milliseconds for flash-sale retailers. |
| EU AI Act Compliance Tooling | Documentation automation for algorithmic accountability reduces fashion marketplace retrofit costs by streamlining audit trails. |
| PIX Payment Rail Integration | Brazil's zero-interchange infrastructure undercuts card network economics for high-volume social commerce merchants. |
| Headless Commerce API Launch | Frontend-backend decoupling enables Southeast Asian retailers to iterate storefronts without replatforming investments. |
| PLI Scheme Hardware Localization | Domestic fulfillment infrastructure production in India reduces total cost of ownership for merchant onboarding. |
Research Methodology
Multiple input streams — primary interviews with CTOs and platform engineers, secondary validation through SEC filings and hyperscaler capex disclosures, and customs records for fulfillment hardware trade flows — were reconciled to construct segment-level demand estimates. Conversations with merchant acquisition leads at payment aggregators, integration specialists at systems integrators, and regulatory affairs directors at multinational retailers informed adoption-timing assumptions. Bottom-up merchant-count modeling and top-down cloud infrastructure spend allocation were triangulated to cross-check volume projections.
Data-stream reconciliation across deployment model, organization size, vertical specialization, and regional adoption pattern enabled granular CAGR derivation through segmented growth-rate blending. The analytical framework incorporated API call volume trajectories, edge-computing node deployment schedules, and central-bank instant-payment rail adoption curves as industry-specific forecast inputs across the projection horizon.
Regulatory enforcement divergence, hyperscaler regional outage events, and cross-border data-localization mandate fragmentation are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in RBI payment-aggregator licensing timelines or EU AI Act implementation severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
South America E-Commerce Apparel Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Global Shopping Cart Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market