
 Couture Millinery Market | 2026-2036
Couture Millinery Market Size, Share, and Industry Trends Forecast 2026-2036
Couture Millinery Market Insights
The premium couture millinery tier is rebalancing away from mass-accessory channels toward appointment-only ateliers and private trunk shows. Philip Treacy leverages its Royal Warrant relationships to sustain exclusivity in ceremonial commissions. Stephen Jones OBE anchors the bridge between avant-garde runway placement and commercial viability through selective department store partnerships. Rachel Trevor Morgan competes on hand-blocked straw specialization, particularly for garden-party and wedding segments.
Couture millinery denotes hand-sculpted headwear produced in limited quantities, typically employing traditional blocking techniques on wooden forms with materials such as sinamay, parasisal straw, or fur felt shaped at temperatures between 80°C and 120°C. Its primary commercial purpose centers on ceremonial, bridal, and high-fashion editorial applications where standardized production cannot replicate individual fit or aesthetic specificity. Fascinators and wide brim hats capture the dominant margin pools, with fascinators benefiting from royal event visibility and wide brim hats commanding sustained bridal demand across spring and summer collections. Cloche hats occupy a mature niche rooted in vintage design style preferences, while beanies remain peripheral to true couture positioning despite material overlap.
The European Union's REACH framework and ECHA chemical restrictions shape material sourcing decisions for ateliers exporting into member states, particularly on azo dyes and formaldehyde-based stiffeners. The UK's BSI standards and residual alignment with CE marking protocols create dual compliance obligations for British-based houses serving both domestic and continental clientele. Stakeholders must monitor evolving sustainability disclosure requirements under CSRD-adjacent supply chain mandates, as fiber traceability becomes a decisive procurement criterion for luxury buyers.
Market Dynamics
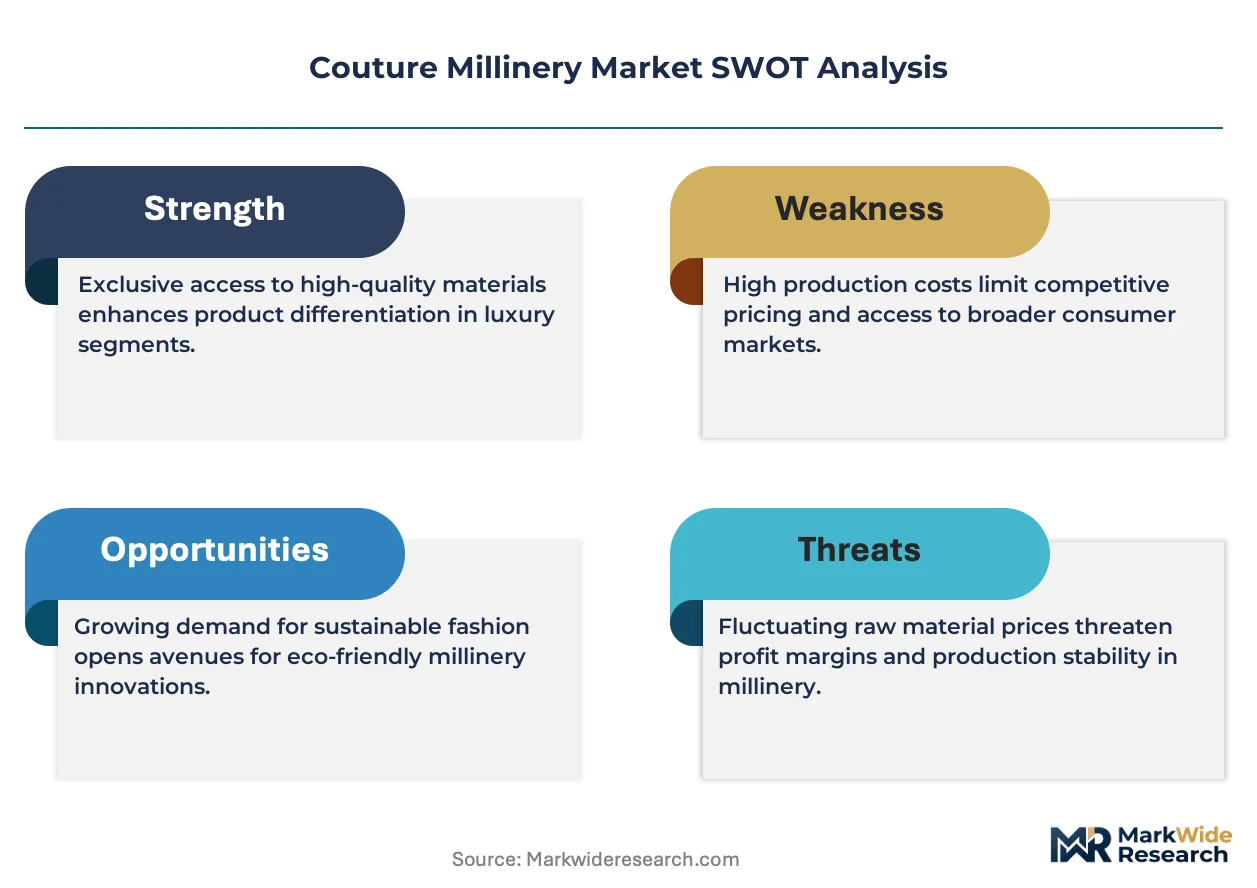
REACH compliance in the European Union is forcing ateliers to abandon azo dyes and formaldehyde-based stiffeners, triggering a wholesale reconfiguration of fiber sourcing toward natural alternatives and certified organic suppliers.
Growth Catalysts
- Bridal ceremonial demand:Western European wedding clients commission bespoke fascinators and wide-brim pieces at elevated frequencies, particularly for spring-summer garden ceremonies.
- Royal ceremonial visibility:State occasions and coronation events sustain collector appetite for hand-blocked straw and sinamay constructions in the United Kingdom.
- CSRD-adjacent disclosure mandates:Fiber traceability requirements under evolving EU supply-chain transparency rules are accelerating certified organic procurement among luxury buyers.
Market Restraints
- Parasisal straw supply concentration:Premium hand-woven straw originates from a narrow band of Ecuadorian and Madagascan cooperatives, exposing ateliers to climate-driven harvest volatility.
- Fur felt input costs:Rabbit and hare felt prices fluctuate with agricultural commodity cycles, compressing margin pools on winter-weight ceremonial pieces.
- REACH chemical restrictions:ECHA prohibitions on specific dye classes force reformulation of archival color palettes, extending production timelines for heritage houses.
Strategic Opportunities
- Private trunk show expansion:Appointment-only ateliers in London and Paris are bypassing department store consignment to capture full margin on direct client relationships.
- Digital measurement integration:3D head-scanning tools paired with traditional wooden blocking forms enable remote bespoke fitting for dispersed bridal clientele.
- Residual UK-EU dual compliance:British houses mastering both BSI standards and CE marking protocols can service cross-channel collectors without regulatory friction.
Industry Challenges
- Master blocker succession gaps:The craft knowledge for hand-sculpting sinamay at 80°C to 120°C temperature thresholds concentrates among aging artisans with limited apprentice pipelines.
- Dual certification timelines:Ateliers exporting from Britain into EU member states must navigate parallel BSI and REACH documentation, extending order-to-delivery cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Couture Millinery Market |
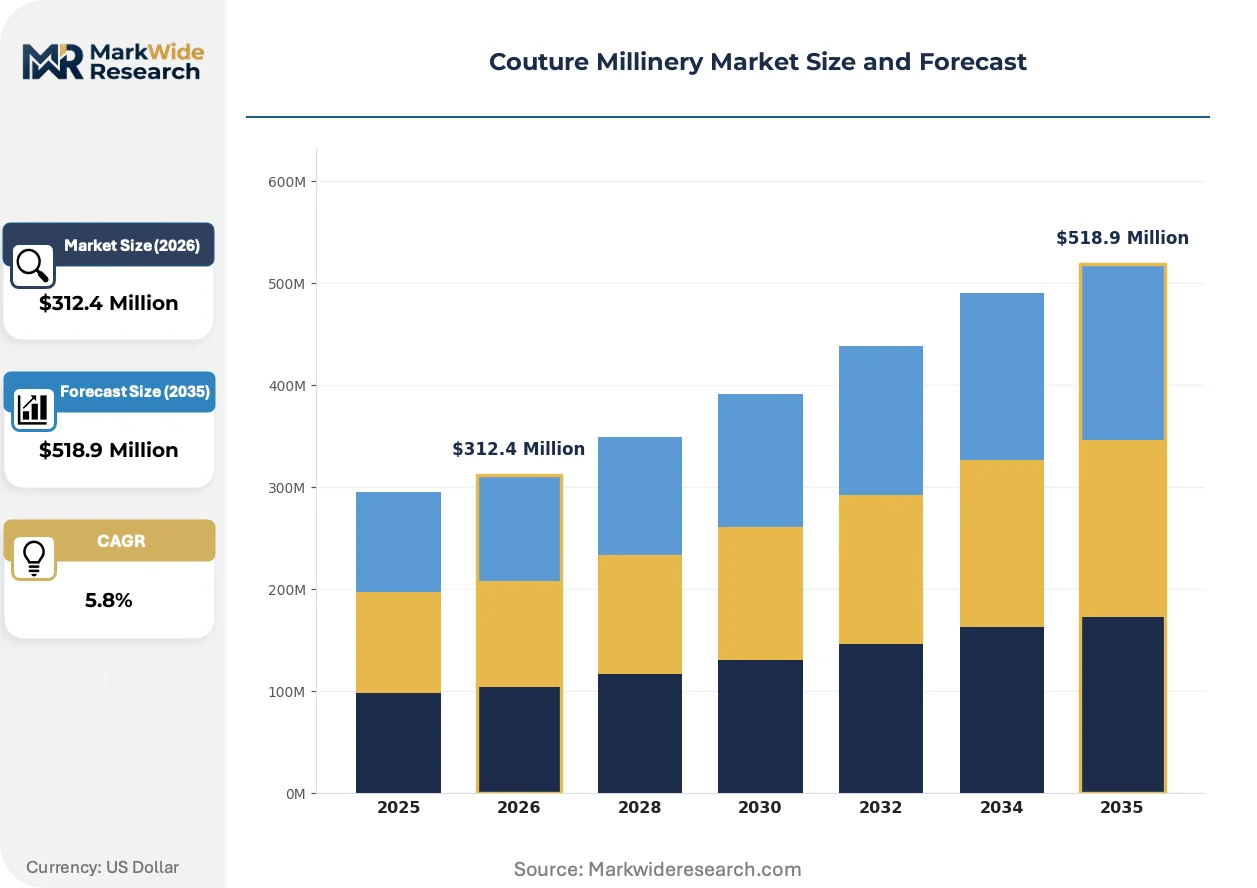
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fascinators, Wide Brim Hats, Cloche Hats, Beanies Material: Felt, Straw, Fabric, Leather Design Style: Classic, Modern, Vintage, Bohemian Customer Type: Brides, Fashion Enthusiasts, Performers, General Public |
| Companies Covered | Philip Treacy, Stephen Jones OBE, Jane Taylor London, Rachel Trevor Morgan, Diana Cavagnaro, Leah C, Suzanne Couture, Emma Moscow, Sarah Cant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Couture Millinery Market Trends and Innovations
Digital fabrication methods are penetrating hand-craft domains without displacing core artisanal techniques, creating hybrid production models that preserve authenticity while compressing measurement and revision cycles.
Laser-cut sinamay layering is electrifying structural possibilities for architectural fascinator designs. Avant-garde bridal boutiques in Milan and London are adopting these precision-cut foundations at accelerated pace. The technology is electrifying demand for geometric, gravity-defying silhouettes previously unattainable through hand-fraying alone.
REACH authorization requirements for chromium-based tanning agents are tightening fur felt processing standards across EU member states. Ateliers dependent on traditional stiffening methods face forced migration to vegetable-based alternatives. British houses with residual CE marking alignment must reformulate inventory or risk market exclusion.
Collector purchasing is gravitating toward provenance-documented pieces with fiber-origin certificates. Private clients now request batch-specific straw harvest documentation and organic dye certification before commissioning. This verification-driven preference shift is most pronounced among wedding-party buyers in France and ceremonial collectors in the United Kingdom.
Couture Millinery Market Segmentation
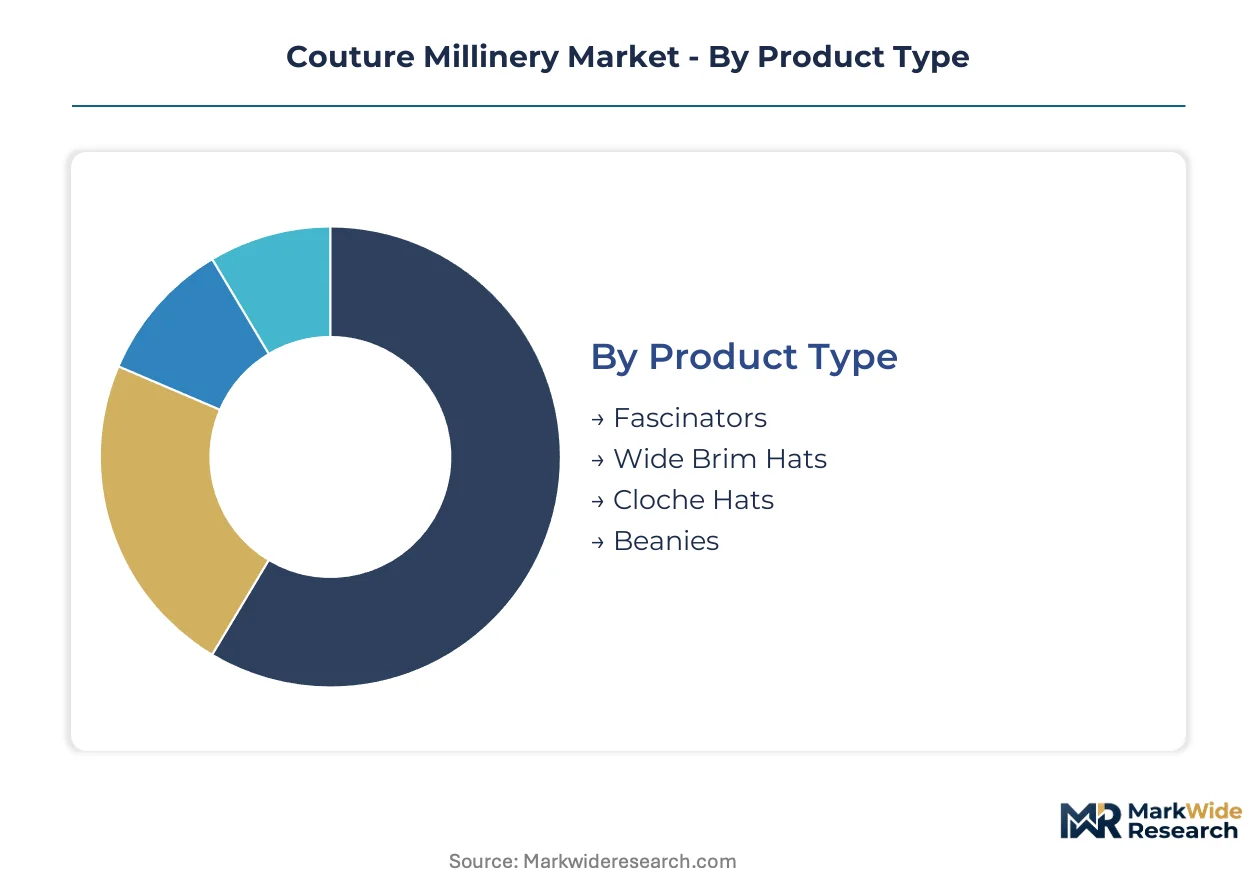
Couture millinery purchasing decisions pivot on occasion specificity and material provenance rather than price elasticity. Buyers commission pieces through discrete channels—bridal appointments, ceremonial trunk shows, or editorial placement—each demanding distinct construction protocols and compliance documentation.
Product Type:
Occasion dictates silhouette selection, with ceremonial visibility and photographic permanence driving margin stratification across form factors.
- Wide Brim Hats:Hand-blocked parasisal straw constructions dominate spring-summer bridal commissions across Western European garden ceremonies. United Kingdom ateliers report sustained demand for royal-occasion-adjacent pieces requiring documented fiber origin and REACH-compliant finishing.
- Fascinators:Architectural sinamay frameworks, increasingly laser-cut for geometric precision, anchor ceremonial and race-day segments. British collectors commission these for state occasion visibility, with ECHA-compliant vegetable stiffeners replacing formaldehyde-based alternatives.
- Cloche Hats:Vintage-revival felt constructions occupy mature demand among period-specific collectors and theatrical costumiers.
- Beanies:Knit forms remain peripheral to true couture positioning despite material overlap, serving primarily as bridge-tier accessories.
Wide brim hats lead on scale; fascinators lead on momentum.
Material:
Procurement is shifting toward traceable natural fibers as regulatory pressure compounds climate-driven supply volatility.
- Straw:Parasisal and sinamay hand-weaving concentrates in Ecuadorian and Madagascan cooperatives, exposing ateliers to harvest variability. Wedding-party buyers in France now mandate batch-specific documentation before commissioning.
- Felt:Rabbit and hare fur felt prices fluctuate with agricultural commodity cycles, compressing margins on winter-weight ceremonial pieces. REACH authorization requirements for chromium tanning agents are forcing migration to vegetable-based processing.
- Fabric:Silk and organza constructions serve avant-garde editorial placement and theatrical performance segments.
- Leather:Exotic and vegetable-tanned variants occupy niche demand among fashion-forward collectors seeking structural rigidity.
Straw commands volume concentration; felt faces the steepest reformulation pressure.
Design Style:
Aesthetic positioning determines atelier-client matching, with archival houses and experimental studios occupying non-overlapping commissioning channels.
- Classic:Timeless silhouettes with hand-sculpted blocking on wooden forms sustain royal warrant holders and heritage houses. United Kingdom ceremonial collectors prioritize these for provenance and resale value.
- Modern:Architectural minimalism and laser-cut precision attract Milan and London bridal boutiques seeking statement pieces for editorial placement.
- Vintage:Period-accurate reconstructions serve theatrical costumiers and cloche-hat collectors with specific era requirements.
- Bohemian:Unstructured fabric and mixed-media constructions appeal to festival-attending fashion enthusiasts outside formal ceremonial channels.
Classic styling retains price authority; modern design climbs fastest in bridal acquisition.
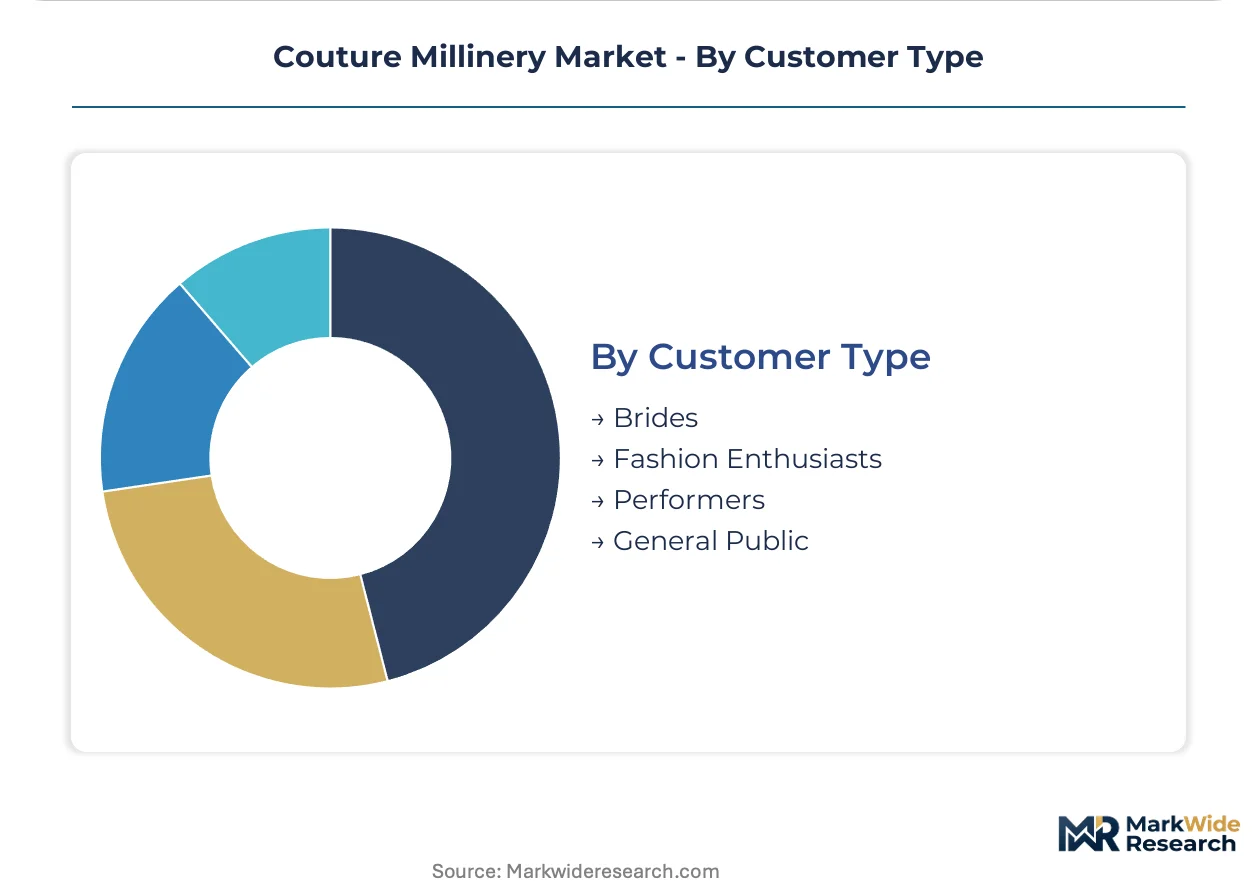
Customer Type:
Commissioning channel and documentation requirements vary sharply across buyer categories, dictating atelier staffing and compliance investment.
- Brides:Bespoke fitting cycles spanning 3D head-scanning and traditional wooden blocking dominate spring-summer demand. Western European wedding clients now require REACH-compliant dye certification and organic fiber traceability.
- Fashion Enthusiasts:Collector purchasing gravitates toward provenance-documented pieces with batch-specific straw harvest documentation, particularly pronounced in France and the United Kingdom.
- Performers:Theatrical and editorial costumiers commission avant-garde constructions prioritizing visual impact over wearability.
- General Public:Occasional purchasers access bridge-tier pieces through selective department store partnerships, though true couture positioning remains appointment-only.
Brides concentrate revenue density; fashion enthusiasts drive documentation premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master blockers and artisan apprentices cluster in London and Paris, anchoring the craft's geographic concentration. Royal ceremonial traditions sustain demand density across Western European capitals. Regulatory divergence between post-Brexit Britain and EU member states reshapes atelier compliance investments.
United Kingdom
Royal warrant holders command collector premiums for hand-blocked ceremonial pieces. BSI standards and residual CE marking obligations create dual documentation burdens for exporting houses. London's Mayfair and Belgravia districts concentrate appointment-only ateliers serving state occasion clientele.
France
Parisian bridal boutiques drive laser-cut sinamay adoption for avant-garde garden ceremonies. ANSM and CNIL oversight extends to cosmetic-grade dye certification for headpiece finishing. The Marais and Saint-Germain-des-Prés clusters host heritage maisons and experimental studios in parallel.
Italy
Milan's editorial placement networks sustain demand for architectural fascinator constructions. REACH alignment through national chemical regulators governs azo dye prohibitions for export-bound ateliers. The Lombardy region concentrates silk and organza suppliers serving theatrical costumiers.
Germany
Baden-Württemberg's precision manufacturing culture supports digital measurement tool integration for remote bespoke fitting. KBA-adjacent quality frameworks influence artisanal production standards for cross-border trade. Berlin's design academies feed apprentice pipelines for traditional blocking techniques.
Spain
Andalusian wedding traditions sustain wide-brim straw demand for spring-summer ceremonial cycles. National alignment with ECHA chemical restrictions shapes vegetable-stiffener formulation for sinamay constructions. Barcelona's fashion week placement generates editorial visibility for emerging milliners.
Couture Millinery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the couture millinery landscape. Heritage houses maintaining wooden blocking foundries and master artisan rosters face pressure from digitally native studios leveraging 3D measurement and remote fitting. The market stratifies into three archetypes: royal warrant holders with ceremonial exclusivity, bridge-tier ateliers with selective department store placement, and experimental studios prioritizing editorial visibility over commercial scale. Competitive moves center on private trunk show expansion to capture full margin and backward integration into certified fiber sourcing to satisfy traceability mandates.
Within the heritage house tier, Philip Treacy and Stephen Jones OBE exemplify warrant-backed exclusivity, while Rachel Trevor Morgan occupies a position defined by hand-blocked straw specialization. These London-based entities anchor distinct competitive vectors—ceremonial state commissions, avant-garde runway placement, and wedding-segment craftsmanship respectively—without overlapping client acquisition channels.
| Leading Market Players |
|---|
| Philip Treacy |
| Stephen Jones OBE |
| Jane Taylor London |
| Rachel Trevor Morgan |
| Diana Cavagnaro |
| Leah C |
| Suzanne Couture |
| Emma Moscow |
| Sarah Cant |
| Others |
Pricing and Supply Chain Analysis
Laser-cut sinamay fabrication is compressing measurement-to-delivery cycles while concentrating premium-tier production among ateliers with capital equipment access, simultaneously reducing per-unit labor hours and widening the gap between digitally enabled houses and hand-only competitors. REACH-driven reformulation costs are flowing through to commissioning prices, with heritage houses absorbing margin compression on archival color palettes while modern studios pass vegetable-stiffener premiums to bridal clients.
Pricing Analysis
Appointment-only trunk shows versus department store consignment represents the fundamental service split, with bundled bespoke fitting commanding three-to-five multiples over unbundled ready-to-wear bridge pieces. Price differentiation rests on certification grade—REACH-compliant dye documentation and organic fiber traceability—and customization depth measured in head-scanning precision and blocking revision cycles. Cost compression in mid-tier felt constructions is intensifying because rabbit and hare input prices track agricultural commodity volatility. General-public occasional purchasers exhibit highest price sensitivity, while United Kingdom ceremonial collectors demonstrate lowest elasticity due to provenance and resale-value considerations.
Supply Chain Analysis
Air and sea freight volatility from Ecuadorian and Madagascan cooperatives is amplifying landed cost uncertainty for parasisal straw, with climate-driven harvest variability now the dominant logistics cost driver. Raw material sourcing draws from Ecuador, Madagascar, and United Kingdom fur felt processors, with ateliers dependent on hand-weaving cooperatives and chromium-tanning migration schedules. Single-source vulnerability concentrates in Ecuadorian parasisal harvests exposed to El Niño precipitation patterns. Distribution runs through appointment-only Mayfair and Belgravia ateliers for ceremonial tiers, selective department store partnerships for bridge access, and direct digital commissioning for dispersed bridal clientele.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through digital measurement adoption reducing revision cycles and certified organic procurement capturing documentation premiums from traceability-mandated buyers.
For Market Incumbents: Cement exclusivity through captive straw cooperative partnerships in Ecuador and Madagascar, insulating supply against climate volatility while locking competitor access. Deepen blocking-foundry capacity in London and Paris to compress order-to-delivery timelines against digitally native entrants. Master dual BSI-REACH compliance documentation to service cross-channel collectors without regulatory friction. For New Entrants and Emerging Players: Begin with laser-cut sinamay architectural fascinators for Milan and London bridal boutiques, where editorial placement networks reward geometric precision over heritage blocking credentials. Target remote bespoke fitting for Western European garden-ceremony clients underserved by appointment-only geographic concentration. Pursue direct-to-consumer digital commissioning with 3D head-scanning partnerships to bypass department store consignment margin splits. For Investors and Strategic Acquirers: Valuations sit cheapest among digitally enabled studios with editorial placement traction but unproven ceremonial commission pipelines, offering acquisition entry before royal warrant credibility compounds. Long-term viability favors houses with backward-integrated fiber sourcing and master blocker apprentice pipelines. Watch ECHA authorization timelines for chromium-based tanning agents as inflection signal for vegetable-stiffener formulation leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Private Trunk Show Expansion | Captures full margin through direct client relationships bypassing department store consignment splits. |
| Certified Organic Fiber Sourcing | Satisfies CSRD-adjacent traceability mandates from French wedding-party and UK ceremonial buyers. |
| Digital Measurement Integration | Compresses bespoke fitting cycles through 3D head-scanning paired with traditional wooden blocking forms. |
| Master Blocker Apprentice Pipeline | Secures craft knowledge concentration aging out among 80°C to 120°C temperature threshold specialists. |
| Dual Compliance Documentation Investment | Enables British houses to service EU collectors without REACH-BSI regulatory friction. |
Research Methodology
Coverage spans the United Kingdom, France, Italy, Germany, and Spain, with primary inputs from each market's atelier clusters and regulatory environments. Primary interviews with master blockers, bridal boutique procurement leads, ceremonial collectors, and REACH compliance officers combined with secondary validation from ECHA authorization databases, BSI standards filings, and Ecuadorian cooperative export records. Bottom-up atelier revenue aggregation and top-down ceremonial occasion demand estimation provided triangulation checks.
Rate-of-change decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material provenance, design style archetype, and customer commissioning channel. CAGRs derived from bridged historical atelier output data and forward-looking bridal demographic and ceremonial occasion schedules. Industry-specific inputs incorporated parasisal harvest variability indices and fur felt agricultural commodity price cycles.
Several conditions sit outside the modeled scope, including sudden ECHA chemical class prohibitions, cooperative labor disruptions in Ecuador and Madagascar, and royal ceremonial occasion cancellations. Forecasts reflect assumptions about apprentice pipeline replenishment and digital adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fashion & Accessories
Sustainable Fashion Market
Fashion & Accessories
Personal Accessories Market
Fashion & Accessories
Middle East and Africa Leather Goods Market
Fashion & Accessories
Decorative Accessories Market
Fashion & Accessories
Selfie Accessories Market
Fashion & Accessories
Cufflink Market
Fashion & Accessories
North America Lingerie Market
Fashion & Accessories
South America Handbags Market
Fashion & Accessories
North America Fashion Accessories Market
Fashion & Accessories
Europe Fashion Accessories Market
Fashion & Accessories
Asia Pacific Fashion Accessories Market
Fashion & Accessories
North America Handbag Market
Fashion & Accessories
Fashion Accessories Market
Fashion & Accessories
Hair Accessories Market
Fashion & Accessories
Hair Scrunchies Market
Fashion & Accessories
Custom Dog Tags Market