
 Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market Insights
Silicon anode chemistries is restructuring cell formation protocols and drying equipment specifications across the Asia-Pacific. Wuxi Lead Intelligent Equipment Co Ltd leverages its domestic supply chain density to dominate coating and calendering system deliveries. Mitsubishi Electric Corporation anchors high-precision laser notching and electrode slitting segments with proprietary motion control architectures. Schuler AG competes on large-format prismatic cell press integration, sustaining its position through German-engineered reliability standards adapted for Asian factory floors.
Asia-Pacific electric vehicle battery manufacturing equipment encompasses the specialized machinery, automation systems, and process control technologies required to produce lithium-ion and next-generation electrochemical cells at commercial scale, with typical line outputs exceeding 10 GWh annually and cell thickness tolerances below 5 micrometers. Cell assembly equipment commands the largest installed base but solid-state pilot lines represent the fastest-growing technology segment as dry electrode coating and sulfide electrolyte handling systems mature. Module assembly equipment occupies stable replacement demand cycles, while testing equipment concentrates margin pools due to the stringency of China's GB/T certification and South Korea's K-Battery safety mandates.
China's MIIT issues binding technical conditions for battery investment projects, directly shaping equipment efficiency minimums and prohibiting certain wet-process technologies in new facilities. Japan's METI coordinates national solid-state battery roadmaps that redirect R&D subsidies toward dry coating and all-solid-state electrolyte deposition tools. South Korea's MFDS and KATS enforce cell safety standards that mandate 100% formation testing, expanding demand for high-voltage cycling and impedance spectroscopy equipment. Stakeholders must monitor which regulatory jurisdiction sets the stricter equipment specification first, as that standard typically propagates across the regional supply base within two to three investment cycles.
Market Dynamics
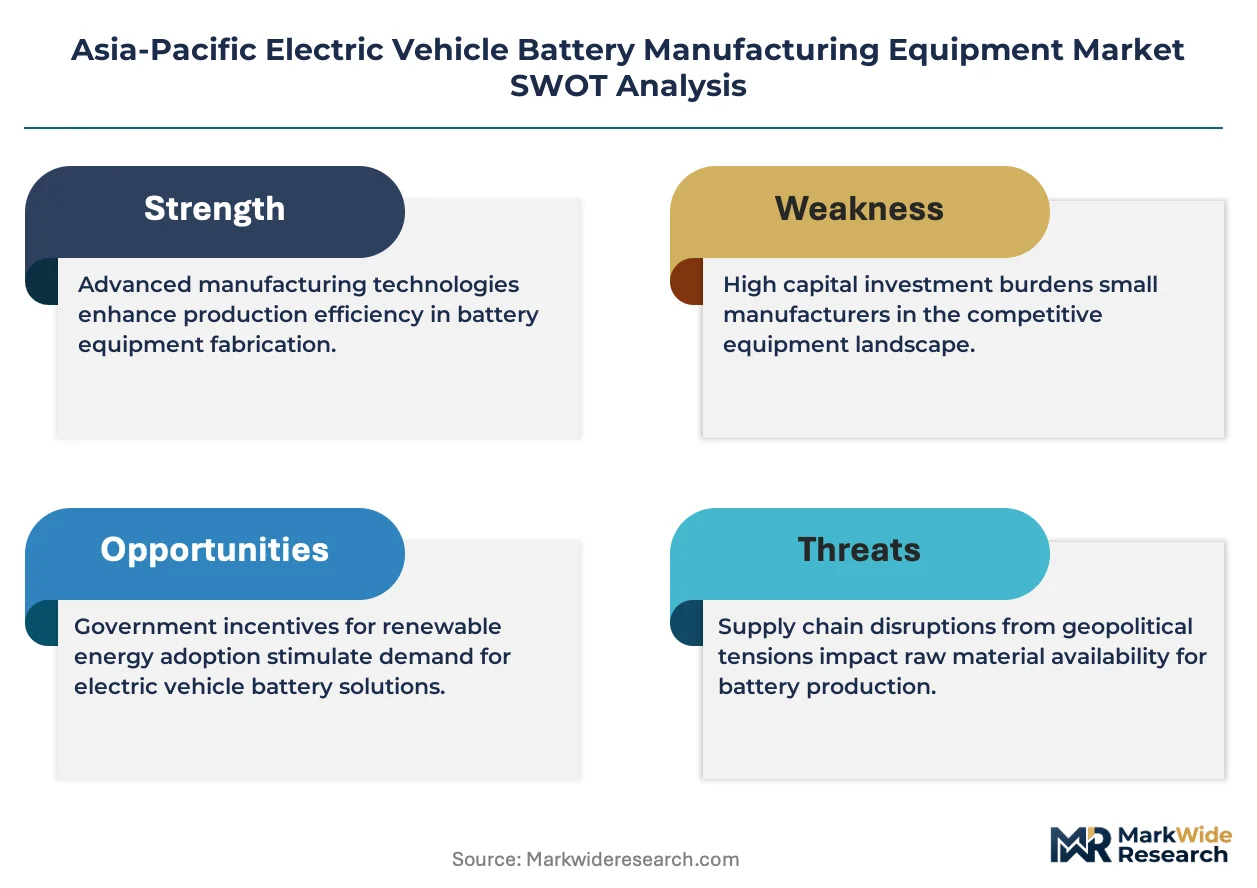
Silicon anode chemistries are forcing wholesale recalibration of formation equipment protocols across Asia-Pacific gigafactories, as cell manufacturers confront thermal runaway risks and electrolyte compatibility constraints that legacy lithium-ion lines cannot accommodate.
Growth Catalysts
- MIIT Energy Density Mandates:China's Ministry of Industry and Information Technology enforces minimum energy density thresholds for new battery investment projects, compelling equipment upgrades toward high-precision coating and calendering systems.
- Captive Production Expansion:Automotive OEMs in Japan and South Korea are building in-house cell assembly capacity, creating sustained demand for formation and testing equipment at multi-gigawatt scales.
- Sulfide Electrolyte Handling:Solid-state pilot lines require specialized dry-room deposition tools, opening equipment procurement cycles for sulfide-compatible coating and pressing machinery.
Market Restraints
- High-Precision Component Concentration:Laser notching heads and motion control systems rely heavily on German and Japanese suppliers, exposing buyers to extended lead times and currency volatility.
- Copper Foil Supply Bottlenecks:Ultra-thin cathode current collectors face processing constraints at rolling mills in China, transmitting cost pressure downstream to electrode manufacturing equipment buyers.
- Technical Limitation in Dry Coating:Binder distribution uniformity remains below wet-process standards, limiting throughput rates for dry electrode pilot lines below commercial viability thresholds.
Strategic Opportunities
- India's PLI Scheme for ACC Batteries:Production-linked incentives for advanced chemistry cell manufacturing are attracting equipment vendors to establish local service infrastructure around Tamil Nadu and Gujarat.
- Second-Life Battery Disassembly:End-of-life electric vehicle batteries require automated dismantling and sorting equipment, creating aftermarket demand for robotics and spectroscopic testing systems.
- Digital Twin Integration:Virtual commissioning of coating and stacking lines reduces physical prototyping cycles, enabling equipment suppliers to offer simulation-as-a-service alongside hardware deliveries.
Industry Challenges
- Electrochemical Engineer Shortage:Formation protocol optimization requires specialists fluent in both solid-state chemistry and high-voltage cycling instrumentation, a skill combination scarce across Jiangsu and Zhejiang industrial corridors.
- GB/T Certification Timelines:China's national standard certification for new equipment variants averages fourteen months, compressing product development windows for foreign suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market |
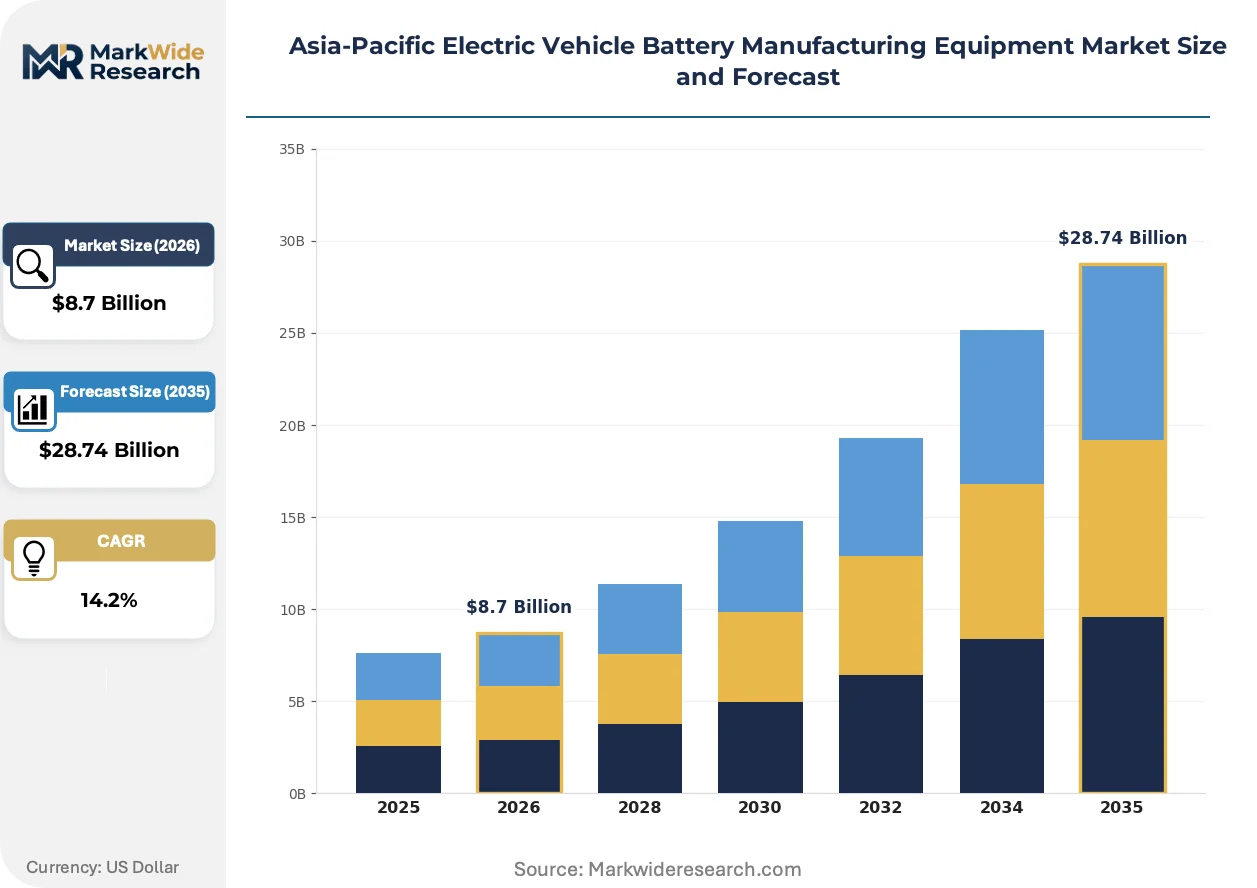
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Assembly Equipment, Module Assembly Equipment, Testing Equipment, Packaging Equipment Technology: Lithium-ion, Solid-state, Nickel-metal Hydride, Flow Battery End User: OEMs, Aftermarket Manufacturers, Research Institutions, Battery Plants Application: Automotive, Energy Storage, Consumer Electronics, Industrial Equipment |
| Companies Covered | Hitachi Ltd., Duerr AG, Schuler AG, Komatsu NTC Ltd., Wuxi Lead Intelligent Equipment Co Ltd, Xiamen Tmax Battery Equipments Limited, Yinghe Technology Co., Ltd., Mitsubishi Electric Corporation, Envision AESC Group Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Equipment architectures are pivoting toward dry-process compatibility and in-line quality verification, as cell manufacturers eliminate solvent recovery systems and compress formation cycle times.
Dry electrode coating is overtaking conventional wet slurry methods in pilot line deployments across South Korea and Japan. Samsung SDI and SK On are retrofitting Jiangsu facilities with binder fibrillation systems that eliminate N-methyl-2-pyrrolidone recovery infrastructure. This technology is overtaking solvent-based coating in capital expenditure efficiency, shrinking environmental compliance footprints while demanding new calendering pressure controls.
METI's national solid-state battery roadmap redirects Japanese R&D subsidies toward sulfide electrolyte deposition tools and all-solid-state formation chambers. Equipment suppliers must now certify compatibility with argon-atmosphere handling protocols to qualify for national funding streams. South Korean cell manufacturers are responding fastest, integrating Japanese dry-coating intellectual property into Gwangju-area pilot lines.
Buyer concentration among tier-one automotive OEMs is consolidating equipment procurement decisions into centralized technical committees. Hyundai Motor Group and BYD now mandate unified equipment specifications across their respective supplier networks, displacing the fragmented purchasing authority previously held at individual plant levels. This pattern is most visible in Zhejiang province, where CATL's customer equipment requirements are propagating to second-tier cell manufacturers through technical licensing agreements.
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market Segmentation
Equipment procurement patterns across Asia-Pacific diverge sharply by production scale and chemistry maturity. Cell manufacturers optimize capital allocation differently when serving automotive OEMs versus energy storage integrators, while regulatory pressure from China's MIIT and South Korea's MFDS reshapes specification requirements across every segment tier.
Product Type:
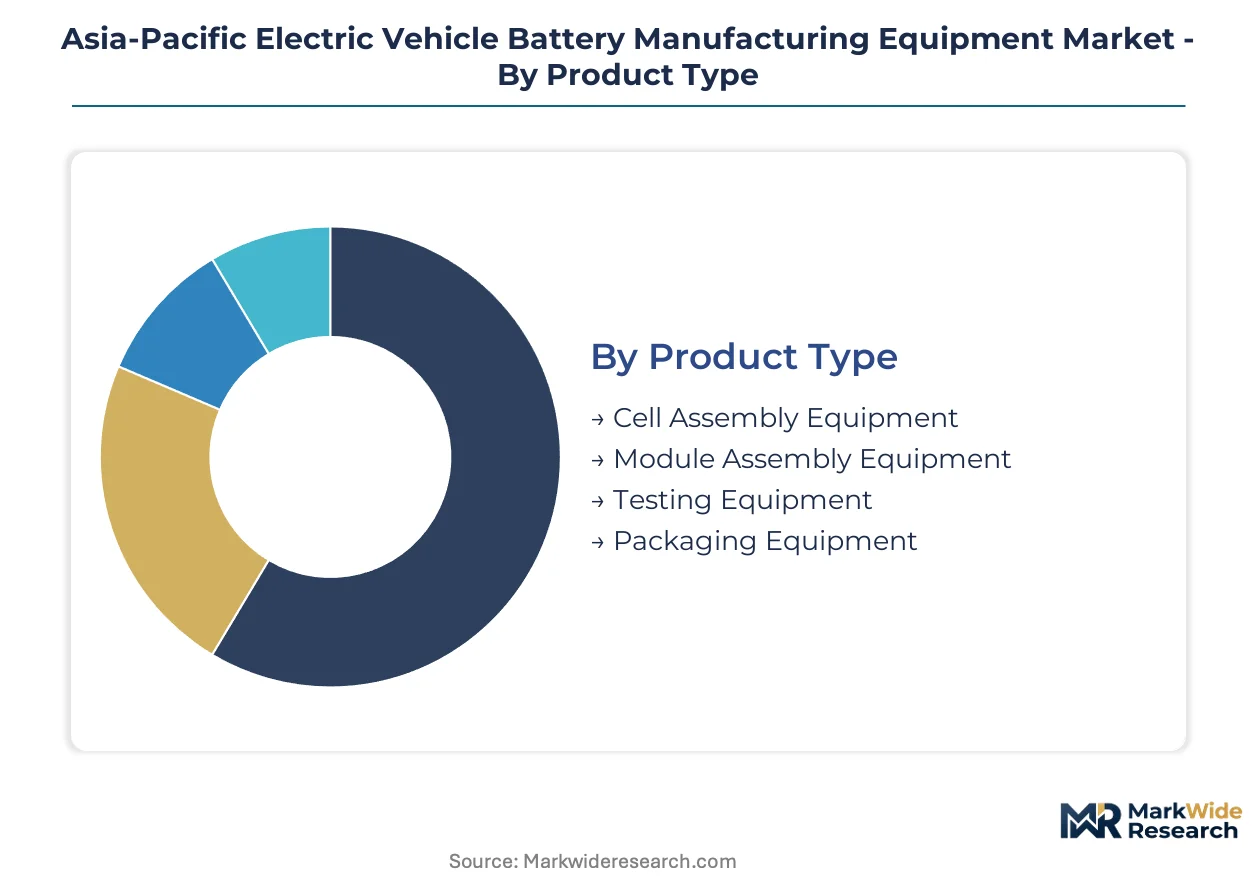
Supply concentration tilts heavily toward formation and coating systems as gigafactory buildouts in Jiangsu and Zhejiang provinces absorb the majority of regional equipment capacity.
- Cell Assembly Equipment:Stacking, winding, and electrolyte filling systems constitute the largest installed base across Asia-Pacific facilities. Jiangsu province's CATL and BYD supplier networks drive continuous demand for high-speed stacking machines with sub-5-micrometer alignment precision.
- Testing Equipment:Formation cycling, impedance spectroscopy, and high-voltage safety verification systems command premium margins due to China's GB/T certification mandates and South Korea's 100% formation testing requirements. South Korean cell manufacturers in Gwangju and Seosan prioritize impedance mapping equipment for silicon-anode compatibility validation.
- Module Assembly Equipment:Welding, laser bonding, and thermal management integration systems serve stable replacement cycles as existing lines upgrade for larger-format prismatic cells.
- Packaging Equipment:Pouch sealing, hard-case crimping, and final inspection systems complete production flows with lower differentiation intensity.
Today's leader: Cell Assembly Equipment. Tomorrow's challenger: Testing Equipment.
Technology:
Cost tier stratification separates pilot-line investments from commercial-scale deployments, with solid-state commanding capital multiples above conventional lithium-ion lines.
- Lithium-ion:NCM and LFP chemistries dominate commercial output across China, Japan, and South Korea. Wet-process coating and formation equipment from Wuxi Lead and Mitsubishi Electric anchor the technology base, with dry-coating retrofits gaining traction in Zhejiang facilities.
- Solid-state:Sulfide electrolyte handling and argon-atmosphere deposition tools attract METI-funded Japanese R&D and South Korean pilot investments. Samsung SDI's Gwangju lines and Toyota's Aichi facilities drive specialized procurement for all-solid-state formation chambers.
- Nickel-metal Hydride:Toyota's hybrid vehicle production in Aichi and Kyushu sustains limited equipment demand for legacy chemistry lines.
- Flow Battery:Vanadium redox systems occupy niche utility-scale storage applications with minimal Asia-Pacific manufacturing equipment presence.
Current volume anchor: Lithium-ion. Steepest expansion trajectory: Solid-state.
End User:
Customer type determines specification stringency, with automotive OEMs consolidating procurement authority into centralized technical committees.
- OEMs:Hyundai Motor Group, BYD, and Toyota mandate unified equipment specifications across captive battery plants, displacing fragmented plant-level purchasing. Their technical committees in Seoul, Shenzhen, and Toyota City enforce harmonized coating and formation protocols.
- Battery Plants:CATL, LG Energy Solution, and SK On operate as independent suppliers to multiple OEMs, requiring flexible equipment configurations for chemistry switching. Their Jiangsu and Seosan facilities prioritize rapid format changeover capabilities.
- Aftermarket Manufacturers:Second-life battery disassembly and refurbishment operations in Tamil Nadu and Gujarat create emerging demand for automated dismantling robotics.
- Research Institutions:Tsinghua University, KAIST, and AIST operate pilot lines with sub-gigawatt throughput for next-chemistry validation.
Specification authority concentrates: OEMs. Volume procurement concentrates: Battery Plants.
Application:
Margin pools vary by certification burden, with automotive applications absorbing the highest compliance costs and energy storage offering volume scale at lower specification intensity.
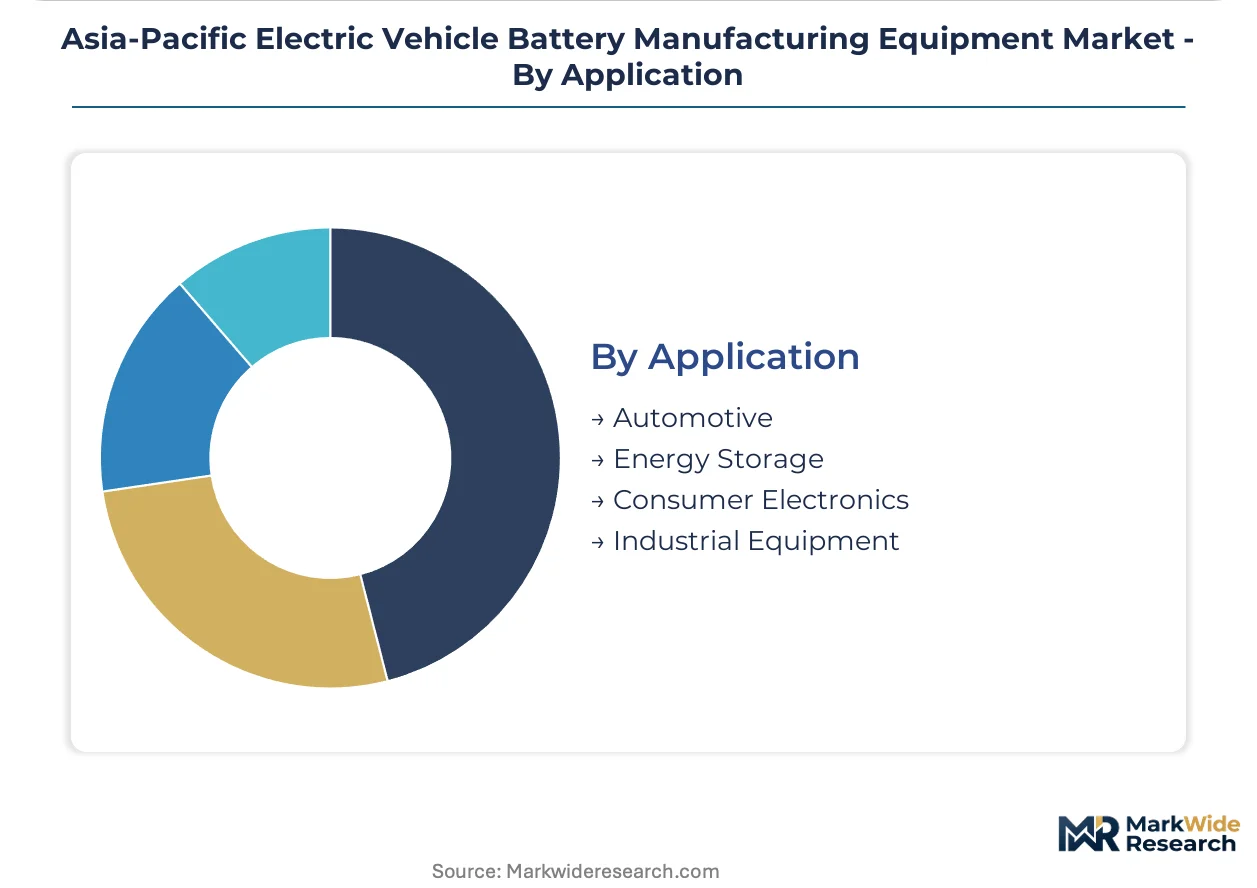
- Automotive:Passenger EV and commercial vehicle battery production absorbs the majority of regional equipment capacity. China's MIIT energy density mandates and South Korea's K-Battery safety standards enforce high-precision coating and 100% formation testing requirements.
- Energy Storage:Grid-scale and residential battery systems prioritize cost efficiency over energy density, favoring LFP chemistry lines with simplified formation protocols. Zhejiang and Guangdong provinces host dedicated ESS equipment configurations.
- Consumer Electronics:Cylindrical cell production for power tools and portable devices sustains compact winding and formation equipment demand in Japan's Osaka industrial corridor.
- Industrial Equipment:Forklift and stationary power applications represent stable replacement demand with limited technology differentiation.
Compliance cost leader: Automotive. Volume scaling opportunity: Energy Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor equipment procurement intensity across the Asia-Pacific, absorbing coating and formation system deliveries at multi-gigawatt scales while MIIT traceability mandates reshape supplier qualification protocols.
China
CATL and BYD supplier networks in Jiangsu and Zhejiang drive continuous demand for high-precision stacking and calendering equipment. MIIT energy density mandates and battery traceability requirements compel equipment upgrades toward automated coating lines with sub-5-micrometer tolerances. Wuxi Lead Intelligent Equipment leverages domestic supply chain density to dominate regional coating system deliveries.
South Korea
LG Energy Solution and SK On operate captive formation and testing facilities in Gwangju and Seosan, prioritizing impedance spectroscopy equipment for silicon-anode validation. MFDS and KATS enforce 100% formation testing requirements that expand demand for high-voltage cycling chambers. Samsung SDI's Gwangju pilot lines integrate Japanese dry-coating intellectual property for sulfide electrolyte handling.
Japan
Toyota's hybrid production in Aichi and Kyushu sustains limited nickel-metal hydride equipment demand alongside solid-state investments. METI's national solid-state battery roadmap redirects R&D subsidies toward dry coating and all-solid-state formation chambers. Mitsubishi Electric anchors high-precision laser notching segments with proprietary motion control architectures adapted for prismatic cell formats.
India
Tamil Nadu and Gujarat are attracting equipment vendors to establish local service infrastructure under the PLI scheme for advanced chemistry cell manufacturing. Reliance Industries and Ola Electric are building gigafactory capacity that requires electrode coating and cell assembly equipment procurement. The country's national industrial regulator is coordinating technical standards adoption with state-level manufacturing incentives.
Vietnam
Vinh Phuc and Bac Ninh provinces are emerging as secondary equipment destinations as Chinese manufacturers establish Southeast Asian assembly nodes. VinFast's battery joint ventures with foreign cell suppliers are driving initial formation equipment inquiries. The country's ministry of industry and trade is drafting technical regulations aligned with Chinese GB/T certification frameworks to accelerate supplier qualification.
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as equipment suppliers race to match gigafactory buildout timelines across Jiangsu and Zhejiang. The vendor base separates into three strategic archetypes: Chinese domestic specialists with integrated supply chains, Japanese precision engineering houses, and German reliability-focused system integrators. M&A activity and strategic partnerships concentrate around dry-coating technology access and Southeast Asian service infrastructure.
Among Japanese precision engineering houses, Mitsubishi Electric Corporation and Hitachi Ltd. exemplify the motion-control-intensive tier, while Schuler AG represents German-engineered reliability standards adapted for Asian factory floors. Wuxi Lead Intelligent Equipment Co Ltd anchors the domestic Chinese specialist archetype through coating and calendering system density. These three occupy positions across the equipment value chain without overlapping core technology specializations.
| Leading Market Players |
|---|
| Hitachi Ltd. |
| Duerr AG |
| Schuler AG |
| Komatsu NTC Ltd. |
| Wuxi Lead Intelligent Equipment Co Ltd |
| Xiamen Tmax Battery Equipments Limited |
| Yinghe Technology Co., Ltd. |
| Mitsubishi Electric Corporation |
| Envision AESC Group Limited |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply and premium-tier pricing access, as equipment vendors must certify energy efficiency benchmarks and carbon disclosure protocols to serve Jiangsu and Zhejiang gigafactory clusters. Buyers with MIIT-compliant traceability systems command 15-20% pricing premiums over uncertified competitors, while carbon-intensive wet-process equipment faces procurement exclusion.
Pricing Analysis
Input-cost pass-through from copper foil and laser notching head suppliers anchors pricing dynamics across formation and coating system tiers. Project-based contracting with volume-scaled discounts dominates procurement, with certification grade and after-sales service bundling as primary price differentiation drivers. Cost compression in standard-tier calendering equipment intensifies as Wuxi Lead and domestic competitors expand capacity. Automotive OEM technical committees demonstrate lowest price sensitivity, while independent battery plants in South Korea prioritize rapid format changeover capabilities over unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from Hyundai Motor Group and BYD technical committees mandate multi-supplier qualification for laser notching heads and motion control systems, fragmenting procurement across German and Japanese vendors. Supply concentrates in China, Japan, and South Korea for electrode coating machinery, with critical dependencies on high-precision linear motors, argon-atmosphere handling components, and sulfide electrolyte deposition tools. Single-source vulnerability in ultra-thin copper foil rolling mills transmits cost pressure downstream. Distribution runs through direct vendor-OEM technical committees, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through dry-process equipment premiums, as METI-funded R&D subsidies and MIIT energy density mandates accelerate substitution away from solvent-based coating systems.
For Market Incumbents: Deploy backward integration into linear motor and precision motion control manufacturing to reduce exposure to German and Japanese supplier lead times. Incumbents must anchor market position by certifying sulfide electrolyte handling compatibility ahead of solid-state pilot line scale-up, while building captive service infrastructure in Tamil Nadu and Gujarat to capture India's PLI-driven demand before foreign entrants establish local presence. For New Entrants and Emerging Players: India's PLI scheme for ACC batteries in Tamil Nadu and Gujarat opens a window for equipment vendors to establish local service infrastructure and capture first-mover advantage in formation and testing equipment. New entrants should prioritize automated dismantling robotics for second-life battery operations as the most penetrable white-space segment, with a go-to-market angle centered on spectroscopic testing system integration for end-of-life sorting protocols. For Investors and Strategic Acquirers: Roll-up economics work for precision motion control specialists because buyer consolidation into centralized technical committees creates vendor rationalization pressure across Hyundai, BYD, and Toyota supplier networks. Investors should target mid-cap dry-coating technology holders with METI or MIIT certification pathways. The signal to watch as inflection indicator is GB/T certification timeline compression below twelve months, which would accelerate foreign supplier market entry and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Coating Scale-Up | Eliminates N-methyl-2-pyrrolidone recovery infrastructure and shrinks environmental compliance footprints for Zhejiang facilities. |
| Sulfide Electrolyte Handling Certification | Qualifies equipment vendors for METI R&D subsidies and Toyota solid-state pilot line procurement. |
| India Service Infrastructure Buildout | Captures PLI scheme demand from Reliance Industries and Ola Electric gigafactory projects in Tamil Nadu. |
| Digital Twin Integration | Enables simulation-as-a-service offerings that reduce physical prototyping cycles for coating line deployments. |
| Second-Life Disassembly Robotics | Addresses emerging aftermarket demand from end-of-life EV battery sorting operations in Gujarat. |
Research Methodology
Coverage spans China, Japan, South Korea, India, and Vietnam, with primary inputs from each market's equipment procurement ecosystem. The analysis combines primary interviews with gigafactory engineering directors, OEM battery technical committee leads, and electrode manufacturing R&D heads with secondary validation from MIIT investment project filings, METI solid-state roadmap disclosures, and customs data on coating system imports. Bottom-up triangulation across Jiangsu and Zhejiang facility announcements and top-down cross-checks against regional battery capacity buildout projections anchor the analytical framework.
Rate-of-change decomposition separates volume growth from unit value shifts across the projection horizon. The forecast framework models equipment demand by product type, technology maturity tier, end-user consolidation pattern, and application-specific certification burden. CAGRs derive from equipment intensity ratios per gigawatt-hour of battery capacity, adjusted for dry-process substitution curves and solid-state pilot line capital multiples. Key inputs include MIIT energy density mandate compliance timelines and MFDS formation testing requirement enforcement phases.
Revisions become necessary when MIIT mandates accelerate wet-process equipment prohibition timelines or when copper foil supply bottlenecks extend beyond rolling mill capacity expansion schedules. Deviation in GB/T certification processing speed would shift the outlook materially for foreign supplier market penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
European EV Battery Systems Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Batteries Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
China Electric Vehicle Battery Market