
 Automated Microplate Handling Systems Market | 2026-2036
Automated Microplate Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Microplate Handling Systems Market Outlook
A shortage of trained laboratory automation technicians is unwinding capacity expansion plans at several contract research organizations. Tecan leverages its integrated liquid-handling platforms to sustain dominance in high-throughput screening workflows. Hudson Robotics anchors its position through specialized colony-picking systems that compete directly with larger platform vendors. Thermo Fisher Scientific extends its channel control across North American academic accounts through bundled service contracts.
Automated microplate handling systems comprise electromechanical devices that transport, position, and process standard-format microplates with positional accuracy typically below 0.1 millimeters in x-y axis repeatability. These systems integrate with washers, readers, and dispensers to execute multi-step assays without manual intervention, primarily serving pharmaceutical and biotechnology laboratories seeking to increase experimental throughput while reducing human error. Robotic arm modules capture the largest installed base due to their flexibility across diverse assay formats, though microplate readers generate disproportionate margin pools from recurring consumables and software licensing. High-throughput screening applications within drug discovery represent the fastest-expanding demand segment, driven by contract research organizations scaling compound library evaluation.
FDA 21 CFR Part 11 compliance requirements shape software validation and audit trail specifications for systems deployed in regulated pharmaceutical environments, while ISO 13485 quality management standards govern manufacturing processes for equipment used in diagnostic applications. The EPA's Good Automated Manufacturing Practice guidelines additionally influence environmental testing laboratory procurement criteria. Stakeholders must monitor evolving EU MDR traceability requirements as European diagnostic laboratories recalibrate automation investments.
Market Dynamics
Contract research organizations are compressing compound screening timelines from months to weeks, forcing equipment vendors to prioritize throughput velocity over incremental precision gains in microplate handling architectures.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in the United States are accelerating replacement cycles for legacy systems lacking compliant audit trails.
- Cell-based assays:Complex phenotypic screening workflows in oncology drug discovery are driving demand for multi-axis robotic positioning modules.
- Boston-San Diego corridor:Biotech cluster density in these metropolitan areas sustains above-average instrument procurement velocity.
Market Restraints
- Precision motion components:Ball screw and linear motor supply chains concentrate in Japanese and German manufacturing bases, exposing buyers to extended lead times.
- ISO 13485 certification:Diagnostic equipment manufacturers face 12-18 month validation timelines that delay commercial deployment.
- Manual pipetting workstations:Lower-cost alternatives retain share in academic laboratories with intermittent throughput requirements.
Strategic Opportunities
- India's PLI scheme:Domestic pharmaceutical manufacturing incentives are stimulating greenfield automation investments in Hyderabad and Bangalore.
- AI-driven colony picking:Machine vision integration with existing robotic arms opens upgrade revenue streams without full platform replacement.
- Cloud-native LIMS integration:API-first microplate handlers can capture recurring software revenue from distributed biotech startups.
Industry Challenges
- Automation technician scarcity:CRO expansion plans in North Carolina and Massachusetts stall due to insufficient trained personnel for system validation.
- Legacy scheduler compatibility:New robotic modules require custom middleware to synchronize with 15-year-old plate reader control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Microplate Handling Systems Market |
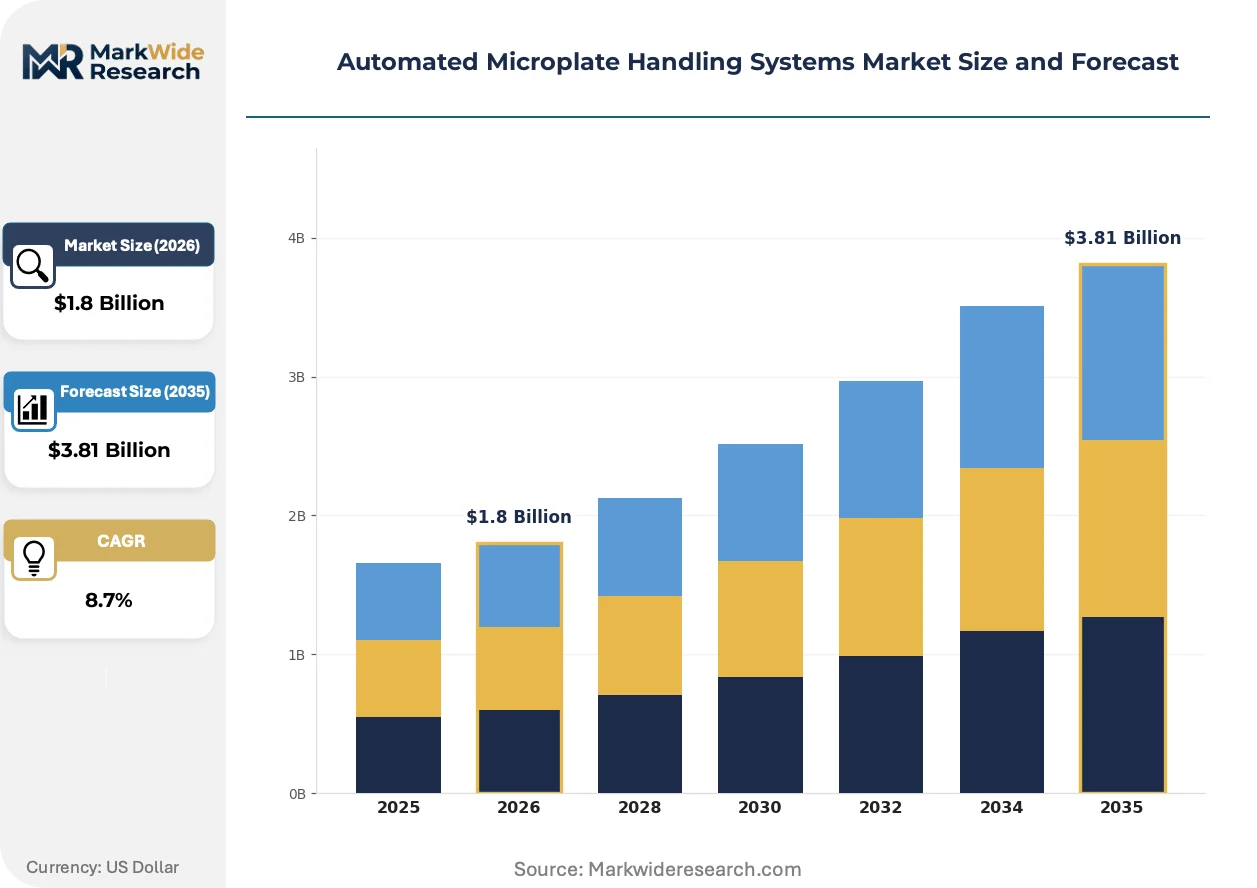
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arm, Microplate Washer, Microplate Reader, Automated Dispenser Application: Drug Discovery, Genomics, Protein Analysis, High-Throughput Screening End User: Pharmaceutical Companies, Academic Research Institutes, Diagnostics Laboratories, Biotech Firms Technology: Vacuum Aspiration, Liquid Handling, Thermal Cycler, Optical Detection |
| Companies Covered | Tecan, Hudson Robotics, Thermo Fisher Scientific, Danaher, Molecular Devices, Agilent Technologies, Berthold Technologies, Beckman Coulter Life Sciences, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Microplate Handling Systems Market Strategic Shifts
Modular robotic architectures are displacing monolithic platforms as laboratories demand reconfigurable workflows that adapt to assay protocol changes without capital replacement.
Acoustic liquid handling is fragmenting the traditional pipetting-dominated sample transfer market. Biopharma discovery groups in Cambridge and Basel are adopting tipless transfer to reduce consumable costs and cross-contamination risk. This technology is fragmenting vendor revenue pools by compressing the addressable market for pipette tip manufacturers while expanding service contracts for acoustic transducer calibration.
EU MDR traceability requirements are reshaping procurement specifications for diagnostic laboratories in Germany and France. Equipment vendors must now embed unique device identification and end-to-end chain-of-custody logging. In vitro diagnostic manufacturers are responding by pre-qualifying automation partners with established quality management systems rather than evaluating on price alone.
Service unbundling is accelerating among academic core facilities. University procurement offices in California and Texas are separating instrument purchase from maintenance contracts, enabling third-party service providers to compete on response time guarantees. This shift is most visible in NIH-funded institutions where grant compliance requires documented uptime SLAs independent of manufacturer support tiers.
Automated Microplate Handling Systems Market Segmentation
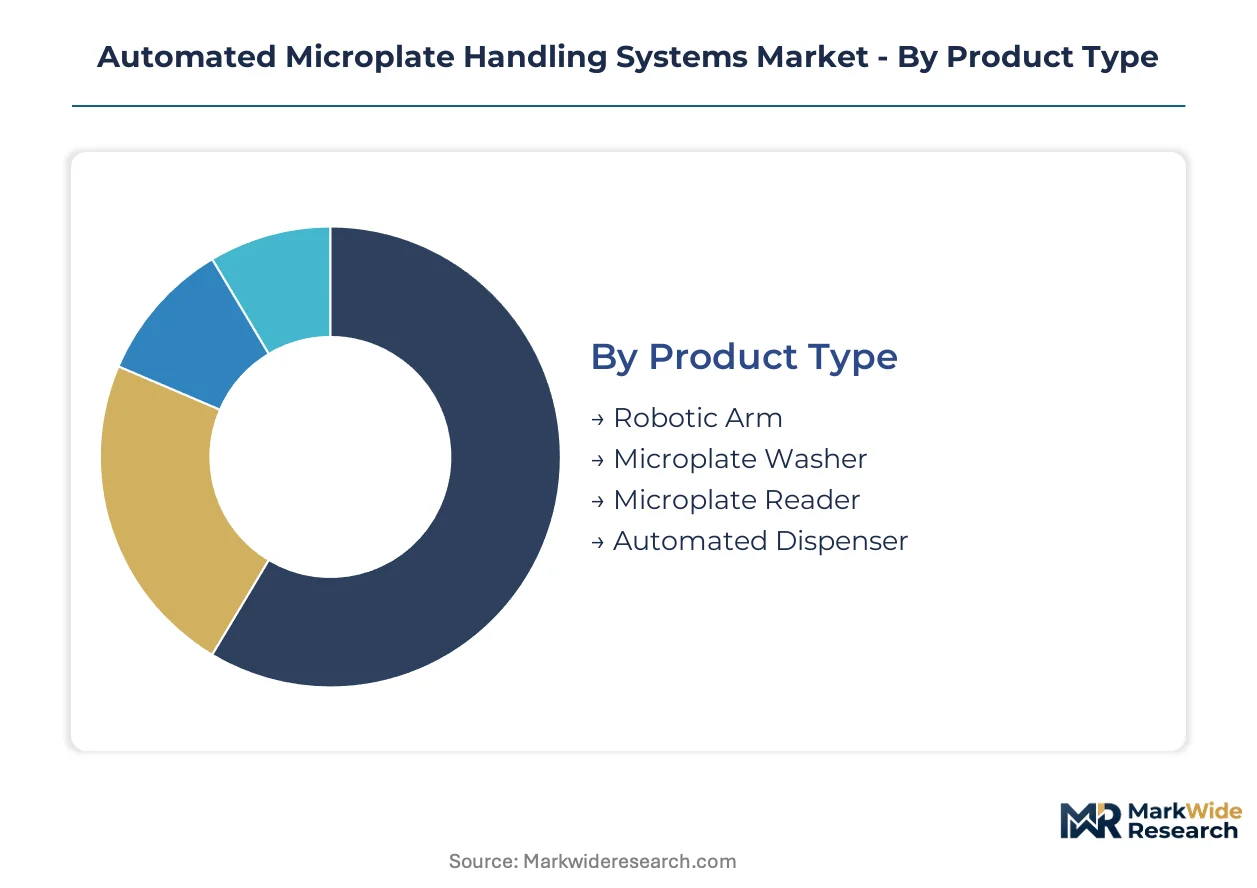
Automated microplate handling systems fragment across multiple technical and commercial dimensions that determine procurement priorities. Product architecture, application intensity, and end-user regulatory exposure each create distinct specification requirements and margin profiles for equipment vendors.
Product Type:
Domestic production concentrates robotic arm and reader assemblies in the United States and Switzerland, while microplate washers and dispensers flow primarily from German and Japanese manufacturing bases.
- Robotic Arm:Electromechanical positioning modules achieve sub-0.1 millimeter repeatability across x-y-z axes. Pharmaceutical laboratories in Boston and Basel specify these for multi-step assay workflows requiring flexible reconfiguration between screening protocols.
- Microplate Reader:Optical detection engines with photomultiplier or CCD architectures generate recurring revenue through software licensing and calibration contracts. Academic core facilities in California and Texas prioritize readers with open API architectures for LIMS integration.
- Microplate Washer:Vacuum aspiration and magnetic bead separation modules for ELISA and cell-based assays. Biotech startups in Bangalore specify compact washers for limited bench space.
- Automated Dispenser:Precision liquid handling units spanning nanoliter to milliliter volumes. Contract research organizations in Hyderabad deploy these for compound library preparation.
Robotic arm modules hold the largest share; momentum sits with microplate readers.
Application:
Cost tiering separates high-throughput screening investments from lower-velocity genomics and protein analysis deployments.
- Drug Discovery:Multi-parameter phenotypic screening drives demand for integrated robotic platforms. Oncology-focused biotech firms in Cambridge, Massachusetts compress compound evaluation timelines from months to weeks.
- High-Throughput Screening:Parallel processing of 10,000+ compounds daily requires synchronized plate handling, liquid transfer, and detection modules. Contract research organizations in North Carolina and Massachusetts anchor procurement volume.
- Genomics:Nucleic acid extraction and library preparation workflows. Academic institutes in Texas prioritize modular systems compatible with third-party thermal cyclers.
- Protein Analysis:ELISA and western blot automation for quantification workflows. Diagnostics laboratories in France specify systems with EU MDR-compliant audit trails.
Drug discovery captures the dominant investment pool; high-throughput screening shows the steepest expansion trajectory.
End User:
Customer type determines validation burden and service contract structure, with pharmaceutical companies demanding FDA 21 CFR Part 11 compliance that academic institutes often bypass.
- Pharmaceutical Companies:Regulated environments mandate electronic records, user access controls, and complete audit trails. Major firms in Switzerland and the United States replace legacy systems on 5-7 year cycles to maintain compliance.
- Biotech Firms:Venture-funded startups in San Diego and Boston prioritize throughput velocity over precision specifications. These buyers favor rental and service-bundled procurement models.
- Academic Research Institutes:NIH-funded core facilities separate instrument purchase from maintenance contracts. Universities in California negotiate third-party service agreements independent of manufacturer tiers.
- Diagnostics Laboratories:Clinical testing environments require ISO 13485-certified equipment with end-to-end traceability. German and French laboratories embed EU MDR unique device identification requirements into procurement specifications.
Pharmaceutical companies dominate absolute spending; biotech firms are gaining share fastest.
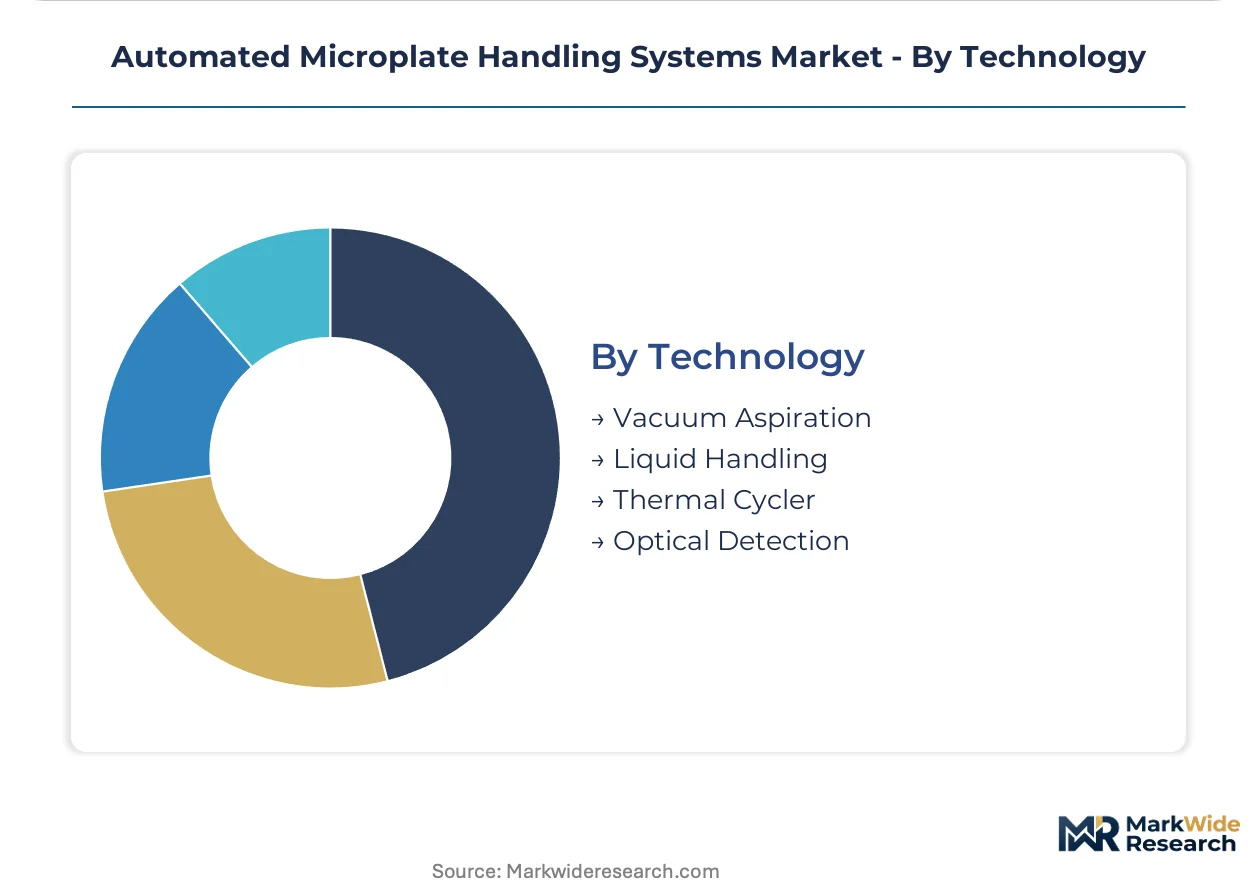
Technology:
Supply concentration for precision motion components and optical subassemblies shapes technology adoption patterns across geographies.
- Liquid Handling:Pipetting and acoustic transfer mechanisms for sample and reagent distribution. Acoustic tipless technology from vendors in Basel reduces consumable costs for high-volume screening.
- Optical Detection:Absorbance, fluorescence, and luminescence measurement engines. German manufacturers concentrate supply of photomultiplier tubes and precision optics.
- Vacuum Aspiration:Plate washing and media removal for cell-based assays. Japanese suppliers dominate precision pump and valve components.
- Thermal Cycler:PCR amplification integration with plate handling robotics. Chinese manufacturers are expanding capacity for basic thermal cycling modules.
Liquid handling retains the broadest installed base; optical detection commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance mandates in the United States are accelerating replacement cycles for legacy systems lacking electronic audit trails. Pharmaceutical and biotechnology clusters across four major economies drive procurement velocity and shape regional specification requirements.
United States
Biotech corridor density in Boston and San Diego sustains above-average instrument procurement cycles. FDA electronic records requirements force pharmaceutical laboratories to replace non-compliant systems on compressed timelines. Contract research organizations in North Carolina and Massachusetts anchor high-throughput screening demand.
Germany
Precision optics and photomultiplier tube manufacturing concentrates in German industrial bases. EU MDR traceability requirements reshape procurement specifications for diagnostic laboratories in Munich and Frankfurt. ISO 13485-certified equipment mandates delay commercial deployment by 12-18 months.
Switzerland
Swissmedic regulatory frameworks govern diagnostic equipment quality management for Basel-based pharmaceutical headquarters. Acoustic liquid handling technology from vendors in this market reduces consumable costs for high-volume screening workflows. Roche and Novartis procurement specifications influence global instrument standards.
India
PLI scheme incentives stimulate greenfield automation investments in Hyderabad and Bangalore pharmaceutical manufacturing zones. Domestic production capacity for basic thermal cycling modules expands from Chinese manufacturers. Contract research organizations in these cities compress compound screening timelines from months to weeks.
Japan
PMDA quality standards govern precision motion component supply chains concentrated in Nagoya and Osaka manufacturing bases. Ball screw and linear motor production exposes buyers to extended lead times. METI industrial policy supports domestic automation equipment for diagnostic applications.
Automated Microplate Handling Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base spans integrated life science conglomerates, specialized robotics fabricators, and optical detection specialists. Three strategic archetypes dominate: full-platform integrators, modular component specialists, and consumables-anchored service providers. Competitive moves concentrate on strategic partnerships for LIMS integration and geographic expansion into India's pharmaceutical manufacturing zones.
Among North American-based conglomerates, Danaher and Thermo Fisher Scientific occupy positions as full-platform integrators with channel control across academic and pharmaceutical accounts. Tecan represents the precision liquid handling specialist archetype, while Agilent Technologies sits within the analytical instrumentation tier. Hudson Robotics exemplifies the focused robotics module approach competing against larger platform vendors. These three anchors illustrate how scale, specialization, and service bundling create distinct competitive positions without overlapping core value propositions.
| Leading Market Players |
|---|
| Tecan |
| Hudson Robotics |
| Thermo Fisher Scientific |
| Danaher |
| Molecular Devices |
| Agilent Technologies |
| Berthold Technologies |
| Beckman Coulter Life Sciences |
| PerkinElmer |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japanese and German precision motion component manufacturers shapes both supply availability and price floors for robotic positioning modules. Pharmaceutical buyers in Boston and Basel face extended lead times that compress negotiation leverage, while academic institutes in Texas exploit service unbundling to drive down total cost of ownership.
Pricing Analysis
United States-based pharmaceutical laboratories pay 15-25% premiums over academic buyers for equivalent robotic arm configurations. Pricing stratifies across FDA 21 CFR Part 11-certified, ISO 13485-compliant, and uncertified equipment tiers. Cost compression in the standard tier intensifies as Chinese thermal cycler manufacturers expand capacity. Contract research organizations in North Carolina exhibit the highest price sensitivity; diagnostics laboratories in France show the least due to EU MDR compliance mandates.
Supply Chain Analysis
Japan and Germany anchor production of ball screws, linear motors, and precision optics that feed robotic positioning modules. German manufacturers concentrate photomultiplier tube supply for microplate readers. Japanese suppliers dominate vacuum pump and valve components for plate washing systems. Single-source vulnerability concentrates in Nagoya-area precision motion fabricators. Distribution runs through authorized service networks that bundle installation validation with hardware delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
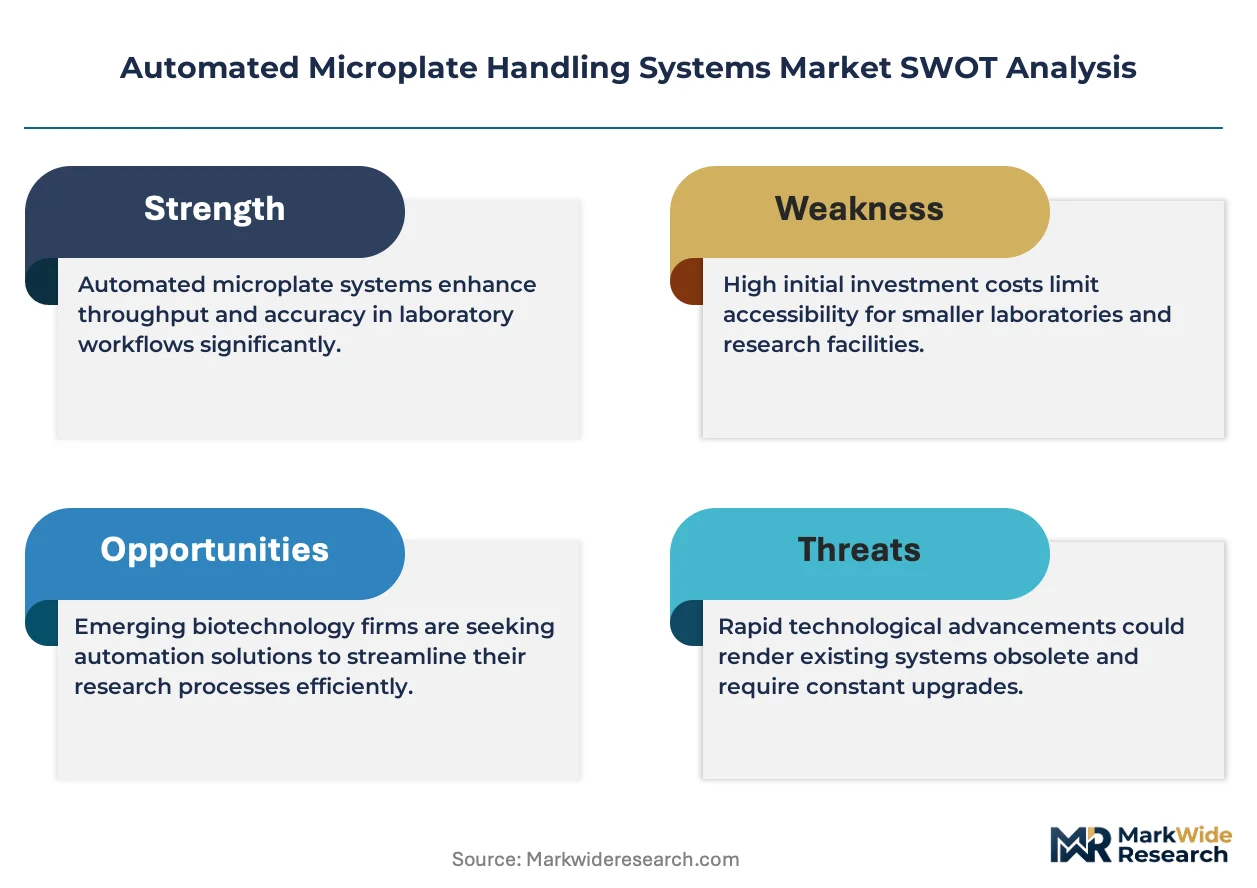
This market is entering a cyclical recovery driven by FDA-mandated replacement cycles for non-compliant legacy systems. Equipment vendors and buyers must position for compressed procurement timelines as pharmaceutical laboratories accelerate validation schedules.
For Market Incumbents: Compound defensive positions by deepening backward integration into precision motion component supply and securing exclusive LIMS integration partnerships. Acoustic liquid handling technology threatens pipetting-dominated revenue pools; incumbents should anchor service contracts for transducer calibration. Channel control across North American academic accounts requires response-time guarantees that match third-party service providers.
For New Entrants and Emerging Players: Lead with modular robotic architectures that enable assay reconfiguration without platform replacement. India's PLI scheme stimulates greenfield automation investments in Hyderabad and Bangalore where incumbent presence remains thin. Cloud-native API-first positioning captures recurring software revenue from distributed biotech startups in Boston and San Diego.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors optical detection specialists with established calibration service revenue and consumables-anchored business models. Long-term viability over a 5-10 year window rests on software licensing attachment rates rather than hardware shipment volumes. Monitor acoustic liquid handling adoption curves in Cambridge and Basel as inflection indicators for pipetting market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Development | Enables assay reconfiguration without capital replacement for CROs in North Carolina. |
| Cloud-Native LIMS Integration | Captures recurring software revenue from biotech startups in Boston and San Diego. |
| Acoustic Liquid Handling Expansion | Reduces consumable costs for high-volume screening workflows in Basel laboratories. |
| India PLI Zone Manufacturing | Establishes greenfield capacity to serve pharmaceutical automation demand in Hyderabad. |
| EU MDR Pre-Qualification Programs | Locks in diagnostic laboratory procurement specifications in Germany and France. |
Study Parameters
Initial hypotheses were tested against primary input from laboratory automation directors, pharmaceutical procurement managers, CRO operations leads, and academic core facility directors and refined through secondary validation. Primary fieldwork drew from FDA 483 inspection databases, ISO 13485 certification registries, NIH grant expenditure records, and EU MDR technical documentation. Bottom-up equipment shipment estimates triangulated against top-down pharmaceutical R&D spending allocations.
Variance decomposition across product architecture, application intensity, end-user regulatory exposure, and geographic procurement cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated replacement cycle timing for FDA 21 CFR Part 11 compliance, acoustic liquid handling adoption velocity, and India's PLI scheme implementation pace.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU MDR, and Swissmedic frameworks; material policy shifts would require re-modeling. Specific risks include automation technician scarcity stalling CRO expansion, precision motion component supply disruption, and legacy scheduler compatibility failures. Recalibration cycles align with material shifts in regulatory enforcement patterns and technology substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Portable Particle Counter Market