
 Near Infrared Spectrum Instruments Market | 2026-2036
Near Infrared Spectrum Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Near Infrared Spectrum Instruments Market Insights
The EU Green Deal's push for sustainable manufacturing is realigning pharmaceutical and food sector investment toward inline analytical tools. Bruker Corporation leverages its Fourier-transform platform strength to sustain European market presence. Thermo Fisher Scientific anchors North American demand through its broad life sciences distribution network. FOSS dominates agricultural applications with specialized grain and dairy analyzers.
Near infrared spectrum instruments operate across the 780–2500 nm wavelength range, employing diffraction gratings or interferometers to measure molecular overtone and combination vibrations for quantitative compositional analysis. Spectrometers occupy the largest revenue share due to their versatility across laboratory and process environments. Hyperspectral imaging systems represent the fastest-expanding technology segment, driven by pharmaceutical tablet mapping and agricultural grading applications where spatial resolution unlocks premium pricing.
FDA process analytical technology guidelines and EMA quality-by-design frameworks mandate real-time monitoring, directly expanding NIR deployment in drug manufacturing. EPA environmental monitoring standards and USDA grain inspection protocols further validate instrument accuracy requirements. Stakeholders must weigh photonic against Fourier-transform architectures as application specificity intensifies and customer integration demands deepen.
Market Dynamics
Process analytical technology mandates from the FDA and EMA are forcing pharmaceutical manufacturers to replace offline quality testing with inline NIR systems, compressing validation timelines and reshaping instrument procurement specifications.
Growth Catalysts
- EU Green Deal sustainable manufacturing mandates:Chemical and food producers in Germany and the Netherlands must install inline analyzers to reduce waste and energy consumption during production cycles.
- Hyperspectral imaging adoption:Pharmaceutical tablet mapping applications now require spatial resolution capabilities that only advanced NIR imaging systems can deliver.
- USDA grain inspection protocol modernization:Elevator operators across the American Midwest are upgrading to automated NIR analyzers to accelerate commodity grading throughput.
Market Restraints
- Indium gallium arsenide detector supply concentration:Japanese and Chinese suppliers control substrate production for NIR array sensors, exposing instrument makers to input cost volatility and allocation constraints.
- Validation timeline friction:FDA process analytical technology submissions require 18-24 month qualification periods that delay revenue recognition for instrument vendors.
- Mid-infrared spectroscopy substitution:Fourier-transform infrared systems with attenuated total reflectance accessories are capturing applications requiring higher molecular specificity than NIR can provide.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO quality-by-design guidelines are creating first-time demand for inline NIR systems among domestic generic drug producers.
- Cell and gene therapy bioprocessing:Real-time culture monitoring applications represent an emerging use case requiring specialized NIR probe configurations.
- Digital twin integration:Convergence between NIR data streams and process simulation software is enabling predictive quality control in continuous manufacturing environments.
Industry Challenges
- Chemometric modeling expertise scarcity:Manufacturers struggle to hire spectroscopists capable of developing and maintaining multivariate calibration models for complex matrices.
- Legacy system integration complexity:Brownfield pharmaceutical facilities face protocol mismatches when connecting modern NIR analyzers to established distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near Infrared Spectrum Instruments Market |
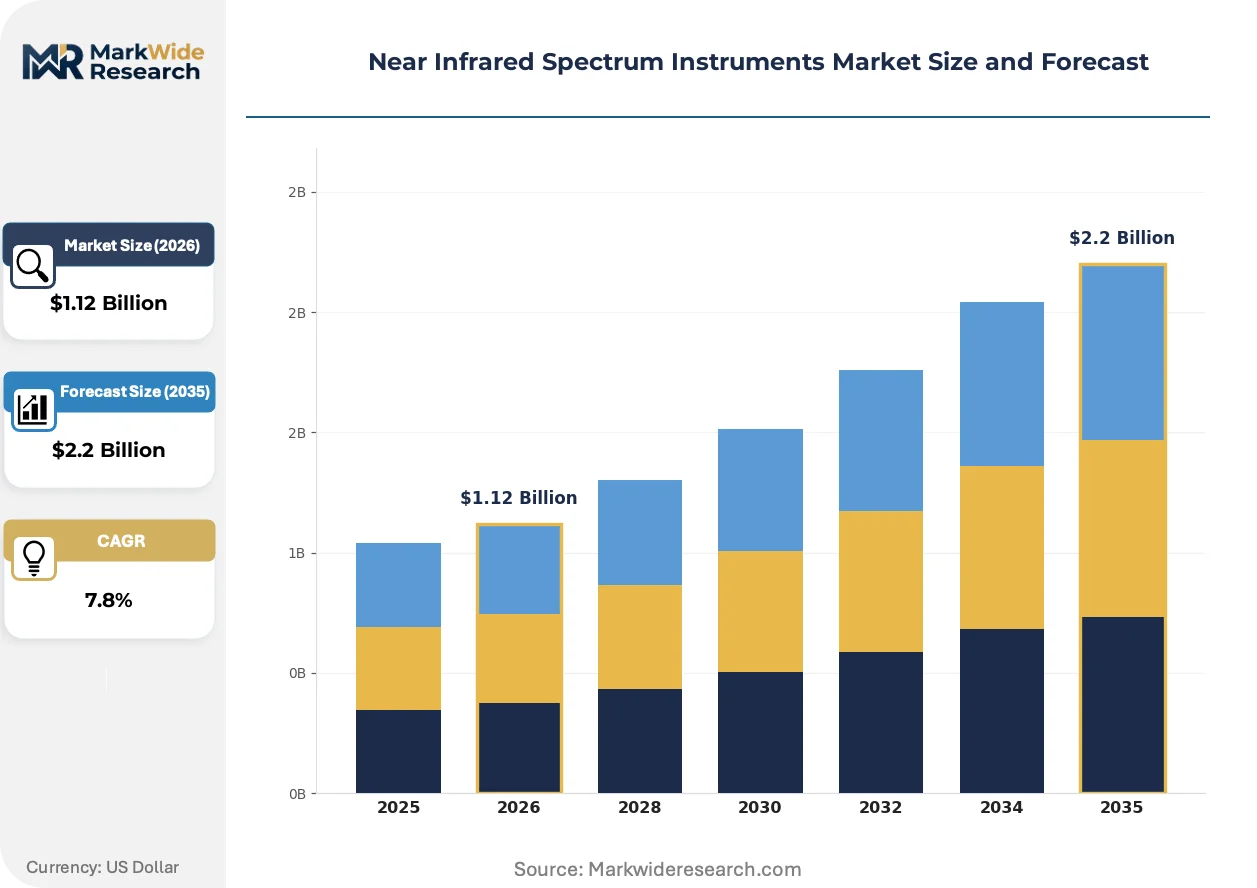
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.2 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Sensors, Imaging Systems, Analyzers Technology: Fourier Transform, Photonic, Multispectral, Hyperspectral End User: Agriculture, Pharmaceutical, Food & Beverage, Environmental Application: Quality Control, Process Monitoring, Research & Development, Medical Diagnostics |
| Companies Covered | Thermo Fisher Scientific Inc., Bruker Corporation, PerkinElmer Inc., Agilent Technologies Inc., FOSS, Shimadzu Corporation, ABB Ltd., Metrohm AG, Malvern Panalytical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near Infrared Spectrum Instruments Market Trends and Innovations
Miniaturization and cloud connectivity are converging to redefine instrument form factors and service delivery models. These developments are compressing the traditional boundaries between laboratory, at-line, and process environments.
MEMS-based scanning grating spectrometers are overtaking conventional moving-grating designs in portable and handheld applications. Food safety inspectors and agricultural procurement officers are adopting these solid-state units for field-based compositional screening. The shift is compressing the addressable market for benchtop laboratory systems while expanding total instrument volume through lower price points.
EMA's updated reflection paper on real-time release testing is tightening validation documentation requirements for NIR-based analytical procedures. Pharmaceutical sponsors must now submit enhanced robustness studies demonstrating model performance across intentional manufacturing variations. German and Swiss contract manufacturers are responding by investing in dedicated chemometric development teams and external statistical consulting relationships.
Service unbundling is fragmenting the traditional instrument-plus-support contract model. Large pharmaceutical buyers are separating hardware procurement from application development and ongoing model maintenance, engaging specialized third-party chemometric consultancies for calibration lifecycle management. This pattern is most pronounced among mid-sized generic drug producers in the United States seeking to reduce captive analytical headcount.
Near Infrared Spectrum Instruments Market Segmentation
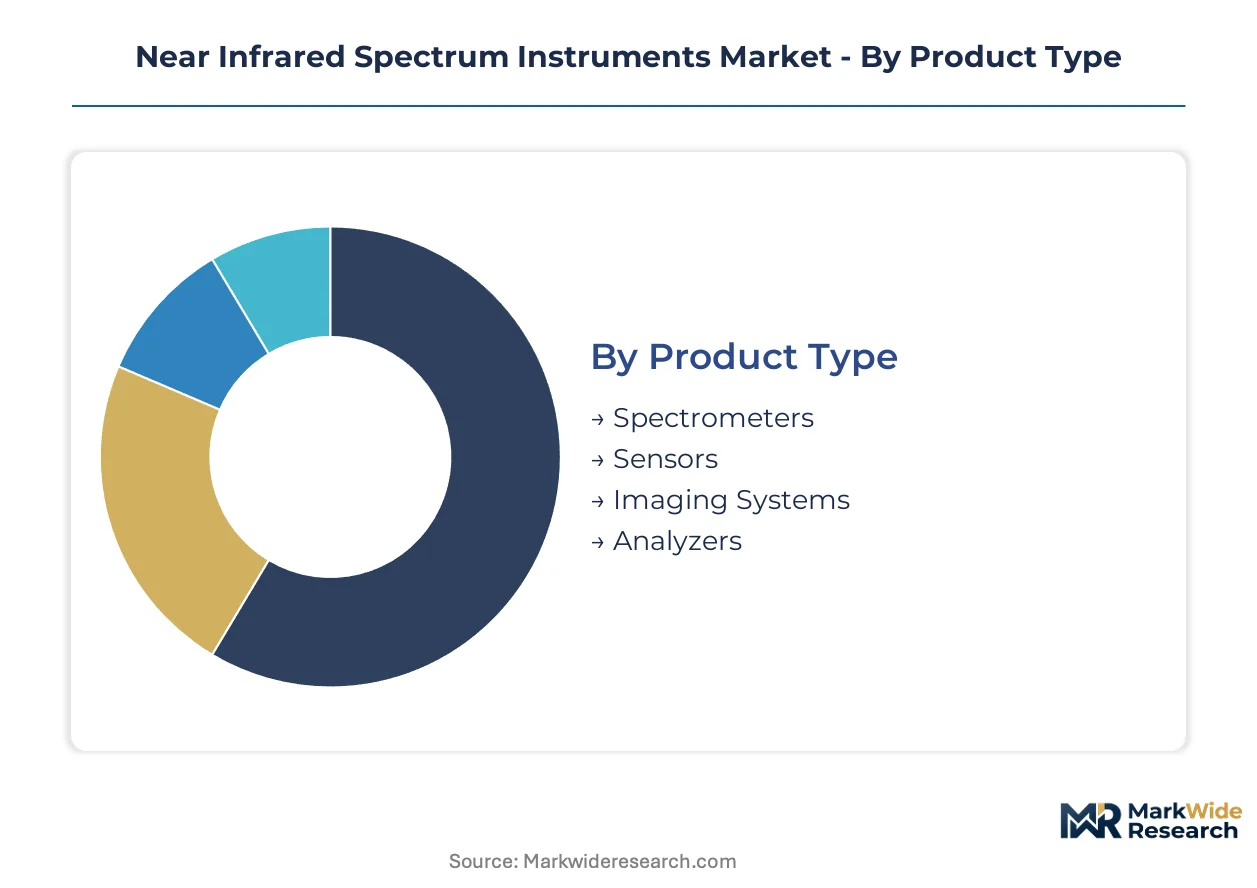
Near infrared spectrum instruments serve divergent capital deployment profiles across product architectures, with laboratory-grade Fourier-transform platforms demanding substantially higher upfront investment than field-deployable photonic sensors. Understanding these capital-intensity gradients enables procurement teams to align instrument specifications with validation requirements and total cost-of-ownership targets.
Product Type:
Capital intensity varies sharply across this category, with hyperspectral imaging systems requiring the most substantial upfront investment due to detector array costs and precision optomechanical assemblies.
- Spectrometers:Benchtop and portable units employing diffraction gratings or interferometers for broadband molecular analysis. German pharmaceutical clusters in Ludwigshafen and Basel drive procurement of laboratory-grade systems for real-time release testing under EMA guidelines.
- Sensors:Compact single-point detectors optimized for inline process integration with minimal sampling interfaces. Food processors in the Netherlands deploy these for continuous moisture monitoring to satisfy EU Green Deal waste reduction mandates.
- Imaging Systems:Spatially resolved platforms capturing spectral cubes for tablet mapping and grain grading.
- Analyzers:Turnkey systems with embedded chemometric models for specific compositional assays.
Most installed capacity flows through spectrometers. Expansion is steepest in imaging systems.
Technology:
Technology selection dictates maintenance burden and calibration complexity, with Fourier-transform platforms demanding specialized service infrastructure while solid-state photonic architectures reduce field support requirements.
- Fourier Transform:Interferometer-based designs delivering high spectral resolution through Michelson or polarization interferometer configurations. Bruker Corporation anchors European market presence with these platforms for pharmaceutical quality control.
- Photonic:MEMS-based and fixed-grating architectures enabling handheld form factors for agricultural procurement officers across the American Midwest.
- Multispectral:Discrete wavelength selection for targeted compositional screening in food safety applications.
- Hyperspectral:Continuous spectral acquisition with spatial resolution for pharmaceutical tablet mapping and premium agricultural grading.
Technology mix favors Fourier-transform in regulated laboratories. Photonic platforms are climbing the fastest in portable deployments.
End User:
End-user concentration determines pricing power and contract structure, with pharmaceutical buyers unbundling hardware from application support while agricultural purchasers favor bundled instrument-plus-calibration packages.
- Agriculture:Grain elevator operators and dairy cooperatives deploying analyzers for protein, moisture, and fat quantification. USDA protocol modernization across Iowa and Illinois is accelerating automated system adoption.
- Pharmaceutical:Manufacturers implementing inline NIR for FDA process analytical technology compliance and EMA quality-by-design frameworks. German and Swiss contract manufacturers lead European deployment intensity.
- Food & Beverage:Processors monitoring composition and authenticity across production lines.
- Environmental:Monitoring agencies and industrial facilities tracking contaminant levels and process emissions.
Agriculture holds the largest installed base. Pharmaceutical applications are gaining share fastest as PAT mandates tighten.
Application:
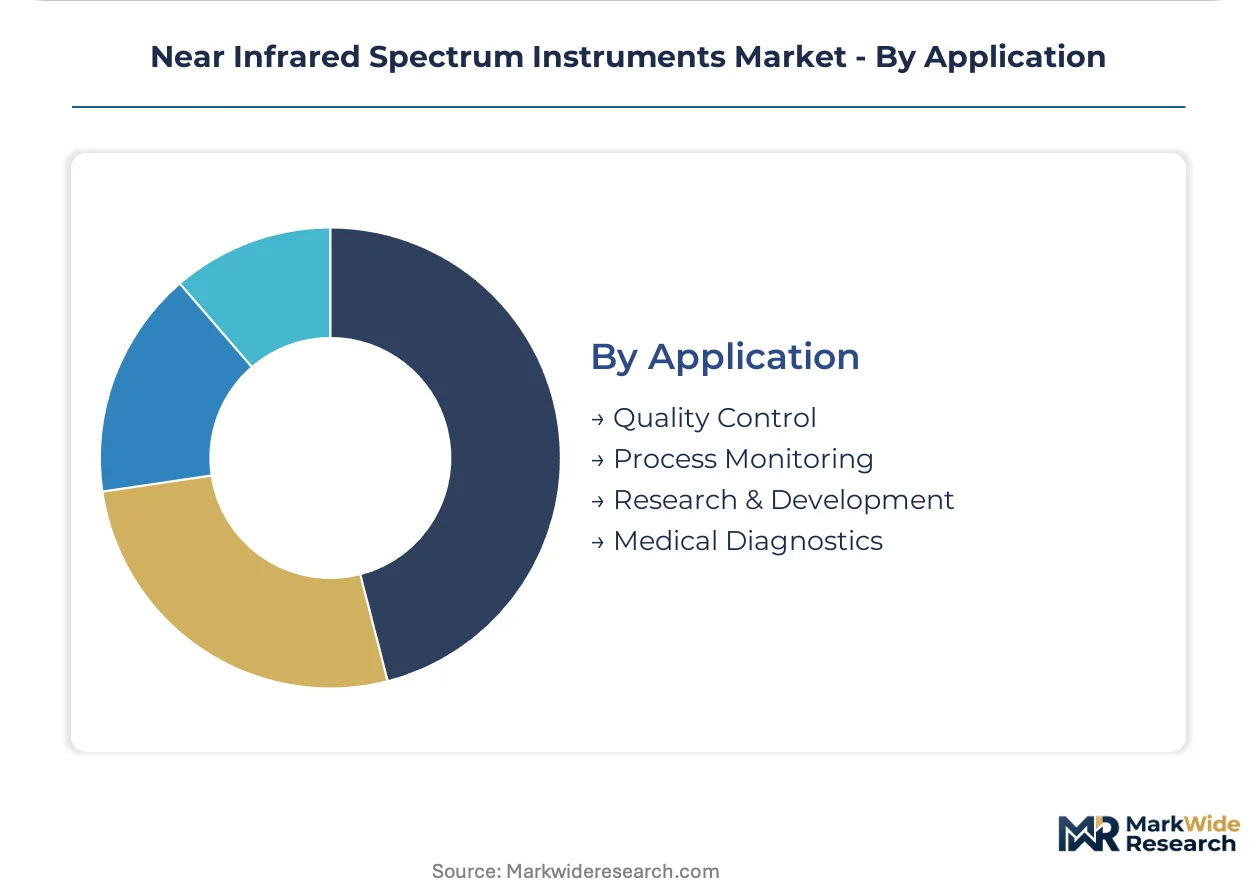
Application context shapes instrument specification, with process monitoring demanding ruggedized hardware and extended validation documentation compared to research laboratory deployments.
- Quality Control:At-line and laboratory testing for raw material identification and finished product verification. Generic drug producers in India are establishing first-time NIR capabilities under CDSCO quality-by-design guidelines.
- Process Monitoring:Inline analyzers for continuous manufacturing with real-time feedback to distributed control systems. FDA submission timelines of 18-24 months constrain vendor revenue recognition in this segment.
- Research & Development:Flexible platforms supporting method development and multivariate calibration studies.
- Medical Diagnostics:Emerging non-invasive glucose monitoring and tissue oxygenation applications.
Quality control absorbs the majority of current installations. Process monitoring shows the steepest expansion trajectory as continuous manufacturing adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The near infrared spectrum instruments industry traces its commercial origins to German optical engineering clusters and Swiss precision manufacturing centers that pioneered Fourier-transform interferometry for pharmaceutical quality control during the 1980s.
Germany
Chemical and pharmaceutical manufacturers in Ludwigshafen and Basel-adjacent Baden-Württemberg drive instrument procurement for real-time release testing. The EU Green Deal mandates inline analyzers for sustainable manufacturing, compressing validation timelines for process deployments. Bavarian contract manufacturers are expanding dedicated chemometric teams to satisfy EMA documentation requirements.
United States
Grain elevator operators across Iowa and Illinois are modernizing inspection infrastructure under USDA protocol revisions. FDA process analytical technology guidelines force pharmaceutical sponsors toward inline NIR systems with 18-24 month qualification periods. Greater Boston biotech clusters are piloting specialized probe configurations for cell therapy bioprocessing applications.
China
Domestic generic drug producers are establishing first-time quality-by-design capabilities under NMPA harmonization with ICH guidelines. The country's national pharmaceutical regulator is tightening real-time monitoring requirements for continuous manufacturing lines. Yangtze River Delta chemical parks are importing European Fourier-transform platforms for process analytical technology compliance.
India
CDSCO quality-by-design guidelines are creating inaugural demand for inline NIR systems among domestic generic manufacturers. Maharashtra and Gujarat pharmaceutical clusters are unbundling hardware procurement from application development, engaging third-party chemometric consultancies. Mumbai-based contract research organizations are building captive calibration lifecycle management capabilities.
Switzerland
Swissmedic oversight of real-time release testing is tightening robustness documentation for NIR-based analytical procedures. Basel-area contract manufacturers are investing in external statistical consulting relationships for model validation. Precision instrumentation heritage in the Jura arc sustains specialized optomechanical assembly expertise for high-resolution systems.
Near Infrared Spectrum Instruments Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth and application specialization, with laboratory-grade Fourier-transform platforms commanding substantially higher upfront investment than field-deployable photonic sensors. The vendor base clusters around three strategic archetypes: diversified life sciences conglomerates with broad distribution networks, specialized analytical instrumentation houses with deep chemometric service capabilities, and regional fabricators focused on cost-optimized portable units. Competitive moves concentrate on technology licensing partnerships for MEMS-based scanning grating designs and backward integration into indium gallium arsenide detector supply channels.
Among diversified analytical instrumentation houses, Bruker Corporation and Thermo Fisher Scientific exemplify contrasting geographic anchoring strategies. Bruker Corporation occupies a position within European pharmaceutical quality control infrastructure, leveraging Fourier-transform platform heritage sustained through Basel-adjacent manufacturing relationships. Thermo Fisher Scientific represents North American life sciences distribution scale, with service unbundling trends fragmenting traditional instrument-plus-support contracts across mid-sized generic drug producers. FOSS sits within the agricultural application specialization tier, anchoring grain and dairy analyzer procurement patterns across American Midwest elevator networks and European food safety inspection regimes.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| PerkinElmer Inc. |
| Agilent Technologies Inc. |
| FOSS |
| Shimadzu Corporation |
| ABB Ltd. |
| Metrohm AG |
| Malvern Panalytical Ltd. |
| Others |
Pricing and Supply Chain Analysis
Indium gallium arsenide substrate costs cascade through detector array pricing tiers, with Japanese and Chinese wafer suppliers feeding premium Fourier-transform laboratory systems while MEMS-based photonic architectures bypass this chokepoint through silicon-compatible designs. Pharmaceutical procurement teams in Germany and Switzerland absorb upstream volatility through long-term service contracts, whereas Midwest grain elevator operators prioritize unit economics in portable analyzer selection.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validation-intensive pharmaceutical platforms from field-deployable agricultural units. Certification grade under EMA and FDA process analytical technology frameworks commands substantial premiums, while volume scale in grain inspection applications compresses per-unit margins. Pricing pressure stems from MEMS-based solid-state designs displacing conventional optomechanical assemblies in portable segments. Generic drug producers in India exhibit highest price sensitivity, whereas Swiss contract manufacturers prioritize analytical robustness over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical demand in Germany and Switzerland, with specialized distributors serving fragmented agricultural buyers across the American Midwest. Manufacturing concentrates in Germany, Switzerland, and Japan for precision interferometer assemblies, while China dominates MEMS foundry capacity for photonic sensors. Indium gallium arsenide substrates, precision gratings, and thermal management components anchor bill-of-materials complexity. Single-source vulnerability in NIR array sensor supply exposes instrument makers to allocation constraints. Distribution runs through life sciences conglomerates with embedded service capabilities in regulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in chemometric service bundling and MEMS platform standardization, with component cost-down trajectories in solid-state architectures enabling premium-tier repositioning.
For Market Incumbents: Anchor market position through backward integration into indium gallium arsenide detector supply channels and captive chemometric model development capabilities. Mid-infrared spectroscopy substitution threatens NIR applications requiring higher molecular specificity. Capacity addition in MEMS-based photonic architectures defends portable segment share against emerging solid-state competitors. For New Entrants and Emerging Players: Enter via India's CDSCO-mandated quality-by-design transition among domestic generic manufacturers, where first-time NIR procurement outpaces established service infrastructure. Cell and gene therapy bioprocessing applications represent penetrable white space requiring specialized probe configurations. Partnership with Mumbai-based contract research organizations accelerates calibration lifecycle management credibility. For Investors and Strategic Acquirers: Consolidation pressure builds where chemometric modeling expertise scarcity constrains pharmaceutical customer retention and service unbundling fragments traditional revenue pools. Long-term viability favors vendors with integrated hardware-chemometric capabilities across the 5-10 year window. Acquisition targets include specialized consultancies with embedded statistical validation relationships. Signal to watch: EMA documentation requirement tightening for real-time release testing robustness studies.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Platform Standardization | Solid-state architectures reduce field support burden for agricultural procurement officers. |
| Chemometric Service Bundling | Integrated model lifecycle management captures recurring revenue from pharmaceutical sponsors. |
| Backward Integration into Detector Supply | Captive indium gallium arsenide sourcing mitigates Japanese and Chinese supplier concentration. |
| Cell Therapy Probe Development | Specialized bioprocessing configurations unlock emerging real-time culture monitoring demand. |
| Digital Twin Integration Partnership | NIR data stream convergence with process simulation enables predictive quality control. |
Research Methodology
Multiple input streams — primary interviews with instrument engineering directors, pharmaceutical analytical development leads, and grain elevator procurement managers; secondary validation through FDA process analytical technology guidance documents, EMA reflection papers, and USDA grain inspection protocol revisions; customs and trade data for NIR component flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against expert panel inputs covering technology mix shifts, end-user concentration changes, and regulatory timeline compressions. Segmentation dimensions modeled include product architecture, technology platform, end-user industry, and application context across the projection horizon. CAGRs were derived from installed base evolution and replacement cycle analysis, with specific weighting for pharmaceutical PAT mandate acceleration and agricultural automation adoption curves.
The model holds under stable regulatory enforcement timelines and intact indium gallium arsenide supply channels; deviation in trade policy restrictions or detector allocation crises would shift instrument availability and pricing trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Portable Gas Chromatograph Market