
 Flashpoint Analyzer Market | 2026-2036
Flashpoint Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Flashpoint Analyzer Market Analysis
REACH is recalibrating the cost-of-entry calculus for flashpoint analyzer vendors serving European petrochemical clients. Anton Paar leverages its Austrian engineering heritage to dominate high-precision automatic closed-cup systems. Grabner Instruments specializes in portable fuel analyzers for military and aviation logistics channels. Koehler Instrument Company anchors North American demand through ASTM-compliant laboratory instrumentation.
A flashpoint analyzer measures the lowest temperature at which a liquid generates sufficient vapor to ignite momentarily under standardized test conditions, typically employing closed-cup or open-cup methods with temperature resolution of 0.1°C. Automatic systems lead installed base value due to throughput advantages in refinery quality control labs, while portable digital units represent the fastest-growing product type as environmental agencies deploy field-based safety screening. Compliance testing applications command premium pricing relative to research and development use cases because failure carries regulatory penalty exposure.
OSHA workplace safety rules, EPA fuel volatility standards, and ASTM D93 test protocols collectively shape product specifications and procurement criteria across the United States. EMA-aligned REACH annexes and F-Gas Regulation indirectly pressure analyzer accuracy requirements through broader chemical handling strictures in Europe. Stakeholders must monitor how evolving GB standards from China's SAMR and dual carbon enforcement timelines alter import qualification pathways for foreign equipment suppliers.
Market Dynamics
Automated closed-cup flashpoint analyzers are absorbing capital allocation from manual open-cup systems as refineries confront throughput mandates and OSHA compliance deadlines. This technology transition concentrates purchasing power among laboratories serving high-volume petrochemical screening.
Growth Catalysts
- REACH chemical safety annexes:European refineries must document flashpoint data for substance registration, forcing analyzer upgrades across Germany, France, and the Netherlands.
- Aviation fuel logistics:Military and commercial airports deploy portable digital units for rapid jet fuel verification before tanker loading.
- GB standard harmonization:China's SAMR alignment with ISO 2719 protocols opens qualification pathways for foreign automatic system suppliers.
Market Restraints
- Platinum sensor supply concentration:Temperature probe manufacturing clusters in Japan and Germany create input cost volatility for high-precision units.
- ASTM D93 calibration complexity:Annual certification requirements extend sales cycles and inflate total cost of ownership for smaller laboratories.
- Alternative predictive modeling:Computational chemistry software for vapor pressure estimation threatens low-end analyzer demand in R&D applications.
Strategic Opportunities
- India petrochemical expansion:Reliance Industries and public sector refineries under BIS fuel quality mandates represent underpenetrated demand for automated systems.
- Battery electrolyte safety screening:Lithium-ion manufacturing lines require flashpoint verification for organic solvent blends, creating a new end-use vertical.
- EPA field monitoring programs:Portable analyzer procurement for Superfund site characterization channels through environmental remediation contractors.
Industry Challenges
- Cross-trained technician scarcity:Refinery laboratories struggle to hire personnel proficient in both ASTM protocols and digital system diagnostics.
- Legacy LIMS integration:Automatic analyzers must interface with 1990s-era laboratory information management systems common in North American facilities.
- CE-GB dual certification timelines:Equipment suppliers face 14-18 month approval cycles for simultaneous European and Chinese market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flashpoint Analyzer Market |
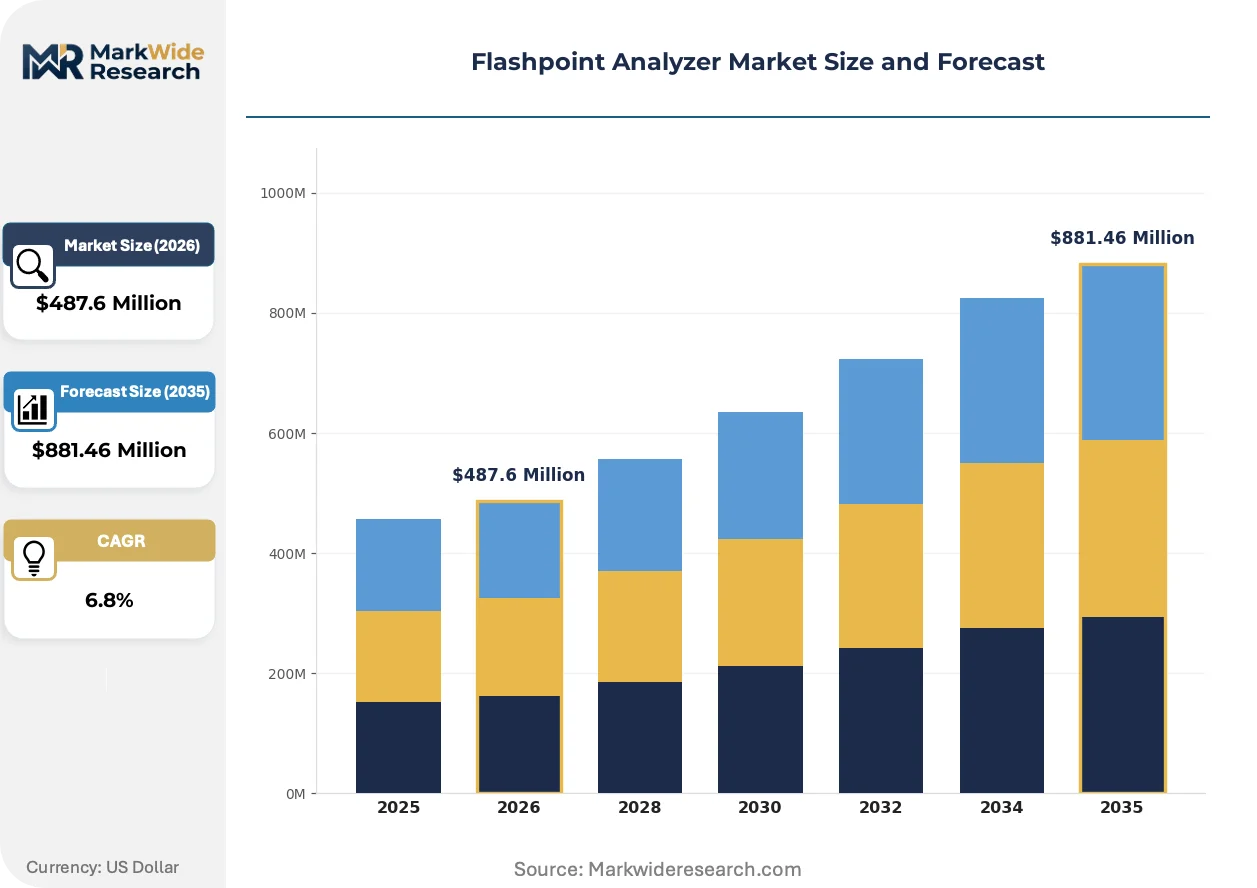
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
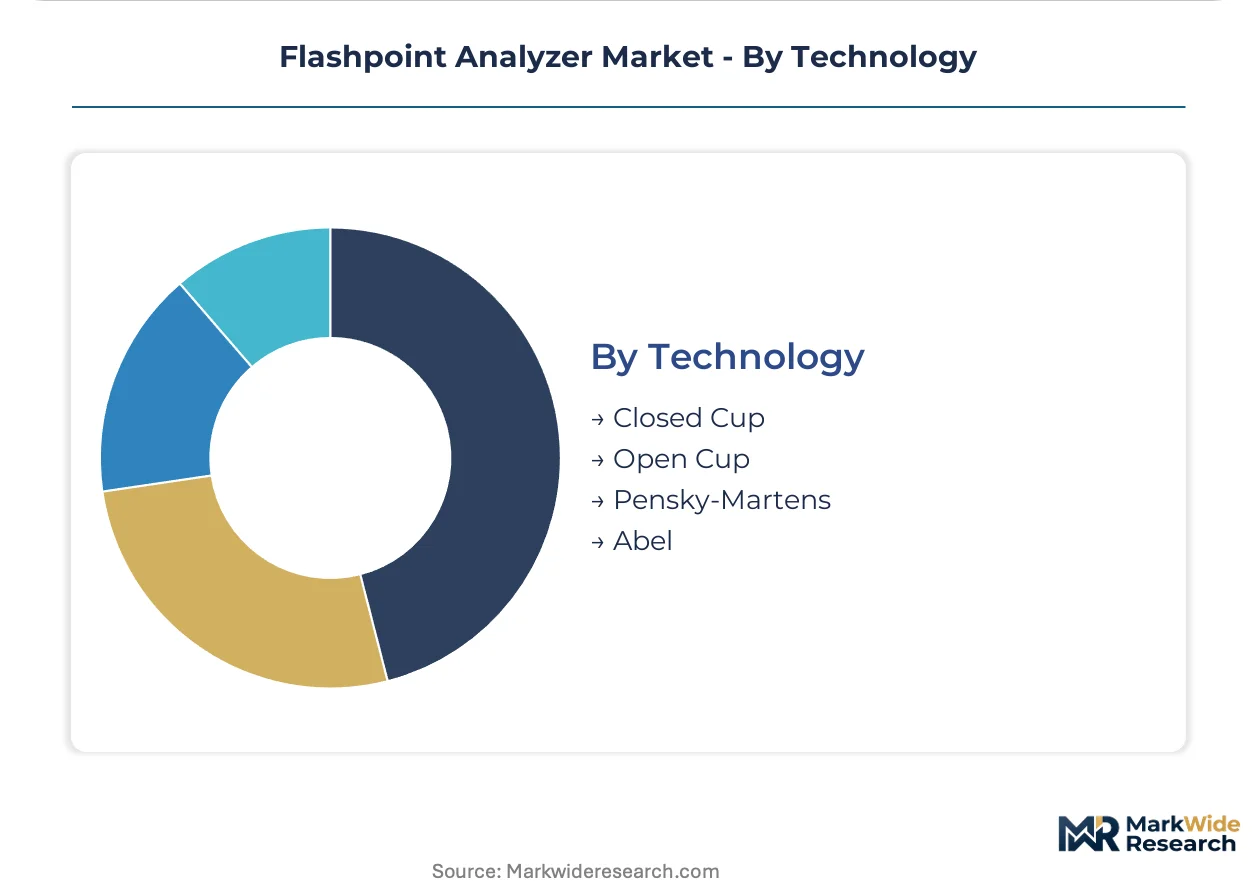
| Segmentation | Product Type: Manual, Automatic, Digital, Portable End User: Laboratories, Petrochemical, Food Industry, Environmental Agencies Application: Quality Control, Safety Testing, Research & Development, Compliance Testing Technology: Closed Cup, Open Cup, Pensky-Martens, Abel |
| Companies Covered | Anton Paar, Grabner Instruments, Koehler Instrument Company, PAC, ERALYTICS, NORMALAB, Cannon Instrument Company, Seta, Labtron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flashpoint Analyzer Market Emerging Trajectories
Digital sensing architectures are compressing the performance gap between laboratory-grade and portable flashpoint analyzers. This convergence is redrawing procurement criteria across environmental monitoring, fuel logistics, and quality control applications.
Microprocessor-controlled closed-cup systems with integrated barometric pressure compensation are absorbing market share from traditional manual Pensky-Martens apparatus. Refinery quality control laboratories in Texas and Rotterdam adopt these units to eliminate operator variability. The technology is absorbing calibration labor costs while compressing test cycle times from 30 minutes to under 12 minutes per sample.
EPA fuel volatility standards under 40 CFR Part 80 are tightening reproducibility requirements for flashpoint documentation. This regulatory pressure forces analyzer vendors to embed automated data logging with tamper-evident timestamps. Portable units deployed for gasoline station compliance screening in California and the Northeast face the strictest audit trail mandates.
Environmental agencies now bundle flashpoint screening with broader contaminant characterization workflows. Field contractors in the United States and Germany purchase multi-parameter portable units rather than single-purpose analyzers. This purchasing consolidation favors vendors offering modular sensor platforms with interchangeable test cups for flashpoint, vapor pressure, and density measurement.
Flashpoint Analyzer Market Segmentation
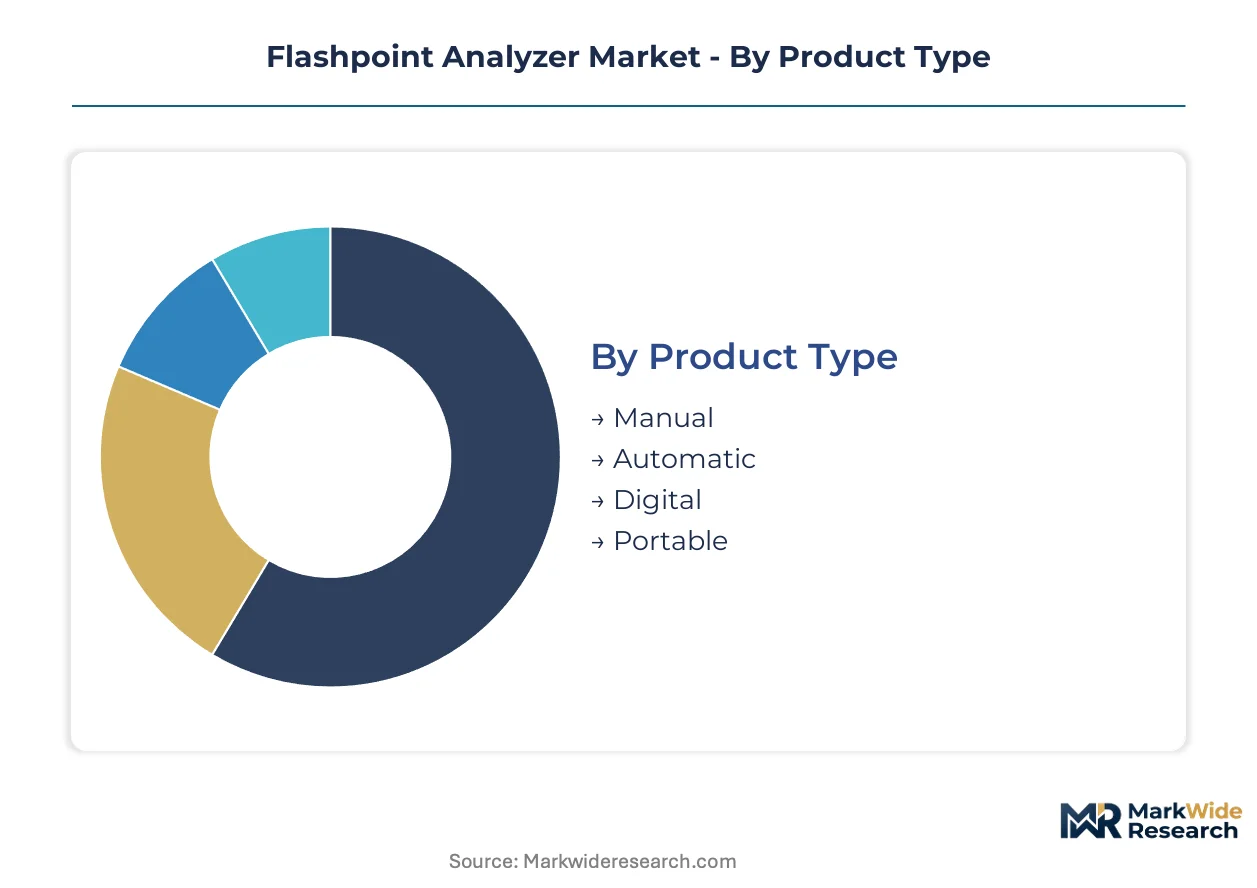
Flashpoint analyzer procurement diverges sharply across operational environments, with refinery laboratories prioritizing throughput automation while field contractors trade precision for portability. Understanding these segment boundaries clarifies why vendors maintain parallel product architectures rather than unified platforms.
Product Type:
Standardization dominates at the laboratory tier where ASTM D93 protocols mandate reproducible test conditions, while field applications tolerate calibration drift in exchange for rapid deployment.
- Automatic:Microprocessor-controlled closed-cup systems with integrated barometric compensation eliminate operator variability in high-volume refinery quality control labs. Texas and Rotterdam facilities absorb these units to compress test cycles from thirty minutes to under twelve minutes per sample. Leading the category by volume: Automatic. Growing fastest: Portable.
- Portable:Battery-powered digital units with simplified ignition detection circuits serve military aviation logistics and EPA Superfund site characterization. California environmental contractors procure these for gasoline station compliance screening where audit trail mandates are strictest.
- Manual:Traditional Pensky-Martens apparatus persists in smaller laboratories with limited capital budgets and low sample throughput requirements.
- Digital:Hybrid architectures bridging laboratory precision with field connectivity target mid-tier environmental agencies upgrading from legacy analog systems.
Automatic systems command the installed base value share. Portable units are expanding most quickly as environmental monitoring decentralizes.
End User:
Margin profiles invert across this category: petrochemical procurement emphasizes total cost of ownership over upfront capital, while environmental agencies optimize for single-unit acquisition cost.
- Petrochemical:Refinery quality control laboratories in the United States, Germany, and China drive demand for high-throughput closed-cup systems under tightening OSHA, REACH, and GB fire safety mandates. Reliance Industries and Indian public sector refineries represent underpenetrated demand under BIS fuel quality standards.
- Laboratories:Independent testing facilities and research institutes require ASTM-compliant instrumentation with documented traceability chains for regulatory submission.
- Environmental Agencies:EPA field monitoring programs and German state environmental offices procure portable multi-parameter units bundling flashpoint screening with vapor pressure and density measurement.
- Food Industry:Edible oil processors and flavoring compound manufacturers employ flashpoint verification for solvent-based extraction safety protocols.
Petrochemical end users dominate capital deployment. Environmental agencies are gaining share fastest as field-based screening programs expand.
Application:
Compliance testing carries premium pricing relative to R&D use cases because failure carries regulatory penalty exposure and mandatory retest costs.
- Compliance Testing:Mandatory documentation for REACH substance registration, EPA fuel volatility standards under 40 CFR Part 80, and aviation fuel logistics verification. Refineries face forced analyzer upgrades when registration deadlines approach.
- Quality Control:Continuous batch verification in petrochemical production lines where flashpoint drift indicates feedstock contamination or process deviation.
- Safety Testing:Pre-shipment verification for hazardous material classification under DOT and IATA shipping regulations.
- Research & Development:Formulation screening for new solvent blends and battery electrolyte organic components, threatened by computational chemistry vapor pressure modeling.
Compliance testing anchors revenue concentration. Battery electrolyte safety screening within R&D shows the steepest expansion trajectory.
Technology:
Closed-cup methods are displacing open-cup architectures as regulatory reproducibility requirements tighten and barometric compensation becomes standard.
- Closed Cup:Sealed test environment with controlled vapor-air mixture ignition under ASTM D93, ISO 2719, and GB/T 261 protocols. Microprocessor-controlled variants absorb market share from manual apparatus in refinery laboratories.
- Pensky-Martens:Specific closed-cup implementation with stirrer mechanism for viscous samples, dominant in heavy fuel oil and bitumen testing applications.
- Abel:Modified closed-cup method for low-flashpoint materials including aviation fuels and light distillates, specified in UK and Commonwealth regulatory frameworks.
- Open Cup:Cleveland and Tag methods persisting in educational settings and jurisdictions with legacy regulatory recognition, losing share to closed-cup standardization.
Closed Cup leads by installed base. Pensky-Martens variants are climbing the fastest as heavy fuel testing requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical refining capacity concentrates in coastal industrial corridors where fire safety mandates drive analyzer procurement. Regulatory deadlines in the United States, Germany, and China compress upgrade cycles for quality control laboratories.
United States
Gulf Coast refineries in Texas and Louisiana deploy automated closed-cup systems to meet OSHA process safety management deadlines. EPA fuel volatility standards under 40 CFR Part 80 mandate tamper-evident data logging for gasoline station compliance screening. Houston-area quality control laboratories absorb microprocessor-controlled units to eliminate operator variability in high-throughput environments.
Germany
REACH chemical safety annexes force analyzer upgrades across BASF and Bayer supply chain facilities in Ludwigshafen and Leverkusen. ECHA substance registration requirements document flashpoint data for solvent imports from Asia. Rotterdam-adjacent refineries in the Rhine-Ruhr corridor adopt barometric compensation systems to compress test cycles below twelve minutes per sample.
China
Sinopec and PetroChina refineries in the Yangtze River Delta confront GB standard harmonization with ISO 2719 protocols under SAMR oversight. Dual carbon enforcement timelines accelerate replacement of manual Pensky-Martens apparatus in Shanghai and Ningbo laboratories. Foreign automatic system suppliers navigate 14-18 month dual certification cycles for CE-GB market entry.
India
Reliance Industries and public sector refineries under BIS fuel quality mandates represent underpenetrated demand for automated systems. The Jamnagar refinery complex and Mumbai-Pune industrial corridor drive procurement for high-throughput compliance testing. DGFT import qualification pathways favor suppliers with documented ASTM D93 calibration chains.
Japan
JX Nippon Oil & Energy and Idemitsu Kosan facilities in the Keihin industrial zone maintain precision standards for export fuel certification. METI technical regulations align with ASTM protocols for aviation fuel logistics verification. Yokkaichi refinery laboratories absorb platinum-sensor automatic systems despite input cost volatility from domestic probe manufacturing concentration.
Flashpoint Analyzer Market Vendor Landscape
European engineering houses anchor the precision-tier; North American instrumentation specialists hold the compliance-documentation tier. The vendor base organizes around three strategic archetypes: Austrian-German precision engineering firms, US-based ASTM certification anchors, and portable-digital specialists serving military-aviation channels. Competitive moves concentrate on strategic partnerships with refinery LIMS integrators and geographic expansion into Indian petrochemical greenfield projects.
Within the precision-engineering tier, Anton Paar GmbH exemplifies Austrian heritage in automatic closed-cup system architecture. Grabner Instruments occupies a position among portable fuel analyzer specialists serving military logistics channels. Koehler Instrument Company anchors North American demand through laboratory instrumentation compliance with ASTM protocols. These three firms represent distinct competitive vectors: heritage engineering, field-portable specialization, and regulatory-certification anchoring.
| Leading Market Players |
|---|
| Anton Paar |
| Grabner Instruments |
| Koehler Instrument Company |
| PAC |
| ERALYTICS |
| NORMALAB |
| Cannon Instrument Company |
| Seta |
| Labtron |
| Others |
Supply Flow & Price Mechanics
Microprocessor-controlled closed-cup architecture migration is compressing unit economics while concentrating procurement leverage among high-volume refinery laboratories in Texas, Rotterdam, and Shanghai. This technology shift simultaneously elevates precision requirements and eliminates manual-system vendors from premium-tier competition, reshaping margin distribution across the supplier base.
Pricing Analysis
Volume procurement by petrochemical refineries commands standard-tier pricing, while environmental agencies and military aviation channels absorb premium markups for portable digital units with embedded audit trails. Price differentiation hinges on ASTM D93 certification grade and after-sales calibration service bundling. Cost compression in the manual-system tier is intensifying because computational chemistry substitutes threaten low-end R&D demand. Smaller independent laboratories exhibit the highest price sensitivity, whereas integrated refinery quality control operations prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
CE-GB dual certification gating stretches qualification timelines to 14-18 months, concentrating supply leverage among incumbent vendors with established regulatory dossiers. Temperature probe manufacturing clusters in Japan and Germany, with final assembly anchoring in Austria and the United States. Platinum sensor supply concentration creates single-source vulnerability for high-precision automatic systems. Distribution runs through direct refinery LIMS integrator relationships and environmental remediation contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platinum sensor manufacturing concentration in Japan and Germany props pricing power for precision-tier automatic systems, constraining capacity expansion for new entrants lacking established component sourcing relationships.
For Market Incumbents: Lock in backward integration into platinum temperature probe supply through long-term offtake agreements with Japanese sensor manufacturers. Defend position against portable-digital specialists by embedding ASTM D93 calibration automation within legacy LIMS integration workflows, raising switching costs for refinery quality control laboratories. For New Entrants and Emerging Players: Enter via battery electrolyte safety screening verticals in lithium-ion manufacturing corridors, where flashpoint verification protocols remain underdeveloped. Target Indian petrochemical expansion under BIS fuel quality mandates as the most penetrable geography, deploying ASTM-compliant automatic systems through DGFT-qualified import channels with documented calibration traceability. For Investors and Strategic Acquirers: Exit pathways concentrate in precision-engineering acquisitions by industrial instrumentation conglomerates seeking REACH-compliant European positioning. Long-term viability favors vendors with captive platinum sensor supply and dual CE-GB certification capabilities. Watch EPA field monitoring program procurement acceleration as the inflection signal for portable digital unit demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive platinum probe manufacturing secures margin control against Japanese-German supply concentration. |
| Dual Certification Investment | Simultaneous CE-GB qualification opens parallel European and Chinese refinery procurement channels. |
| LIMS Integration Partnership | Embedded connectivity with 1990s-era laboratory systems raises incumbent switching costs. |
| Battery Electrolyte Vertical Entry | Lithium-ion solvent safety protocols create unclaimed demand outside traditional petrochemical channels. |
| Field Monitoring Channel Development | EPA Superfund contractor relationships position portable units for decentralized environmental screening. |
Methodological Framework
Multi-period observation of refinery capital expenditure cycles, ASTM D93 certification timelines, and platinum sensor import volumes anchored the trend analysis, supplemented by interviews with quality control laboratory directors, petrochemical procurement leads, environmental agency field contractors, and LIMS integration specialists. Secondary validation drew from EPA fuel volatility enforcement data, ECHA substance registration filings, SAMR GB standard harmonization notices, and customs records of automatic analyzer trade flows. Bottom-up unit deployment tracking across Texas, Rotterdam, and Shanghai facilities triangulated against top-down petrochemical refining capacity estimates.
Input-output matrices mapped automatic, portable, manual, and digital product architectures against petrochemical, laboratory, environmental agency, and food industry end-use segments. Modeled dimensions spanned test method technology, compliance versus R&D application intensity, and regional regulatory framework clusters. CAGRs were derived from installed base replacement cycles and greenfield refinery project pipelines. Forecast inputs incorporated REACH registration deadline phasing, OSHA process safety management compliance windows, and dual carbon enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under platinum supply disruption or accelerated computational chemistry substitution in R&D applications. A model refresh is warranted upon material change in EPA field monitoring program funding or SAMR GB standard implementation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Melt Flow Meter Market