
 Sleeping Pods Market | 2026-2036
Sleeping Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeping Pods Market Outlook
Market Context
Ergonomic certification tiers is unwinding price compression across the competitive landscape. Minute Suites, LLC leverages its airport concession expertise to dominate gate-adjacent locations. YOTEL LIMITED anchors urban micro-hotel concepts with integrated pod installations. GoSleep OY specializes in aviation-grade acoustic engineering for high-traffic terminals.
Technical Definition and Segments
Sleeping pods are enclosed, climate-controlled rest enclosures engineered with sound-dampening composites, adjustable recline mechanisms, and occupancy sensors for commercial and institutional deployment. Their primary purpose is delivering restorative micro-sleep intervals in space-constrained environments where traditional hotel access proves impractical. Portable pods lead volume shipments due to lower installation friction and lease flexibility, while modular systems capture premium margin pools through scalable campus deployments. Smart control systems represent the fastest-growing technology segment as IoT integration enables usage analytics and predictive maintenance.
Regulatory Framework
OSHA workplace rest guidelines, ISO ergonomic standards, and FAA airport concession regulations collectively shape product compliance thresholds and market access conditions. OSHA guidelines mandate adequate rest facilities in continuous-operation workplaces, directly expanding corporate office demand. Stakeholders must monitor evolving fire safety codes for enclosed furniture and building occupancy classifications as jurisdictions update commercial space regulations.
Market Dynamics
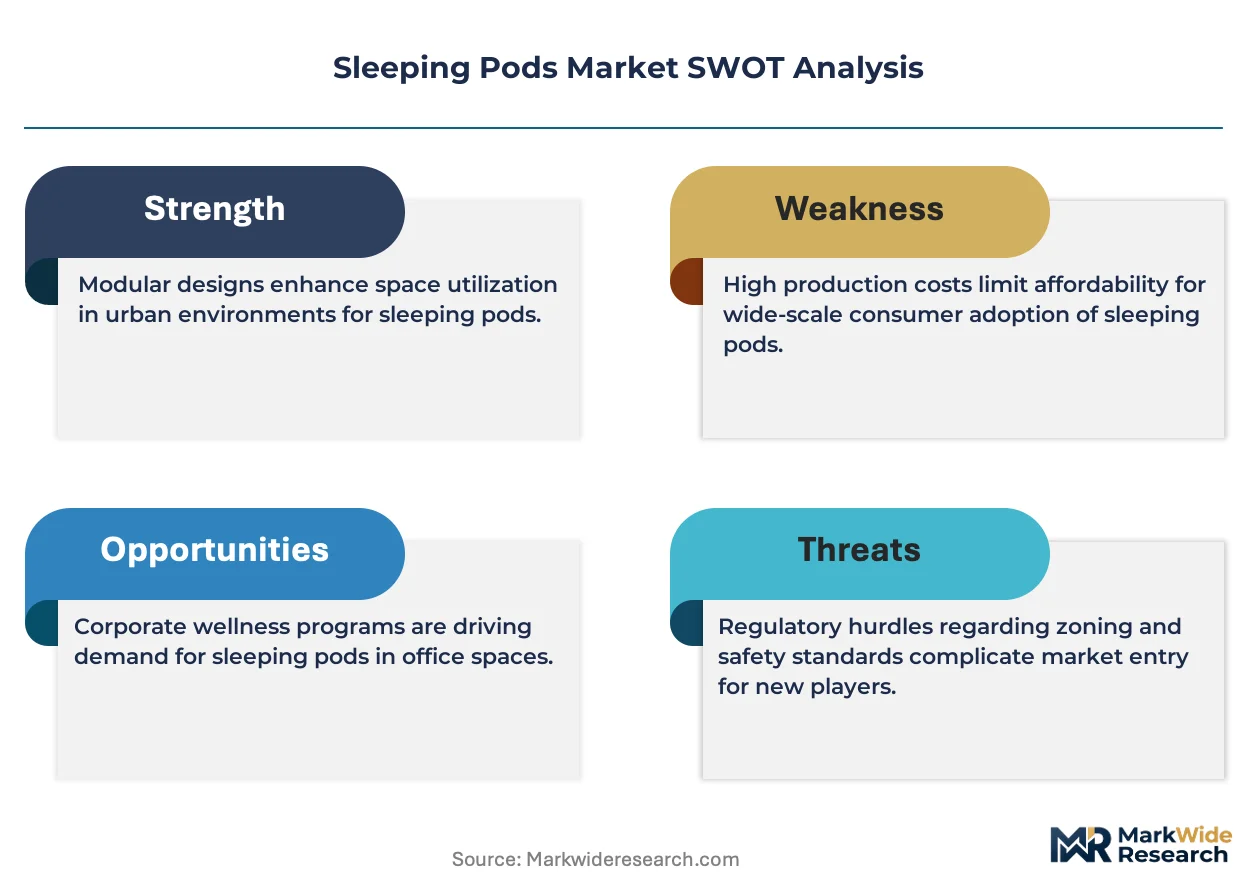
ISO ergonomic certification requirements are compressing competitive margins while creating tiered product positioning across commercial and institutional channels. Employers now mandate certified rest facilities as OSHA workplace guidelines harden into procurement specifications.
Growth Catalysts
- OSHA Workplace Rest Mandates:Continuous-operation employers must provide adequate rest facilities, directly expanding corporate office installations and campus deployments.
- Aviation Hub Expansions:Gate-adjacent concession spaces at major US airports are converting to pod-based micro-rest concepts to capture stranded passenger dwell time.
- IoT-Enabled Predictive Maintenance:Smart control systems with occupancy analytics reduce downtime and extend asset life across high-traffic terminal environments.
Market Restraints
- Acoustic Composite Supply Concentration:Aviation-grade sound-dampening materials depend on a limited supplier base concentrated in East Asian manufacturing clusters.
- Fire Safety Code Fragmentation:Jurisdictional variation in enclosed furniture classification creates compliance friction and delays multi-site rollouts.
- Traditional Hotel Substitution:Extended-stay properties and airport hotels compete for the same traveler rest budgets with established brand recognition.
Strategic Opportunities
- Healthcare Facility Underpenetration:Hospital staff rest rooms and clinician overnight quarters represent an untapped installation channel with 24-hour operational requirements.
- EU CSRD Wellness Reporting:Corporate sustainability disclosure mandates create procurement tailwinds for measurable workforce rest infrastructure investments.
- Modular Campus Scalability:Tech headquarters and co-working networks favor expandable pod systems over fixed construction for workforce amenity programs.
Industry Challenges
- ISO Ergonomic Certification Timelines:Multi-stage testing protocols for adjustable recline mechanisms and climate control systems delay product launches by 8-14 months.
- Legacy Building System Integration:HVAC and electrical retrofits in older commercial structures complicate climate-controlled enclosure deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeping Pods Market |
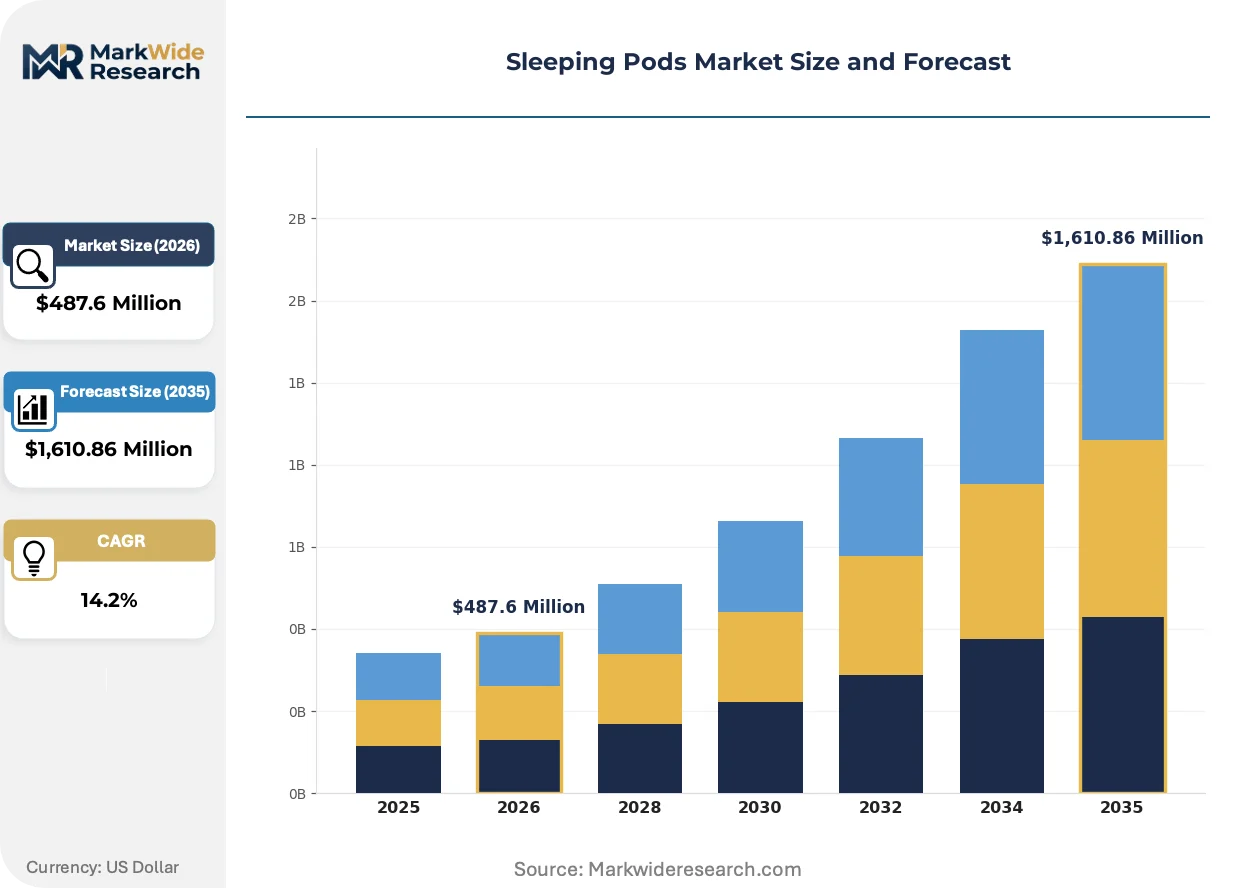
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pods, Wall-Mounted Units, Modular Systems, Acoustic Pods End User: Corporate Offices, Airports, Hospitals, Universities Technology: Smart Control Systems, Noise Reduction Technology, Ergonomic Design, Energy-Efficient Lighting Installation Type: Standalone, Integrated, Mobile, Custom-Fitted |
| Companies Covered | Minute Suites, LLC, YOTEL LIMITED, GoSleep OY, Podtime Pty Ltd., DreamPod Europe Ltd., Napcabs GmbH, MetroNaps Inc., Nine Hours Co., Ltd., Sleepbox LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeping Pods Market Strategic Shifts
Smart sensor integration and acoustic engineering advances are redefining product differentiation beyond basic enclosure design. Vendors now compete on data-enabled operational efficiency and occupant biometric feedback.
Biometric sleep monitoring systems embedded in pod control interfaces track heart rate variability and micro-movement patterns to optimize rest cycle timing. Corporate wellness programs at Fortune 500 headquarters are piloting these systems for workforce recovery analytics. This convergence of sleep science and IoT hardware is decomposing the traditional price-based procurement model into outcome-measured service contracts.
The FAA is revising airport concession regulations to explicitly recognize sleep pod installations as eligible for gate-adjacent retail space allocation. This regulatory clarity accelerates lease negotiations and standardizes fire safety compliance thresholds. Terminal operators in the United States are responding by converting underutilized hold room areas into pod-based revenue centers.
Facility managers now bundle pod access into broader workplace amenity subscriptions rather than capitalizing standalone installations. This shift compresses vendor sales cycles and transfers utilization risk to operators. The model is most visible in San Francisco Bay Area tech campuses where landlord-tenant service agreements increasingly specify rest infrastructure as standard Class A office provisions.
Sleeping Pods Market Segmentation
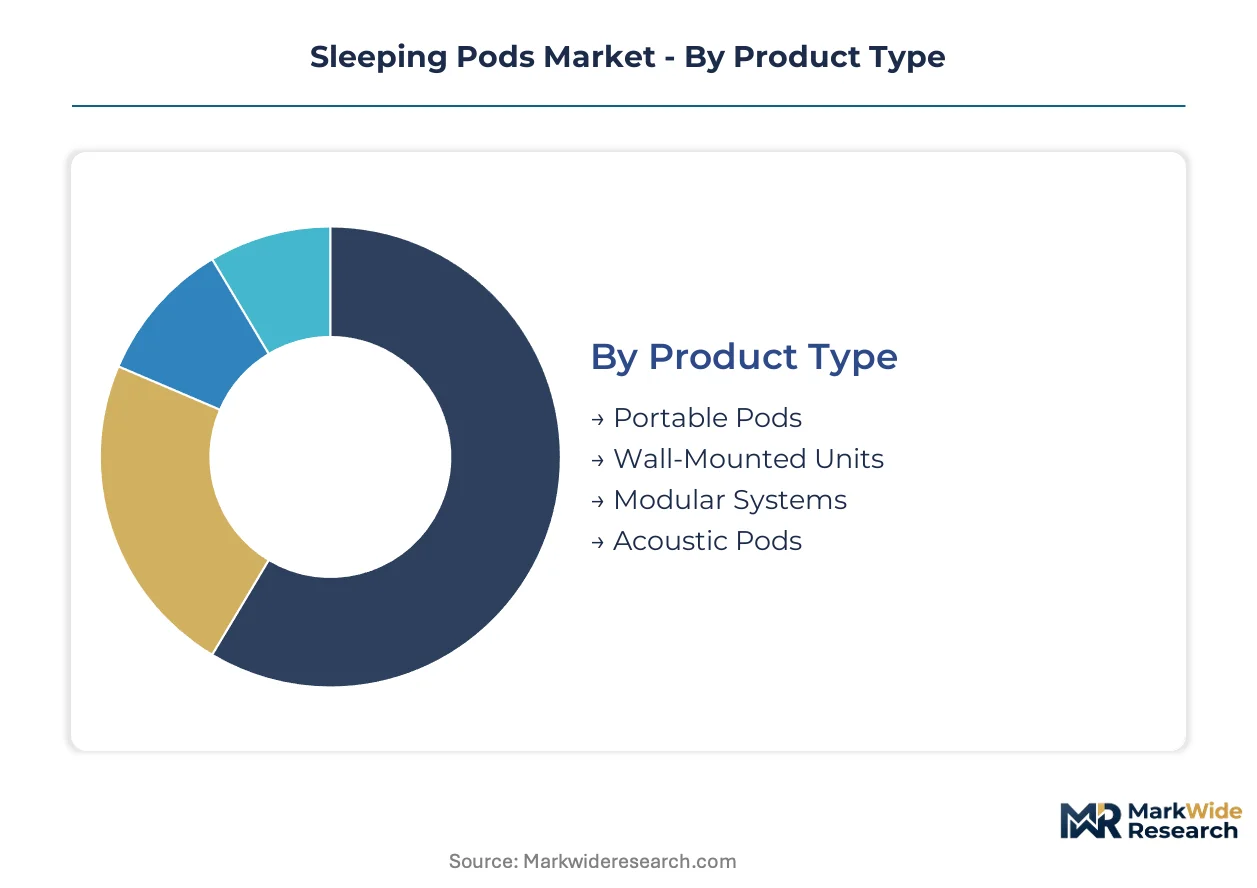
Sleeping pod segmentation reveals divergent competitive pressures across form factors and deployment contexts. Product architecture and installation constraints determine which segments face displacement from traditional hotel properties versus protected niche positions.
Product Type:
Portable pods encounter the strongest substitution threat from extended-stay hotels, while fixed installations benefit from space constraints that rule out conventional alternatives.
- Portable Pods:Self-contained units with wheeled bases and plug-and-play electrical connections enable rapid repositioning across corporate campuses. Demand concentrates in United States tech headquarters where lease flexibility and relocation frequency outweigh permanent build-out costs; OSHA workplace rest mandates accelerate procurement specifications for these low-friction deployments.
- Modular Systems:Scalable pod arrays with shared HVAC infrastructure and centralized control nodes support campus-wide workforce amenity programs. United States airport hub expansions favor these configurations for gate-adjacent micro-rest concepts; FAA concession regulation revisions clarify lease eligibility and compress approval timelines for terminal operators.
- Wall-Mounted Units:Fixed enclosures anchored to structural walls optimize floor space in constrained urban offices.
- Acoustic Pods:Aviation-grade composite enclosures engineered for high-traffic terminal environments with extreme noise dampening requirements.
Portable pods retain volume leadership; modular systems hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich institutional buyers from budget-constrained facility operators.
- Airports:Gate-adjacent concession operators deploy pods to monetize stranded passenger dwell time during extended layovers. United States terminal expansions at Atlanta, Denver, and Dallas-Fort Worth drive installation volumes; FAA regulatory clarity on concession eligibility accelerates lease negotiations and standardizes fire safety compliance.
- Corporate Offices:Fortune 500 headquarters and Class A office landlords integrate pods into workforce wellness amenity subscriptions. San Francisco Bay Area tech campuses lead adoption; ISO ergonomic certification requirements harden into procurement specifications as OSHA guidelines mandate adequate rest facilities.
- Hospitals:Clinical staff rest rooms and overnight quarters for rotating physicians represent emerging demand with 24-hour operational requirements.
- Universities:Campus libraries and student centers pilot pod installations for commuter student populations.
Corporate offices command premium pricing tiers; airports generate the highest unit volumes through concession density.
Technology:
Application-specific performance requirements separate biometric-enabled systems from basic enclosure specifications.
- Smart Control Systems:IoT-enabled occupancy sensors, usage analytics dashboards, and predictive maintenance algorithms reduce downtime across high-traffic deployments. United States airport terminals prioritize these systems for revenue optimization; biometric sleep monitoring pilots at corporate headquarters are decomposing price-based procurement into outcome-measured service contracts.
- Noise Reduction Technology:Multi-layer acoustic composites and active cancellation systems achieve aviation-grade sound isolation. East Asian manufacturing concentration for specialized materials creates supply vulnerability; limited supplier base compresses margins for vendors without captive composite sourcing.
- Ergonomic Design:Adjustable recline mechanisms and climate control interfaces require ISO certification testing protocols.
- Energy-Efficient Lighting:Circadian-aligned LED systems support micro-sleep cycle optimization.
Smart control systems are gaining share fastest; noise reduction technology anchors premium positioning.
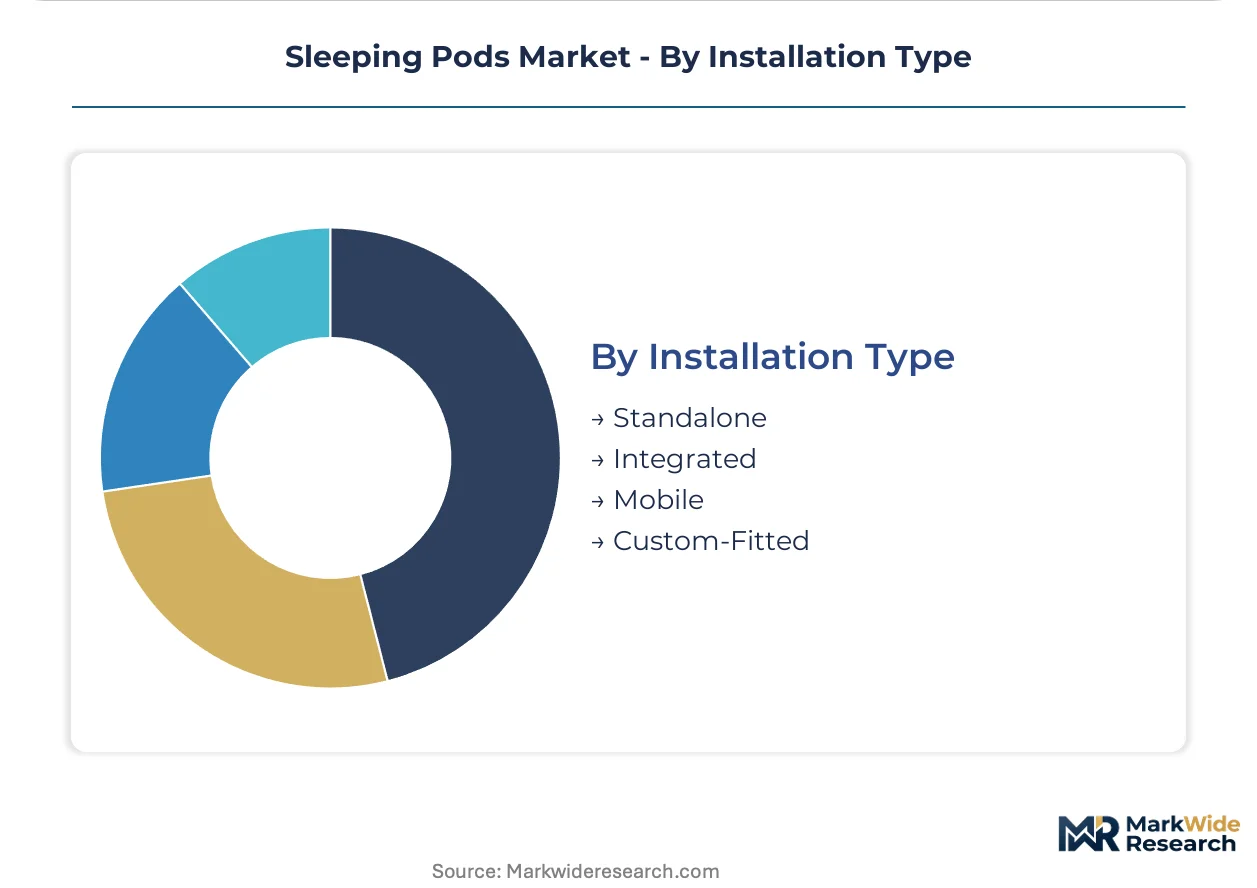
Installation Type:
Customer type segmentation distinguishes capital owners from service-oriented operators with divergent risk appetites.
- Standalone:Self-sufficient units with independent power and climate systems bypass legacy building infrastructure constraints. United States retrofit markets favor these configurations where HVAC integration proves cost-prohibitive; facility managers bundle access into amenity subscriptions rather than capitalizing purchases.
- Integrated:Hardwired connections to building management systems enable centralized monitoring and energy optimization. New construction projects in United States tech campuses specify these installations; landlord-tenant service agreements increasingly mandate rest infrastructure as standard Class A provisions.
- Mobile:Battery-powered and wireless units support temporary event deployments and seasonal demand spikes.
- Custom-Fitted:Bespoke dimensions and finishes for branded hospitality environments and flagship corporate installations.
Standalone installations dominate retrofit volume; integrated systems capture new construction specification share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export volumes of aviation-grade acoustic composites concentrate in East Asian manufacturing clusters, while import demand for finished pod systems clusters in North American and European deployment hubs. The United States runs the largest installation deficit, sourcing modular systems from European fabricators and portable units from Asian suppliers.
United States
OSHA workplace rest mandates and FAA airport concession regulations are accelerating corporate campus and terminal deployments. The San Francisco Bay Area tech corridor leads corporate adoption, with Class A office landlords specifying rest infrastructure in amenity subscriptions. Atlanta, Denver, and Dallas-Fort Worth airport expansions are converting hold room areas into pod-based revenue centers.
Germany
EU CSRD wellness reporting requirements and REACH chemical safety standards for acoustic composites are reshaping procurement specifications. The country's automotive and industrial engineering clusters in Baden-Württemberg and Bavaria are piloting workforce recovery pods for shift workers. Napcabs GmbH anchors domestic manufacturing capacity for modular terminal installations.
Japan
METI workplace health guidelines and compact urban living constraints are driving capsule hotel concept extensions into corporate settings. The Kanto region around Tokyo concentrates demand from financial services and technology headquarters seeking micro-rest solutions. Nine Hours Co., Ltd. exemplifies the domestic specialization in high-density sleep infrastructure.
United Kingdom
ISO ergonomic certification requirements and London Heathrow Terminal expansions are creating dual demand channels for aviation and corporate applications. The Southeast England logistics corridor is testing portable pod deployments for distribution center rest facilities. DreamPod Europe Ltd. represents regional manufacturing capacity for modular campus systems.
Australia
Workplace health and safety codes in mining and resources sectors are mandating fatigue management infrastructure at remote operational sites. Western Australia and Queensland resource corridors are importing portable pod systems for fly-in-fly-out worker accommodations. Domestic airport hubs in Sydney and Melbourne are evaluating gate-adjacent micro-rest concessions.
Sleeping Pods Market Competitive Environment
Concentration sits with specialized terminal operators and ergonomic furniture fabricators rather than diversified hospitality conglomerates. The competitive terrain splits between aviation-concession specialists with lease negotiation expertise and workplace wellness vendors with ISO certification capabilities. Two archetypes dominate: gate-adjacent micro-hotel operators and corporate campus amenity providers. Strategic moves center on FAA concession eligibility lobbying and backward integration into acoustic composite sourcing.
Within the aviation-specialist tier, Minute Suites, LLC and GoSleep OY exemplify divergent geographic anchoring and technical positioning. YOTEL LIMITED occupies a position bridging urban micro-hotel concepts with integrated pod installations. These three entities represent the spectrum from North American airport concession dominance to Nordic acoustic engineering specialization to British-founded global hospitality scaling.
| Leading Market Players |
|---|
| Minute Suites, LLC |
| YOTEL LIMITED |
| GoSleep OY |
| Podtime Pty Ltd. |
| DreamPod Europe Ltd. |
| Napcabs GmbH |
| MetroNaps Inc. |
| Nine Hours Co., Ltd. |
| Sleepbox LLC |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at East Asian acoustic composite manufacturers shapes both supply concentration and price floors for finished pod systems. Scale advantages in multi-layer sound-dampening production concentrate margin capture upstream, forcing downstream fabricators to absorb certification cost inflation or cede share to integrated competitors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates ISO-certified ergonomic systems from basic enclosure specifications, with aviation-grade acoustic engineering commanding the widest spreads. Pricing pressure stems from fire safety code fragmentation, which extends sales cycles and inflates compliance overhead. Airport concession operators exhibit the highest price sensitivity due to lease margin constraints, while corporate wellness programs at Fortune 500 headquarters prioritize outcome-measured service contracts over unit economics.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites logistics risk for aviation-grade acoustic composite shipments. Manufacturing concentration in China, South Korea, and Japan feeds specialized multi-layer sound-dampening materials to European and North American fabricators. Raw material dependencies center on aerospace-grade aluminum honeycomb cores, phenolic resin binders, and active noise cancellation membranes. Single-source vulnerability in East Asian phenolic resin production creates exposure to regional regulatory shifts. Distribution runs through terminal concession operators and Class A office landlords with bundled amenity subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from extended-stay hotel properties and micro-hotel concepts that compete for identical traveler rest budgets with established brand recognition. Defense requires structural repositioning around irreplaceable deployment constraints.
For Market Incumbents: Consolidate backward integration into captive acoustic composite sourcing to neutralize East Asian supplier concentration risk. Lock long-term concession agreements at Atlanta, Denver, and Dallas-Fort Worth terminal expansions before FAA regulatory clarity triggers competitive lease auctions. ISO ergonomic certification investment creates switching costs that protect corporate campus accounts against modular furniture cross-entry.
For New Entrants and Emerging Players: ISO 9241-5 ergonomic fast-track certification unlocks procurement eligibility at OSHA-mandated corporate facilities before incumbent certification timelines expire. Healthcare facility underpenetration offers the most penetrable white-space, with hospital staff rest rooms and clinician overnight quarters lacking established vendor relationships. Target fly-in-fly-out resource corridors in Western Australia and Queensland with portable pod deployments tailored to mining sector fatigue management codes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors IoT-enabled pod operators with predictive maintenance capabilities and biometric sleep monitoring pilots. Long-term viability rests on outcome-measured service contract conversion across Fortune 500 wellness programs. Acquisition target archetype: regional fabricators with FAA concession eligibility and captive acoustic composite supply. The signal to watch is EU CSRD wellness reporting mandate expansion, which would accelerate measurable workforce rest infrastructure procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acoustic Composites | Captive supply of aviation-grade materials neutralizes East Asian supplier concentration and margin compression. |
| FAA Concession Eligibility Lobbying | Regulatory clarity accelerates lease negotiations at Atlanta, Denver, and Dallas-Fort Worth terminal expansions. |
| ISO Ergonomic Certification Fast-Track | Compressed 8-14 month testing protocols unlock OSHA-mandated corporate procurement before incumbent renewal cycles. |
| Healthcare Facility Pilot Programs | Hospital staff rest rooms and clinician overnight quarters represent untapped 24-hour operational demand channels. |
| Biometric Sleep Monitoring Integration | Corporate wellness analytics at Fortune 500 headquarters decompose price-based procurement into outcome-measured contracts. |
Study Parameters
Operator-level perspectives from terminal concession managers, Class A office landlords, corporate wellness directors, airport procurement officers, and healthcare facility managers anchored the qualitative base. Primary interviews triangulated against secondary validation from FAA regulatory filings, OSHA workplace guideline updates, ISO certification registry data, and SEC 10-K disclosures from ergonomic furniture manufacturers. Bottom-up installation volume estimates across product segments reconciled with top-down market size triangulation.
Sensitivity analysis framed demand elasticity around OSHA mandate enforcement intensity and FAA concession regulation revision timing. Segmentation modeling spanned product type, end user, technology tier, and installation configuration across the projection horizon. CAGRs derived from unit shipment trajectories and average selling price evolution, with biometric-enabled smart control systems and modular campus deployments as distinct growth vectors.
Decision-makers should treat outputs as directional under sustained OSHA workplace rest guideline adoption and stable East Asian acoustic composite supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU CSRD wellness reporting mandate scope and fire safety code harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Multi-Door Fridges Market
Household Items
Leaf Blower Market
Household Items
Tablet Tissue Paper Market
Household Items
Japan Faucets Market
Household Items
Barbeque Grill Market
Household Items
Collapsible Water Bottle Market
Household Items
Electric Brooms Market
Household Items
Smart Bath Heater Market
Household Items
Brush Cover Market
Household Items
Europe Digital Showers Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Portable Steamers Market
Household Items
Electric Hedge Trimmer Market
Household Items
India Cookware Market
Household Items
Hydration Containers Market
Household Items
Mosquito Trap Market