
 US Air Purifier Market | 2026-2036
US Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
US Air Purifier Market Intelligence
A shift from single-source to multi-source component procurement is broadening the supplier base for air purifier manufacturers. Honeywell International, Inc. leverages its established distribution networks in the commercial sector. Dyson Limited competes on technological innovation and premium design aesthetics, targeting the high-end residential market. Coway Co., Ltd. differentiates through its service-oriented rental models.
An air purifier is an appliance designed to remove contaminants from the air in a confined space. These devices often incorporate a multi-stage filtration system, commonly using a High-Efficiency Particulate Air (HEPA) filter capable of capturing 99.97% of particles down to 0.3 microns. HEPA-based systems dominate the product landscape due to their proven efficacy. While the residential segment constitutes the largest end-user base, the commercial sector shows significant adoption in offices and healthcare facilities.
The US Environmental Protection Agency (EPA) provides guidance on indoor air quality, influencing purchasing decisions. Certifications from bodies like the California Air Resources Board (CARB) are critical for market access, ensuring devices meet ozone emission and electrical safety standards. Vendor success depends on navigating evolving energy efficiency standards and communicating certified performance benefits to consumers.
Market Dynamics
Heightened public health awareness, combined with increasing frequency of air quality events like wildfires, represents the central force shaping the US air purifier market. This dual pressure accelerates consumer education and drives demand for certified filtration efficacy.
Growth Catalysts
- EPA Guidance:Recommendations from the US Environmental Protection Agency on managing indoor particulate matter inform consumer and commercial purchasing decisions.
- Wildfire Frequency:Persistent wildfire seasons in Western states, particularly California, create acute, geographically concentrated demand for high-capacity air purification units.
- Residential Health Focus:Consumer emphasis on mitigating allergens, airborne viruses, and volatile organic compounds within homes sustains a broad base of demand.
Market Restraints
- Filter Replacement Costs:The recurring expense of proprietary HEPA and carbon filter replacements creates a total cost of ownership barrier for some consumers.
- Energy Consumption:High Clean Air Delivery Rate (CADR) units can have significant energy footprints, impacting utility costs for continuous operation.
- HVAC System Integration:The increasing availability of high-MERV filters for central HVAC systems presents a substitute for standalone portable units in some homes.
Strategic Opportunities
- Smart Home Integration:Developing units with Wi-Fi connectivity and sensor-driven automation for integration into platforms like Google Home or Amazon Alexa offers new value.
- Light Commercial Expansion:Targeting underpenetrated small-to-medium businesses, clinics, and classrooms provides a growth vector beyond saturated residential and large corporate segments.
- Advanced Sanitization:Combining proven HEPA filtration with emerging technologies like UV-C light or photocatalytic oxidation addresses specific concerns about pathogens.
Industry Challenges
- Certification Complexity:Manufacturers must navigate a fragmented landscape of standards, including mandatory CARB certification and voluntary programs like Energy Star and AHAM Verifide.
- Component Supply Volatility:Securing consistent, high-quality supply of critical components like advanced sensors and specialized HEPA media presents an ongoing logistical challenge.
- Educating Consumers:Communicating the technical differences and benefits of various filtration technologies and performance metrics like CADR to a mass audience is difficult.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Air Purifier Market |
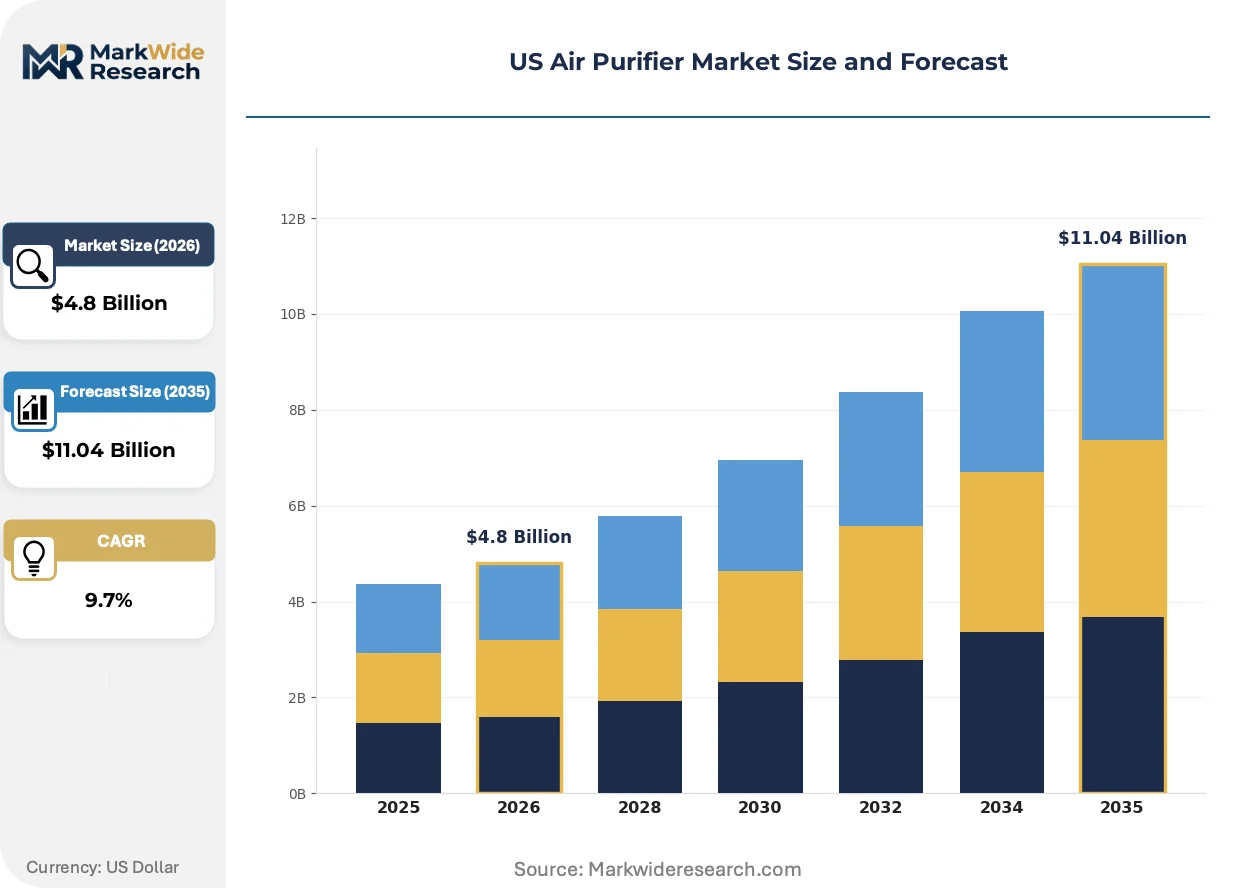
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Ionizer, UV-C End User: Residential, Commercial, Industrial, Automotive Technology: Passive, Active, Photocatalytic, Electrostatic Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Honeywell International, Inc., Levoit (Vesync Co., Ltd.), Dyson Limited, Koninklijke Philips N.V., Coway Co., Ltd., Blueair AB, IQAir North America, Inc., Whirlpool Corporation, Winix Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Air Purifier Market Strategic Shifts & Innovations
The market's focus is evolving from standalone mechanical filtration to integrated, data-informed air quality management. This shift redefines the air purifier as a core component of a connected and health-aware home or commercial building.
Advanced sensors that detect specific pollutants like PM2.5 and volatile organic compounds (VOCs) form the core of new product intelligence. Health-conscious residential buyers and commercial facility managers are rapidly adopting sensor-equipped models. This onboard sensing capability is converging with smart home ecosystems, enabling automated adjustments based on real-time indoor air quality data without user intervention.
California Air Resources Board (CARB) certification for ozone and electrical safety has become a critical market access requirement. This state-level rule effectively functions as a national baseline, compelling manufacturers to design products for compliance to reach the entire US market. Consequently, brands targeting national retail channels prioritize CARB certification from the initial product development phase.
A notable shift is occurring from one-time hardware sales toward recurring revenue models, including automated filter subscription services. This disrupts the traditional retail purchase by creating an ongoing service relationship between the brand and the consumer. The model is most prominent in the direct-to-consumer channel and with commercial clients seeking outsourced maintenance solutions.
US Air Purifier Market Segmentation
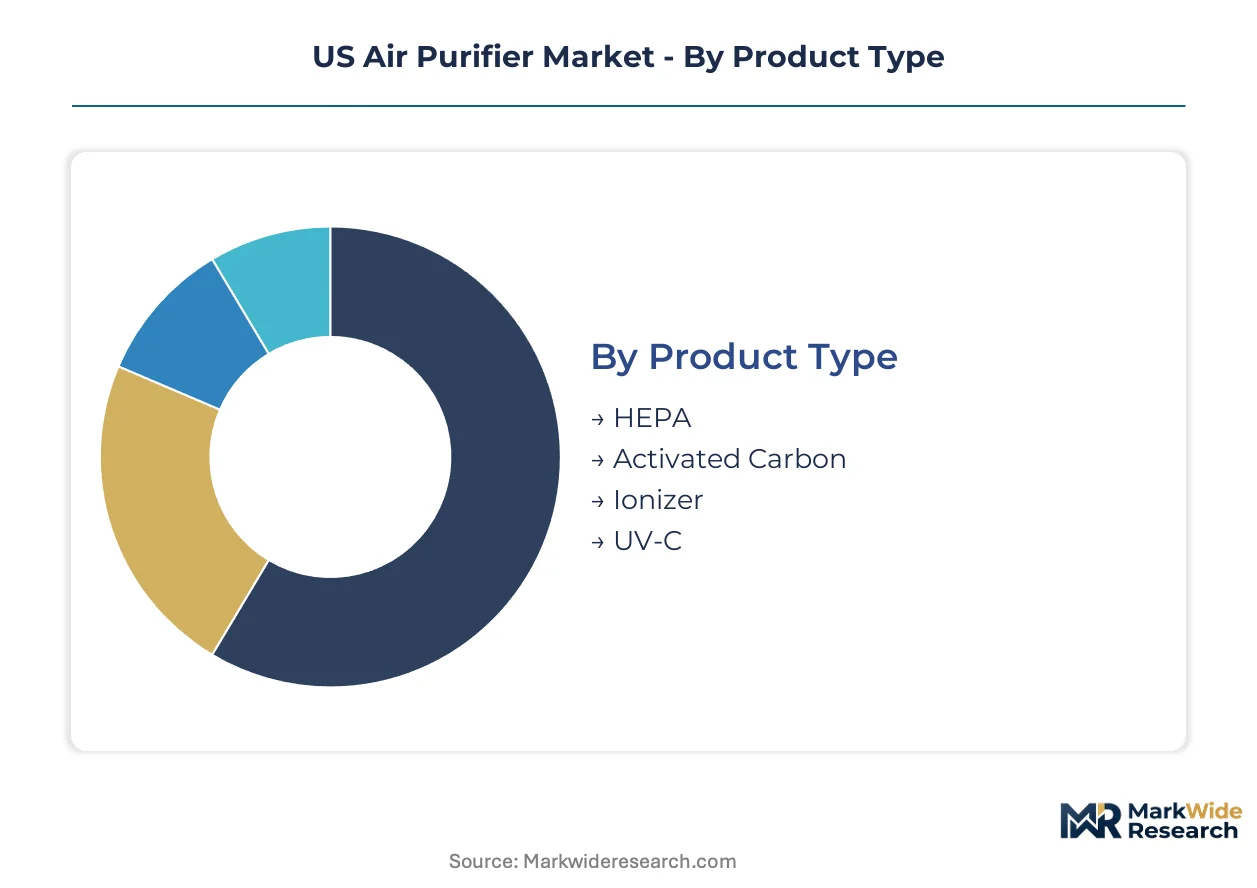
Understanding the varied segments within the US air purifier market provides clarity on where demand concentrates and how technological advancements are shaping product offerings. Market segmentation reveals distinct buyer behaviors and operational requirements across different product types, end-users, technologies, and distribution channels.
Product Type:
The operational mechanism of an air purifier, defining how it integrates into a space's air quality strategy, forms the basis of product type segmentation.
- HEPA:High-Efficiency Particulate Air filters capture 99.97% of particles down to 0.3 microns, utilizing a dense mesh of fibers. Demand concentrates heavily in the US residential sector, driven by consumer focus on mitigating allergens and particulate matter from events like wildfires.
- Activated Carbon:These filters employ porous carbon to adsorb volatile organic compounds (VOCs), gases, and odors from the air. US consumers in urban areas and those with pets increasingly seek these units to address specific odor and chemical pollutant concerns.
- Ionizer:Ionizers release charged ions that attach to airborne particles, causing them to fall out of the air or stick to surfaces. These systems find use in specific residential applications for allergen reduction, often as a supplementary filtration stage.
- UV-C:Ultraviolet-C light technology targets and inactivates airborne microorganisms like bacteria and viruses. Healthcare facilities and health-conscious US households adopt UV-C enabled units for enhanced sanitization.
HEPA leads volumes today; Activated Carbon is gaining share fastest.
End User:
The primary application focus dictates the end-user segmentation, reflecting distinct environmental needs and purchasing criteria.
- Residential:This segment encompasses air purifiers used in private homes, apartments, and other living spaces to improve indoor air quality. US households prioritize units addressing allergens, pet dander, and wildfire smoke, particularly in Western states.
- Commercial:Air purifiers deployed in offices, retail spaces, hotels, and educational institutions fall into this category. US commercial entities invest in these systems to enhance employee well-being and meet indoor air quality standards in shared environments.
- Industrial:Industrial settings such as manufacturing plants or workshops utilize robust air purification systems to manage dust, fumes, and other airborne contaminants. Facilities in the US comply with OSHA guidelines, necessitating specialized filtration for worker safety.
- Automotive:Air purification systems integrated into vehicles or designed for car interiors address cabin air quality concerns. US consumers consider these units for reducing pollutants during commutes.
Market expansion hinges on increasing penetration within the Commercial sector, complementing the established Residential base.
Technology:
The functional approach to air purification defines the technology segmentation, ranging from mechanical capture to advanced chemical reactions.
- Passive:Passive systems rely on physical barriers like HEPA and activated carbon filters to trap pollutants as air passes through them. These mechanical filtration methods dominate the US market due to their proven efficacy and widespread acceptance.
- Active:Active technologies, such as ionizers and UV-C, actively modify or neutralize airborne contaminants using electrical charges or light. US consumers seeking enhanced pathogen control or specific particle removal often consider these supplementary technologies.
- Photocatalytic:Photocatalytic oxidation (PCO) technology uses UV light in conjunction with a titanium dioxide (TiO2) filter to break down VOCs and other pollutants. This method finds application in specialized US commercial and residential settings for chemical removal.
- Electrostatic:Electrostatic precipitators use an electric field to charge particles, which are then collected on oppositely charged plates. These systems are used in certain industrial and commercial US environments where fine particle capture is critical.
Innovation in Photocatalytic technology drives future growth alongside the established Passive filtration methods.
Distribution Channel:
The accessibility and reach of air purifiers to consumers and businesses categorize the distribution channels, influencing purchasing convenience.
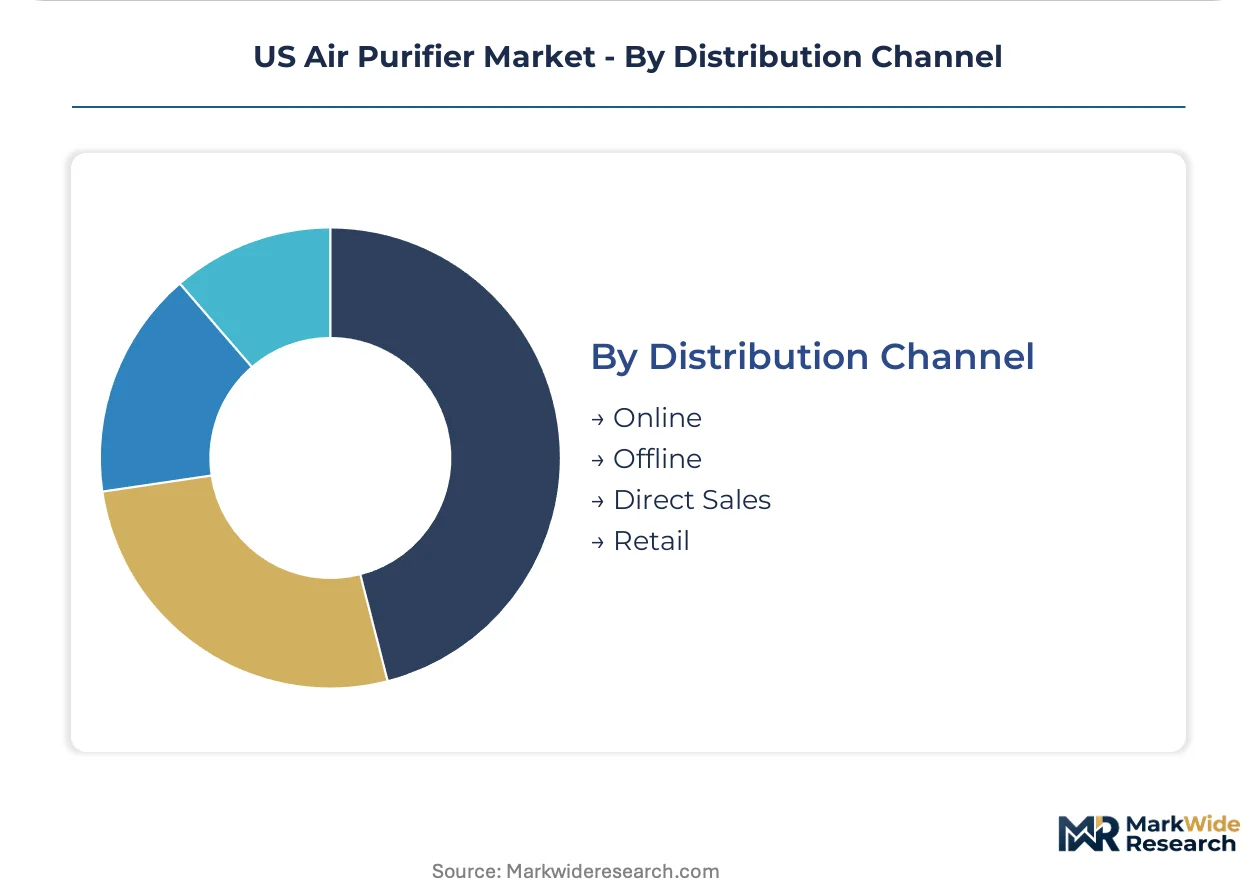
- Online:This channel includes e-commerce platforms, brand websites, and direct-to-consumer sales via the internet. US consumers increasingly purchase air purifiers online for convenience, wider selection, and competitive pricing.
- Offline:Offline distribution encompasses traditional brick-and-mortar stores, local appliance retailers, and specialized home improvement centers. Many US buyers prefer to physically inspect units before purchase, supporting this channel.
- Direct Sales:Manufacturers sell directly to end-users, particularly for commercial or industrial clients requiring customized solutions or bulk orders. This approach fosters direct relationships with US businesses and ensures specialized support.
- Retail:Large retail chains, mass merchandisers, and electronics stores constitute a significant portion of the retail channel. These US outlets offer broad consumer access and often feature promotional pricing.
Digital platforms reshape purchasing patterns for consumers, with Online channels experiencing substantial expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's dense urban centers and vulnerability to wildfires drive significant demand for air purification. This state's stringent environmental regulations often set national benchmarks for product performance. Other US regions also exhibit distinct demand profiles shaped by local environmental factors.
California
Demand for air purifiers in California stems primarily from seasonal wildfire smoke and persistent PM2.5 pollution. CARB certification is a critical market access requirement for devices sold within the state. Los Angeles and San Francisco metropolitan areas show high consumer adoption of HEPA-based units due to recurring air quality alerts.
Pacific Northwest
Seasonal wildfire smoke originating from both local and Californian fires, alongside pollen, fuels air purifier sales in the Pacific Northwest. State environmental agencies in Washington and Oregon emphasize indoor air quality guidance during smoke events. Seattle and Portland urban clusters prioritize sensor-equipped models for real-time air quality monitoring in homes.
Northeast Corridor
Urban pollution, allergens, and humidity-related indoor contaminants generate consistent demand for filtration solutions across the Northeast Corridor. New York City's commercial building codes increasingly consider indoor air quality standards for tenant well-being. Boston and New York City households invest in advanced multi-stage units to combat fine particulate matter and VOCs.
Southeast
High humidity, mold spores, and persistent allergen issues from pollen contribute to a steady demand for air purifiers in the Southeast. Florida's Department of Health issues guidance on indoor air quality, particularly concerning mold prevention. Atlanta and Miami residents seek units with active technologies like UV-C to address biological contaminants and improve home air quality.
US Air Purifier Market Key Industry Players
Global majors compete with regional champions across technological innovation and distribution reach. The market exhibits a tiered structure, from premium design-focused brands to value-oriented manufacturers. Strategic archetypes include established appliance conglomerates, specialized air quality technology firms, and direct-to-consumer innovators. Portfolio diversification into smart home ecosystems and strategic partnerships with HVAC providers represent dominant competitive moves.
On the premium-tier vector, Dyson Limited exemplifies brands emphasizing design aesthetics and advanced filtration. Honeywell International, Inc., a global industrial conglomerate, anchors the market through its extensive distribution networks in both residential and commercial sectors. Coway Co., Ltd. represents the service-oriented model, leveraging rental subscriptions and integrated maintenance solutions to differentiate its offering. These companies collectively shape market expectations for product features and service delivery.
| Leading Market Players |
|---|
| Honeywell International, Inc. |
| Levoit (Vesync Co., Ltd.) |
| Dyson Limited |
| Koninklijke Philips N.V. |
| Coway Co., Ltd. |
| Blueair AB |
| IQAir North America, Inc. |
| Whirlpool Corporation |
| Winix Inc. |
| Others |
Cost & Logistics Intelligence
US commercial facility managers often prioritize long-term service contracts for air purification, influencing manufacturers toward value-based pricing models. This approach accounts for installation, maintenance, and filter subscriptions rather than just hardware cost.
Pricing Analysis
Input cost fluctuations for specialized HEPA media and advanced sensor components directly influence air purifier pricing. The dominant pricing structure involves a per-unit transactional sale for residential units, often complemented by recurring revenue from filter subscriptions. Price differentiation stems from certification levels like CARB and brand premium, with pricing softness running through the economy-tier residential segment due to high buyer price sensitivity. Commercial buyers, prioritizing performance and total cost of ownership, exhibit lower price sensitivity.
Supply Chain Analysis
Reverse logistics for air purifier components, particularly filter recycling and unit refurbishment, represents a growing consideration for manufacturers. The supply chain draws heavily from component manufacturers in China and South Korea for specialized HEPA media and advanced sensors. Raw material dependencies include polypropylene for HEPA filters and activated carbon for VOC removal, creating a structural risk of commodity price volatility. Distribution runs through online retailers, traditional brick-and-mortar stores, and direct sales channels for commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US air purifier market presents a geographic-arbitrage opportunity, as stringent California Air Resources Board (CARB) regulations often exceed federal standards, creating a higher compliance cost burden for manufacturers. Brands can leverage this by designing for CARB compliance then distributing nationally.
For Market Incumbents:Acquire specialized sensor technology firms to integrate advanced pollutant detection capabilities into existing product lines. Consolidate distribution networks, particularly in underserved light commercial segments, to counter margin pressure from new entrants. Invest in R&D for next-generation filtration media that offers enhanced efficacy against emerging airborne threats like novel pathogens. Leverage established brand recognition and certification investments to reinforce market leadership.
For New Entrants and Emerging Players:Launch via direct-to-consumer online channels, emphasizing subscription-based filter replacement models to build recurring revenue streams. Target the underpenetrated light commercial sector, such as small clinics and classrooms, with cost-effective, high-CADR units. Develop products with integrated smart home connectivity and sensor-driven automation for a distinct go-to-market angle. Focus on specific regional needs, like UV-C enabled units for the humid Southeast.
For Investors and Strategic Acquirers:HVAC system integrators are the most active acquirers in this space, seeking to bundle air purification with broader indoor climate solutions. The long-term viability favors firms with strong intellectual property in advanced filtration and sensor technologies. Monitor the integration of air purification into central HVAC systems as a key inflection indicator. Acquisition targets should possess robust direct-to-consumer channels or established commercial client bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Advanced Sensor Integration | Enables real-time air quality monitoring and automated adjustments, enhancing product value for health-conscious consumers. |
| Expand Service-Oriented Rental Models | Generates recurring revenue streams and fosters long-term customer relationships, shifting from one-time hardware sales. |
| Secure CARB Certification for All Products | Ensures market access across the US, setting a national compliance baseline for product safety and emissions. |
| Target Light Commercial Sector Expansion | Diversifies revenue beyond saturated residential markets, addressing underpenetrated segments like clinics and classrooms. |
| Form Strategic Partnerships with HVAC OEMs | Integrates standalone units with central systems, offering comprehensive indoor air quality solutions to broader markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary data validation. Primary research involved discussions with product development executives, procurement managers, distribution channel partners, and environmental health specialists. Secondary data sources included EPA reports, CARB publications, industry association whitepapers, and company financial filings. This approach facilitated bottom-up and top-down triangulation for robust market sizing.
Segment weighting across product type, end-user, technology, and distribution channel formed the basis of the forecast framework. The analytical approach projected market growth over the projection horizon, with CAGRs derived from historical trends and future demand drivers. Key forecast inputs included residential housing starts and commercial construction spending, alongside air quality event frequency.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme climate events or rapid regulatory shifts. Forecasts reflect assumptions regarding economic stability and technological advancement. Practitioners should monitor wildfire intensity and evolving indoor air quality standards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Hand Wash Station Market
Household Items
Aquarium Hydrometers Market
Household Items
Smart Drying Racks Market
Household Items
Thermos Drinkware Market
Household Items
Gel Warmers Market
Household Items
Powered Lawn Mowers Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Smart Bathroom Market
Household Items
Neck Pillows Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Insulated Tumblers Market
Household Items
Shower Heads and Systems Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Tiki Torch Market