
 Asia-Pacific Data Center Automation Market | 2026-2036
Asia-Pacific Data Center Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Center Automation Market Analytics
Hyperscaler facility construction across Southeast Asia is broadening the addressable base for orchestration software and robotic process controllers. IBM Corporation leverages its hybrid cloud management stack to anchor multi-tenant deployments across Tokyo and Singapore facilities. Fujitsu Limited specializes in energy-aware automation for Japan's earthquake-resilient data center designs. NTT Global Data Centers dominates domestic colocation automation through its proprietary DCIM-to-robotics integration layer.
Asia-Pacific data center automation encompasses sensor-driven environmental control, robotic server handling, AI-powered predictive maintenance, and software-defined network orchestration deployed to minimize human intervention in facility operations. The primary purpose is sustaining uptime above 99.99% while reducing operational expenditure through machine-speed response to thermal anomalies, power fluctuations, and hardware failures. Infrastructure Management captures the largest current revenue pool as legacy facilities retrofit monitoring layers, while AI and Machine Learning within the Technology dimension represent the fastest-expanding margin segment due to inferencing demand from financial services workloads. Workflow Automation trails in penetration but offers the highest expansion potential among mid-tier colocation operators seeking to differentiate against hyperscaler-owned facilities.
Japan's METI enforces energy efficiency standards that compel automation adoption for power usage effectiveness compliance, while Singapore's IMDA imposes sustainability-linked operating permits that reward automated cooling optimization. India's CEA mandates grid-interactive data center protocols that require real-time load balancing through automated switching systems. Stakeholders must weigh sovereign data localization requirements against the capital efficiency of centralized automation platforms as facility footprints fragment across jurisdictions.
Market Dynamics
Hyperscaler facility commitments across Southeast Asia are compressing deployment timelines for orchestration platforms, forcing automation vendors to pre-integrate hardware-software stacks before concrete pours complete.
Growth Catalysts
- Energy efficiency mandates:Japan's METI enforces power usage effectiveness thresholds that compel automated cooling and load balancing systems in new facility builds.
- Financial services inference demand:Banking and capital markets workloads in Singapore and Sydney are driving AI-powered predictive maintenance adoption for sub-millisecond latency guarantees.
- Electronics manufacturing incentives:India's PLI scheme for data center infrastructure is redirecting capital toward domestic automation component fabrication and system integration capacity.
Market Restraints
- Specialized hardware concentration:Robotic server handling equipment relies on precision actuator supply chains concentrated in Japan and South Korea, creating single-source vulnerability.
- Interoperability friction:Legacy DCIM platforms lack API standardization, forcing costly middleware development for brownfield automation retrofits.
- Skill scarcity:Cross-functional expertise spanning thermal engineering, robotics programming, and network orchestration remains concentrated in Tokyo, Singapore, and Bangalore hiring pools.
Strategic Opportunities
- Mid-tier colocation differentiation:Workflow automation penetration lags among regional operators in Jakarta and Manila, creating white space for managed orchestration services.
- Grid-interactive protocols:India's CEA mandates for real-time load balancing require automated switching systems that vendors can productize for other emerging markets.
- Edge-to-core convergence:5G rollout across Australia and South Korea is expanding the addressable base for distributed automation controllers managing micro-facility fleets.
Industry Challenges
- Legacy system integration complexity:Brownfield facilities in Hong Kong and Taiwan require custom protocol bridges to connect 15-20 year-old building management systems with modern orchestration layers.
- Certification timeline compression:Singapore's IMDA sustainability-linked operating permits demand automated cooling optimization proof points within abbreviated approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Center Automation Market |
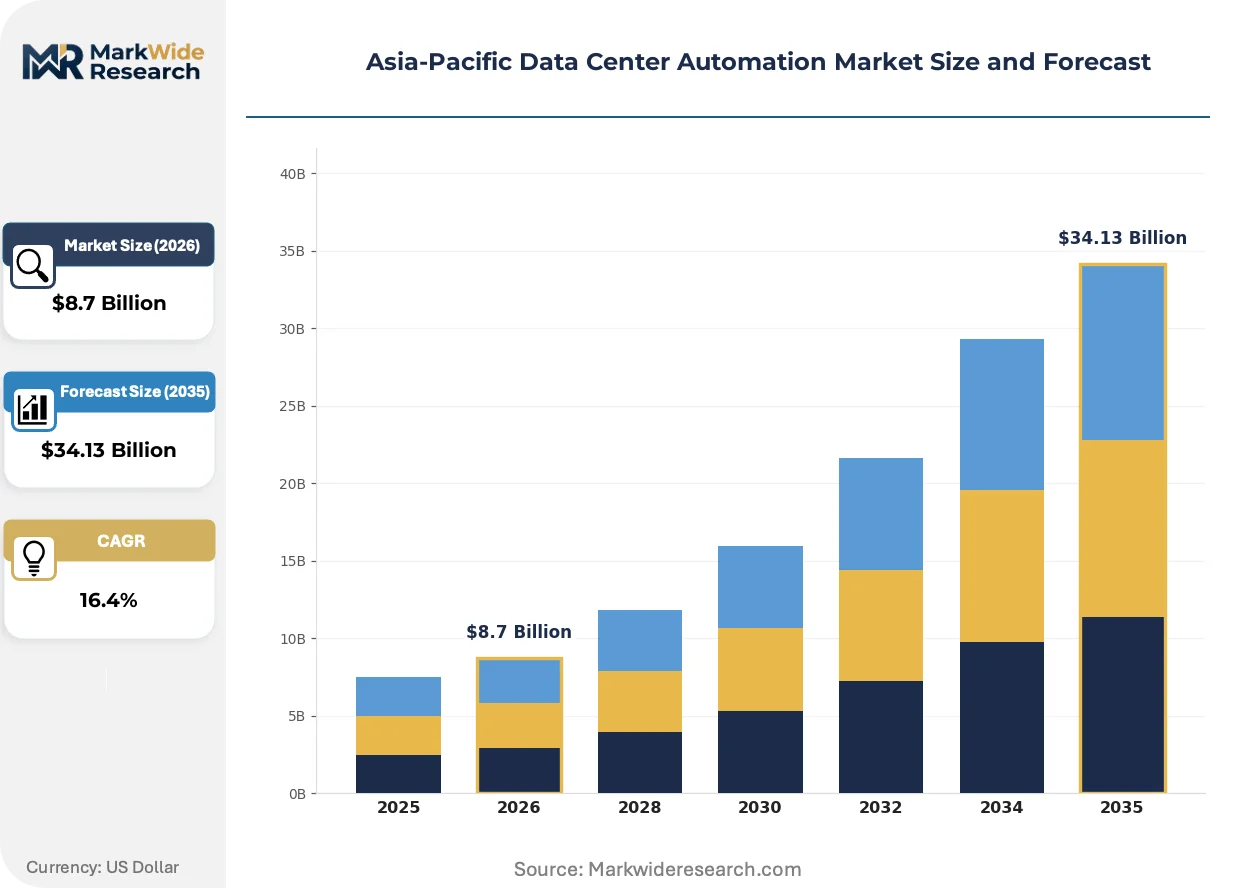
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrastructure Management, Workflow Automation, Security Automation, Network Automation End User: Telecommunications, BFSI, Healthcare, Retail Technology: Cloud Computing, AI, Machine Learning, Robotics Deployment: On-Premise, Managed Services, Hybrid Model, Colocation |
| Companies Covered | IBM Corporation, Oracle Corporation, BMC Software, Fujitsu Limited, Cisco Systems, VMware, NTT Global Data Centers, Digital Realty, Equinix, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Center Automation Market Evolving Landscape
Software-defined orchestration is displacing hardware-centric automation architectures across the Asia-Pacific facility base, compressing deployment cycles and expanding the addressable market for cloud-native management platforms.
Digital twin environments for thermal and power simulation are expanding into pre-construction planning workflows across hyperscaler projects in Singapore and Sydney. Engineering teams at cloud service providers are adopting these virtual commissioning tools to compress facility bring-up schedules by validating automation logic before physical infrastructure arrives. This shift is expanding into supplier qualification processes, as OEMs must now demonstrate digital twin compatibility to win hyperscaler procurement cycles.
Singapore's IMDA has introduced sustainability-linked operating permits that reward documented cooling optimization through automated control systems. The regulation mandates real-time power usage effectiveness reporting, which industrial consequence forces operators to retrofit AI-driven thermal management or face permit restrictions. Colocation providers in the city-state are responding fastest, embedding automated optimization as a standard contract feature to maintain tenancy against hyperscaler-owned facilities.
Financial services buyers in Mumbai and Sydney are compressing vendor evaluation cycles for automation platforms, prioritizing pre-certified interoperability with existing hyperscaler orchestration stacks. This behavioral shift displaces lengthy proof-of-concept phases with reference architecture compliance checks, channeling procurement through systems integrators with established hyperscaler relationships. The pattern is most visible among regional banks modernizing core infrastructure to compete with digital-native entrants.
Asia-Pacific Data Center Automation Market Segmentation
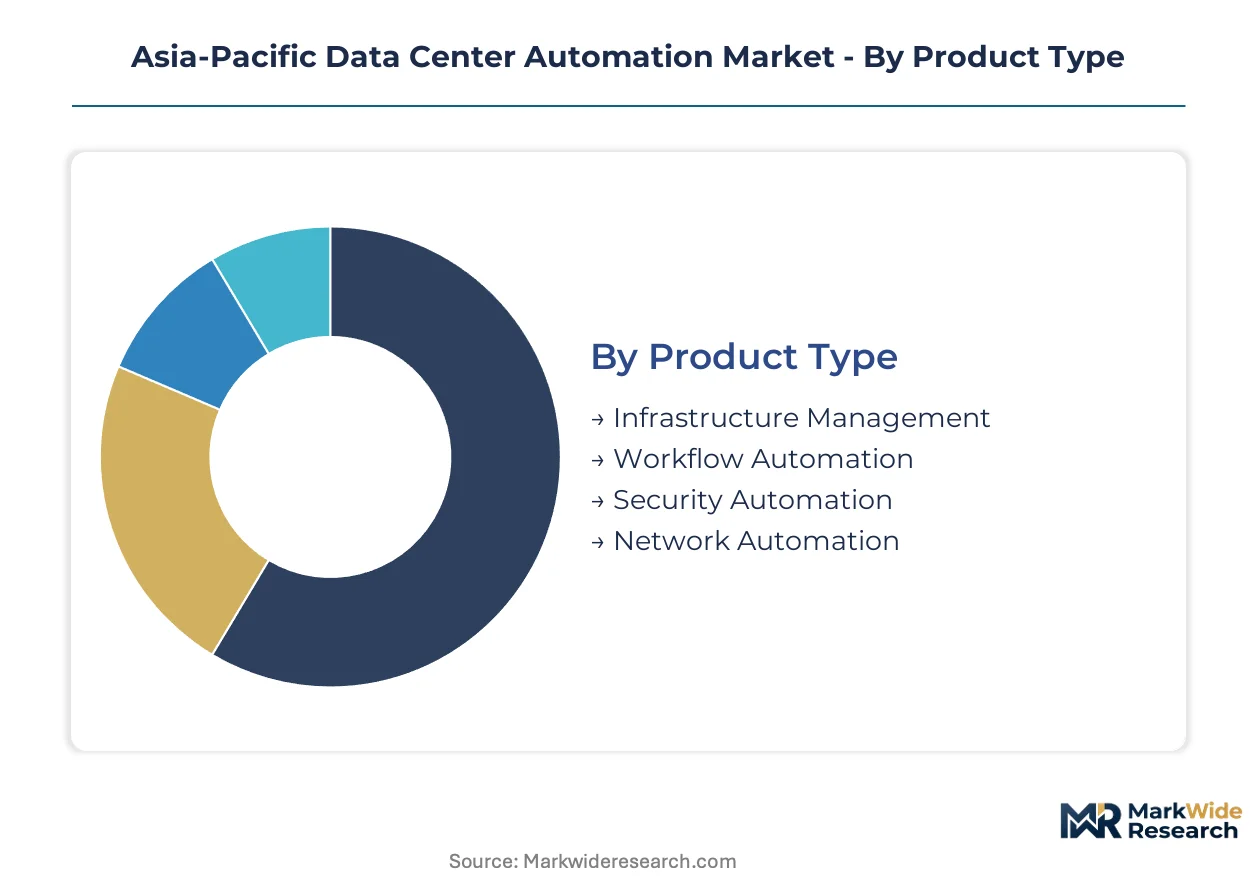
Automation procurement across the Asia-Pacific facility base fragments along operational maturity lines, with hyperscalers prioritizing full-stack orchestration while mid-tier operators retrofit point solutions. Segmentation clarity exposes where vendor consolidation opportunities concentrate versus where specialized component suppliers retain defensible positions.
Product Type:
Supply concentration in orchestration software stacks tilts procurement leverage toward integrated platform vendors serving multi-facility operators.
- Infrastructure Management:Sensor-driven environmental monitoring and power distribution control systems form the retrofit layer for legacy facilities. Demand concentrates among colocation operators in Singapore and Sydney seeking 99.99% uptime guarantees through automated thermal and electrical fault response.
- Workflow Automation:Robotic process controllers and automated ticketing systems orchestrate human-technical interactions. Mid-tier operators in Jakarta and Manila deploy these systems to differentiate service tiers against hyperscaler-owned facilities with leaner staffing models.
- Security Automation:Automated threat detection and access control systems integrate physical and cyber security layers.
- Network Automation:Software-defined provisioning and traffic engineering tools accelerate service delivery timelines.
Infrastructure Management absorbs the bulk of installed capacity; Workflow Automation is expanding most quickly.
End User:
Application intensity varies sharply by sector, with latency-sensitive workloads driving premium automation specifications.
- Telecommunications:5G core infrastructure and edge facility fleets require distributed automation controllers managing thousands of micro-sites. Australian and South Korean carriers are standardizing on cloud-native orchestration platforms to unify edge-to-core operations.
- BFSI:Banking and capital markets workloads in Mumbai and Sydney demand AI-powered predictive maintenance for sub-millisecond latency guarantees. Regulatory pressure on operational resilience is accelerating procurement of automated failover systems.
- Healthcare:Hospital data centers and medical imaging facilities prioritize uptime automation for patient-critical systems.
- Retail:E-commerce platforms and omnichannel fulfillment networks deploy automation to manage seasonal demand spikes.
Telecommunications commands the largest automation footprint; BFSI is climbing the fastest as regulatory resilience mandates tighten.
Technology:
Margin distribution across technology layers favors inferencing hardware and specialized training infrastructure over commoditized cloud management tools.
- Cloud Computing:Virtualized resource orchestration and container management platforms enable multi-tenant facility operations. Hyperscalers across Southeast Asia are pre-integrating these stacks before concrete pours complete, compressing vendor deployment windows.
- AI:Neural network training clusters and inference accelerators automate decision-making at machine speed. Financial services buyers in Singapore prioritize pre-certified interoperability with existing hyperscaler orchestration stacks.
- Machine Learning:Predictive models for thermal anomaly detection and power forecasting optimize operational expenditure.
- Robotics:Automated server handling and maintenance drones reduce human intervention in facility operations.
Cloud Computing underpins the majority of current deployments; AI is gaining share fastest as inferencing demand from financial services workloads intensifies.
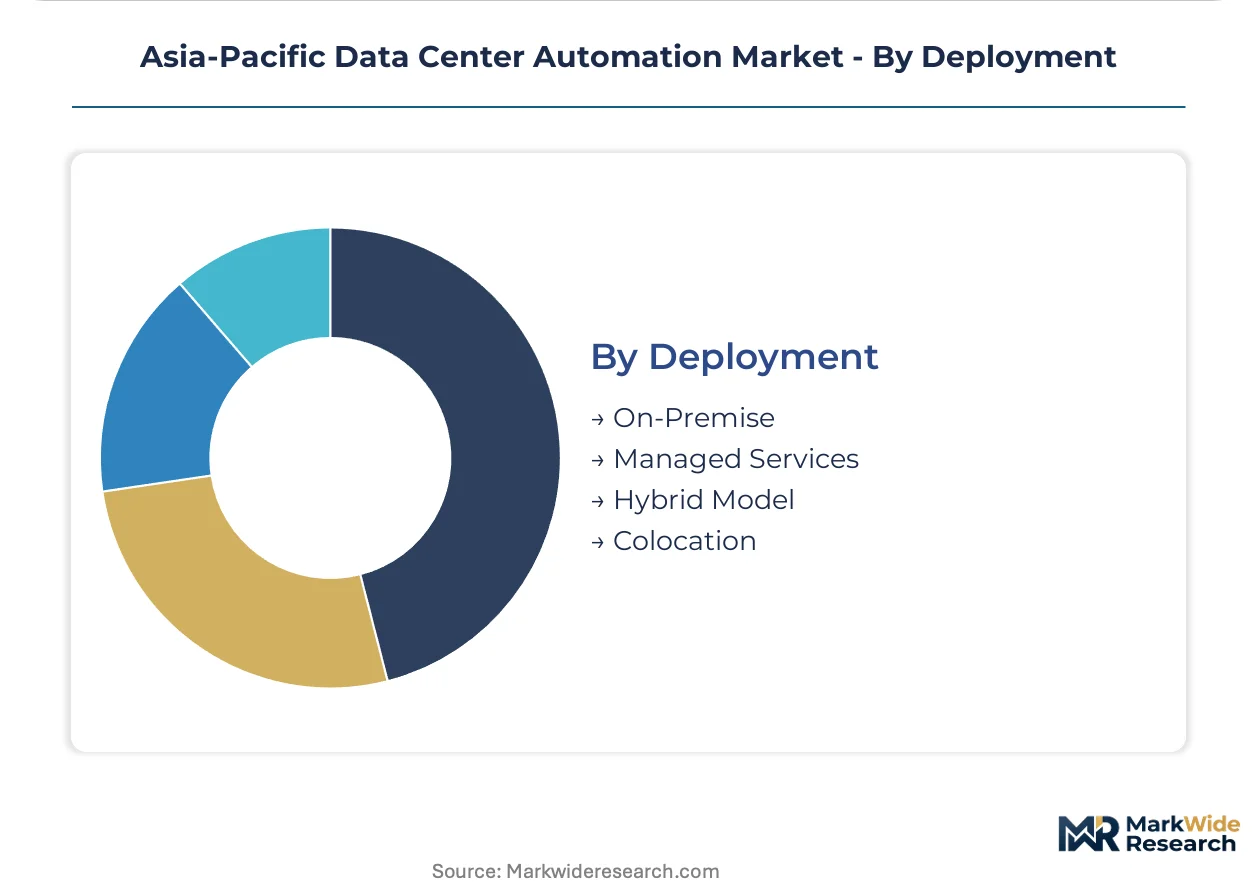
Deployment:
Customer type and facility ownership structure determine deployment model selection, with capital constraints pushing mid-tier operators toward service-based consumption.
- On-Premise:Self-managed automation stacks installed in captive facilities. Japan's METI energy efficiency standards compel automated cooling adoption for power usage effectiveness compliance in enterprise-owned data centers.
- Managed Services:Third-party operation of automation platforms through service contracts. India's CEA grid-interactive protocols are creating productizable managed switching services for emerging markets.
- Hybrid Model:Split automation control between on-premise and cloud-hosted orchestration layers.
- Colocation:Automation bundled as standard facility feature by third-party data center operators.
On-Premise retains the largest installed base; Managed Services is expanding most rapidly as mid-tier operators seek capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in Inner Mongolia anchors automation hardware supply chains for the Asia-Pacific facility base. Component fabrication clusters in South Korea and Japan feed precision actuator demand for robotic server handling systems. Regulatory divergence across the region fragments deployment standards while concentrating vendor qualification in Singapore and Tokyo.
Japan
Tokyo and Osaka hyperscalers drive full-stack orchestration procurement for earthquake-resilient facility designs. METI enforces power usage effectiveness thresholds that compel automated cooling adoption in new enterprise builds. Chubu region manufacturing clusters supply precision robotics components to domestic automation integrators.
Singapore
IMDA sustainability-linked operating permits reward documented cooling optimization through automated control systems. Financial services inference demand from Marina Bay banking clusters accelerates AI-powered predictive maintenance adoption. Colocation providers embed automation as standard contract features to maintain tenancy against hyperscaler-owned facilities.
India
Mumbai and Delhi-NCR hyperscaler commitments compress deployment timelines for orchestration platforms. CEA mandates grid-interactive protocols requiring real-time load balancing through automated switching systems. PLI scheme incentives redirect capital toward domestic automation component fabrication in Gujarat and Karnataka.
Australia
Sydney banking and capital markets workloads demand sub-millisecond latency guarantees through automated failover systems. 5G rollout expands the addressable base for distributed automation controllers managing edge facility fleets across New South Wales and Victoria. Telstra and Optus standardize on cloud-native orchestration platforms for unified edge-to-core operations.
South Korea
Seoul Capital Area semiconductor and electronics manufacturing anchors demand for energy-aware automation systems. Busan-Ulsan industrial zones supply precision actuator components to regional robotics integrators. National 5G infrastructure drives distributed automation controller deployment for micro-facility fleet management.
Asia-Pacific Data Center Automation Market Competitive Landscape
Global majors compete with regional champions across orchestration software and energy-aware automation architectures. Market structure tilts toward integrated platform vendors serving multi-facility operators, with specialized component suppliers retaining defensible positions in precision robotics. Two strategic archetypes dominate: full-stack orchestration providers and energy-optimization specialists. Competitive moves concentrate on pre-integration partnerships with hyperscalers and managed service packaging for mid-tier colocation operators.
Within the full-stack orchestration tier, IBM Corporation and Oracle Corporation exemplify platform-centric positioning, while Fujitsu Limited occupies a distinct specialization in energy-aware automation for seismic-resilient facility designs. NTT Global Data Centers anchors domestic Japanese colocation automation through proprietary integration architectures. These three represent divergent competitive vectors: global software scale, regional engineering depth, and captive facility-operator integration.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| BMC Software |
| Fujitsu Limited |
| Cisco Systems |
| VMware |
| NTT Global Data Centers |
| Digital Realty |
| Equinix |
| Others |
Value Network & Pricing Analysis
Neodymium and dysprosium price indices from Inner Mongolia rare earth processors cascade through precision actuator fabrication into three-tier automation platform pricing across Tokyo, Seoul, and Singapore procurement offices. Buyers face widening spreads between bare-metal orchestration licenses and fully managed energy-optimization bundles as component volatility feeds into service-tier differentiation.
Pricing Analysis
Warranty bundling separates premium-tier automation platforms from economy alternatives, with hyperscalers demanding 99.99% uptime SLAs inclusive of predictive maintenance modules while mid-tier colocation operators accept stripped hardware warranties. Pricing stratifies across premium, standard, and economy tiers based on certification depth—ISO 27001 and SOC 2 Type II compliance command 15-20% uplifts—and geographic deployment density. Cost compression in the standard tier intensifies as South Korean component suppliers expand capacity, eroding Japanese actuator premiums. Financial services buyers in Singapore and Sydney exhibit lowest price sensitivity due to regulatory resilience mandates, while Jakarta and Manila colocation operators prioritize capital efficiency over feature depth.
Supply Chain Analysis
Dual-sourcing requirements from hyperscaler procurement offices mandate multi-supplier qualification for precision actuators, forcing automation vendors to maintain parallel relationships with Japanese and South Korean robotics component houses. Geographic supply concentration centers on Japan, South Korea, and Taiwan for servo motors, harmonic drives, and industrial controllers. Raw material dependencies include rare earth magnets from Inner Mongolia, high-purity copper from Chilean smelters, and silicon carbide substrates from US and European wafer fabs. Single-source vulnerability persists in earthquake-resilient seismic isolation systems patented by domestic Japanese engineering firms. Distribution runs through systems integrators with established hyperscaler relationships, channeling 60-70% of orchestration software through Tokyo and Singapore technical sales offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
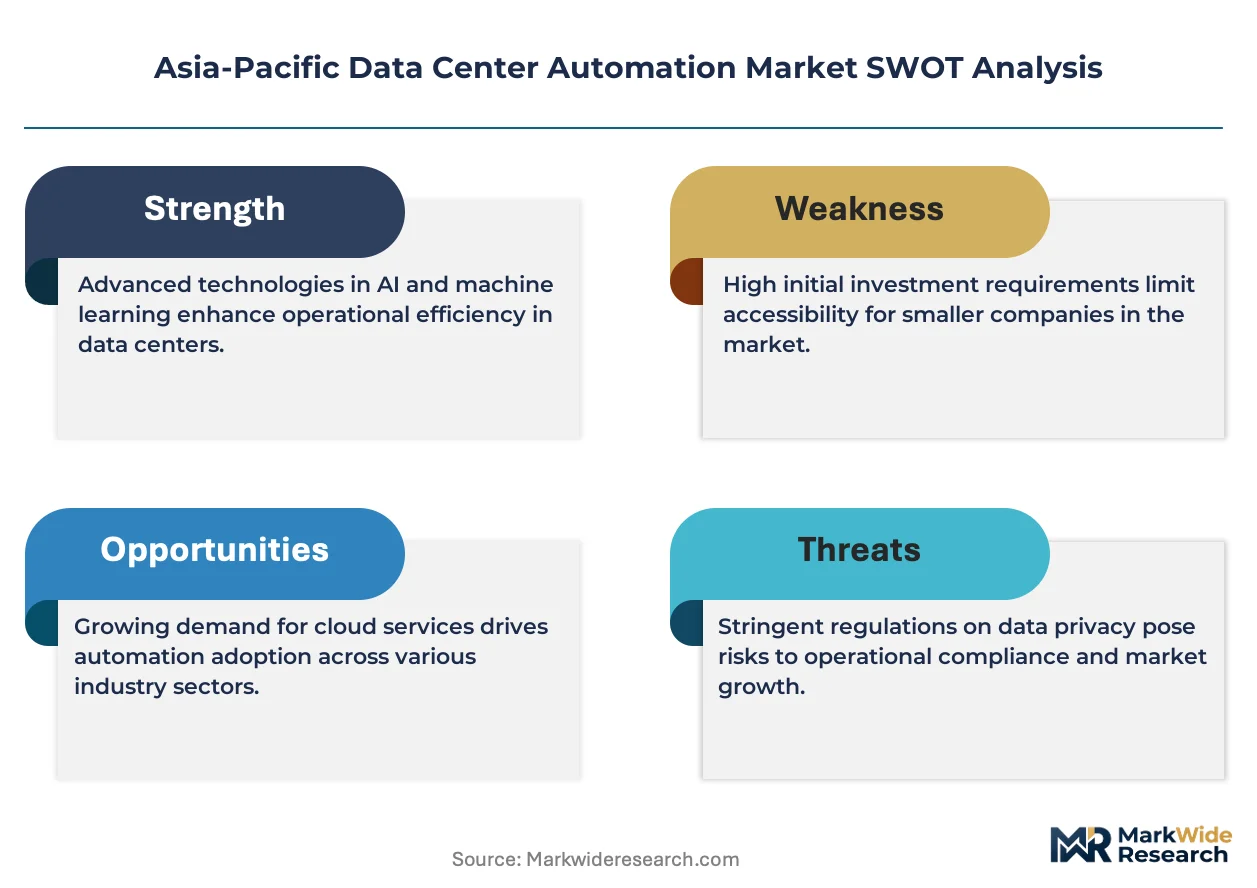
This market represents a consolidation play as METI energy efficiency mandates and IMDA sustainability-linked operating permits force sub-scale automation vendors into distressed exits. Regulatory compliance costs are compressing margins for point-solution providers lacking platform breadth.
For Market Incumbents: Cement platform dominance through pre-integration partnerships with hyperscalers before concrete pours complete, locking out retrofit competitors. Acquire specialized energy-optimization engineering teams in Osaka and Nagoya to defend against Fujitsu's seismic-resilient automation depth. Prioritize certification investment in ISO 50001 energy management to capture Singapore IMDA permit-driven replacement cycles. For New Entrants and Emerging Players: The 400-600 basis point spread between premium hyperscaler orchestration and economy colocation automation creates entry space for mid-market workflow specialists. Target Jakarta and Manila colocation operators seeking managed orchestration services to differentiate against lean-staffed hyperscaler facilities. Lead with grid-interactive switching systems productized from India's CEA mandate experience, selling compliance-as-a-service to emerging market operators. For Investors and Strategic Acquirers: The window for entry favors energy-aware automation specialists with proprietary DCIM-to-robotics integration layers and established hyperscaler reference architectures. Long-term viability hinges on 5-10 year regulatory tailwinds from Japan METI and Singapore IMDA efficiency mandates. Watch for inflection in India's PLI scheme disbursement velocity as signal for domestic component fabrication scale-up.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Integration Partnership | Hyperscaler facility commitments compress deployment timelines before concrete completion. |
| Energy-Aware Automation Acquisition | Seismic-resilient engineering teams in Osaka defend against METI compliance mandates. |
| Managed Orchestration Service Launch | Jakarta and Manila colocation operators seek differentiation against hyperscaler-owned facilities. |
| Grid-Interactive Protocol Productization | India CEA mandates create transferable compliance-as-a-service offerings for emerging markets. |
| Certification Investment Acceleration | ISO 50001 energy management captures Singapore IMDA permit-driven replacement demand. |
Research Methodology
SEC filings from listed automation vendors, hyperscaler capital expenditure disclosures, and Japan METI energy efficiency compliance databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with data center engineering directors, colocation procurement leads, and systems integration specialists validated deployment timelines and pricing benchmarks. Bottom-up facility count triangulation across Singapore, Sydney, Tokyo, Mumbai, and Jakarta combined with top-down automation spend per megawatt assumptions to anchor revenue estimates.
Bottom-up modeling segmented the market by product type, end user vertical, technology layer, and deployment model across the projection horizon. Segment-specific CAGRs were derived from facility construction pipeline analysis, regulatory mandate implementation schedules, and technology substitution curves for AI-driven predictive maintenance displacing scheduled human intervention. Key forecast inputs included hyperscaler commitment announcements, PLI scheme disbursement trajectories, and 5G edge facility rollout timelines from Australian and South Korean carriers.
Inputs from hyperscaler procurement offices and METI compliance filings were available through the study window; gaps in mid-tier colocation operator automation spend introduce uncertainty bands in the Jakarta and Manila market estimates. Forecasts reflect assumptions regarding regulatory mandate enforcement consistency and rare earth supply chain stability. A model refresh is warranted upon material change in Japan METI power usage effectiveness threshold adjustments or Singapore IMDA permit condition modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Marketing Automation Solutions Market
Automation
Laboratory Automation Market
Automation
Parcel Sorting System Market
Automation
Postal Automation System Market
Automation
Home Automation and Controls Market
Automation
Workload Scheduling and Automation Market
Automation
Global Process Automation and Instrumentation Market
Automation
IoT Home Automation Market
Automation
Self Bag Drop Machine Market
Automation
Process Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Europe Marketing Automation Software Market
Automation
Global Automated Liquid Handling System Market
Automation
Automation Lifecycle Services Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Global Automated Sample Storage Systems Market