
 Asia Pacific Marketing Automation Software Market | 2026-2036
Asia Pacific Marketing Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Marketing Automation Software Market Outlook
SaaS subscription financing and usage-based leasing is rewriting competitive dynamics across the Asia Pacific marketing automation landscape. Salesforce Inc. leverages extensive API integration capabilities to anchor enterprise accounts across Australia and Singapore. Zoho Corporation competes aggressively on price while sustaining deep localization for Indian small businesses.
Asia Pacific marketing automation software encompasses cloud-native and on-premises platforms that orchestrate multi-channel campaign execution, lead scoring, and behavioral analytics through machine-driven workflow engines. These systems process customer interaction data in real time to trigger personalized communications across email, social, and mobile touchpoints. Email marketing retains the largest revenue pool among product type segments, while social media management captures the fastest expansion as short-form video platforms proliferate. Cloud-based deployment dominates new installations, though hybrid architectures gain traction among Japanese and South Korean enterprises with legacy data residency requirements.
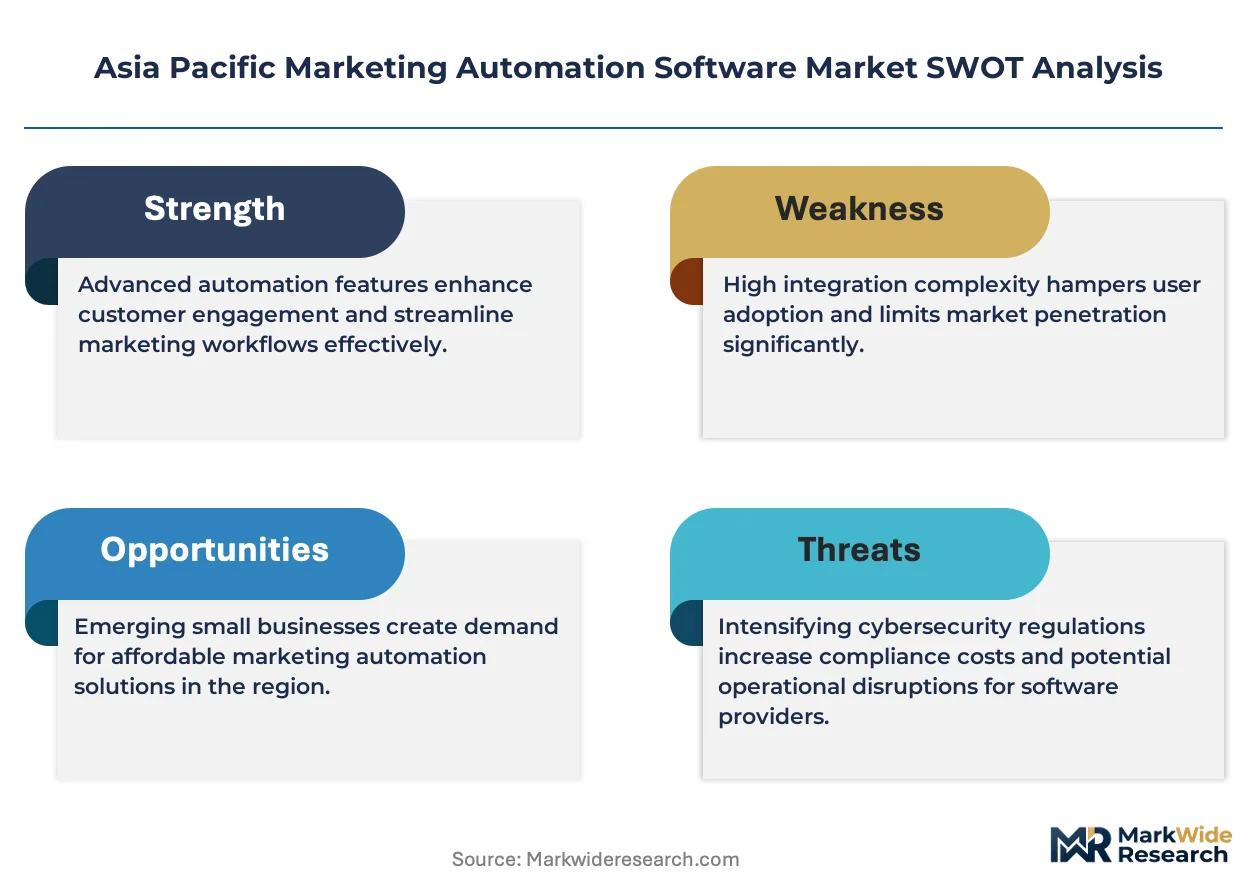
India's Digital Personal Data Protection Act, Australia's Privacy Act framework, and Singapore's PDPC guidelines collectively shape product roadmaps and data localization investments across the region. Vendors must engineer consent management modules and region-specific hosting to maintain market access. Stakeholders should monitor evolving cross-border data flow restrictions as the primary variable that could alter platform economics and customer acquisition costs.
Market Dynamics
Consent architecture rebuilds forced by India's Digital Personal Data Protection Act are fragmenting platform economics across Asia Pacific, compelling vendors to engineer region-specific hosting modules and data residency controls that alter customer acquisition costs.
Growth Catalysts
- E-commerce platform automation:Southeast Asian merchants are automating customer journeys across short-form video touchpoints, driving demand for behavioral analytics engines that process real-time interaction data.
- India's Digital Personal Data Protection Act:Compliance mandates are accelerating investment in consent management modules, creating upgrade cycles among existing marketing automation deployments.
- Cloud-native workflow engines:Machine-driven orchestration platforms are displacing legacy email-centric systems as Australian and Singaporean enterprises pursue multi-channel campaign execution.
Market Restraints
- Data localization requirements:Japanese and South Korean enterprises with legacy data residency mandates face hybrid architecture costs that cloud-native competitors avoid.
- Cross-border data flow restrictions:Evolving regulatory frameworks across Australia, Singapore, and India are creating compliance complexity that extends sales cycles.
- Technical talent scarcity:Shortages of machine learning engineers and privacy architects in emerging Southeast Asian markets constrain implementation velocity.
Strategic Opportunities
- Vietnam and Philippines e-commerce:Underpenetrated merchant segments in these markets present first-mover advantages for localized marketing automation platforms.
- PDPC guidelines in Singapore:Regulatory clarity around data governance is creating procurement tailwinds for vendors with pre-built compliance architectures.
- AI-powered predictive scoring:Convergence of generative models and behavioral analytics is opening premium pricing tiers for real-time lead qualification.
Industry Challenges
- Legacy system integration:On-premises customer databases in Japanese financial services require complex API bridging that extends deployment timelines.
- Certification timeline compression:Multiple overlapping privacy frameworks demand simultaneous compliance engineering, straining product roadmap bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Marketing Automation Software Market |
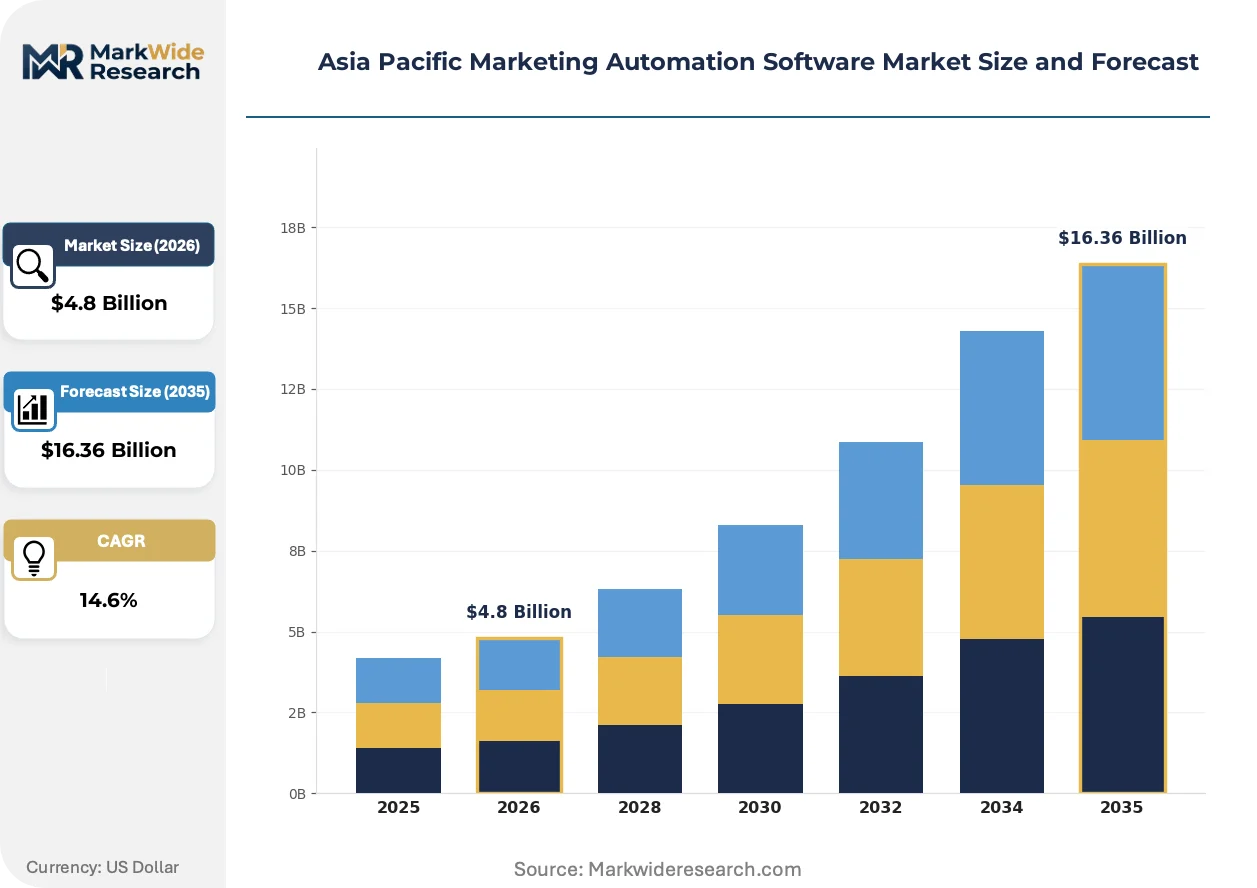
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Marketing, Social Media Management, Lead Management, Campaign Management End User: Small Businesses, Large Enterprises, Marketing Agencies, E-Commerce Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Integration Level: API Integration, CRM Integration, Third-Party Tools, Custom Solutions |
| Companies Covered | Microsoft Corporation, IBM Corporation, Adobe Systems, SAS Institute Inc., Teradata Corporation, Salesforce Inc., Hubspot Inc., Zoho Corporation, Oracle Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Marketing Automation Software Market Strategic Shifts
Machine-driven workflow virtualization is compressing the traditional campaign-to-conversion pipeline, while regulatory fragmentation and procurement model evolution are rewriting how vendors structure platform economics across the region.
Serverless behavioral analytics infrastructure is virtualizing the traditional campaign management stack. E-commerce merchants across Indonesia and Thailand are adopting these architectures fastest, eliminating dedicated server provisioning. This compression is virtualizing cost structures that previously required enterprise-scale IT commitments.
Singapore's PDPC guidelines on cross-border data transfers are mandating region-specific hosting configurations. Vendors must engineer separate consent architectures for Australian, Indian, and Singaporean deployments. Financial services and healthcare verticals across these three markets are responding with extended vendor evaluation cycles that prioritize pre-certified compliance modules.
Subscription-to-usage pricing migration is disrupting traditional SaaS contracting. Mid-market retailers in Australia are unbundling email marketing from full-platform licenses, purchasing event-triggered automation as discrete microservices. This behavioral shift is most visible among direct-to-consumer brands that prioritize cash-flow flexibility over feature breadth.
Asia Pacific Marketing Automation Software Market Segmentation
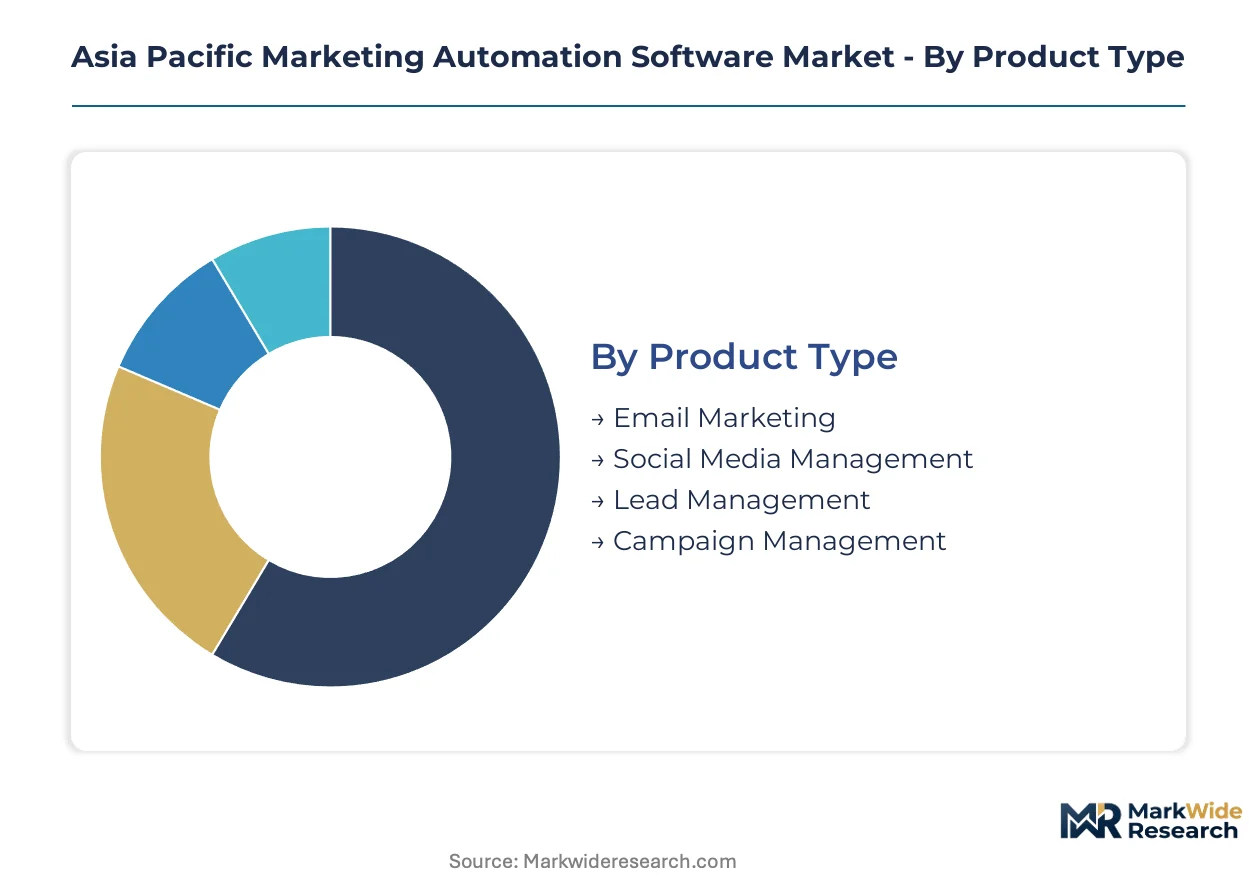
Marketing automation platforms fragment across four critical dimensions that determine deployment economics and vendor selection criteria. Each segmentation axis carries distinct implications for data residency compliance, integration complexity, and pricing architecture across Asia Pacific's heterogeneous regulatory landscape.
Product Type:
Cost tier separation in this category reflects diverging infrastructure requirements and per-seat pricing elasticity across customer segments.
- Email Marketing:Core orchestration engines deliver batch and triggered messaging through SMTP relay architectures and deliverability optimization layers. Indian small businesses and Australian mid-market retailers anchor demand, driven by India's Digital Personal Data Protection Act consent logging requirements that force platform migrations.
- Social Media Management:Short-form video platform APIs and real-time engagement analytics compress campaign-to-conversion pipelines. Southeast Asian e-commerce merchants in Indonesia and Thailand are rotating toward these tools fastest as TikTok Shop and Shopee Live integrations become non-negotiable.
- Lead Management:Behavioral scoring algorithms and pipeline stage automation for B2B sales cycles.
- Campaign Management:Multi-channel workflow orchestration with budget allocation and attribution modeling.
Email Marketing holds installed capacity. Social Media Management is rotating up the share rankings.
End User:
Application context determines feature depth requirements and willingness-to-pay thresholds across the customer base.
- E-Commerce:Real-time cart abandonment triggers and product recommendation engines process behavioral event streams through serverless architectures. Southeast Asian merchants represent the steepest expansion trajectory as Shopee, Lazada, and TikTok Shop sellers automate customer journeys across fragmented marketplaces.
- Large Enterprises:Multi-tenant governance layers and regional data residency controls satisfy Japanese and South Korean compliance mandates. Salesforce and Oracle deployments concentrate in Australian financial services and Singaporean healthcare verticals where PDPC guidelines mandate audit trails.
- Small Businesses:Zoho and HubSpot tiered offerings with simplified workflow builders.
- Marketing Agencies:White-label capabilities and multi-account dashboards for client portfolio management.
Large Enterprises hold installed capacity. E-Commerce is rotating up the share rankings.
Deployment:
Volume scalability and capital commitment structure separate procurement preferences across maturity levels.
- Cloud-Based:Serverless auto-scaling eliminates capacity planning for seasonal demand spikes. Singaporean and Australian enterprises lead adoption, prioritizing OpEx flexibility over infrastructure ownership as subscription-to-usage pricing models proliferate.
- Hybrid:Split architectures retain sensitive customer data on-premises while pushing campaign execution to cloud edge nodes. Japanese financial services and South Korean chaebol subsidiaries require these configurations to satisfy legacy data residency mandates without sacrificing real-time personalization.
- On-Premises:Fully captive infrastructure for air-gapped environments in defense and critical infrastructure.
- SaaS:Multi-tenant shared infrastructure with standardized feature releases and pooled security patching.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
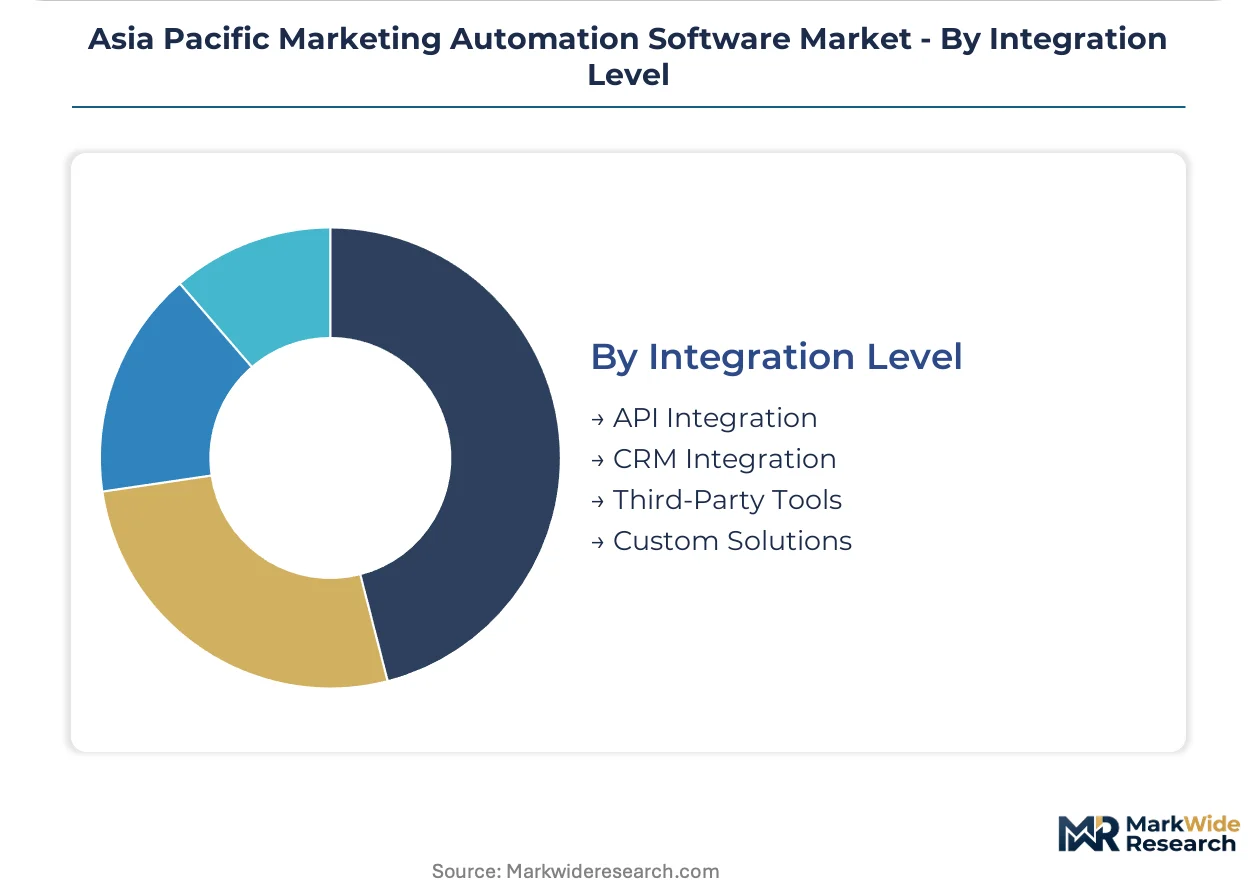
Integration Level:
Customer type and technical maturity dictate connectivity depth and professional services attachment rates.
- API Integration:REST and GraphQL endpoints enable custom data flows between marketing automation and proprietary systems. Australian fintechs and Singaporean insurtechs anchor demand, building bespoke customer data platforms that bypass native CRM connectors.
- CRM Integration:Pre-built connectors to Salesforce, Microsoft Dynamics, and Zoho synchronize lead records and campaign responses. Indian IT services firms and Philippine BPOs deploy these heavily for client account management at scale.
- Third-Party Tools:Marketplace plugins for analytics, advertising, and collaboration stacks.
- Custom Solutions:Professional services engagements for legacy system bridging and data migration.
CRM Integration holds installed capacity. API Integration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific marketing automation software flows exhibit distinct import-export patterns across national boundaries. India and Singapore function as net technology exporters, hosting regional headquarters that serve neighboring markets. Australia retains a services trade surplus in martech consulting while importing core platform licenses from US and European parents.
India
Domestic demand from e-commerce merchants and IT services firms drives platform adoption. The Digital Personal Data Protection Act mandates consent logging architectures that force upgrade cycles among existing deployments. Bengaluru and Hyderabad host engineering centers where vendors rebuild data residency modules for regional compliance.
Australia
Financial services and retail verticals anchor enterprise demand for multi-channel orchestration. The Privacy Act framework and OAIC enforcement actions extend procurement cycles as vendors pre-certify compliance modules. Sydney and Melbourne concentrate implementation partnerships serving Asia Pacific headquarters of multinational corporations.
Singapore
PDPC guidelines on cross-border data transfers create procurement tailwinds for vendors with pre-built governance architectures. The city-state functions as regional headquarters for vendors serving Southeast Asian markets. Raffles Place and Marina Bay financial districts concentrate financial services and healthcare deployments requiring audit trail capabilities.
Japan
Legacy data residency requirements in financial services and manufacturing sustain hybrid architecture demand. METI industrial policy encourages domestic cloud adoption while respecting existing on-premises investments. Tokyo and Osaka host enterprise accounts where Salesforce and Oracle compete for multi-tenant governance contracts.
South Korea
Chaebol subsidiaries and financial institutions require split architectures that retain sensitive data on-premises. MFDS and financial regulator guidelines shape vendor certification requirements for healthcare and banking verticals. Seoul's Gangnam and Yeouido districts concentrate enterprise procurement decisions affecting regional platform economics.
Asia Pacific Marketing Automation Software Market Competitive Environment
On the supply side, the industry is consolidating around three distinct competitive tiers. Enterprise software conglomerates anchor the premium segment through extensive API integration capabilities. Mid-market specialists compete on localized pricing and simplified deployment. Cloud-native challengers displace legacy email-centric systems through serverless architectures. Dominant competitive moves include geographic expansion into underpenetrated Southeast Asian markets and portfolio diversification into adjacent customer data platform categories.
Within the enterprise tier, Salesforce Inc. and Microsoft Corporation exemplify platform consolidation strategies that bundle marketing automation with broader cloud ecosystems. Zoho Corporation occupies a distinct position among India-based specialists competing aggressively on price while sustaining deep localization for small business segments. Hubspot Inc. represents the mid-market archetype that unbundles email marketing from full-platform licenses as subscription-to-usage pricing proliferates among Australian direct-to-consumer brands.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Adobe Systems |
| SAS Institute Inc. |
| Teradata Corporation |
| Salesforce Inc. |
| Hubspot Inc. |
| Zoho Corporation |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
The Singapore-Jakarta data center corridor's bandwidth cost dynamics compress margin structures for cloud-native vendors while amplifying price differentiation between API-heavy enterprise tiers and standardized SaaS offerings. Indian engineering centers feed cost-advantaged development into Southeast Asian deployments, creating geographic arbitrage that vendors exploit across consent-architecture rebuilds mandated by the Digital Personal Data Protection Act.
Pricing Analysis
Large enterprise buyers anchor subscription-to-usage pricing migration across Australian and Singaporean deployments. Three-tier pricing structure across premium API-integration, standard CRM-connector, and economy email-centric levels separates Salesforce and Oracle multi-tenant governance contracts from Zoho's localized small-business tiers. Pricing pressure stems from unbundling trends among mid-market retailers purchasing event-triggered automation as discrete microservices. Small businesses exhibit highest price sensitivity, while financial services verticals prioritize pre-certified compliance modules over cost.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers and supply-chain finance facilities reduce working capital pressure for vendors scaling serverless infrastructure. Engineering talent concentrates in India, Australia, and Singapore, with Bengaluru and Hyderabad hosting consent-architecture rebuild centers. Raw material dependencies include GPU compute clusters, data center real estate, and API access licenses from short-form video platforms. Single-source vulnerability runs through TikTok Shop and Shopee Live integration partnerships. Distribution runs through direct enterprise sales teams in Sydney and Singapore plus channel partners serving Southeast Asian e-commerce merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific marketing automation software functions as a service-attach opportunity where implementation partnerships and compliance consulting layers expand faster than core platform licensing. Recurring revenue from consent-management module upgrades and API integration professional services outpaces new customer acquisition economics.
For Market Incumbents: Entrench multi-tenant governance capabilities through pre-certified compliance architectures that satisfy PDPC guidelines and India's Digital Personal Data Protection Act simultaneously. Deepen API integration moats against cloud-native challengers by embedding serverless behavioral analytics into existing Salesforce and Oracle deployments. Prioritize channel control over Australian fintech and Singaporean insurtech verticals where bespoke customer data platform builds bypass native CRM connectors.
For New Entrants and Emerging Players: Vietnam and Philippines e-commerce merchant segments offer first-mover terrain for localized marketing automation platforms with TikTok Shop-native onboarding workflows. Philippine BPOs and Vietnamese direct-to-consumer brands represent the most penetrable buyer archetypes, with procurement decisions concentrated in Manila and Ho Chi Minh City commercial districts. Lead with usage-based microservices pricing that unbundles email marketing from full-platform commitments.
For Investors and Strategic Acquirers: Carve-out targets emerge from US-based enterprise software parents seeking to divest non-core regional marketing automation assets lacking localized consent architectures. Mid-market specialists with pre-built PDPC compliance modules and established Southeast Asian channel relationships present viable acquisition profiles. Monitor cross-border data flow restriction announcements from Australian OAIC and Singapore PDPC as inflection indicators that would accelerate consolidation among vendors lacking region-specific hosting investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Consent Architecture Rebuild | Compliance engineering investments satisfy India's Digital Personal Data Protection Act mandates while creating upgrade revenue cycles. |
| Serverless Infrastructure Deployment | Auto-scaling behavioral analytics eliminates capacity planning for Indonesian and Thai e-commerce seasonal demand spikes. |
| API Integration Deepening | REST and GraphQL endpoint expansion anchors Australian fintech and Singaporean insurtech accounts against platform switching. |
| Geographic Expansion into Vietnam | Localized TikTok Shop integrations capture underpenetrated merchant segments before incumbent channel establishment. |
| Professional Services Attachment | Implementation partnerships in Sydney and Melbourne generate recurring revenue from legacy system bridging engagements. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at Australian fintechs, IT procurement officers at Singaporean healthcare systems, platform engineers at Indian IT services firms, and channel partners serving Southeast Asian e-commerce merchants. Secondary validation drew from SEC filings of listed enterprise software vendors, hyperscaler capex disclosures from AWS and Azure regional expansion announcements, and PDPC enforcement action databases. Bottom-up deployment counts across cloud-native and hybrid architectures were triangulated against top-down addressable market sizing from regional IT spending surveys.
Calibration against historical adoption curves in comparable regulatory environments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size tier, vertical industry, integration complexity level, and regional adoption pattern. CAGRs were derived from elasticity-adjusted growth rate synthesis. Forecast inputs incorporated e-commerce GMV trajectories across Shopee, Lazada, and TikTok Shop platforms plus data center capacity expansion timelines in Singapore and Sydney.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by Microsoft or Salesforce would shift outcomes beyond modeled ranges. Macroeconomic contraction in Australian retail, regulatory fragmentation accelerating beyond India's Digital Personal Data Protection Act timeline, or generative AI disruption of behavioral analytics workflows would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Italy Marketing Automation Market
Automation
Hyperautomation Market
Automation
Indonesia Automation and Control System Market
Automation
Automation-As-A-Service Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Window Automation Market
Automation
Digital Process Automation Market
Automation
Laboratory Automation Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
US Workload Scheduling and Automation Market
Automation
United States Laboratory Automation Market
Automation
Distributed Control System Market
Automation
Smart Home Automation Market
Automation
RFID Kanban Systems Market
Automation
North America Marketing Automation Software Market