
 Asia-Pacific Commercial Vehicles Lubricants Market | 2026-2036
Asia-Pacific Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Vehicles Lubricants Market Outlook
The gap between premium synthetic formulations and commodity mineral-based lubricants is broadening across Asia-Pacific commercial fleets. ENEOS Corporation leverages its Japanese R&D base to supply high-performance engine oils for severe-duty applications, while Indian Oil Corporation Limited anchors its position through extensive distribution networks serving domestic fleet operators. China National Petroleum Corporation dominates upstream feedstock access, allowing integrated cost structures that commodity blenders cannot replicate.
Asia-Pacific commercial vehicles lubricants encompass refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in powertrain components operating under sustained heavy loads. These products typically maintain viscosity stability across temperature ranges from minus twenty degrees Celsius to one hundred fifty degrees Celsius while meeting OEM drain-interval specifications. Engine oil commands the largest revenue pool given per-unit consumption volumes and formulation complexity, though transmission fluid generates superior margins due to specialized additive packages and narrower supplier bases. Hydraulic oil applications in construction equipment represent the fastest-growing segment as infrastructure investment accelerates across Indonesia and Vietnam.
China's MIIT enforces GB standards governing lubricant performance and emissions compatibility, while India's BIS certifies products for domestic commercial use under mandatory quality orders. Japan's METI promotes next-generation fuel-economy standards that directly influence lubricant viscosity grade specifications for imported and domestic vehicles. Stakeholders must monitor regulatory divergence between national standards bodies, as compliance fragmentation across the region will determine which formulation portfolios retain market access.
Market Dynamics
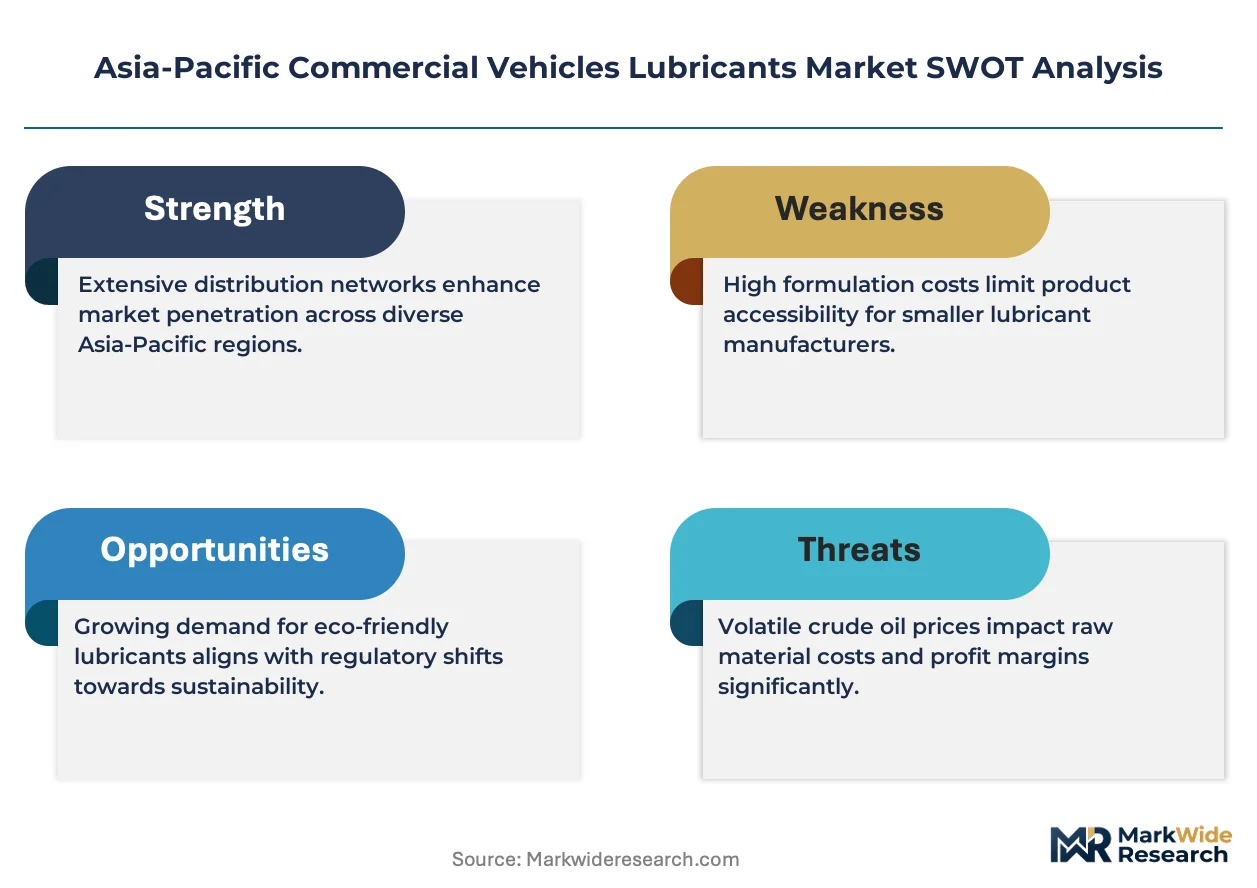
China's MIIT emission standards and India's BIS fuel-efficiency mandates are compressing formulation cycles, forcing blenders to retire mineral-based portfolios before amortization while synthetic capacity expansion lags demand acceleration across Southeast Asian logistics corridors.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement of carbon intensity benchmarks is compelling fleet operators to specify lower-viscosity engine oils that reduce fuel consumption in heavy-duty trucks operating along the Yangtze River Delta corridor.
- Construction equipment deployment:Indonesia's infrastructure investment acceleration is expanding hydraulic oil consumption in excavators and earth-moving machinery, with state-backed projects in Java and Sumatra anchoring bulk procurement.
- Transmission fluid specifications:OEM drain-interval extension requirements for automated manual transmissions are driving demand for specialized additive packages that withstand higher thermal loads in severe-duty applications.
Market Restraints
- Base oil supply concentration:China National Petroleum Corporation and Sinopec control upstream Group II/III feedstock access, limiting independent blenders' cost structure flexibility.
- Technical limitation:Current synthetic formulations face viscosity stability challenges in high-altitude operations across the Himalayan foothills where temperature differentials exceed formulation tolerances.
- Regulatory friction:Divergent GB standards between China's MIIT and India's BIS create compliance fragmentation, requiring parallel certification investments for cross-border suppliers.
Strategic Opportunities
- Vietnam's central region:Underpenetrated fleet lubricant markets in Da Nang and Quy Nhon present first-mover advantages as manufacturing investment shifts from southern China.
- Electric commercial vehicle compatibility:Thermal management fluid formulations for battery-electric trucks represent an emerging application as OEMs in Japan and South Korea accelerate electrification roadmaps.
- Direct fleet contracting:Bypassing traditional distributor networks through telematics-integrated supply agreements is reshaping procurement in Australia's long-haul mining transport sector.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in friction-modifier additive chemistry is concentrating at Japanese and South Korean headquarters, constraining regional R&D localization.
- Certification timeline compression:Accelerated OEM specification updates are outstripping BIS and GB approval cycles, creating market access gaps for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Vehicles Lubricants Market |
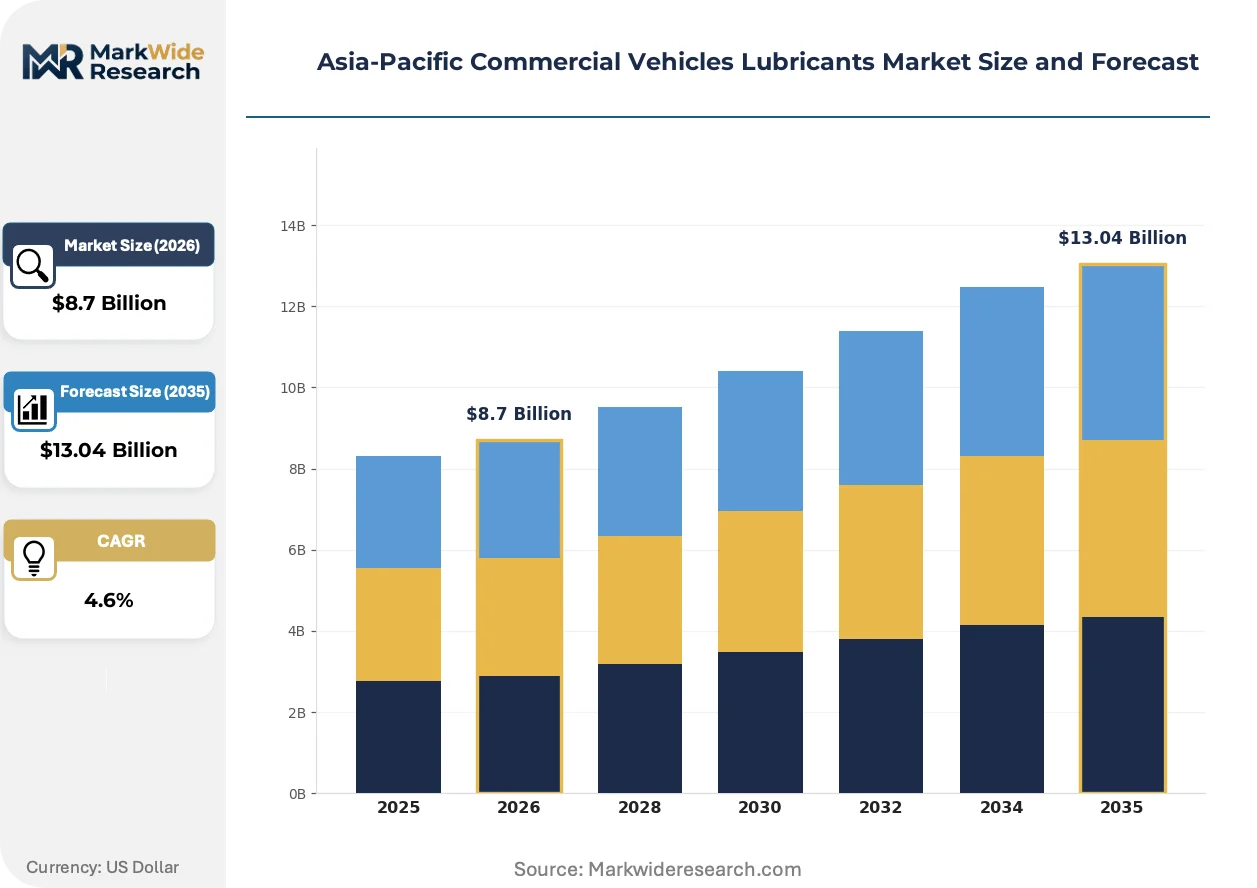
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Hydraulic Oil Service Type: Routine Maintenance, Emergency Repairs, Preventive Service, Engine Overhaul End User: Fleet Operators, Transportation Companies, Logistics Providers, Municipal Services Application: Heavy-Duty Trucks, Buses, Construction Equipment, Agricultural Vehicles |
| Companies Covered | China National Petroleum Corporation, ENEOS Corporation, BP PLC (Castrol), PT Pertamina, Indian Oil Corporation Limited, Chevron Corporation, China Petroleum & Chemical Corporation, PTT Lubricants, ExxonMobil Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Vehicles Lubricants Market Strategic Shifts
Reformulation toward lower-viscosity grades is restructuring competitive advantage, with additive package sophistication separating suppliers capable of meeting extended drain intervals from commodity blenders facing margin compression.
Polyalphaolefin-based synthetic engine oils are overtaking Group III mineral formulations in severe-duty fleet applications. Japanese heavy-duty operators in Hokkaido's cold-climate corridors specify PAO grades for pour-point performance below minus forty degrees Celsius. This technology is overtaking conventional hydrocracked stocks in premium segments, compressing the addressable market for mid-tier blenders lacking Group IV/V capacity.
India's BIS mandatory quality orders for commercial vehicle lubricants are eliminating substandard formulations from domestic distribution. The regulatory consequence is a consolidation of approved supplier lists, with unregistered blenders losing access to Maharashtra and Gujarat transportation hubs. Fleet operators in these western industrial belts are responding by centralizing procurement through certified vendors with documented traceability.
Consolidated fleet procurement through telematics-enabled usage-based contracts is displacing traditional spot purchasing. Large logistics operators in Australia's Pilbara mining region and Indonesia's coal transport corridors are unbundling lubricant supply from equipment maintenance agreements. This behavioral shift is most visible in Japan, where METI-promoted fuel-economy standards have conditioned fleet managers to specify lubricants as energy-efficiency investments rather than commodity consumables.
Asia-Pacific Commercial Vehicles Lubricants Market Segmentation
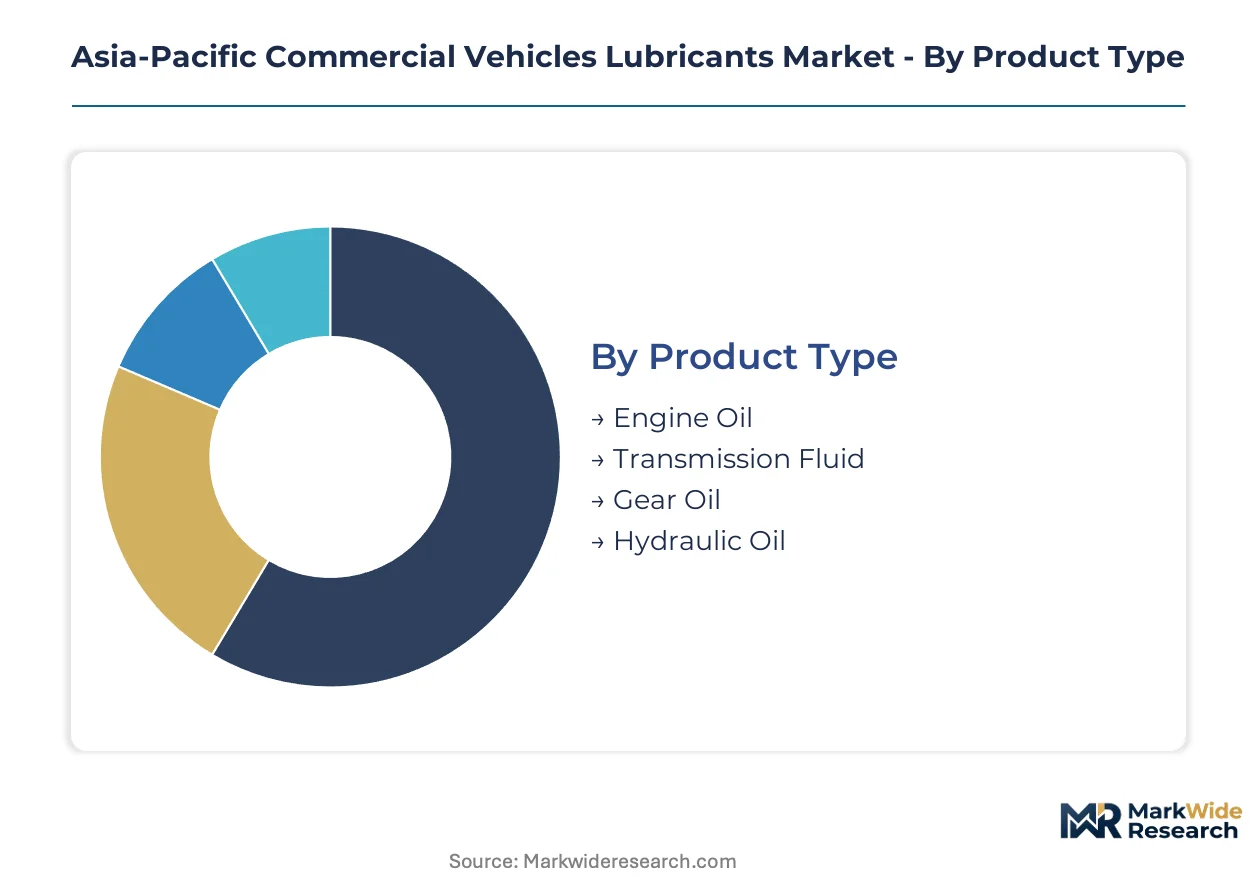
Commercial vehicle lubricant procurement patterns diverge sharply across product formulations and service modalities. Fleet operators in Asia-Pacific corridors select lubricant specifications based on OEM drain-interval requirements, operating climate severity, and total cost of ownership calculations rather than unit price alone.
Product Type:
Supply concentration in Group II/III base oils among Chinese state-owned refiners shapes competitive dynamics across lubricant categories, with independent blenders facing feedstock access constraints that favor integrated producers.
- Engine Oil:Formulations range from mineral-based 15W-40 grades to synthetic 5W-30 low-viscosity specifications engineered for fuel economy. Demand concentrates in India's western industrial belt where Gujarat and Maharashtra transportation hubs specify extended-drain products for heavy-duty trucks operating under BIS mandatory quality orders.
- Transmission Fluid:Specialized additive packages withstand thermal loads in automated manual transmissions, generating superior margins through narrower supplier bases. Japanese fleet operators in severe-duty cold-climate corridors specify polyalphaolefin-based grades for pour-point performance below minus forty degrees Celsius.
- Gear Oil:Hypoid gear formulations for differential and axle applications maintain film strength under high-load conditions.
- Hydraulic Oil:Anti-wear formulations for construction and agricultural equipment represent the segment expanding most quickly as Indonesia's state-backed infrastructure projects in Java and Sumatra accelerate equipment deployment.
Today's leader: Engine Oil. Tomorrow's challenger: Hydraulic Oil.
Service Type:
Cost tier differentiation separates scheduled maintenance programs from reactive service interventions, with premium positioning attaching to predictive and usage-based offerings.
- Routine Maintenance:Scheduled oil changes at OEM-specified intervals dominate volume procurement through distributor networks serving fleet operators across Southeast Asian logistics corridors.
- Emergency Repairs:Unplanned lubricant replacement following component failure commands price premiums due to downtime costs and expedited logistics requirements.
- Preventive Service:Oil analysis programs and condition-based replacement are gaining share fastest as telematics-enabled fleet management systems penetrate Australia's Pilbara mining transport sector.
- Engine Overhaul:Complete lubricant system refurbishment during powertrain rebuilds specifies high-detergent formulations for post-warranty commercial vehicles.
Preventive Service is climbing the fastest as digitization reshapes procurement.
End User:
Customer type determines contract structure, with consolidated fleet operators extracting volume discounts unavailable to fragmented owner-operators.
- Fleet Operators:Large logistics companies centralize lubricant procurement through direct supplier agreements, bypassing traditional distributor networks in Japan's METI-influenced fuel-efficiency procurement frameworks.
- Transportation Companies:Regional bus and coach operators specify products meeting OEM warranty requirements while balancing acquisition cost against drain-interval extension benefits.
- Logistics Providers:Third-party fulfillment operators in Vietnam's central region present first-mover opportunities as manufacturing investment shifts from southern China.
- Municipal Services:Government fleet procurement follows standardized specifications with emphasis on local supplier registration and documented traceability under national quality orders.
Fleet Operators command current volume. Logistics Providers show steepest expansion trajectory.
Application:
Operating environment severity dictates formulation specifications, with construction and mining applications demanding thermal stability beyond highway duty cycles.
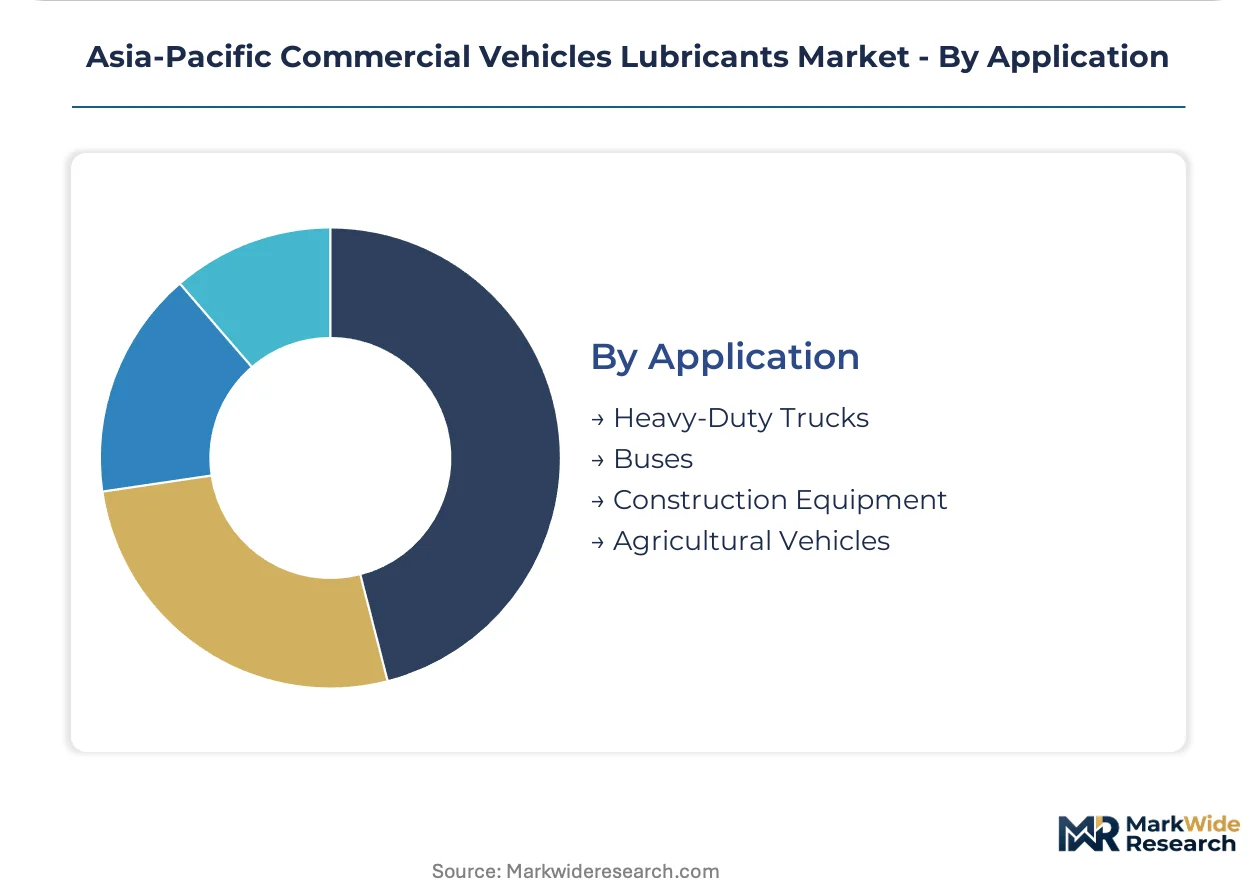
- Heavy-Duty Trucks:Long-haul freight operators along China's Yangtze River Delta corridor specify lower-viscosity engine oils compliant with MIIT emission standards to reduce fuel consumption intensity.
- Buses:Urban transit applications with stop-start duty cycles prioritize oxidation-resistant formulations for extended service intervals in high-temperature operating conditions.
- Construction Equipment:Excavators and earth-moving machinery in Indonesia's infrastructure acceleration drive hydraulic oil consumption with specialized anti-wear additive packages.
- Agricultural Vehicles:Tractor and harvester applications in India's western states require all-season viscosity stability across temperature ranges from minus twenty to one hundred fifty degrees Celsius.
Heavy-Duty Trucks anchor present demand. Construction Equipment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in Japanese and South Korean headquarters, constraining regional R&D localization while state-owned refiners in China dominate upstream feedstock access.
China
Heavy-duty truck utilization intensifies along the Yangtze River Delta corridor as fleet operators specify lower-viscosity engine oils. MIIT enforces GB standards governing lubricant performance and emissions compatibility. Shanghai and Jiangsu province transportation hubs anchor bulk consumption as dual carbon goals compress formulation cycles.
India
Gujarat and Maharashtra-based transportation hubs drive bulk procurement of extended-drain products for heavy-duty trucks. BIS mandatory quality orders certify products for domestic commercial use under mandatory quality frameworks. Fleet operators in the western industrial belt centralize procurement through certified vendors with documented traceability.
Japan
METI-promoted fuel-economy standards condition fleet managers to specify lubricants as energy-efficiency investments. Next-generation fuel-economy standards directly influence lubricant viscosity grade specifications for imported and domestic vehicles. Hokkaido's cold-climate corridors specify polyalphaolefin-based grades for pour-point performance below minus forty degrees Celsius.
Indonesia
State-backed infrastructure projects in Java and Sumatra accelerate hydraulic oil consumption in excavators and earth-moving machinery. Construction equipment deployment expands hydraulic oil applications as infrastructure investment accelerates. Jakarta and Surabaya logistics corridors anchor equipment procurement for mining and transport sectors.
Vietnam
Manufacturing investment shifts from southern China into Da Nang and Quy Nhon present first-mover advantages in underpenetrated fleet lubricant markets. Logistics providers in the central region specify products meeting OEM warranty requirements while balancing acquisition cost against drain-interval benefits. Ho Chi Minh City remains the dominant consumption hub for southern corridor freight operations.
Asia-Pacific Commercial Vehicles Lubricants Market Competitive Environment
Top-tier vendors anchor integrated upstream-downstream positions, while independent blenders face feedstock access constraints. State-owned refiners control Group II/III base oil supply concentration, limiting cost structure flexibility for non-integrated competitors. Three strategic archetypes dominate: integrated national oil companies with captive feedstock, multinational lubricant specialists with additive technology leadership, and regional distributors with fleet contracting relationships. Competitive moves center on synthetic capacity expansion and telematics-integrated direct supply agreements.
Within the integrated national oil company tier, China National Petroleum Corporation and China Petroleum & Chemical Corporation exemplify upstream control over Group II/III feedstock access. ENEOS Corporation occupies a position representing Japanese R&D-base specialization in high-performance formulations for severe-duty applications. Indian Oil Corporation Limited anchors the extensive distribution network archetype serving domestic fleet operators across certified vendor frameworks.
| Leading Market Players |
|---|
| China National Petroleum Corporation |
| ENEOS Corporation |
| BP PLC (Castrol) |
| PT Pertamina |
| Indian Oil Corporation Limited |
| Chevron Corporation |
| China Petroleum & Chemical Corporation |
| PTT Lubricants |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist scarcity in Japan and South Korea widens pricing-tier spreads across the Asia-Pacific commercial vehicles lubricants market, as labor-cost differentials between specialized synthetic-blending expertise and commodity-compounding operations translate into premium-mid-economy pricing stratification that fleet operators navigate under divergent national quality mandates.
Pricing Analysis
Bundled maintenance contracts versus unbundled spot purchasing splits the pricing architecture across fleet procurement modalities. Three-tier pricing structure across premium synthetic, certified mineral, and unregistered economy levels reflects BIS and GB certification status alongside volume-scale discounts. Cost compression in commodity mineral tiers intensifies because Chinese state-owned refiners leverage captive Group II/III feedstock access. Owner-operators in fragmented Southeast Asian corridors exhibit highest price sensitivity, while Japanese fleet managers under METI fuel-efficiency frameworks prioritize performance over unit cost.
Supply Chain Analysis
Certification gating under India's BIS mandatory quality orders and China's MIIT GB standards fragments supplier access to western industrial belt consumption clusters. Upstream concentration in China, Japan, and South Korea shapes base oil availability, with formulation draws from polyalphaolefin stocks, hydrocracked Group III feeds, and specialized friction-modifier additive packages. Single-source vulnerability concentrates in Chinese state-owned refinery control over Group II/III capacity. Distribution runs through certified vendor networks serving Maharashtra and Gujarat transportation hubs, with telematics-enabled direct contracting emerging in Australia's Pilbara mining sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific commercial vehicles lubricants market represents a late-cycle quality story, as fleet procurement shifts decisively toward extended-drain synthetic specifications that reduce total cost of ownership despite higher upfront unit pricing.
For Market Incumbents: Anchor synthetic capacity expansion in Vietnam's central region to capture manufacturing investment migration from southern China, while deepening backward integration into additive-package chemistry to defend margin position against integrated national oil companies with captive feedstock control. Prioritize BIS and GB certification maintenance as regulatory timeline compression threatens market access for reformulated products awaiting approval cycles. For New Entrants and Emerging Players: Thermal management fluid formulations for battery-electric commercial vehicles present a technology-first wedge into electrification-adjacent white space, with Japanese and South Korean OEM roadmaps creating penetrable demand ahead of incumbent portfolio rebalancing. Target Vietnam's Da Nang and Quy Nohn logistics corridors through telematics-integrated usage-based supply agreements that bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Integrated national oil companies with captive base oil access are the most active acquirer in this space, consolidating independent blenders facing feedstock cost-structure disadvantages. Long-term viability hinges on synthetic formulation capabilities and certification portfolio breadth. Watch for MIIT emission standard acceleration as the inflection indicator triggering reformulation investment cycles and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Capacity Expansion | Captures premium positioning as PAO formulations overtake mineral grades in severe-duty fleet applications. |
| Backward Integration into Additive Chemistry | Reduces dependency on Japanese and South Korean friction-modifier expertise concentrating at headquarters. |
| Telematics-Integrated Direct Supply Agreements | Reshapes procurement in Australia's Pilbara mining transport sector by unbundling lubricant from maintenance contracts. |
| Dual Certification Investment (BIS/GB) | Preserves market access across India's western industrial belt and China's Yangtze River Delta corridor amid regulatory divergence. |
| Electric Vehicle Thermal Fluid Development | Positions portfolios for battery-electric truck deployment as OEMs in Japan and South Korea accelerate electrification roadmaps. |
Study Parameters
Direct dialogue with lubricant blending plant managers, fleet procurement directors at logistics operators, BIS certification officers, and aftermarket distribution channel partners grounded the qualitative foundation, cross-referenced against customs trade data, MIIT regulatory filings, SEC 10-K disclosures from integrated oil companies, and base oil production statistics from Chinese state-owned refiners. Bottom-up volume builds triangulated with top-down market sizing across product formulation tiers.
Segment-level value projections emerged from modeling engine oil, transmission fluid, and hydraulic oil demand across fleet operator, logistics provider, and municipal service end-user categories, with propulsion architecture and regional regulatory cluster dimensions incorporated throughout the projection horizon. CAGRs derived from elasticity-adjusted consumption curves responding to OEM drain-interval specifications and infrastructure investment trajectories in Indonesia and Vietnam.
The model holds under stable regulatory certification timelines and continued fleet consolidation trends; deviation in MIIT or BIS approval acceleration, or sudden base oil supply disruption from Chinese refinery capacity adjustments, would shift volume and value trajectories. A model refresh is warranted upon material change in electric commercial vehicle penetration rates or substantive revision to national emission standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
South Korea Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
High Performance Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Kenya Lubricants Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Marine Grease Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Textile Machine Lubricants Market