
 Automotive Data Monetization Market | 2026-2036
Automotive Data Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Data Monetization Market Analysis
Multi-source data aggregation from tier-1 suppliers, cloud platforms, and aftermarket sensor networks is recalibrating how OEMs build data pipelines. Harman International Industries leverages its embedded infotainment footprint to capture cabin and powertrain signals at the edge. Wejo Group Limited anchors its position through direct vehicle-to-cloud connectivity partnerships with major automakers. Continental AG competes on the strength of its integrated sensor-to-analytics stack spanning braking, powertrain, and ADAS domains.
Automotive data monetization encompasses the extraction, aggregation, and commercialization of machine-generated vehicle information through standardized APIs, edge computing nodes, and privacy-preserving federated architectures. Raw data streams undergo normalization, anonymization, and valuation before delivery to downstream buyers across insurance, urban planning, and predictive maintenance verticals. Telematics data and vehicle diagnostics currently dominate transaction volumes due to their direct applicability in usage-based insurance and remote condition monitoring programs. Software solutions within the service type dimension command premium pricing because they embed proprietary algorithms that transform raw feeds into actionable risk scores and operational dashboards. OEMs as an end-user category retain the deepest data lakes but face structural pressure to open access under regulatory mandates and competitive fleet-manager demands.
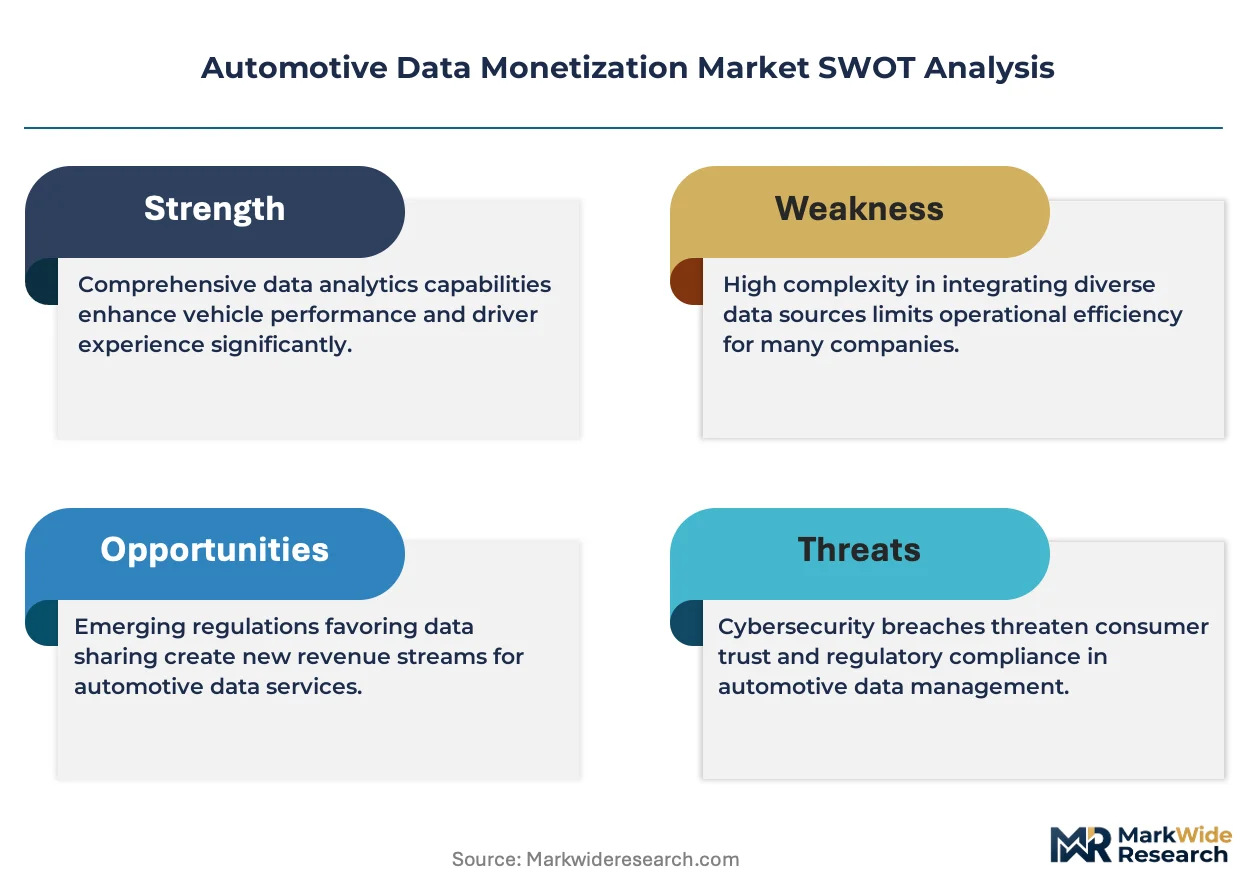
The EU AI Act and GDPR impose strict algorithmic transparency and purpose-limitation requirements on automated decision systems consuming driver behavior data. The California Consumer Privacy Act and emerging state-level statutes in the United States create a fragmented compliance map that increases platform engineering costs for cross-border deployments. Stakeholders must monitor the divergence between European data-localization mandates and American sectoral privacy approaches when architecting scalable revenue models.
Market Dynamics
EU AI Act compliance deadlines are forcing OEMs to rebuild consent management infrastructure from the ground up, triggering wholesale re-architecture of data pipelines and supplier contracts across the value chain.
Growth Catalysts
- Usage-based insurance expansion:Live telematics feeds enable dynamic risk scoring that replaces static actuarial tables. Insurers in Germany and Japan now mandate OEM data partnerships for fleet policies.
- GDPR Article 20 portability rights:Driver data ownership claims are creating standardized API demand. Fleet managers leverage this to consolidate multi-brand vehicle pools under single analytics dashboards.
- Edge computing node deployment:Embedded inference chips process cabin and powertrain signals locally. This architecture reduces cloud egress costs while satisfying data residency requirements.
Market Restraints
- Cross-border data localization:GDPR-mandated EU residency conflicts with US CLOUD Act reach. Platform engineering costs surge for architectures spanning Frankfurt and Virginia data centers.
- Sensor hardware concentration:LiDAR and high-resolution camera modules rely on Taiwanese semiconductor packaging capacity. Geopolitical friction threatens component availability for aftermarket retrofit networks.
- Anonymization technical limits:Re-identification attacks on sparse vehicle trajectory datasets expose liability gaps. Insurers hesitate to underwrite data breach policies for aggregated mobility feeds.
Strategic Opportunities
- India fleet telematics penetration:Commercial vehicle data capture rates remain below 15%. PLI scheme subsidies for automotive electronics manufacturing reduce hardware deployment costs for domestic platform operators.
- Predictive maintenance convergence:Brake wear algorithms fused with traffic pattern data enable just-in-time service scheduling. Independent repair chains in the United States pilot subscription access to OEM diagnostic streams.
- CSRD sustainability reporting:Mandatory Scope 3 emissions disclosure requires granular vehicle utilization data. Corporate fleet buyers now specify data-sharing clauses in lease agreements.
Industry Challenges
- Federated learning engineering scarcity:Privacy-preserving model training across siloed OEM datasets demands specialized distributed systems expertise. Compensation premiums for this talent pool exceed 40% above standard ML engineering roles.
- Legacy CAN bus integration:Pre-2020 vehicle fleets lack standardized OBD-II data dictionaries. Retrofit hardware must map proprietary manufacturer signal formats to open telemetry schemas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Data Monetization Market |
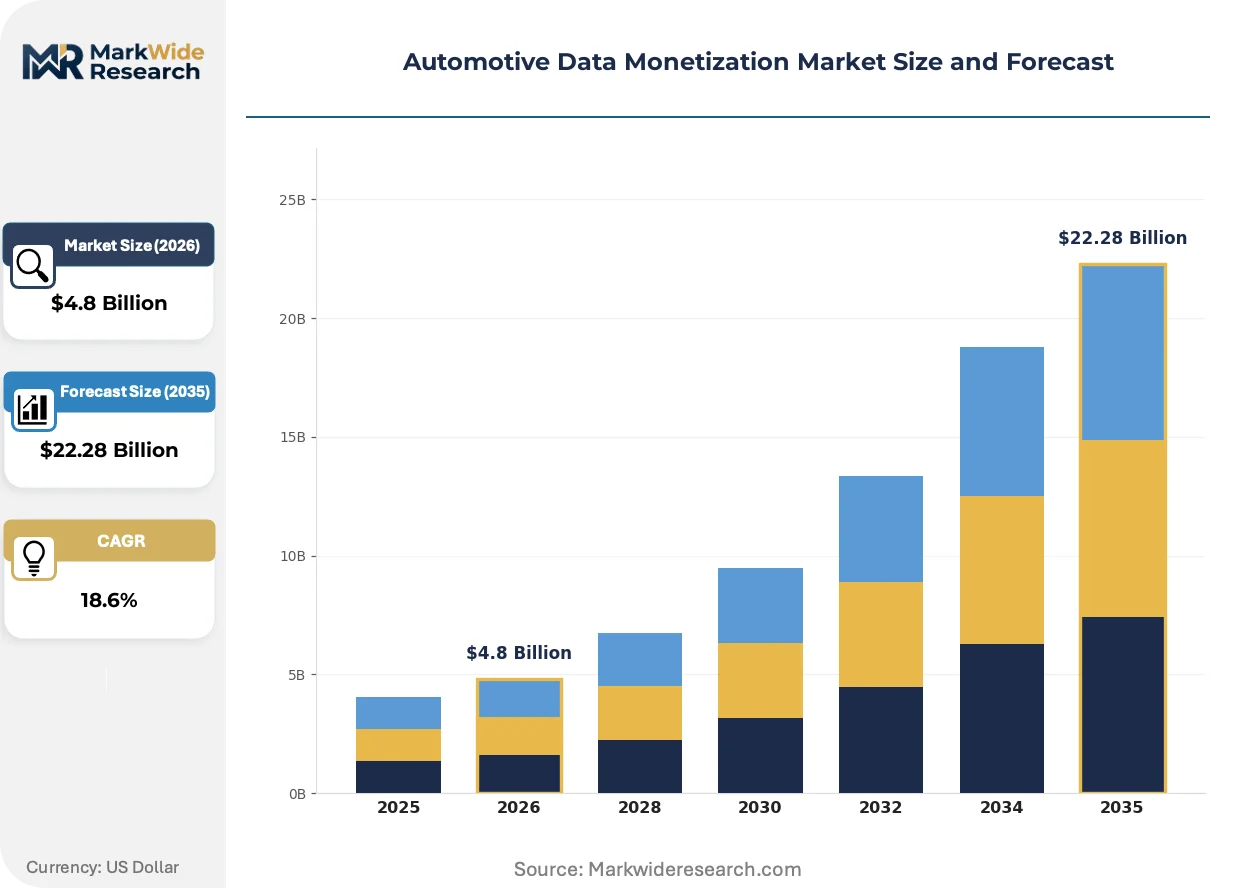
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Type: Telematics Data, Vehicle Diagnostics, Driver Behavior, Usage Patterns Service Type: Consulting, Analytics, Software Solutions, Data Management End User: OEMs, Fleet Managers, Insurance Companies, Aftermarket Providers Revenue Model: Subscription, Licensing, Pay-Per-Use, Advertising |
| Companies Covered | Harman International Industries Inc., Caruso GmbH, Otonomo Technologies Ltd., Xevo Inc, Infosys Limited, Wejo Group Limited, Stellantis N.V., Tech Mahindra Limited, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Data Monetization Market Emerging Trajectories
Automotive data architectures are pivoting from centralized cloud lakes toward distributed edge-to-cloud meshes. This shift redistributes computational load and compliance risk across the vehicle-network boundary.
Federated machine learning is decentralizing model training across OEM, insurer, and municipal datasets without raw data centralization. Tier-1 suppliers embed training-capable silicon in domain controllers. Municipal traffic authorities in the Netherlands and Singapore pilot this architecture for congestion prediction without exposing individual trip records.
The EU AI Act's risk classification system imposes documentation burdens on automated decision systems processing driver behavior. High-risk categorization triggers conformity assessment requirements that extend development timelines by 8-14 months. OEMs are responding by segregating algorithmic stacks into explainable and black-box components, routing only the former toward customer-facing applications.
Fleet procurement teams now unbundle data access from vehicle acquisition, negotiating standalone telemetry subscriptions with competing analytics platforms. This disintermediation fragments what was previously captive OEM revenue. Large logistics operators in the United States and Germany leverage multi-source data aggregation to arbitrage insurance and maintenance service pricing across competing providers.
Automotive Data Monetization Market Segmentation
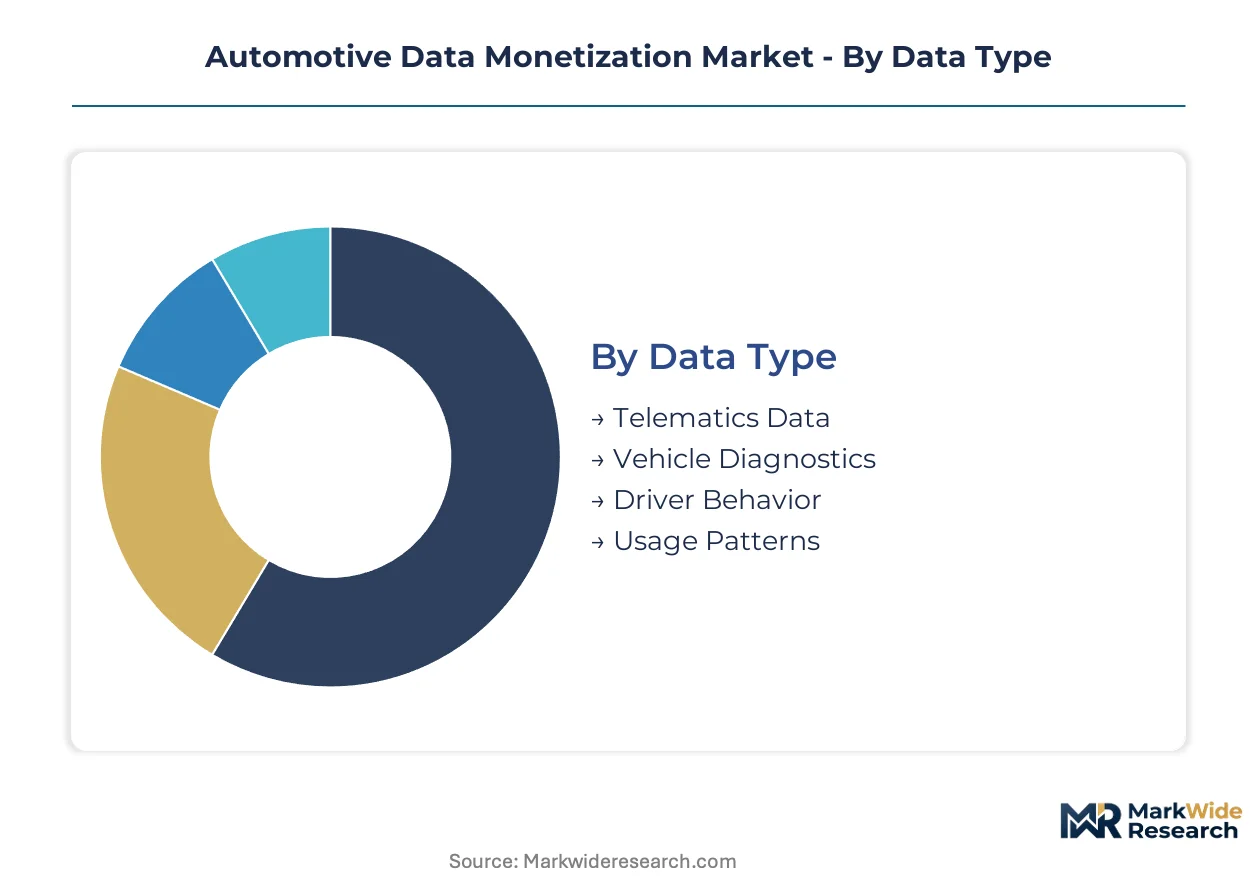
Segmentation in automotive data monetization determines which data streams command premium pricing and which revenue models align with buyer risk tolerance. Buyers differ sharply in technical sophistication, regulatory exposure, and willingness to share proprietary vehicle information.
Data Type:
Buyers in this category separate by analytical maturity and liability exposure around personally identifiable information.
- Telematics Data:Location, speed, and trip-duration feeds transmitted via cellular or satellite links. German and Japanese insurers now require real-time telematics integration for commercial fleet underwriting, driving standardization of OBD-II output formats.
- Vehicle Diagnostics:Powertrain fault codes, brake wear indicators, and battery health metrics pulled from CAN bus architectures. Independent repair chains in the United States subscribe to OEM diagnostic streams to schedule just-in-time maintenance appointments.
- Driver Behavior:Acceleration patterns, harsh braking events, and steering aggressiveness scores derived from IMU sensors.
- Usage Patterns:Cabin occupancy duration, infotainment interaction logs, and charging cycle timing for electric powertrains.
Telematics data leads volumes today; vehicle diagnostics is gaining share fastest.
Service Type:
Margin profiles diverge sharply between human-delivered advisory work and algorithmic software products.
- Software Solutions:Embedded proprietary algorithms that normalize raw vehicle feeds into risk scores, predictive maintenance alerts, and operational dashboards. Premium pricing reflects recurring license value and API integration complexity with insurer core systems.
- Analytics:Custom model development and visualization layers that transform aggregated fleet data into actionable procurement or route optimization recommendations.
- Consulting:Advisory engagements on data governance architecture, consent framework design, and regulatory compliance strategy.
- Data Management:Pipeline engineering, storage optimization, and residency-compliant replication across multi-cloud environments.
Software solutions capture the highest margins; analytics services expand most quickly as fleet operators build in-house data science teams.
End User:
Contracting power and data ownership rights vary enormously across this buyer spectrum.
- OEMs:Original equipment manufacturers with deepest historical data lakes but mounting pressure to open access under GDPR Article 20 portability mandates and competitive fleet-manager demands.
- Fleet Managers:Logistics operators and corporate vehicle pool administrators who unbundle telemetry access from vehicle acquisition to arbitrage insurance and maintenance pricing across competing analytics platforms.
- Insurance Companies:Underwriters expanding usage-based policy offerings that replace static actuarial tables with dynamic risk scoring from live vehicle feeds.
- Aftermarket Providers:Independent sensor networks, retrofit telematics hardware vendors, and third-party analytics platforms aggregating multi-brand vehicle pools.
OEMs retain the largest installed base; fleet managers are climbing the fastest as procurement teams renegotiate data access terms.
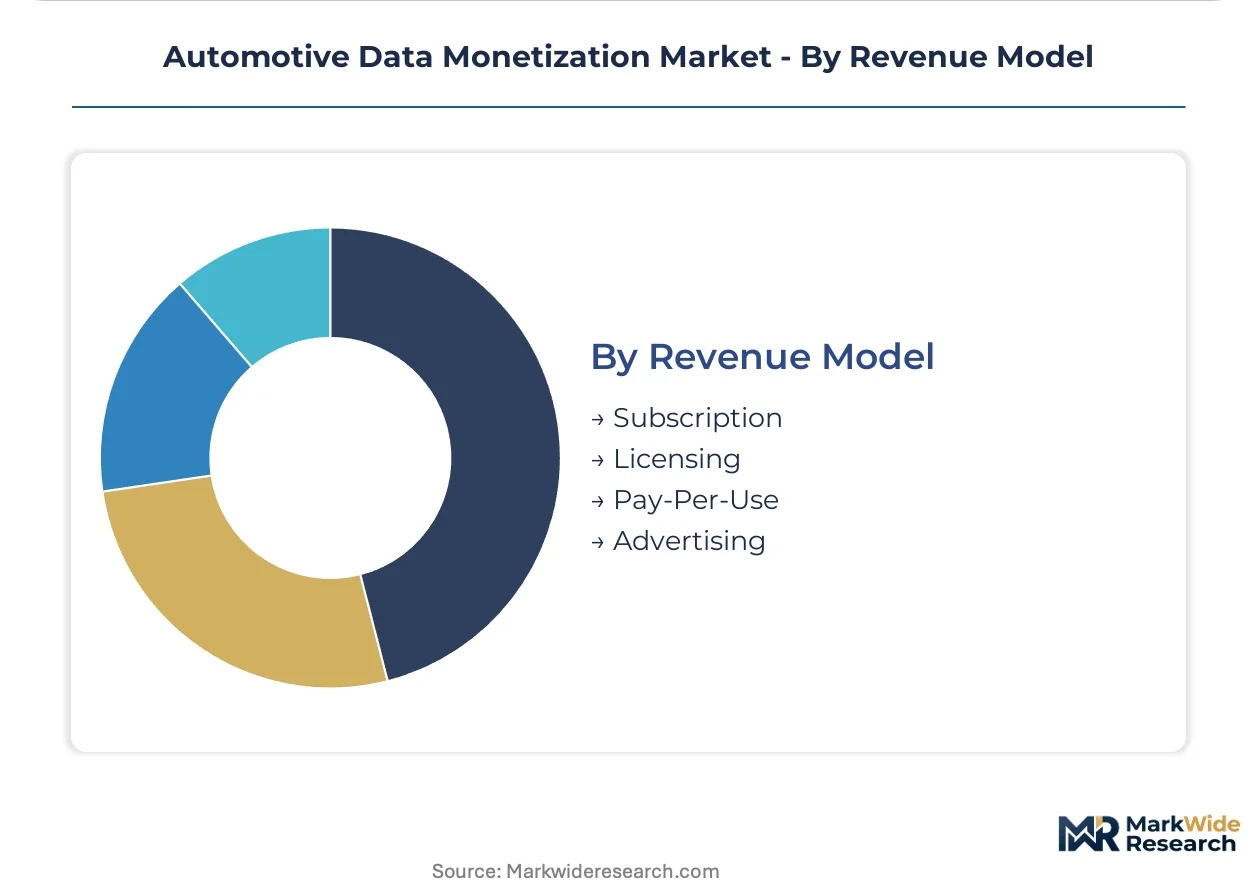
Revenue Model:
Payment structure preferences track buyer cash flow predictability and usage volatility.
- Subscription:Fixed monthly or annual fees for unlimited API calls, dashboard seats, or vehicle-node connections. Preferred by fleet managers seeking budget certainty.
- Licensing:Perpetual or term-limited rights to deploy proprietary algorithms on-premise or in private cloud environments. Common among OEMs with strict data residency requirements.
- Pay-Per-Use:Metered charges per data record processed, API query executed, or vehicle-mile monitored. Aligns costs with actual consumption for seasonal or variable-duty fleets.
- Advertising:Revenue share arrangements where in-vehicle infotainment platforms serve targeted promotions based on location and behavioral profiles.
Subscription dominates current bookings; pay-per-use shows the steepest expansion trajectory as variable-duty commercial fleets seek cost alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Munich corridor anchors automotive data platform development through embedded infotainment and sensor-to-cloud integration. The EU AI Act and GDPR Article 20 portability mandates reshape cross-border data architectures across European automaker headquarters.
United States
Detroit's OEM engineering centers and Silicon Valley cloud infrastructure drive fleet telematics deployment at scale. NHTSA guidelines on automated vehicle data logging intersect with the California Consumer Privacy Act's purpose-limitation requirements. Dallas-Fort Worth logistics hubs pilot multi-source data aggregation for usage-based insurance arbitrage.
Germany
KBA vehicle-type approval processes now embed algorithmic transparency documentation for driver behavior analytics. Munich-based tier-1 suppliers federate model training across siloed OEM datasets to satisfy GDPR residency protocols. Baden-Württemberg's industrial sensor clusters supply edge computing silicon for powertrain signal processing.
Japan
METI's data-free flow with trust initiative structures cross-border automotive data sharing agreements with European counterparts. Nagoya's Toyota supplier ecosystem commercializes predictive maintenance algorithms through standardized API marketplaces. Tokyo insurers mandate real-time telematics integration for commercial fleet underwriting.
India
PLI scheme subsidies for automotive electronics manufacturing reduce hardware deployment costs below 15% fleet penetration thresholds. CDSCO and BIS frameworks for connected vehicle cybersecurity create compliance entry barriers for foreign platform operators. Tamil Nadu's Sriperumbudur electronics corridor hosts domestic telematics device assembly for Southeast Asian export.
Netherlands
Amsterdam's municipal traffic authority pilots federated learning architectures for congestion prediction without exposing individual trip records. The Dutch data protection authority's guidance on vehicle trajectory anonymization shapes EU-wide technical standards. Eindhoven's high-tech systems district supplies embedded inference chips for cabin signal processing.
Automotive Data Monetization Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue aftermarket sensor networks and federated analytics architectures. The vendor base stratifies across three maturity levels: integrated OEM-tethered platforms, independent multi-brand aggregators, and specialized edge computing hardware fabricators. Strategic archetypes include sensor-to-cloud stack owners, API marketplace operators, and privacy-preserving infrastructure specialists. Competitive moves concentrate on M&A for data pipeline engineering talent and strategic partnerships with fleet management software vendors.
Within the integrated platform tier, Continental AG and Harman International Industries occupy positions spanning embedded hardware through cloud analytics. Wejo Group Limited exemplifies the direct vehicle-to-cloud connectivity archetype through automaker partnership structures. Caruso GmbH represents European-based API standardization efforts for cross-OEM data portability. These anchors illustrate how geographic clustering around German engineering centers and US cloud infrastructure shapes competitive positioning.
| Leading Market Players |
|---|
| Harman International Industries Inc. |
| Caruso GmbH |
| Otonomo Technologies Ltd. |
| Xevo Inc |
| Infosys Limited |
| Wejo Group Limited |
| Stellantis N.V. |
| Tech Mahindra Limited |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Software-embedded algorithm tiers diverge sharply from raw data feed commoditization, with proprietary risk-scoring engines commanding recurring license premiums while unprocessed telematics streams face downward price pressure from multi-source aggregation platforms. This bifurcation concentrates margin capture among tier-1 suppliers with integrated sensor-to-analytics stacks, while aftermarket hardware vendors compete on deployment cost minimization across fragmented fleet procurement budgets.
Pricing Analysis
Input-cost pass-through from Taiwanese semiconductor packaging capacity constraints feeds into LiDAR and high-resolution camera module pricing, with tier-1 suppliers partially absorbing these pressures through captive edge-computing silicon sourcing. Three-tier pricing structure across premium algorithmic solutions, standardized API access, and commodity raw data feeds reflects certification complexity under GDPR Article 20 portability mandates and EU AI Act conformity requirements. Cost compression in aftermarket retrofit hardware intensifies as Indian PLI scheme subsidies expand domestic electronics manufacturing capacity. Fleet managers exhibit highest price sensitivity through unbundled telemetry procurement, while OEMs retain lowest sensitivity due to captive data lake monetization strategies.
Supply Chain Analysis
Freight cost volatility from Asia-Europe semiconductor lanes complicates just-in-time delivery commitments for edge computing node deployment, with platform operators holding larger safety stocks of embedded inference chips. Manufacturing concentration centers on Germany for domain controller integration, Taiwan for advanced sensor packaging, and Japan for precision IMU components. Raw material dependencies span rare earth elements for magnet manufacturing, high-purity silicon for chip fabrication, and specialized polymers for cabin sensor housings. Single-source vulnerability around Taiwanese semiconductor capacity threatens component availability for federated learning infrastructure buildouts. Distribution runs through direct OEM partnerships for integrated platforms and independent distributor networks for aftermarket retrofit hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithmic software tiers as edge computing deployment reduces cloud egress cost burdens and federated architectures lower compliance overhead across multi-jurisdictional deployments.
For Market Incumbents: Anticipate disintermediation pressure from fleet procurement teams unbundling data access from vehicle acquisition, and respond through backward integration into edge computing silicon design and exclusive API marketplace control. Prioritize certification investment for EU AI Act high-risk system documentation to extend development timeline advantages over emerging competitors. Defensive consolidation around data pipeline engineering talent pools offsets 40% compensation premiums for federated learning expertise scarcity. For New Entrants and Emerging Players: Capture white-space in Indian commercial fleet telematics where penetration rates remain below 15% and PLI subsidies compress hardware deployment thresholds. Target independent repair chains in the United States seeking subscription access to OEM diagnostic streams for predictive maintenance scheduling. Pursue municipal traffic authority partnerships in the Netherlands and Singapore as anchor customers for privacy-preserving federated learning architectures. For Investors and Strategic Acquirers: Consolidation pressure builds where federated learning engineering scarcity intersects with fragmented aftermarket sensor network competition, favoring acquisition of specialized distributed systems teams over horizontal platform rollups. Long-term viability frames around 5-10 year regulatory divergence between European data-localization mandates and American sectoral privacy approaches. Target acquisition archetype: privacy-preserving infrastructure specialists with deployed edge computing node networks and municipal pilot references. Signal to watch: fleet procurement RFP language shifting from bundled vehicle-data packages to standalone telemetry subscription requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Infrastructure Investment | GDPR-compliant model training across siloed OEM datasets satisfies residency mandates without raw data centralization. |
| Edge Computing Node Deployment | Embedded inference chips in domain controllers reduce cloud egress costs while processing cabin signals locally. |
| API Standardization Partnership | Cross-OEM data portability agreements under Article 20 enable fleet manager multi-brand aggregation demand. |
| Predictive Maintenance Algorithm Licensing | Brake wear algorithms fused with traffic data enable just-in-time service scheduling for independent repair chains. |
| Consent Management Platform Rebuild | EU AI Act compliance deadlines force wholesale re-architecture of data pipelines and supplier contract restructuring. |
Methodological Framework
Coverage spans Germany, Japan, the United States, India, and the Netherlands, with primary inputs from each market informing cross-border architectural requirements. The analysis combines structured interviews with OEM platform engineers, tier-1 supplier procurement leads, fleet management software vendors, and aftermarket telematics distributors with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and regulatory guidance documents from the EU AI Act and GDPR implementing bodies. Bottom-up triangulation across data type, service type, end user, and revenue model segmentation dimensions reconciles with top-down market sizing from automotive electronics manufacturing capacity and connected vehicle deployment trajectories.
Granularity-level modeling captures differential growth rates across telematics data, vehicle diagnostics, driver behavior, and usage pattern categories, with software solutions, analytics, consulting, and data management service types projected separately throughout the forecast period. End user segmentation distinguishes OEM captive monetization strategies from fleet manager unbundling behavior and insurance company usage-based policy expansion. CAGRs derive from regression analysis of historical connected vehicle penetration, regulatory implementation timelines, and fleet procurement pattern shifts. Industry-specific forecast inputs include edge computing node deployment cost curves and federated learning infrastructure investment trajectories.
Regulatory implementation delays, semiconductor supply disruptions, and re-identification attack liability exposures are the dominant revision risks to modeled projections. Forecasts reflect assumptions around GDPR Article 20 enforcement consistency, PLI scheme subsidy continuity, and cross-border data flow agreement stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Motorcycle Infotainment System Market