
 ASEAN E-Commerce Logistics Market | 2026-2036
ASEAN E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN E-Commerce Logistics Market Outlook
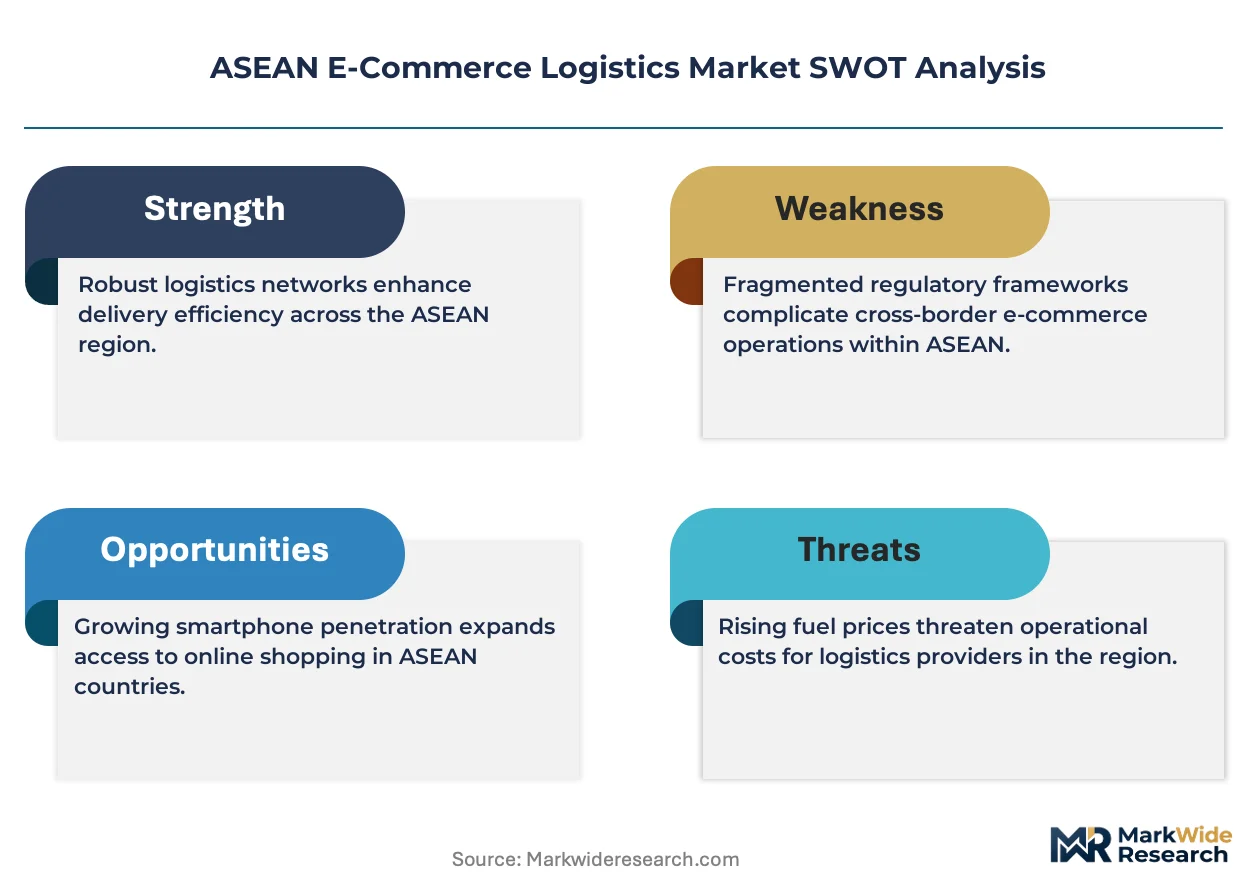
The EU Green Deal's extraterritorial carbon accounting requirements for maritime shipping is restructuring procurement priorities for ASEAN-bound parcel networks. J&T Express leverages its Indonesia-Philippines lane density to sustain unit economics on cross-border flows. Ninja Van anchors its last-mile density in Vietnam and Thailand through hyperlocal sorting infrastructure. SF Express competes on Shenzhen-ASEAN air freight connectivity, controlling premium express corridors into Singapore and Malaysia.
ASEAN E-Commerce Logistics encompasses the multimodal movement, storage, and fulfillment of goods ordered through digital retail platforms across Southeast Asia, combining parcel sortation hubs with temperature-controlled warehousing and real-time inventory visibility systems. The sector's primary commercial purpose is collapsing delivery latency between dispersed archipelagic populations and centralized fulfillment centers while managing high return rates endemic to cash-on-delivery markets. Last mile delivery occupies the dominant share of operational expenditure due to fragmented addressing and motorcycle-dependent urban access across Jakarta, Manila, and Bangkok. Warehouse Management Systems represent the fastest-growing technology segment as operators automate bin retrieval and cross-dock sequencing to offset rising labor costs in Vietnam and Indonesia. Express shipping commands premium pricing power from electronics and pharmaceutical shippers demanding defined-time delivery windows into Singapore and Kuala Lumpur.
Indonesia's Ministry of Trade import de minimis regulations and Thailand's FDA cold-chain mandates for health products shape product-specific compliance burdens across fulfillment networks. Singapore's IMDA data localization requirements and Malaysia's Customs Act amendments on e-commerce declarations determine platform architecture and clearance automation investments. Stakeholders must monitor how ASEAN member states harmonize digital economy taxation frameworks against divergent national logistics subsidy programs.
Market Dynamics
Indonesia's import de minimis threshold adjustments and Thailand's FDA cold-chain mandates are compressing margin structures while forcing multimodal networks to reconfigure for compliance-first routing.
Growth Catalysts
- ASEAN Single Window customs integration:Cross-border parcel clearance times are collapsing as unified electronic documentation replaces sequential national inspections. Electronics retailers are consolidating fulfillment nodes around this friction reduction.
- Hyperlocal sorting infrastructure:Dense urban motorcycle courier networks in Ho Chi Minh City and Bangkok are absorbing last-mile volume spikes without proportional labor expansion. Temperature-controlled pharmaceutical flows are anchoring premium lane investments.
- Indonesia's logistics modernization directives:National port automation and bonded zone expansion are redirecting transshipment volume from Singapore to Batam and Belawan. Domestic e-commerce platforms are backward-integrating into captive warehousing.
Market Restraints
- Fragmented addressing infrastructure:Jakarta's informal street naming and Manila's unmapped subdivisions force manual courier coordination. Geocoding investments absorb disproportionate technology budgets.
- Fuel cost volatility:Diesel-dependent inter-island ferry networks and motorcycle last-mile fleets expose operators to unhedged energy price swings. Margin compression is acute on economy-tier delivery products.
- Singapore's IMDA data localization:Cross-border inventory visibility systems must maintain sovereign data storage, duplicating cloud infrastructure across national boundaries. Platform architecture costs are rising.
Strategic Opportunities
- Vietnam's manufacturing corridor densification:Warehouse demand clusters around Bac Ninh and Binh Duong provinces are outpacing supply. Speculative development of ambient and cold-storage facilities is attracting institutional capital.
- Cross-border returns automation:High cash-on-delivery return rates in Philippine and Indonesian markets are absorbing AI-driven reverse logistics platforms. Inspection and re-staging workflows are compressing cycle times.
- EU Green Deal maritime carbon accounting:ASEAN-bound parcel networks are restructuring procurement toward low-emission ocean freight. Carbon-intensity disclosure is becoming a contract qualification threshold.
Industry Challenges
- Warehouse Management System integration:Legacy ERP platforms in Malaysian and Thai distribution centers resist real-time API connectivity with marketplace order management. Middleware development timelines are extending.
- Cold-chain technician scarcity:FDA-compliant temperature monitoring and HACCP documentation require certified personnel that Vietnam's vocational pipeline is not yet producing at scale. Training costs are inflating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN E-Commerce Logistics Market |
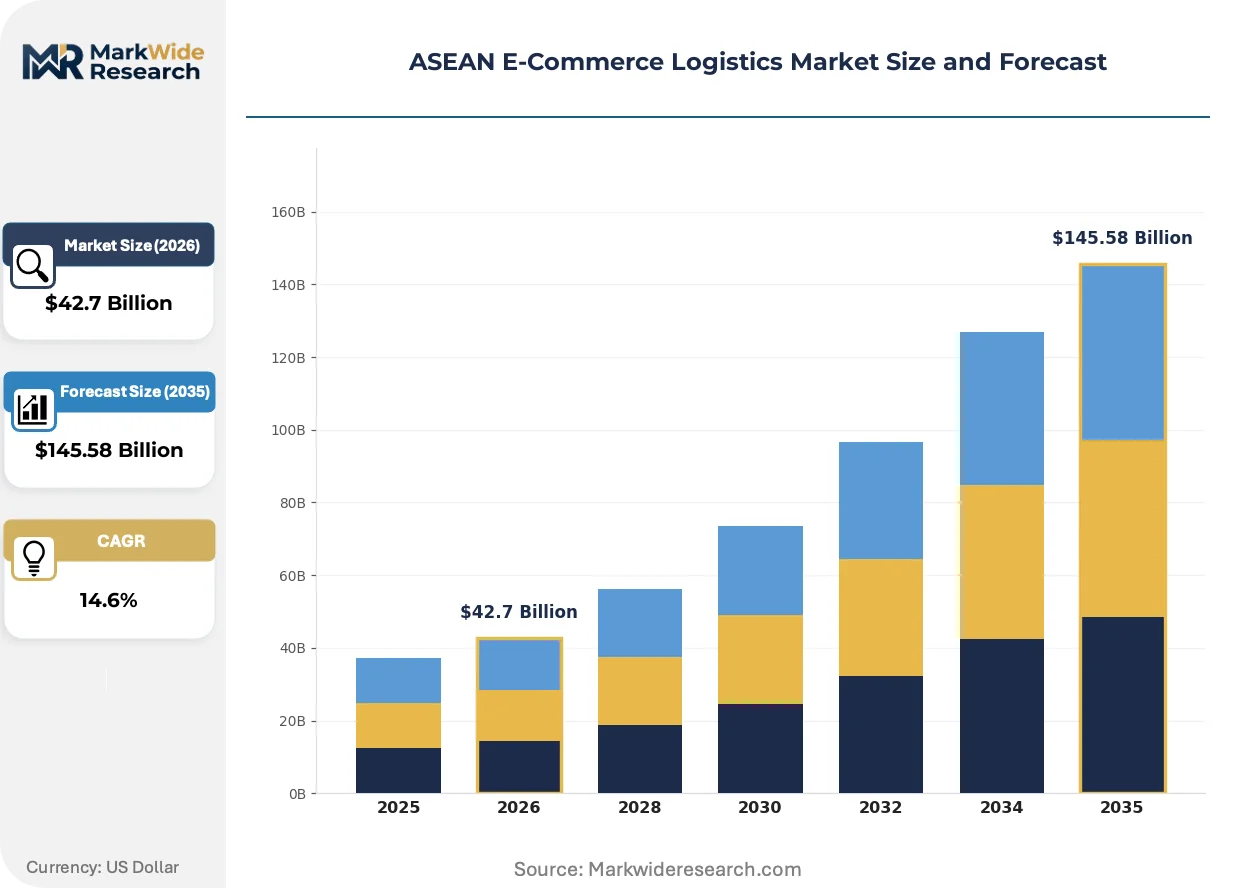
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $145.58 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Freight Forwarding, Warehousing, Return Management Delivery Mode: Standard Shipping, Express Shipping, Same-Day Delivery, Pickup Points Customer Type: B2B, B2C, C2C, Retailers Technology: Warehouse Management Systems, Route Optimization, Tracking Solutions, Automation |
| Companies Covered | J&T Express, Ninja Van, Deutsche Post DHL Group, FedEx Corporation, Kerry Logistics, SF Express, Lazada Logistics, Shopee Xpress, DSV, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN E-Commerce Logistics Market Strategic Shifts
Automation is penetrating sortation and inventory retrieval while regulatory compliance reshapes network design and buyer expectations compress delivery windows.
Autonomous mobile robots in bin retrieval and pallet movement are absorbing labor cost pressures in Vietnamese and Indonesian fulfillment centers. Third-party logistics operators are deploying these systems in greenfield facilities around Hanoi and Surabaya. The technology is absorbing wage inflation that would otherwise erode unit economics on same-day delivery promises.
Malaysia's Customs Act amendments on e-commerce declarations are forcing real-time manifest submission before parcel loading. Platform operators are re-architecting order-to-shipment workflows to embed pre-clearance data capture. Electronics and pharmaceutical shippers into Kuala Lumpur are absorbing compliance infrastructure costs to maintain lane access.
Buyer expectations for defined-time delivery windows are compressing procurement contracts toward penalty-backed service level agreements. Electronics retailers in Singapore and Malaysia are unbundling express shipping from standard basket economics. Pharmaceutical distributors are absorbing premium pricing for temperature-verified arrival commitments.
ASEAN E-Commerce Logistics Market Segmentation
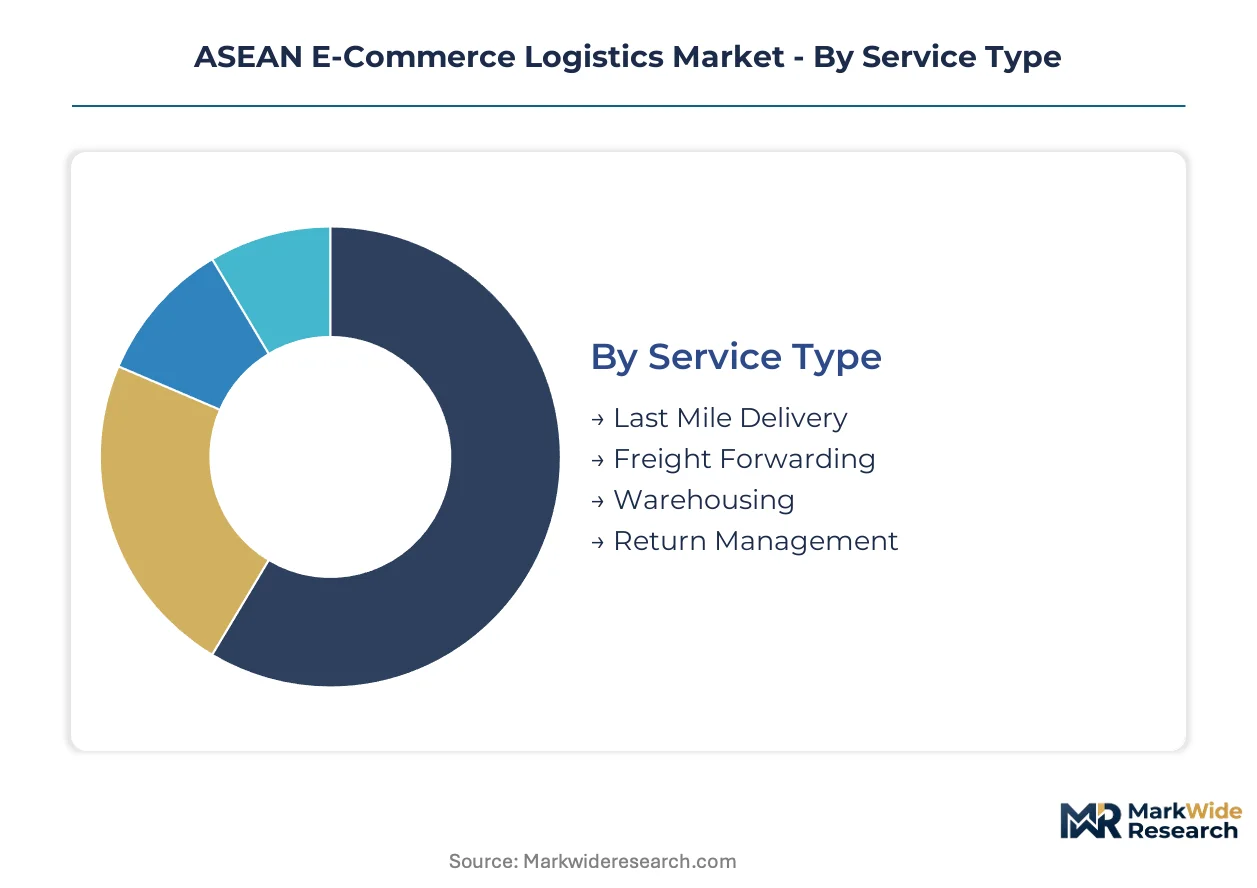
Service configuration determines cost structure and capital intensity across ASEAN's archipelagic geography. Buyers select delivery modes based on product margin density and customer lifetime value, while technology investments separate automated operators from labor-dependent competitors.
Service Type:
Shippers prioritize reliability guarantees and damage rates when selecting service tiers, with cost sensitivity varying by product category and destination density.
- Last Mile Delivery:Motorcycle-based courier networks execute final-leg distribution across Jakarta, Manila, and Bangkok's unmapped subdivisions. Fragmented addressing infrastructure forces manual coordination, absorbing disproportionate technology budgets for geocoding investments.
- Freight Forwarding:Consolidated ocean and air cargo movements bridge inter-island distances and cross-border corridors. Electronics retailers leverage Indonesia-Philippines lane density to sustain unit economics on cross-border flows.
- Warehousing:Ambient and temperature-controlled storage facilities cluster near Ho Chi Minh City and Hanoi's manufacturing corridors. Speculative development is attracting institutional capital as supply lags demand.
- Return Management:Reverse logistics platforms process high cash-on-delivery return rates endemic to Philippine and Indonesian markets. AI-driven inspection and re-staging workflows compress cycle times for recommerce.
Volume sits with Last Mile Delivery; growth tilts toward Return Management.
Delivery Mode:
Speed premiums correlate with product value density and customer willingness to pay for certainty, creating three distinct procurement tiers.
- Standard Shipping:Economy-tier ocean and ground transport serves price-sensitive basket economics across domestic Indonesian and Vietnamese e-commerce. Diesel cost volatility exposes operators to unhedged margin compression.
- Express Shipping:Air freight connectivity controls premium corridors into Singapore and Malaysia with defined-time delivery windows. Electronics and pharmaceutical shippers absorb premium pricing for arrival commitments.
- Same-Day Delivery:Hyperlocal sorting infrastructure and dense urban motorcycle networks enable compressed fulfillment windows. Ho Chi Minh City and Bangkok absorb volume spikes without proportional labor expansion.
- Pickup Points:Consolidated collection locations reduce failed delivery attempts in areas with unreliable addressing. Convenience store partnerships and locker networks expand coverage at lower per-stop cost.
Standard Shipping carries volume density; Same-Day Delivery climbs the fastest.
Customer Type:
Relationship structure determines contract terms, with enterprise accounts demanding service level agreements and penalty clauses absent from transactional consumer arrangements.
- B2B:Bulk procurement contracts from manufacturers and distributors require scheduled replenishment and vendor-managed inventory integration. Warehouse Management Systems automate bin retrieval for enterprise fulfillment.
- B2C:Individual parcel movements from marketplace orders dominate transaction volume across the region. Cash-on-delivery preferences in Indonesia and the Philippines elevate return rates and working capital requirements.
- C2C:Peer-to-peer platform sales generate fragmented, low-weight shipments with irregular density. Social commerce growth in Thailand and Vietnam expands this segment's contribution.
- Retailers:Omnichannel merchants operate captive logistics or outsource to third-party operators based on scale thresholds. Fashion and electronics retailers are expanding cross-border fulfillment networks.
B2C commands transaction volume; B2B delivers margin stability.
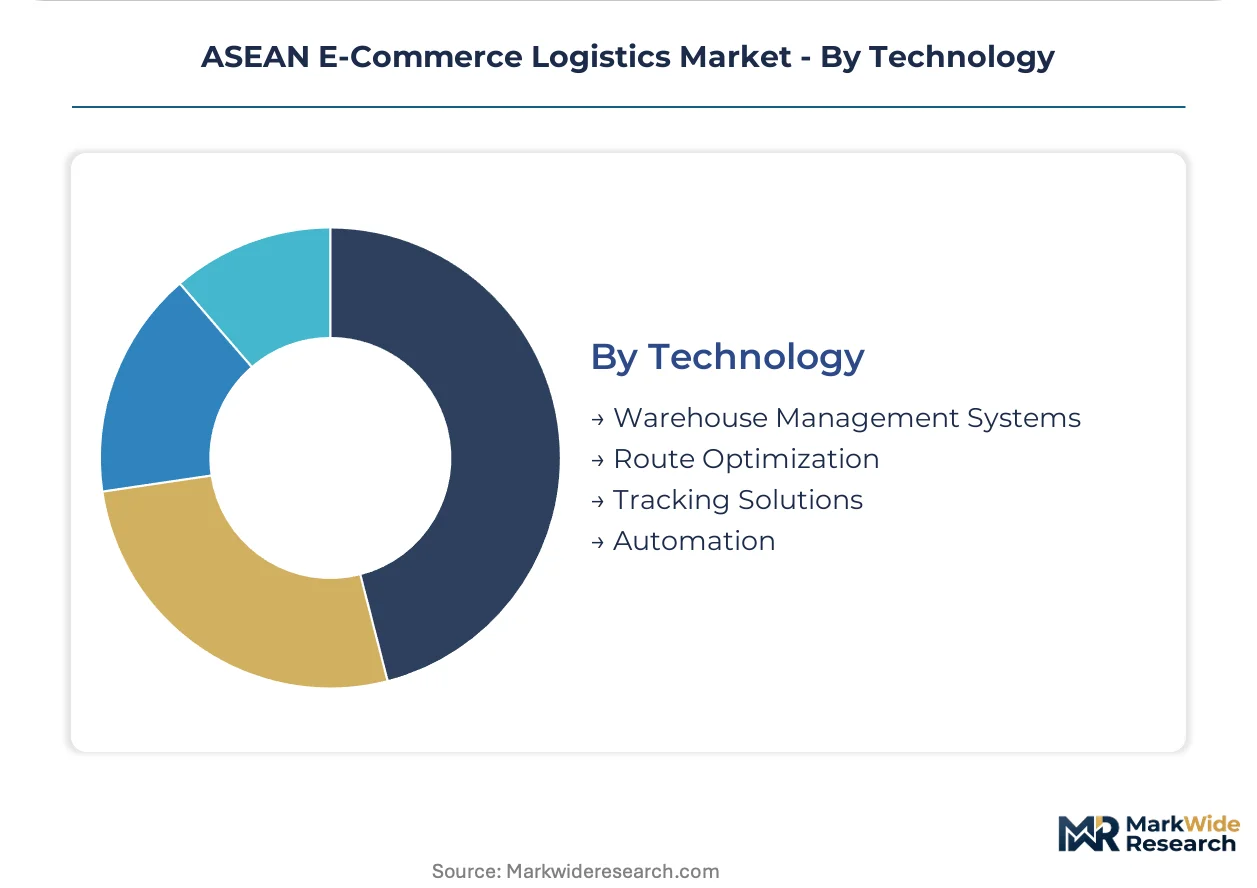
Technology:
Automation investments separate capital-rich operators from competitors exposed to wage inflation in Vietnamese and Indonesian labor markets.
- Warehouse Management Systems:Software platforms coordinate inventory visibility, bin retrieval, and cross-dock sequencing across fulfillment centers. This segment represents the fastest-growing technology category as operators offset rising labor costs.
- Route Optimization:Algorithmic dispatch systems reduce empty kilometers and improve courier productivity across motorcycle-dependent urban networks. Real-time traffic integration improves delivery density.
- Tracking Solutions:Parcel-level visibility systems must maintain sovereign data storage under Singapore's IMDA requirements. Duplicating cloud infrastructure across national boundaries elevates platform architecture costs.
- Automation:Autonomous mobile robots absorb labor cost pressures in greenfield facilities around Hanoi and Surabaya. The technology sustains same-day delivery promises against wage inflation.
Tracking Solutions anchor baseline infrastructure; Automation gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City's manufacturing corridor anchors warehouse demand density across Southeast Asia, with Bac Ninh and Binh Duong provinces absorbing speculative cold-storage development. Indonesia's port automation directives and Vietnam's electronics export growth are redrawing fulfillment network maps.
Indonesia
Domestic e-commerce platforms are backward-integrating into captive warehousing as import de minimis regulations shift compliance burdens. The Ministry of Trade's logistics modernization directives redirect transshipment volume from Singapore to Batam and Belawan. Jakarta's informal addressing infrastructure forces geocoding investments that absorb disproportionate technology budgets.
Vietnam
Electronics manufacturers cluster around Hanoi and Ho Chi Minh City, generating dense parcel flows that justify hyperlocal sorting infrastructure. The country's national pharmaceutical regulator enforces cold-chain mandates that elevate technician training costs. Binh Duong province attracts institutional capital for speculative ambient and temperature-controlled facility development.
Thailand
FDA cold-chain mandates for health products reshape pharmaceutical fulfillment network design around Bangkok. The Customs Act amendments on e-commerce declarations force real-time manifest submission before parcel loading. Dense urban motorcycle courier networks absorb last-mile volume spikes without proportional labor expansion.
Singapore
IMDA data localization requirements duplicate cloud infrastructure across national boundaries, elevating platform architecture costs for cross-border inventory visibility. Electronics retailers consolidate premium express corridors through Changi air freight connectivity. The city-state's bonded zone expansion competes with Indonesian transshipment alternatives.
Philippines
High cash-on-delivery return rates in Manila and Cebu absorb AI-driven reverse logistics platform investments. Unmapped subdivisions force manual courier coordination that fragments last-mile economics. Social commerce growth expands C2C shipment volumes with irregular density patterns.
ASEAN E-Commerce Logistics Market Competitive Environment
The competitive structure tilts toward platform-captive logistics arms and independent third-party operators with hyperlocal density. Parcel networks fragment across archipelagic geography, with no single operator commanding cross-border share. Three archetypes dominate: Indonesia-Philippines lane specialists, Vietnam-Thailand last-mile density builders, and Shenzhen-ASEAN air freight controllers. Capacity expansion and compliance-first routing investments constitute the dominant competitive moves.
Among Indonesia-Philippines specialists, J&T Express occupies a position exemplifying cross-border lane density economics. Ninja Van anchors the Vietnam-Thailand hyperlocal infrastructure archetype. SF Express represents the premium air freight connectivity model into Singapore and Malaysia. These three operators illustrate how geographic specialization separates capital-efficient competitors from labor-dependent challengers.
| Leading Market Players |
|---|
| J&T Express |
| Ninja Van |
| Deutsche Post DHL Group |
| FedEx Corporation |
| Kerry Logistics |
| SF Express |
| Lazada Logistics |
| Shopee Xpress |
| DSV |
| Others |
Value Chain & Pricing Dynamics
Electronics retailers' defined-time delivery window demands are compressing procurement contracts toward penalty-backed service level agreements, forcing operators to absorb premium lane infrastructure costs and restructure tiered pricing around reliability guarantees rather than speed alone.
Pricing Analysis
Outcome-based pricing anchored to delivery window certainty commands premium positioning across Singapore and Kuala Lumpur corridors. Pricing stratifies across premium express, standard deferred, and economy ocean tiers, with differentiation driven by FDA cold-chain certification status and parcel-level tracking granularity. Cost compression in economy-tier delivery products is intensifying because diesel-dependent inter-island ferry networks expose operators to unhedged energy price swings. Cash-on-delivery markets in Indonesia and the Philippines exhibit highest price sensitivity, while pharmaceutical distributors into Singapore show lowest sensitivity for temperature-verified arrival commitments.
Supply Chain Analysis
Dual-sourcing requirements from multinational electronics and pharmaceutical shippers mandate multi-operator qualification across Indonesia, Vietnam, and Thailand fulfillment nodes. Raw material dependencies center on lithium-ion battery cells for electric motorcycle fleets, temperature-controlled packaging materials, and cloud computing infrastructure for inventory visibility systems. Single-source vulnerability concentrates in Changi air freight connectivity for premium express lanes. Distribution runs through bonded zone clusters at Batam, Belawan, and Binh Duong with cross-dock sequencing into hyperlocal sorting facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehouse Management Systems are displacing legacy ERP platforms across Malaysian and Thai distribution centers, creating a technology-transition window where automation investments separate capital-efficient operators from labor-dependent challengers.
For Market Incumbents: Cement cross-border lane density through captive warehousing investments in Vietnam's Bac Ninh corridor and Indonesia's Batam bonded zone. J&T Express's Indonesia-Philippines unit economics demonstrate how lane concentration absorbs compliance cost inflation from Thailand's FDA cold-chain mandates. Backward integration into temperature-controlled facility ownership defends margin position against rising third-party logistics rates.
For New Entrants and Emerging Players: Begin with speculative cold-storage development in Binh Duong province where supply lags demand and institutional capital is underallocated. AI-driven reverse logistics platforms for Philippine and Indonesian cash-on-delivery returns represent the most penetrable white-space segment. Partner with convenience store chains for pickup point density rather than building proprietary last-mile motorcycle networks.
For Investors and Strategic Acquirers: The window for entry favors mid-cap operators with hyperlocal sorting infrastructure in Ho Chi Minh City and Bangkok. Long-term viability hinges on automation deployment timelines and compliance-first routing capabilities against EU Green Deal maritime carbon accounting thresholds. Monitor ASEAN Single Window customs integration velocity as the signal for cross-border margin expansion inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hyperlocal Sorting Infrastructure Deployment | Dense urban motorcycle networks in Ho Chi Minh City absorb volume spikes without proportional labor expansion. |
| Temperature-Controlled Facility Development | Binh Duong and Bac Ninh provinces attract institutional capital as pharmaceutical cold-chain demand outstrips supply. |
| Cross-Border Customs Integration Investment | ASEAN Single Window electronic documentation reduces clearance friction for Indonesia-Philippines lane specialists. |
| Autonomous Mobile Robot Implementation | Greenfield facilities around Hanoi and Surabaya offset wage inflation threatening same-day delivery unit economics. |
| Reverse Logistics Platform Acquisition | AI-driven inspection workflows compress cycle times for high cash-on-delivery return rates in Manila and Jakarta. |
Study Parameters
Trade databases, customs declaration records, and logistics operator SEC filings formed the secondary backbone, cross-referenced with primary interviews involving warehouse operations directors, e-commerce platform supply chain leads, cold-chain compliance officers, and third-party logistics procurement managers. Bottom-up parcel volume modeling across service type, delivery mode, and customer type segments was triangulated against top-down macroeconomic consumption trends.
Historical trendline analysis established baseline growth trajectories across the projection horizon, with segmentation modeling incorporating service configuration, delivery speed tier, customer relationship structure, and technology automation level. CAGRs were derived from elasticity-adjusted demand projections. Forecast inputs included ASEAN Single Window implementation velocity, Indonesia's port automation deployment schedules, and Vietnam's electronics export shipment densities.
Fuel cost volatility, regulatory harmonization delays, and cold-chain technician pipeline constraints are the dominant revision risks to modeled outcomes. Deviation in EU Green Deal maritime carbon accounting enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
US SMS Marketing Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
E-Commerce Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
India E-Commerce Warehousing Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market